
 H. Pylori Breath Test Kit Market | 2026-2036
H. Pylori Breath Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
H. Pylori Breath Test Kit Market Insights
Point-of-care molecular detection is narrowing the performance gap between laboratory-grade analyzers and portable breath test platforms. Meridian Bioscience leverages its FDA-cleared assay portfolio to anchor hospital laboratory contracts across North America. Beijing Richen-force dominates domestic procurement channels through in-house production of isotope ratio mass spectrometry components. Exalenz Bioscience Ltd. specializes in compact bedside systems that compete with traditional send-out laboratory workflows.
H. pylori breath test kits detect urease activity through carbon isotope analysis of exhaled breath samples, typically requiring a baseline breath collection followed by urea solution ingestion and a timed post-dose sample; most clinical-grade systems achieve specificity above 95 percent when operated under controlled fasting conditions. Laboratory test kits retain the largest installed base among product types, though rapid test kits are gaining share in outpatient settings where same-day diagnosis determines treatment initiation. Distribution through hospital pharmacies generates the highest per-unit margins, while online stores are extending reach into patient-directed screening segments previously served only by clinic-based workflows.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device commercialization in the United States, while China's NMPA enforces GB/T diagnostic reagent registration for domestic manufacturing. The EU Medical Device Regulation mandates notified body involvement for breath analysis systems marketed in Europe, adding compliance cost layers that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor evolving reimbursement codes for non-invasive H. pylori confirmation testing, as payor acceptance of breath-based methods over serology or stool antigen alternatives will determine volume trajectories in cost-sensitive health systems.
Market Dynamics
Centralized laboratory capacity in China's tier-one hospital networks is compressing demand for portable point-of-care systems, while FDA 510(k) clearance timelines continue to gate US market entry for emerging manufacturers.
Growth Catalysts
- Non-invasive screening protocols:East Asian national health systems prioritize early gastric cancer detection, expanding urea breath testing workflows in diagnostic centers across Japan and South Korea.
- ISO 13485 quality management:Certification requirements drive consolidation among contract manufacturers, elevating device reliability standards for laboratory-grade analyzers.
- Isotope ratio mass spectrometry:In-house production capabilities in Beijing and Shanghai reduce component lead times for domestic Chinese manufacturers.
Market Restraints
- Helium-3 isotope supply volatility:Mass spectrometry systems depend on constrained nuclear byproduct channels, creating input cost uncertainty for high-precision analyzers.
- EU Medical Device Regulation notified body bottlenecks:Breath analysis system approvals face extended review queues, delaying European commercialization for mid-cap developers.
- Serology and stool antigen alternatives:Lower-cost diagnostic methods retain reimbursement preference in cost-sensitive Medicaid programs across several US states.
Strategic Opportunities
- Patient-directed screening channels:Online retail platforms bypass clinic-based workflows, capturing previously unreachable asymptomatic testing demand.
- Carbon-13 urea substrate convergence:Stable isotope chemistry combines with compact infrared spectroscopy, enabling bedside systems without mass spectrometer infrastructure.
- NMPA streamlined Class II registration:China's 2023 diagnostic reagent reforms accelerate domestic approval timelines for urea breath test kits.
Industry Challenges
- Cross-trained clinical laboratory technologists:Breath sample handling protocols require specialized competency in isotope handling, creating workforce scarcity outside major metropolitan hospital networks.
- Laboratory information system integration:Disparate HL7 interface standards between analyzer manufacturers and hospital electronic health records generate implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H. Pylori Breath Test Kit Market |
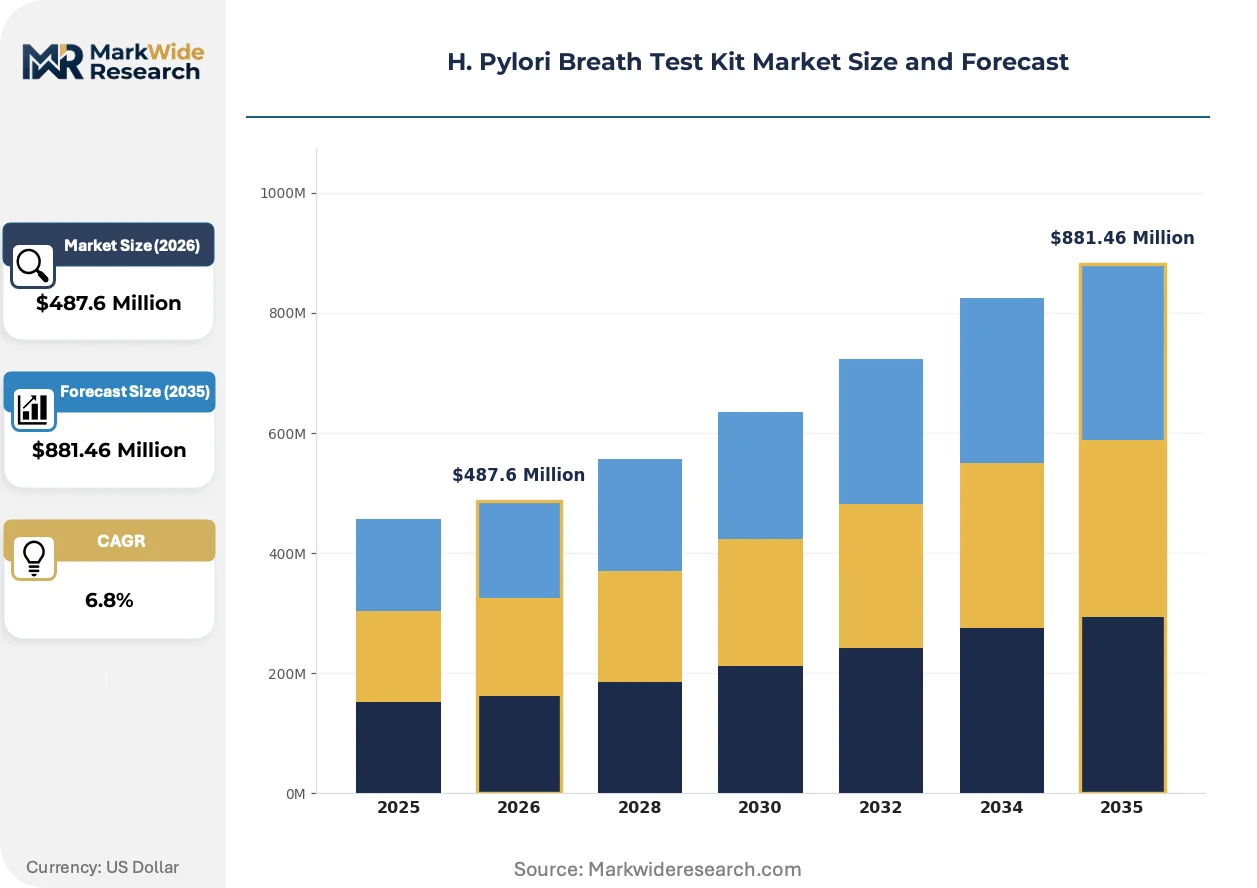
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Test Kits, Laboratory Test Kits, Professional Test Kits, Rapid Test Kits Distribution Channel: Pharmacies, Online Stores, Hospitals, Clinics End User: Patients, Healthcare Professionals, Diagnostic Centers, Research Institutions Packaging Type: Sachets, Vials, Bottles, Pouches |
| Companies Covered | Meridian Bioscience, Otsuka Electronics, Beijing Richen-force, Zhonghe Headway, Shanghai Topfeel Medtech, Exalenz Bioscience Ltd., Mayoli Spindler, Otsuka Pharmaceutical Co. Ltd., Sercon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H. Pylori Breath Test Kit Market Trends and Innovations
Detection methodology is fragmenting across three parallel tracks: laboratory precision systems, compact bedside analyzers, and emerging smartphone-integrated sensors. Each trajectory carries distinct regulatory pathways and capital requirements.
Infrared spectroscopy is migrating from laboratory benchtop configurations toward handheld point-of-care platforms. Outpatient gastroenterology clinics in Germany and France adopt these systems to eliminate send-out laboratory delays. The technology is migrating from centralized hospital laboratories toward ambulatory settings, compressing the diagnostic-treatment interval from days to hours.
China's NMPA enforcement of GB/T diagnostic reagent registration creates divergent compliance pathways for domestic versus imported manufacturers. Local producers gain accelerated review timelines while foreign applicants face extended documentation requirements. Breath test kit developers targeting the Chinese market increasingly establish domestic legal entities to access the streamlined registration channel.
Hospital pharmacy procurement committees now mandate same-day result turnaround as a contract prerequisite, displacing traditional send-out laboratory relationships. Gastroenterology departments in US academic medical centers unbundle testing services from reference laboratory contracts. This behavioral shift concentrates purchasing authority within individual hospital systems rather than regional laboratory networks.
H. Pylori Breath Test Kit Market Segmentation
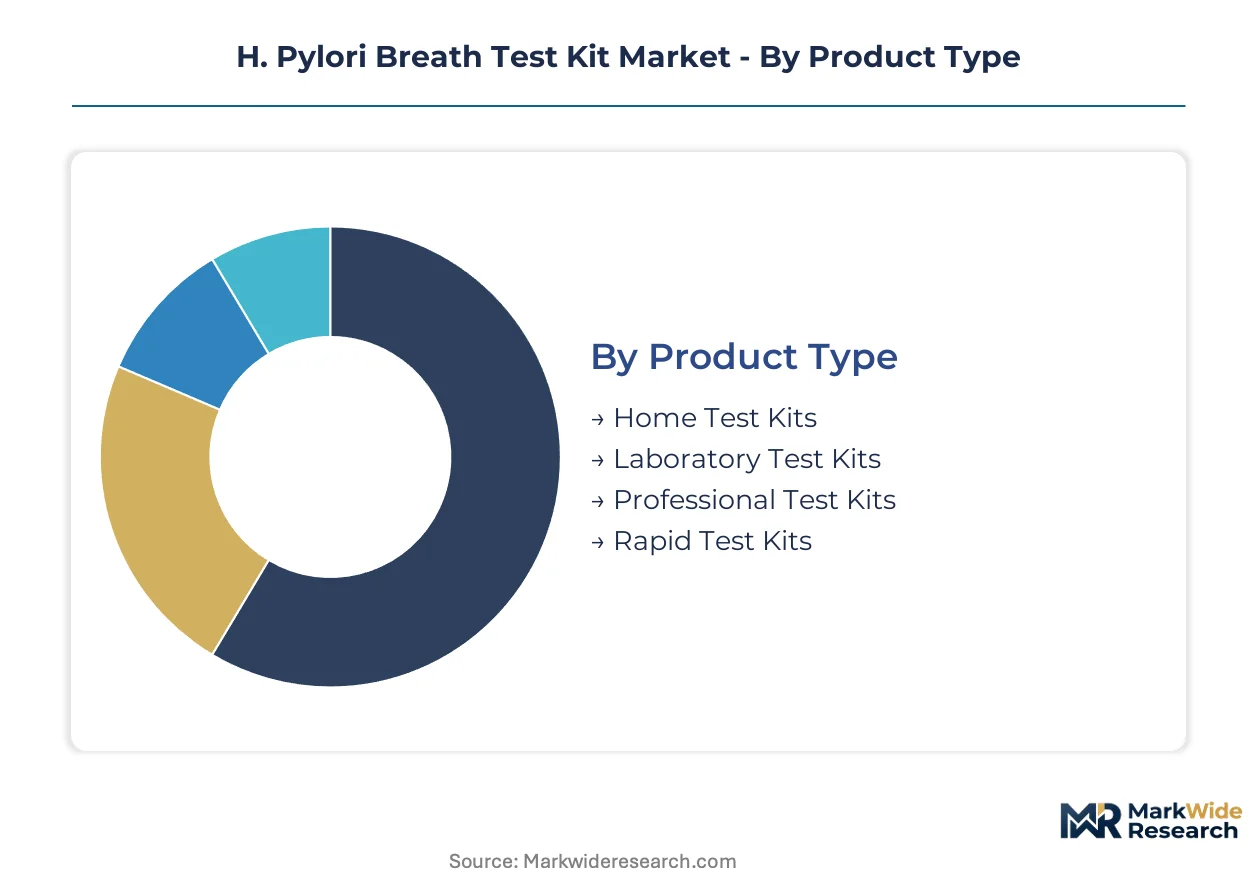
Segmentation in the H. pylori breath test kit market reveals divergent technical requirements between centralized laboratory infrastructure and decentralized screening workflows. Product architecture, distribution logistics, and end-user competency levels determine margin structures and regulatory pathways across each category.
Product Type:
Mature laboratory systems anchor hospital procurement while emerging portable formats reshape outpatient access models.
- Laboratory Test Kits:These systems integrate isotope ratio mass spectrometry or infrared spectroscopy for carbon-13 analysis, requiring controlled fasting protocols and trained technologist oversight. Demand concentrates in China's tier-one hospital networks where centralized laboratory capacity supports high-throughput urea breath testing workflows and same-day result mandates from pharmacy procurement committees.
- Rapid Test Kits:Compact bedside analyzers eliminate send-out delays through carbon-13 urea substrate chemistry paired with portable detection modules. German and French outpatient gastroenterology clinics adopt these systems to compress diagnostic-treatment intervals from days to hours, bypassing traditional reference laboratory relationships.
- Home Test Kits:Patient-directed screening formats bypass clinic-based workflows entirely, capturing asymptomatic testing demand through direct-to-consumer channels.
- Professional Test Kits:Clinic-grade systems balance analytical precision with moderate throughput for mid-sized diagnostic centers without full laboratory infrastructure.
Laboratory test kits retain volume leadership; rapid test kits hold the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates premium hospital contracts from economy online retail penetration.
- Hospitals:Direct procurement through pharmacy committees generates the highest per-unit margins, with academic medical centers in the United States unbundling testing services from regional laboratory networks to concentrate purchasing authority within individual systems.
- Online Stores:Digital retail platforms extend reach into patient-directed screening segments previously served only by clinic-based workflows, capturing unreachable asymptomatic demand.
- Pharmacies:Traditional retail channels serve prescription-anchored testing with established reimbursement pathways.
- Clinics:Ambulatory settings prioritize rapid turnaround formats over send-out laboratory relationships.
Hospital channels dominate value capture; online stores are expanding most quickly.
End User:
Customer type determines technical complexity tolerance and regulatory exposure across the value chain.
- Healthcare Professionals:Gastroenterology departments and primary care physicians drive standardized protocol adoption, with FDA 510(k) clearance requirements governing device selection in the United States.
- Diagnostic Centers:East Asian national health systems prioritize early gastric cancer detection, expanding urea breath testing workflows across Japan and South Korea through non-invasive screening protocols.
- Patients:Self-directed testers favor simplified collection methods without specialized isotope handling competency.
- Research Institutions:Academic users require mass spectrometry precision for clinical trial endpoints and epidemiological surveillance.
Healthcare professionals anchor procurement volume; diagnostic centers are gaining share fastest.
Packaging Type:
Supply concentration in isotope handling shapes packaging format selection and cold chain requirements.
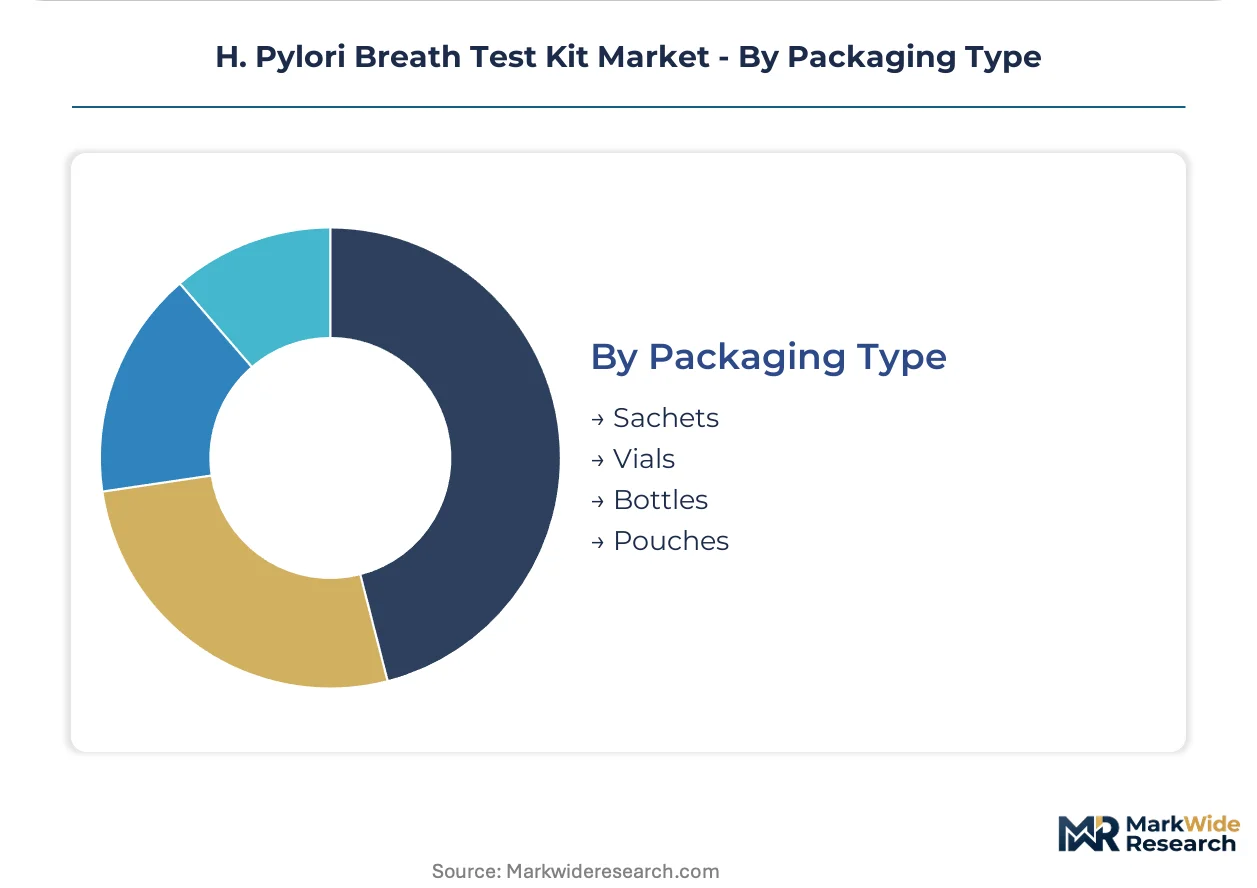
- Vials:Rigid containers support carbon-13 urea substrate stability during transport and storage, preferred by laboratory networks with established cold chain infrastructure.
- Sachets:Single-dose foil packaging reduces contamination risk for point-of-care deployment.
- Bottles:Bulk formats serve high-throughput centralized laboratories with dedicated inventory management systems.
- Pouches:Flexible packaging minimizes shipping cube for direct-to-consumer distribution channels.
Vials retain institutional preference; pouches are climbing the fastest in patient-directed channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for isotope-enriched urea substrates shapes procurement economics across major consuming markets, while export-oriented manufacturers in East Asia leverage integrated chemical processing capabilities to capture value from downstream diagnostic assembly.
United States
FDA 510(k) clearance timelines gate market entry for emerging breath test kit developers, with academic medical centers in Massachusetts and California unbundling testing services from regional laboratory networks. Hospital pharmacy procurement committees now mandate same-day result turnaround as a contract prerequisite. The Boston-Cambridge corridor hosts concentrated clinical trial activity for novel detection platforms.
China
NMPA streamlined Class II registration reforms since 2023 accelerate domestic approval timelines for urea breath test kits, favoring manufacturers with captive isotope ratio mass spectrometry component production. Beijing and Shanghai house the dominant installed base of centralized laboratory analyzers. Yangtze River Delta diagnostic centers expand non-invasive screening protocols as national health systems prioritize early gastric cancer detection.
Germany
EU Medical Device Regulation notified body involvement adds compliance cost layers that favor established players with dedicated regulatory affairs teams, particularly for infrared spectroscopy-based bedside systems. Outpatient gastroenterology clinics in Bavaria and North Rhine-Westphalia adopt compact analyzers to eliminate send-out laboratory delays. The Munich-Stuttgart axis concentrates precision instrument engineering expertise.
Japan
METI industrial policy supports domestic production of diagnostic reagents, while PMDA oversight maintains stringent performance validation requirements for breath analysis systems. Diagnostic centers across Kanto and Kansai regions expand urea breath testing workflows through national health insurance reimbursement for gastric cancer screening protocols. Osaka-based manufacturers supply isotope handling equipment across East Asian markets.
South Korea
MFDS enforcement of in-vitro diagnostic device standards shapes product development timelines for manufacturers targeting the domestic market, with Seoul Capital Area hospitals driving demand for high-throughput laboratory systems. National cancer screening programs expand non-invasive H. pylori confirmation testing eligibility. Busan-Ulsan industrial clusters support chemical synthesis of carbon-13 urea substrates for regional export.
H. Pylori Breath Test Kit Market Competitive Landscape
On the supply side, the industry is bifurcated between consolidated laboratory-grade system providers and fragmented point-of-care device specialists. Three strategic archetypes dominate: mass spectrometry-anchored precision manufacturers, compact infrared spectroscopy developers, and integrated isotope chemistry suppliers. Competitive intensity centers on regulatory clearance velocity and hospital pharmacy contract capture rather than price alone.
Among North American diagnostic specialists, Meridian Bioscience occupies a position exemplifying laboratory-contract anchoring through FDA-cleared assay portfolios. Beijing Richen-force represents the integrated manufacturing archetype with in-house isotope ratio mass spectrometry component production. Exalenz Bioscience Ltd. exemplifies the compact bedside system segment competing with traditional send-out workflows.
| Leading Market Players |
|---|
| Meridian Bioscience |
| Otsuka Electronics |
| Beijing Richen-force |
| Zhonghe Headway |
| Shanghai Topfeel Medtech |
| Exalenz Bioscience Ltd. |
| Mayoli Spindler |
| Otsuka Pharmaceutical Co. Ltd. |
| Sercon Group |
| Others |
Pricing and Supply Chain Analysis
Helium-3 isotope supply volatility determines both pricing tier spreads and supply chain shape across the H. pylori breath test kit market, compressing margins for mass spectrometry-dependent laboratory systems while amplifying cost advantages for infrared spectroscopy-based alternatives that bypass nuclear byproduct channels.
Pricing Analysis
The technology-generation pricing gap separates legacy isotope ratio mass spectrometry systems from emerging compact infrared platforms and next-generation smartphone-integrated sensors. Three-tier pricing structure across premium laboratory analyzers, standard bedside systems, and economy direct-to-consumer formats reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from serology and stool antigen alternatives retaining Medicaid reimbursement preference in cost-sensitive US state programs. Diagnostic centers exhibit highest price sensitivity due to volume procurement mandates, while hospital pharmacy committees prioritize same-day turnaround over per-unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for carbon-13 urea substrate sourcing. Manufacturing concentrates in China, Germany, and Japan, drawing from isotope-enriched chemical feedstocks, precision optical components, and specialized detector arrays. Single-source vulnerability persists for helium-3 derived from constrained nuclear byproduct channels. Distribution runs through hospital pharmacy procurement committees, direct-to-consumer online platforms, and regional diagnostic laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The H. pylori breath test kit market sits in a cyclical recovery phase driven by East Asian national health system expansion of gastric cancer screening protocols, creating procurement windows for equipment refresh cycles.
For Market Incumbents: Pre-empt emerging compact infrared spectroscopy entrants by anchoring hospital laboratory contracts through integrated isotope chemistry supply guarantees. Capture pharmacy procurement committee same-day mandate requirements with high-throughput analyzer platforms. Defend against point-of-care displacement by embedding laboratory information system connectivity that outpatient clinics cannot replicate.
For New Entrants and Emerging Players: Southeast Asian diagnostic center networks offer underpenetrated access points where centralized laboratory infrastructure remains underdeveloped. Target patient-directed screening channels through online retail platforms with simplified collection protocols that bypass specialized technologist requirements. Pursue NMPA streamlined Class II registration pathways to accelerate Chinese market entry ahead of EU MDR notified body queues.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated isotope chemistry suppliers with captive component production. Long-term viability over the next decade rests on regulatory clearance velocity rather than price competition alone. Monitor FDA 510(k) clearance timeline compression as the inflection signal for emerging manufacturer viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Academic medical center unbundling from reference laboratories creates direct procurement access. |
| Reimbursement Strategy | Payor acceptance of breath-based methods over serology alternatives determines volume trajectories. |
| Software Companion Development | HL7 interface standardization reduces electronic health record integration friction for hospital adoption. |
| CE Marking Pathway | EU MDR notified body involvement adds compliance cost layers favoring established regulatory affairs teams. |
| Backward Integration | In-house carbon-13 urea substrate production insulates against isotope supply channel volatility. |
Research Methodology
The analysis maps laboratory test kits, rapid test kits, home test kits, and professional test kits, each validated through hospital procurement managers, diagnostic center laboratory directors, regulatory affairs specialists, and GPO contracts managers. Primary interview insights combined with secondary validation from FDA 510(k) filings, NMPA registration databases, EU MDR notified body documentation, and hospital procurement databases. Bottom-up installed base modeling and top-down epidemiological screening demand estimates undergo triangulation.
Fixed assumptions include sustained East Asian gastric cancer screening program expansion, continued helium-3 supply constraints, and stable FDA 510(k) review timelines across the projection horizon. Modeled segmentation spans product architecture, distribution channel, end-user type, and packaging format. CAGRs derive from patient population screening eligibility expansion and equipment replacement cycle analysis, with carbon-13 substrate chemistry adoption curves and infrared spectroscopy cost reduction trajectories as key forecast inputs.
Practitioners should monitor reimbursement code revisions, isotope supply channel disruptions, and regulatory approval timeline shifts for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market