
 North America Amber Glass Packaging Market | 2026-2036
North America Amber Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Amber Glass Packaging Market Intelligence
Asset-light leasing and project finance for glass furnace retrofits is fragmenting competitive barriers across the North America Amber Glass Packaging landscape. Ardagh Group S.A leverages captive float-glass technology to sustain cost leadership in high-volume bottle production. Gerresheimer AG anchors its position through specialized pharmaceutical-grade vial manufacturing for FDA-regulated drug makers. Piramal Enterprises Ltd. competes by extending its North American distribution footprint for specialty amber glass containers.
Amber glass packaging denotes soda-lime silica containers tinted with iron, sulfur, and carbon compounds to block ultraviolet and visible light below 500 nanometers, protecting photosensitive contents from degradation. The glass derives its protective properties from controlled redox chemistry during melting, yielding amber hues that absorb approximately 90% of UV radiation up to 450 nanometers. Bottles dominate volume throughput across pharmaceutical and beverage applications, while vials command premium positioning in injectable drug segments where USP Type I compliance is mandatory. Jars represent a mature, slower-expanding category tied to niche food preservation and cosmetic cream formats with limited light-protection requirements.
FDA stability testing protocols under ICH Q1B guidelines mandate photostability validation for drug packaging, directly shaping amber glass specification requirements across pharmaceutical supply chains. EPA emissions standards for glass manufacturing furnaces and OSHA silica exposure limits constrain production economics and facility siting decisions across U.S. and Canadian operations. Stakeholders must monitor pending state-level extended producer responsibility legislation in California and New York that could reshape collection and recycling cost structures for amber glass containers.
Market Dynamics
FDA's evolving photostability validation requirements under ICH Q1B guidelines are forcing pharmaceutical packaging procurement toward amber glass specifications, compressing substitution windows and elevating compliance costs across the supply chain.
Growth Catalysts
- Pharmaceutical-grade specifications:FDA ICH Q1B photostability mandates require amber glass for light-sensitive drug categories, locking in material demand across injectable and oral solid dosage formats.
- Carbon-intensive furnace retrofits:EPA emissions standards for glass manufacturing are accelerating capital deployment into oxy-fuel and electric melting technologies that favor amber glass production economics.
- Northeast pharmaceutical corridor:Concentrated biopharma manufacturing across New Jersey, Pennsylvania, and Massachusetts generates localized procurement pull for amber vials and bottles.
Market Restraints
- Silica and soda ash input volatility:Energy-intensive raw material processing exposes margins to natural gas price swings across U.S. and Canadian furnace operations.
- Single-source furnace dependency:North American amber glass capacity concentrates among three integrated producers, creating supply concentration risk for pharmaceutical contract manufacturers.
- Plastic barrier substitution:Multilayer polyethylene terephthalate with UV inhibitors is capturing cost-sensitive over-the-counter pharmaceutical segments.
Strategic Opportunities
- Canadian biologics expansion:Health Canada accelerated approval pathways for biosimilars are driving demand for USP Type I amber vials in Toronto and Montreal manufacturing clusters.
- Extended producer responsibility frameworks:Pending California and New York state legislation on packaging waste creates first-mover advantage for closed-loop amber glass collection infrastructure.
- Digital printing convergence:Laser-etched serialization on amber glass surfaces enables unit-level track-and-trace compliance without label adhesives.
Industry Challenges
- Specialized furnace operator scarcity:Redox chemistry control for consistent amber hue requires skills that aging workforce demographics are depleting across U.S. glass manufacturing regions.
- USP Type I certification timelines:Pharmaceutical-grade compliance documentation stretches 18-24 months, constraining capacity expansion velocity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Amber Glass Packaging Market |
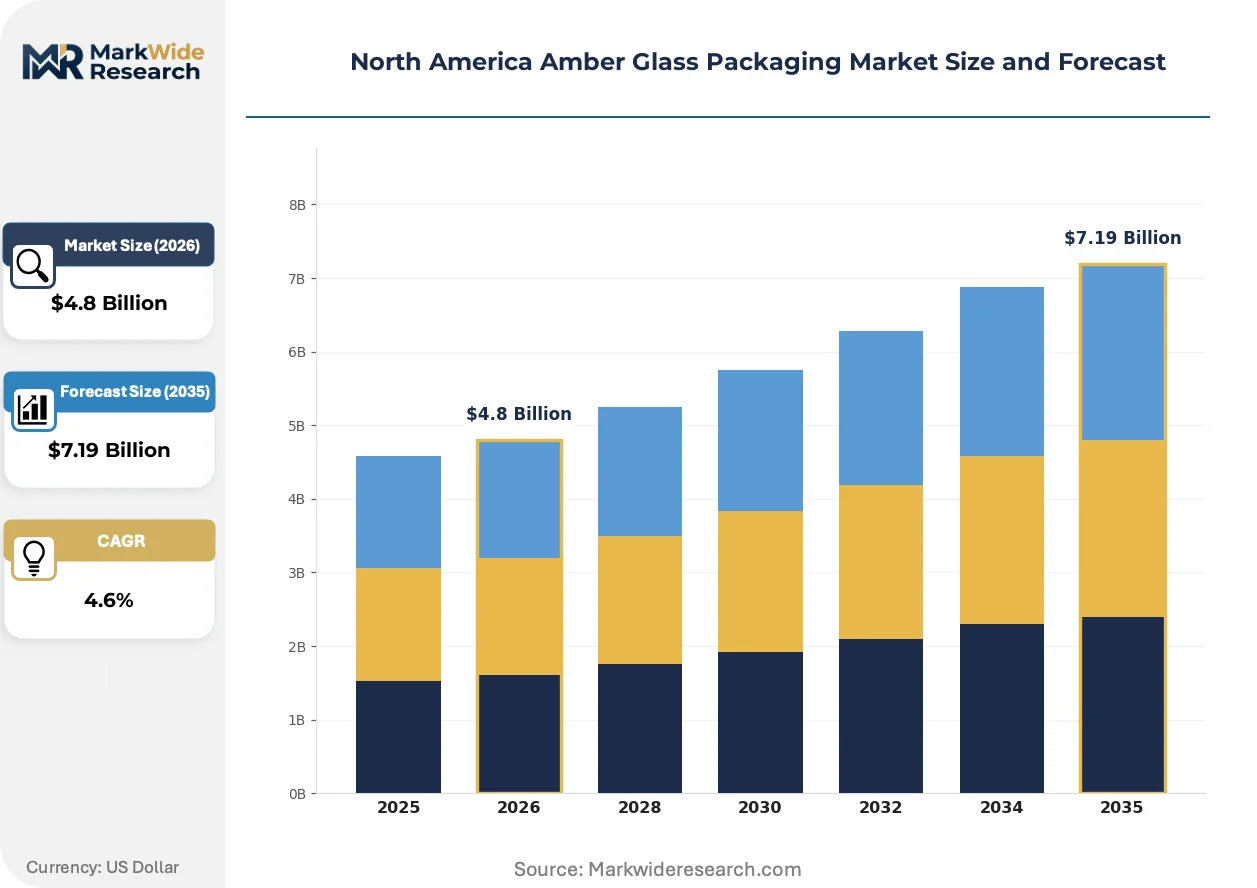
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Jugs Application: Food & Beverages, Pharmaceuticals, Personal Care, Cosmetics Industry Vertical: Retail, Healthcare, Food Service, Beauty End User: Manufacturers, Wholesalers, Distributors, Retailers |
| Companies Covered | Piramal Enterprises Ltd., Kaufman Container, Ardagh Group S.A, Origin Pharma Packaging, Pacific Vial, Gerresheimer AG, Anchor Glass Container Corp., J.G. Finneran Associates, Inc., O-I, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Amber Glass Packaging Market Strategic Shifts & Innovations
Electrification of glass melting and precision forming technologies are compressing energy intensity while tightening dimensional tolerances for pharmaceutical applications. These shifts are reconfiguring capital deployment patterns and supplier qualification criteria.
Narrow-neck press-and-blow forming is migrating from standard beverage bottle production into pharmaceutical-grade amber containers, enabling thinner wall sections with maintained structural integrity. Injectable drug manufacturers in Massachusetts and New Jersey are qualifying these lightweight formats for stability-critical biologics. The technology is migrating from cost-driven beverage applications into compliance-driven pharmaceutical segments where vial weight reduction directly reduces cold-chain shipping costs.
OSHA silica exposure limits are tightening permissible levels in U.S. glass manufacturing facilities, forcing automation investments in batch handling and furnace charging operations. These standards are compressing allowable manual intervention windows and accelerating robotic system deployment. Smaller Midwestern glass producers face disproportionate compliance burdens relative to integrated coastal competitors with existing capital reserves.
Consolidated buying desks at major pharmaceutical contract manufacturers are unbundling container sourcing from fill-finish service contracts, creating direct procurement relationships with glass converters. This disintermediation is compressing distributor margins and exposing price transparency between converter tiers. The pattern is most visible in New Jersey and Pennsylvania, where large CDMOs now negotiate amber glass volumes independently from legacy packaging distributors.
North America Amber Glass Packaging Market Segmentation
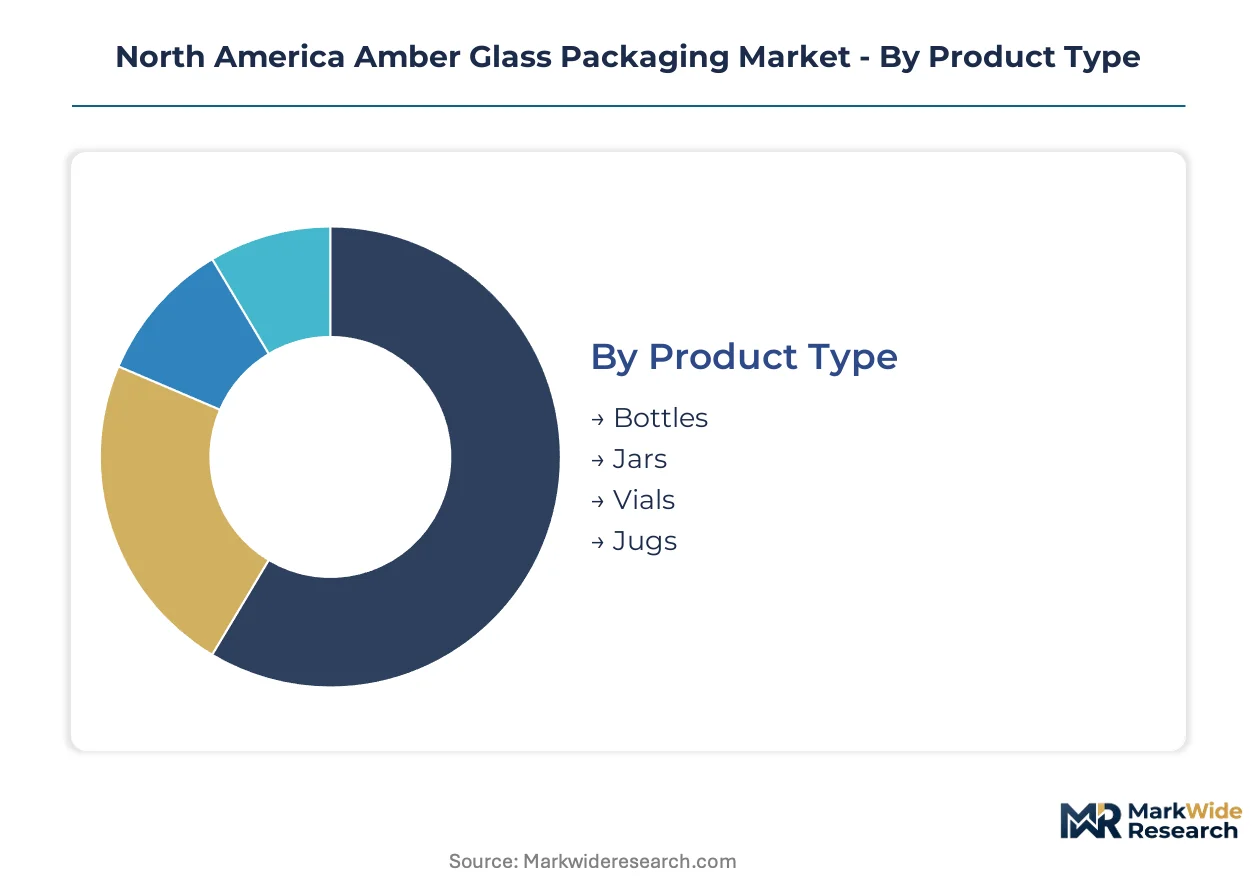
Segmentation in North America amber glass packaging reveals how specification requirements diverge across regulatory environments and end-use criticality. Product form factors, application sensitivity, and channel economics each create distinct procurement patterns that suppliers must navigate simultaneously.
Product Type:
Volume concentration across container geometries reflects the tension between pharmaceutical compliance premiums and beverage cost efficiency.
- Bottles:Soda-lime silica construction with narrow neck press-and-blow forming dominates pharmaceutical oral solid dosage and craft beverage segments. Massachusetts injectable manufacturers are qualifying lightweight amber bottles for cold-chain cost reduction.
- Vials:USP Type I borosilicate-grade specifications mandate dimensional tolerances within 0.1 millimeters for biologics stability. New Jersey CDMO procurement concentrates here, with 18-24 month qualification timelines locking in supplier relationships.
- Jars:Wide-mouth configurations serve niche food preservation and cosmetic cream formats where UV protection requirements remain secondary to moisture barrier performance.
- Jugs:High-capacity formats anchor institutional pharmaceutical compounding and food service syrup dispensing with limited premium positioning.
Bottles hold installed capacity. Vials are rotating up the share rankings.
Application:
Regulatory stringency tiers separate compliance-driven pharmaceutical procurement from cost-optimized consumer segments.
- Pharmaceuticals:FDA ICH Q1B photostability mandates require amber glass for light-sensitive drug categories, with Northeast U.S. biopharma corridors generating concentrated demand for certified vial supply. USP Type I documentation requirements create 18-24 month supplier qualification barriers.
- Food & Beverages:Craft beer and kombucha producers leverage amber glass for brand differentiation and UV protection without pharmaceutical-grade certification overhead. California and New York extended producer responsibility legislation is reshaping collection economics.
- Personal Care:Essential oil and serum formulations require UV blocking for active ingredient stability, though specifications remain below pharmaceutical thresholds.
- Cosmetics:Premium cream and fragrance packaging prioritizes aesthetic amber tinting over functional photoprotection, with shorter supply chains and faster design cycles.
Pharmaceuticals command margin premiums. Food & Beverages is climbing the fastest on volume scale.
Industry Vertical:
Channel structure determines whether procurement flows through consolidated buying desks or fragmented distributor networks.
- Healthcare:Hospital systems and pharmacy chains enforce direct converter relationships, bypassing legacy packaging distributors. New Jersey and Pennsylvania CDMOs now negotiate amber glass volumes independently.
- Retail:Mass merchandisers and specialty grocers drive standardization across beverage and personal care segments, with private label growth compressing branded supplier margins.
- Food Service:Institutional buyers prioritize jug formats and bulk pricing with minimal specification differentiation.
- Beauty:Prestige cosmetics houses source through specialized packaging agencies that coordinate design, decoration, and limited-run production.
Healthcare concentrates purchasing power. Beauty is gaining share fastest on premiumization trends.
End User:
Supply chain position shapes whether stakeholders absorb compliance costs or pass them downstream.
- Manufacturers:Pharmaceutical and beverage producers face direct FDA and EPA regulatory exposure, driving captive qualification investments and long-term converter contracts.
- Wholesalers:Regional pharmaceutical distributors maintain buffer inventory of USP Type I certified stock, bearing working capital costs for availability guarantees.
- Distributors:Legacy packaging intermediaries face margin compression as New Jersey and Pennsylvania CDMOs disintermediate direct converter relationships.
- Retailers:Grocery and drug chains increasingly specify amber glass for private label differentiation, though with limited technical involvement in material selection.
Manufacturers hold specification authority. Retailers are rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical corridors command pricing premiums that Canadian biologics clusters cannot replicate. This asymmetry concentrates converter investment in FDA-regulated supply chains while Health Canada pathways capture volume scale.
United States
FDA ICH Q1B photostability mandates drive amber glass specification for light-sensitive injectables. EPA emissions standards for glass furnaces accelerate oxy-fuel retrofit capital deployment. Massachusetts and New Jersey biopharma corridors concentrate USP Type I vial demand among contract manufacturers.
Canada
Health Canada accelerated biosimilar approval pathways expand demand for pharmaceutical-grade amber containers. Federal carbon pricing mechanisms reshape furnace economics across Ontario and Quebec. Toronto and Montreal manufacturing clusters anchor biologics fill-finish capacity expansion.
Mexico
Nearshoring of pharmaceutical packaging operations attracts amber glass converter investment for U.S. market access. Mexican environmental regulator SEMARNAT enforces emissions standards that lag EPA stringency. Baja California and Querétaro industrial corridors develop specialty glass forming capabilities.
North America Amber Glass Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process control. The North America amber glass packaging market consolidates around three integrated furnace operators with captive melting capacity. Strategic archetypes separate high-volume bottle producers, pharmaceutical-grade vial specialists, and regional distribution extenders. Competitive moves concentrate on furnace electrification partnerships and direct procurement relationships with contract manufacturers.
Among integrated glass producers, Ardagh Group S.A and Gerresheimer AG occupy distinct archetype positions. Ardagh exemplifies the scale-driven platform integrator with captive float-glass technology. Gerresheimer represents the compliance-focused specialist anchored in pharmaceutical-grade certification. Piramal Enterprises Ltd. sits within the distribution extension tier, leveraging North American footprint expansion for specialty container access.
| Leading Market Players |
|---|
| Piramal Enterprises Ltd. |
| Kaufman Container |
| Ardagh Group S.A |
| Origin Pharma Packaging |
| Pacific Vial |
| Gerresheimer AG |
| Anchor Glass Container Corp. |
| J.G. Finneran Associates, Inc. |
| O-I |
| Others |
Cost & Logistics Intelligence
The I-95 freight corridor running from Boston through Philadelphia to Washington carries silica sand and soda ash inbound to furnace operations while outbound amber glass containers move toward pharmaceutical CDMOs in New Jersey and Massachusetts. This logistics backbone concentrates cost leverage among three integrated producers, allowing configured-to-order pharmaceutical vials to command substantial premiums over standard beverage bottles while smaller Midwestern converters absorb disproportionate fuel surcharges.
Pricing Analysis
Configured-to-order USP Type I amber vials for biologics manufacturers carry customization premiums of 40-60% above standard oral solid dosage bottles, with price differentiation driven by certification grade and volume scale. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy beverage-grade levels is compressing at the middle tier as craft brewers consolidate procurement. Cost compression in standard bottles is intensifying because multilayer PET with UV inhibitors captures over-the-counter pharmaceutical share. Mass merchandisers exhibit highest price sensitivity, while Massachusetts biologics CDMOs prioritize qualification speed over unit cost.
Supply Chain Analysis
Export-control regimes on advanced glass-forming equipment from Germany and Japan constrain technology transfer to North American furnace operators, limiting capacity expansion velocity. Geographic supply concentration centers on the United States, Canada, and Mexico, with raw material dependencies drawing from high-purity silica deposits in Wisconsin, soda ash from Wyoming trona mines, and boron for borosilicate grades from Turkey. Single-source furnace vulnerability creates structural risk as pharmaceutical contract manufacturers qualify alternative suppliers. Distribution runs through direct converter relationships with large healthcare buying desks, bypassing legacy packaging distributors in New Jersey and Pennsylvania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized furnace operator scarcity for redox chemistry control represents the critical capability gap constraining market expansion, with aging workforce demographics depleting technical skills faster than training pipelines replenish them.
For Market Incumbents: Build regulatory moats through accelerated USP Type I certification investments for electric melting furnace outputs, securing 18-24 month qualification timelines that lock out emerging competitors. Capture backward integration into Wyoming soda ash sourcing to buffer margin pressure from natural gas volatility. Anchor capacity additions in the Northeast pharmaceutical corridor to defend against Mexican nearshoring entrants. For New Entrants and Emerging Players: Establish a beachhead in Toronto and Montreal biologics clusters where Health Canada accelerated biosimilar pathways outpace FDA qualification backlogs. Target Canadian market entry through partnerships with existing USP Type I certified converters seeking geographic extension rather than greenfield furnace investment. Lead with digital printing convergence for laser-etched serialization as a compliance wedge against legacy label-dependent suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial glass parents seeking to divest non-core pharmaceutical packaging assets with embedded furnace capacity but underutilized certification infrastructure. Long-term viability hinges on electrification capital deployment and direct healthcare procurement relationship depth. Watch for California and New York extended producer responsibility legislation passage as an inflection signal for closed-loop collection infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Partnership | EPA emissions standards force oxy-fuel and electric melting retrofits across US operations. |
| USP Type I Certification Acceleration | FDA ICH Q1B mandates lock in pharmaceutical-grade amber glass demand for light-sensitive drugs. |
| Direct Procurement Relationship | New Jersey and Pennsylvania CDMOs bypass distributors to negotiate amber glass volumes independently. |
| Canadian Biologics Expansion | Health Canada accelerated biosimilar pathways drive demand for pharmaceutical-grade amber vials. |
| Closed-Loop Collection Infrastructure | Pending California and New York EPR legislation reshapes recycling cost structures for converters. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA drug packaging guidance documents, EPA emissions compliance filings, and Health Canada regulatory notices. Primary interviews engaged furnace operations managers, pharmaceutical packaging procurement leads at CDMOs, regulatory affairs specialists, and glass batch chemists. Secondary validation drew from SEC 10-K filings of integrated glass producers, customs trade data on soda ash and silica imports, and OSHA silica exposure enforcement records. Bottom-up capacity modeling triangulated against top-down pharmaceutical production forecasts.
Forecast inputs span product type segmentation across bottles, vials, jars, and jugs; application tiers from pharmaceutical-grade to beverage-grade; and regional regulatory clusters distinguishing FDA, Health Canada, and SEMARNAT jurisdictions. Modeled variables include furnace electrification capex cycles, USP Type I certification queue lengths, and extended producer responsibility implementation timelines. CAGRs derive from regression analysis of historical pharmaceutical production growth against amber glass container intensity ratios.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, pharmaceutical R&D investment cycles, or biologics approval velocity would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and furnace technology migration timelines. Material shifts in EPA emissions standard stringency or FDA photostability testing protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
United Arab Emirates Glass Packaging Market