
 Foldable/Compressible Beverage Carton Market | 2026-2036
Foldable/Compressible Beverage Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable/Compressible Beverage Carton Market Foresight
Polyethylene-coated paperboard is rebalancing toward PLA bioplastic and cellulose laminates as brand owners absorb extended producer responsibility costs. Tetra Pack Group leverages its aseptic filling integration to sustain premium positioning in dairy and juice applications. Stora Enso AB anchors Nordic supply through captive pulp sourcing and certified fiber traceability. WestRock competes on corrugated integration, offering beverage clients combined primary and secondary packaging procurement.
Foldable and compressible beverage cartons are rigid or semi-rigid containers engineered from multi-ply substrates, typically 300–400 gsm liquid packaging board with internal polyethylene or aluminum barrier layers, designed to collapse flat after emptying for reduced post-consumer volume. Their primary purpose is to contain liquid refreshments while minimizing storage footprint throughout retail distribution and consumer disposal. Gable top formats dominate ambient dairy and juice segments due to established filling line compatibility and consumer familiarity. Aseptic packaging styles command margin concentration because sterilized shelf-stable formats eliminate cold chain dependency for beverage manufacturers. Spouted designs in energy drinks and on-the-go coffee applications represent the fastest structural expansion, driven by single-serve convenience positioning among food service providers and vending operators.
The EU Green Deal and REACH frameworks mandate recyclability thresholds and restrict persistent barrier coatings, compelling converters to validate fiber recovery rates through CE marking protocols. The EPA and state-level extended producer responsibility laws in California and New York impose fee structures tied to post-consumer collection targets, reshaping material specifications for brands exporting to North America. Stakeholders must monitor how the EU AI Act's supply chain traceability requirements intersect with packaging passport mandates, as automated sorting and digital product identifiers become compliance prerequisites rather than voluntary sustainability markers.
Market Dynamics
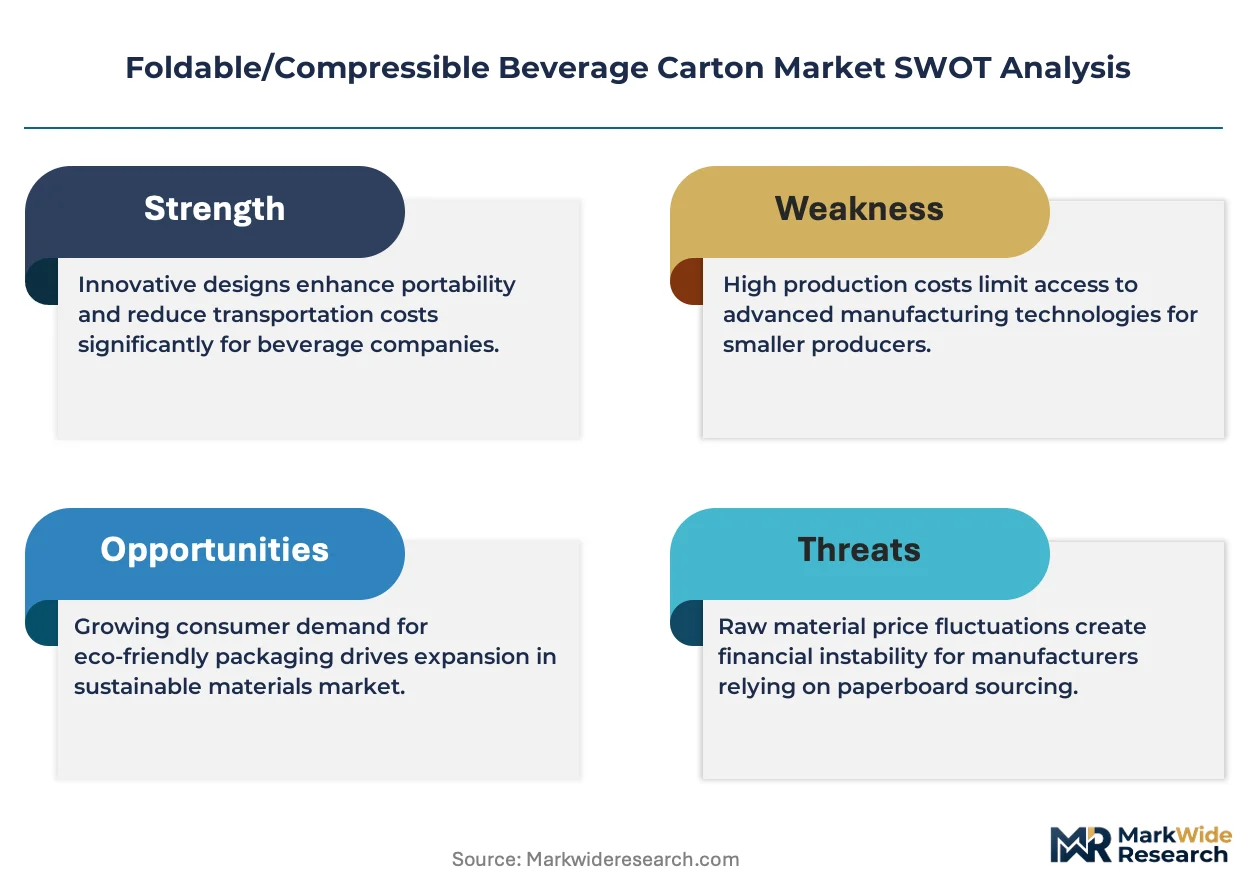
Extended producer responsibility frameworks are compressing margins across the foldable beverage carton value chain, forcing converters to absorb end-of-life collection costs while reformulating barrier substrates to meet fiber recovery mandates.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory recyclability thresholds under the Green Deal are compelling dairy and juice brands to transition from polyethylene-coated formats toward cellulose-based laminates, expanding addressable demand for fiber-compliant designs.
- Vending channel expansion:Food service operators and automated retail networks in Germany are standardizing shelf-efficient compressible formats to maximize SKU density in constrained footprint environments.
- Aseptic filling compatibility:Shelf-stable sterilization technology eliminates cold chain dependency for beverage manufacturers, opening ambient distribution channels previously locked to refrigerated supply chains.
Market Restraints
- Pulp input cost volatility:Nordic softwood pulp pricing swings directly compress converter margins, as liquid packaging board specifications require 300–400 gsm virgin fiber grades with limited recycled content flexibility.
- Aluminum barrier supply concentration:Thin-gauge foil lamination for oxygen-sensitive beverages depends on a concentrated supplier base in Scandinavian metallurgy clusters, creating single-source vulnerability during energy price spikes.
- REACH coating restrictions:Persistent fluorinated barrier chemistries face phase-out timelines under ECHA authorization protocols, forcing premature capital redeployment toward unproven bio-based alternatives.
Strategic Opportunities
- Spouted format penetration:Energy drink and ready-to-drink coffee applications represent underexploited white space, as single-serve convenience positioning aligns with on-the-go consumption patterns among urban demographics.
- California EPR implementation:State-level extended producer responsibility fee structures create first-mover advantage for brands validating post-consumer collection infrastructure ahead of 2030 compliance deadlines.
- Digital product passport integration:EU AI Act supply chain traceability requirements are converging with automated sorting infrastructure, enabling premium positioning for cartons embedding blockchain-verified fiber provenance.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise spanning polymer science, fiber engineering, and food-contact compliance concentrates in legacy packaging conglomerates, constraining mid-tier converter R&D velocity.
- CE marking validation timelines:Third-party certification of fiber recovery rates under evolving testing protocols extends product launch cycles by 8–14 months, compressing competitive response windows.
- Legacy filling line retrofit costs:Gable top equipment dominates dairy and juice installed bases, and spouted format adoption requires capital-intensive changeover of aseptic sealing mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable/Compressible Beverage Carton Market |
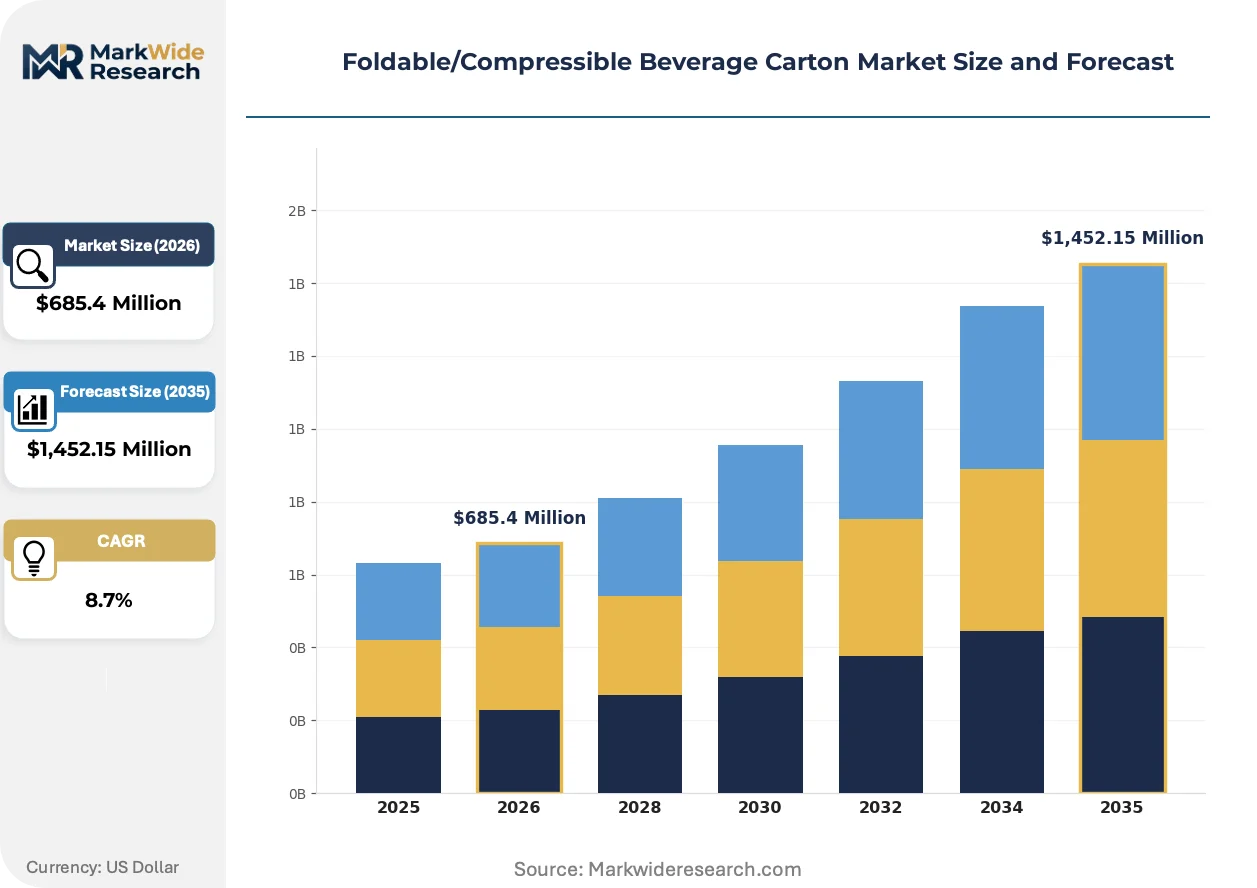
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Polyethylene, Aluminum Foil, PLA Bioplastic, PET, Cellulose Filling Type: Carbonated Drinks, Juices, Dairy Beverages, Water, Tea & Coffee, Energy Drinks Packaging Style: Gable Top, Flat Bottom, Spouted, Aseptic, Sleeve Wrapped, Wraparound End User: Beverage Manufacturers, Food Service Providers, Retail Chains, Vending Operators, Institutional Buyers |
| Companies Covered | Tetra Pack Group, Stora Enso AB, WestRock, Sig Holding AG, ELOPAK, Visy Industries, Ingersoll Paper Box, International Paper, TigerPress, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable/Compressible Beverage Carton Market Shifts & Advancements
Barrier material science and automated production systems are restructuring competitive advantage in beverage carton manufacturing, separating converters with captive biopolymer development from commodity substrate suppliers.
Near-infrared sorting compatibility layers are automating the separation of cellulose laminates from contamination streams in municipal recovery facilities. German retail chains and Dutch waste processors are specifying these detectable substrates in procurement tenders released since 2023. The technology is automating compliance with EU packaging waste directives by enabling high-purity fiber recovery without manual presorting.
REACH authorization reviews for persistent organic pollutants are accelerating substitution timelines for polyethylene barrier coatings. ECHA's restriction proposals targeting per- and polyfluoroalkyl substances in food contact materials are forcing reformulation of internal laminates before 2027 sunset dates. Dairy applications with extended shelf-life requirements face the steepest technical adaptation curves, as oxygen transmission rate specifications tighten under revised safety assessments.
Consolidated beverage procurement through retail private-label programs is compressing supplier rosters and elevating volume-scale requirements. German discount chains and Nordic cooperative buying groups are consolidating carton sourcing across juice, dairy, and plant-based beverage categories. This concentration is most visible in Central European markets, where three retail banners now control over sixty percent of ambient carton placement decisions.
Foldable/Compressible Beverage Carton Market Segmentation
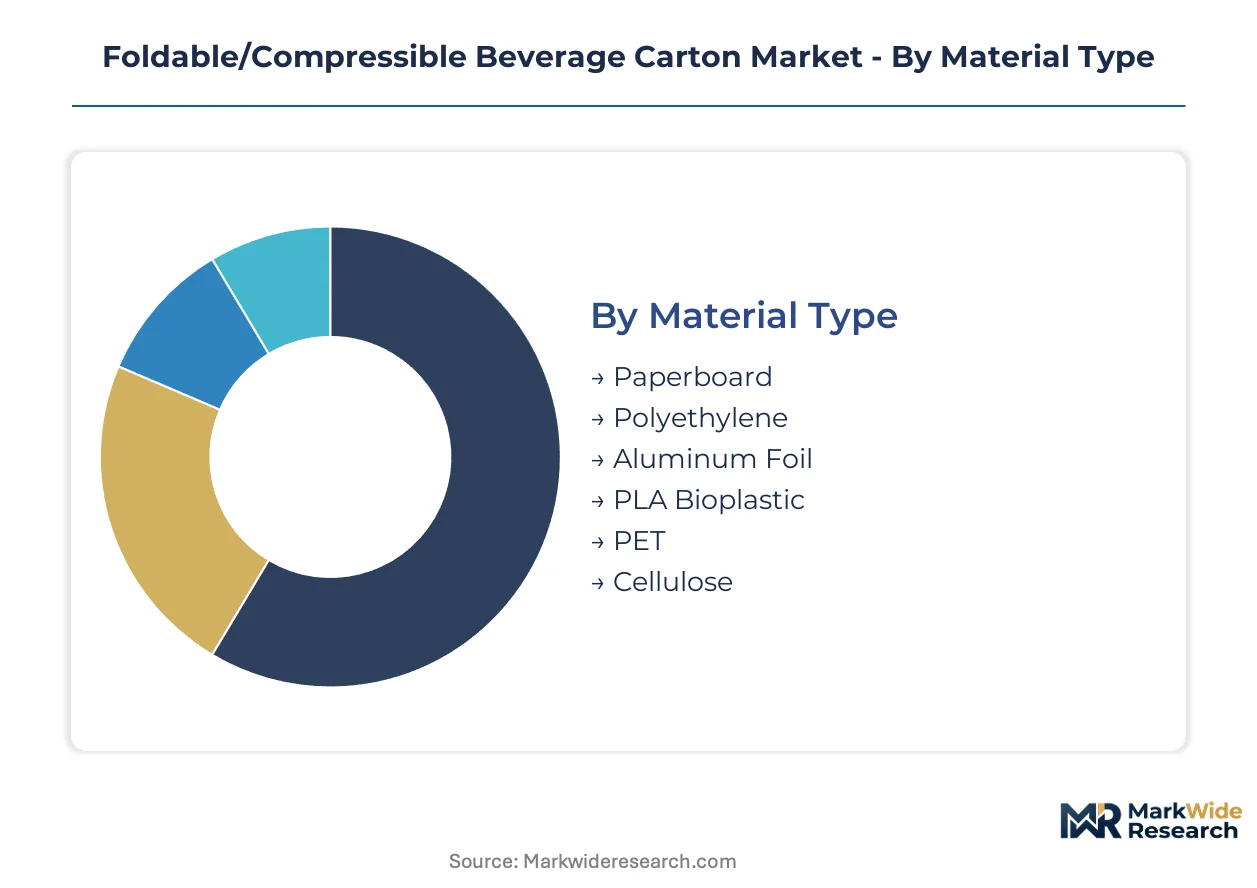
Material substrate selection and filling line compatibility determine converter capital allocation and margin structure in foldable beverage cartons. Each segmentation dimension reveals distinct barriers to entry and customer switching costs that shape competitive positioning.
Material Type:
Paperboard and aluminum foil laminates demand the heaviest upfront investment in metallization and coating infrastructure, while bioplastic alternatives require downstream compounding capabilities.
- Paperboard:Virgin liquid packaging board at 300–400 gsm forms the structural backbone of ambient cartons. German dairy brands specify Nordic softwood grades for stiffness and printability under EU Green Deal fiber traceability mandates.
- Aluminum Foil:Thin-gauge oxygen barriers at 6–9 microns enable 12-month shelf stability for aseptic juice applications. Scandinavian metallurgy clusters supply the majority of European converters, creating single-source vulnerability during energy price volatility.
- Polyethylene:Internal lamination layers provide moisture resistance and heat-seal functionality. REACH authorization reviews are forcing premature phase-out of conventional grades.
- PLA Bioplastic:Polylactic acid derived from corn starch offers compostable end-of-life pathways. Industrial composting infrastructure gaps limit deployment to premium organic beverage lines.
- PET:Recycled polyethylene terephthalate integrates into sleeve-wrapped formats for carbonated drinks. California EPR fee structures favor post-consumer content validation.
- Cellulose:Regenerated wood pulp barriers replace synthetic coatings in next-generation fiber-compliant designs. Near-infrared sorting compatibility automates municipal recovery compliance.
Most installed capacity flows through paperboard. Expansion is steepest in cellulose laminates as ECHA sunset dates approach.
Filling Type:
Carbonated and aseptic applications generate the widest margin spreads due to barrier complexity and sterilization equipment integration.
- Dairy Beverages:Extended shelf-life milk and cream demand aluminum-foil oxygen barriers and sterile filling environments. Nordic cooperatives anchor volume procurement through private-label consolidation.
- Juices:Ambient-stable concentrates and not-from-drink categories rely on aseptic carton compatibility. German discount chains standardize gable top formats across private-label placement.
- Carbonated Drinks:Internal pressure resistance requires multilayer board construction with PET or aluminum reinforcement. Filling line retrofits for CO2 retention add capital intensity.
- Water:Still and sparkling variants prioritize cost minimization over barrier sophistication. Shelf-stable formats gain traction in vending channel expansion.
- Tea & Coffee:Ready-to-drink and cold brew segments favor spouted convenience formats. Urban food service operators drive single-serve specification.
- Energy Drinks:Functional beverage brands adopt compressible cartons for gym and convenience store distribution. On-the-go consumption patterns accelerate spouted design adoption.
Procurement concentrates in dairy and juice. Energy drinks are gaining share fastest as convenience positioning penetrates younger demographics.
Packaging Style:
Aseptic and spouted formats require the most specialized sealing and sterilization capital, while gable top equipment dominates legacy installed bases.
- Aseptic:Sterilized filling environments eliminate cold chain dependency through hydrogen peroxide or UV treatment integration. Shelf-stable distribution opens ambient retail channels previously locked to refrigerated supply chains.
- Spouted:Screw-cap or flip-top closures enable resealability for energy drinks and ready-to-drink coffee. Food service providers and vending operators prioritize single-serve convenience in constrained footprint environments.
- Gable Top:Established dairy and juice filling line compatibility minimizes capital redeployment. Consumer familiarity sustains volume placement in German retail chains.
- Flat Bottom:Shelf-stable standing pouch alternatives compete in plant-based beverage segments. Secondary packaging efficiency drives adoption in e-commerce fulfillment.
- Sleeve Wrapped:Shrink-label decoration enables brand differentiation without substrate modification. PET integration supports post-consumer recycling claims.
- Wraparound:Corrugated secondary packaging integration offers combined primary and secondary procurement efficiency. WestRock and integrated converters compete on bundled sourcing.
Production gravity centers on gable top. Steepest expansion trajectory belongs to spouted formats as on-the-go consumption accelerates.
End User:
Beverage manufacturers and retail chains command the largest volume contracts, while vending operators drive format innovation for space-constrained deployment.
- Beverage Manufacturers:Integrated dairy and juice producers specify aseptic filling compatibility and fiber recovery compliance. Extended producer responsibility costs flow upstream to converter pricing negotiations.
- Retail Chains:German discount banners and Nordic cooperatives consolidate procurement across private-label programs. Three Central European banners control the majority of ambient carton placement decisions.
- Vending Operators:Automated retail networks in Germany standardize compressible formats to maximize SKU density. Shelf-efficient designs reduce restocking frequency in constrained footprint environments.
- Food Service Providers:Cafes and institutional catering specify single-serve spouted formats for grab-and-go positioning. Urban demographic concentration drives regional demand clustering.
- Institutional Buyers:Schools, hospitals, and corporate catering prioritize cost minimization and portion control. Bulk procurement contracts emphasize standard gable top economics.
Contract concentration sits with beverage manufacturers. Vending operators are expanding most quickly as automated retail networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail chains and vending operators anchor foldable beverage carton demand through shelf-efficient procurement standards that compress logistics costs across ambient dairy and juice distribution networks.
Germany
Discount banners Aldi and Lidl consolidate private-label carton sourcing across juice, dairy, and plant-based beverage categories. The EU Green Deal packaging waste directives mandate fiber recovery thresholds that accelerate cellulose laminate adoption. Stuttgart and Munich industrial clusters host converter facilities specializing in aseptic filling line integration.
United States
California and New York state-level extended producer responsibility laws impose fee structures tied to post-consumer collection targets, reshaping material specifications for beverage brands. The EPA oversees compliance frameworks that intersect with state mandates. Pacific Northwest pulp supply chains feed liquid packaging board production for West Coast dairy processors.
China
Urban vending network expansion in Shanghai and Beijing drives demand for compressible formats maximizing SKU density in constrained retail footprints. SAMR regulates food-contact material safety under evolving GB standards. Yangtze River Delta converters develop near-infrared sorting compatible substrates for municipal recovery compliance.
Sweden
Nordic cooperative buying groups standardize fiber traceability requirements through certified chain-of-custody protocols. ECHA REACH authorization reviews target persistent fluorinated barrier chemistries with 2027 sunset timelines. Stockholm-Uppsala metallurgy clusters supply thin-gauge aluminum foil lamination for oxygen-sensitive aseptic applications.
Netherlands
Dutch waste processors specify detectable cellulose substrates in procurement tenders released since 2023, automating high-purity fiber recovery. CE marking validation protocols under EU packaging waste directives extend product launch cycles for converter innovations. Randstad logistics hubs concentrate beverage distribution infrastructure serving Benelux retail networks.
Foldable/Compressible Beverage Carton Market Competitive Landscape
Global majors compete with regional champions across filling line integration and fiber traceability certification, creating a tiered structure where scale-driven conglomerates hold aseptic technology advantages while specialized converters compete on sustainability credentials. Three archetypes dominate: integrated packaging conglomerates with captive pulp sourcing, machinery-integrated solution providers, and regional converters leveraging proximity to retail procurement hubs. Competitive moves concentrate on strategic partnerships for biopolymer development and capacity expansion in fiber-compliant substrate manufacturing.
Within the integrated conglomerate tier, Tetra Pack Group and Stora Enso AB exemplify divergent strategic positions. Tetra Pack Group occupies a machinery-anchored position through aseptic filling system integration that locks in dairy and juice manufacturer relationships. Stora Enso AB represents the captive-resource archetype, with Nordic pulp supply chain control enabling certified fiber traceability claims. WestRock sits within the corrugated-integration segment, competing on bundled primary and secondary packaging procurement efficiency for beverage clients seeking consolidated vendor relationships.
| Leading Market Players |
|---|
| Tetra Pack Group |
| Stora Enso AB |
| WestRock |
| Sig Holding AG |
| ELOPAK |
| Visy Industries |
| Ingersoll Paper Box |
| International Paper |
| TigerPress |
| Others |
Supply & Pricing Matrix
Near-infrared sorting compatibility layers are simultaneously elevating converter R&D expenditure and consolidating procurement leverage among German retail chains that specify detectable substrates. This dual cost-and-concentration dynamic reshapes how cellulose laminate producers negotiate volume contracts against legacy polyethylene-coated board suppliers.
Pricing Analysis
Input-cost pass-through from Nordic softwood pulp swings dominates converter margin structure, with virgin fiber grades at 300–400 gsm commanding premium contract tiers. Three-tier pricing structure across premium, standard, and economy levels separates aseptic-compatible cellulose laminates from gable top polyethylene formats and commodity board for institutional buyers. Cost compression in standard tiers is intensifying because ECHA sunset dates force premature barrier reformulation. Beverage manufacturers with integrated filling lines exhibit lowest price sensitivity; vending operators and institutional buyers drive hardest bargain pressure.
Supply Chain Analysis
CE marking validation and EU Green Deal fiber traceability certification gate entry for converters serving German retail chains and Nordic cooperatives. Geographic supply concentration rests on Sweden for metallized foil lamination, Finland for captive pulp sourcing, and Germany for aseptic filling line integration. Raw material dependencies center on Nordic softwood pulp, thin-gauge aluminum from Scandinavian metallurgy clusters, and PLA bioplastic feedstock. Single-source vulnerability in aluminum foil supply creates structural exposure during energy price spikes. Distribution runs through Randstad logistics hubs and Stuttgart industrial clusters into Benelux and Central European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foldable beverage carton market functions as a regulatory compounder where EU Green Deal packaging waste directives mandate fiber recovery thresholds that mechanically expand addressable demand for compliant substrate designs.
For Market Incumbents: Cement machinery-anchored relationships through aseptic filling line integration that locks in dairy and juice manufacturer switching costs. Deepen backward integration into captive pulp sourcing to neutralize Nordic softwood price volatility. Prioritize certification investment in CE marking protocols ahead of competitor validation timelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in spouted format energy drink applications offers white-space entry with lower capital intensity than aseptic dairy segments. Target food service provider procurement in urban German clusters where single-serve convenience specifications outpace incumbent response velocity. Pursue direct-to-vending-operator go-to-market positioning that bypasses consolidated retail chain supplier rosters. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with cellulose laminate pilot capacity but lacking CE marking validation. Long-term viability favors machinery-integrated solution providers over commodity substrate suppliers as automated sorting infrastructure proliferates. Watch for inflection where California EPR fee structures trigger North American material specification convergence with EU mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Stora Enso AB's captive Nordic fiber supply neutralizes raw material volatility for German dairy contracts. |
| Aseptic Filling Line Compatibility Investment | Tetra Pack Group's sterilization technology integration locks in shelf-stable beverage manufacturer relationships. |
| Near-Infrared Sorting Substrate Development | Dutch waste processor procurement tenders since 2023 automate municipal recovery compliance for compliant converters. |
| Spouted Format Capacity Expansion | Food service provider demand for energy drink and ready-to-drink coffee convenience accelerates format penetration. |
| Digital Product Passport Integration | EU AI Act supply chain traceability requirements enable blockchain-verified fiber provenance premium positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with converter operations directors, beverage manufacturer procurement leads, retail chain category buyers, and Dutch waste processor technical managers with secondary validation. Regulatory filings from ECHA authorization reviews, EU Green Deal implementation directives, EPA state-level EPR frameworks, and SAMR GB standards provided compliance trajectory inputs. Customs data on Nordic softwood pulp trade flows and liquid packaging board production statistics anchored supply-side modeling. Bottom-up volume builds triangulated against top-down macroeconomic consumption projections.
Segment-weighting approaches distributed value and volume across material type, filling compatibility, packaging style, and end-user procurement archetype dimensions. CAGRs derived from regression analysis of historical adoption curves applied to regulatory mandate timelines and filling line retrofit cycles. Industry-specific forecast inputs incorporated ECHA sunset date phase-out schedules and German vending network expansion trajectories across the analysis window.
Caveats apply where ECHA authorization timeline acceleration or Nordic energy price volatility spikes could materially shift the outlook. Forecasts embed assumptions about CE marking validation throughput rates and retail chain supplier consolidation velocity. A model refresh is warranted upon material change in EU packaging waste directive enforcement stringency or California EPR fee structure implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Braille Cartons Packaging Market
Cartons
Beverage Cartoners Market
Cartons
Carton Bottle Market
Cartons
Carton Sealer Market
Cartons
Folding Cartons Market
Cartons
Carton Liners Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Japan Corrugated Boxes Market
Cartons
Global Cartonboard Market
Cartons
Carton Sealer Machine Market
Cartons
Luxury Folding Carton Market
Cartons
Global Open Top Cartons Market
Cartons
Tetrahedron Carton Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Carton Display Market