
 Ethiopia Container Glass Market | 2026-2036
Ethiopia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Ethiopia Container Glass Market Insights
Ethiopian Investment Commission local content mandates for industrial park tenants is restructuring glass sourcing requirements across beverage and pharmaceutical packaging buyers. Addis Ababa Bottle and Glass Share Company leverages vertical integration from silica sand access through finished bottle production to anchor supply security for domestic brewers. East African Glass competes on furnace scale and multi-format flexibility across amber and flint glass lines. Juniper Glass Industries PLC specializes in pharmaceutical-grade borosilicate and soda-lime containers for injectable and oral dosage packaging.
Container glass comprises silica sand, soda ash, limestone, and cullet melted in continuous or batch furnaces at temperatures exceeding 1500°C, then formed via blow-and-blow or press-and-blow methods into hollow vessels designed for product protection, shelf stability, and consumer handling. The material serves as the primary barrier packaging for carbonated beverages, wines, spirits, and sensitive pharmaceuticals across Ethiopia's growing manufacturing base. Bottles dominate volume throughput given brewery and soft-drink bottler offtake, while pharmaceutical-grade amber and flint bottles command premium positioning due to compliance burdens and certification requirements. Jars and jugs occupy narrower but expanding niches in processed food exports and household chemical packaging. Transparent and brown forms split demand between premium beverage visibility branding and UV-sensitive pharmaceutical and beer protection.
Ethiopian Investment Commission industrial park regulations, Ethiopian Standards Agency container specifications, and Ministry of Health pharmaceutical packaging directives collectively shape product standards, testing protocols, and market access conditions for domestic and imported glass. The Ethiopian Customs Commission enforces import duty differentials that protect local furnace operations against dumped container imports from Middle Eastern and Asian suppliers. Stakeholders must monitor Addis Ababa's planned municipal waste segregation mandates and their impact on cullet recovery economics and furnace batch cost structures.
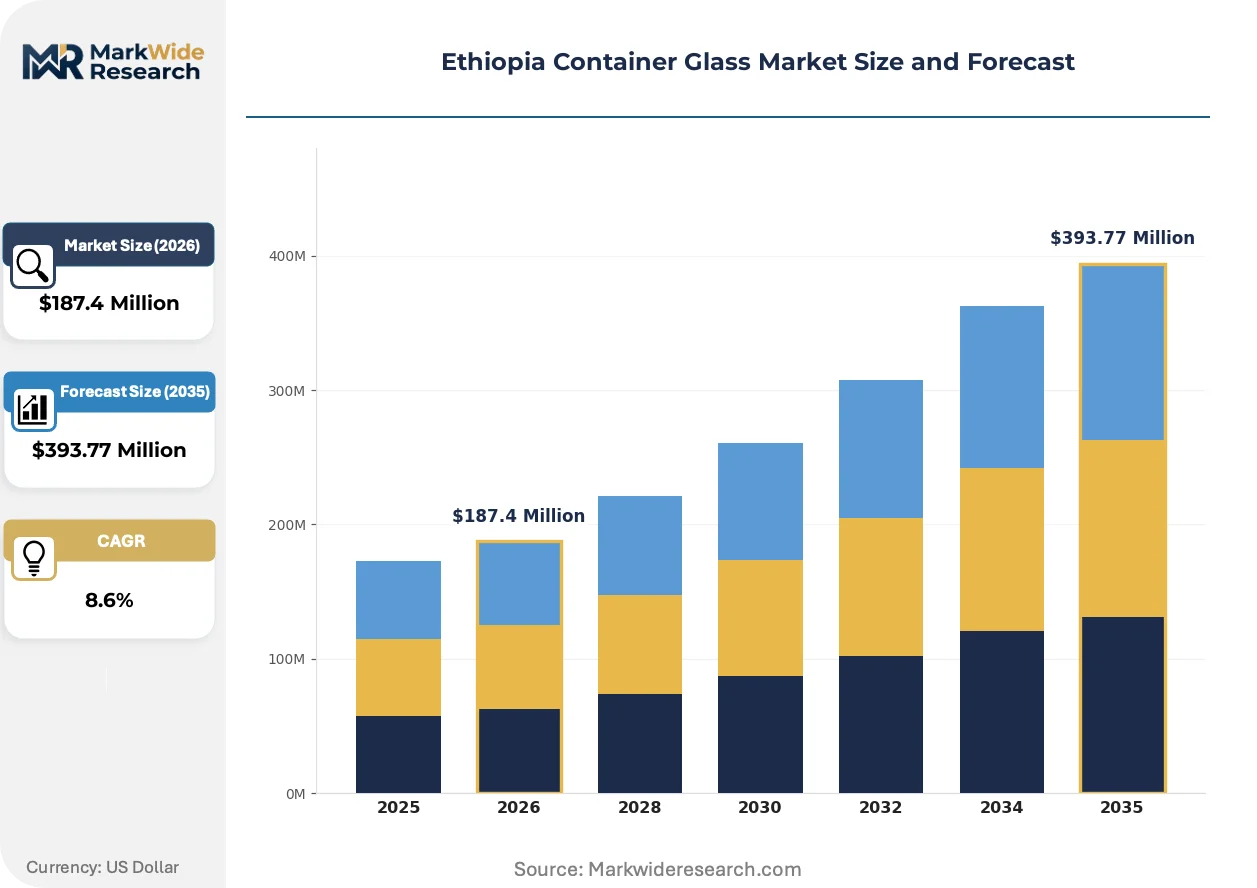
Market Dynamics
Ethiopian Investment Commission local content mandates are restructuring procurement patterns across beverage and pharmaceutical packaging buyers, forcing furnace operators to reconfigure batch compositions and supply contracts around domestic silica sand and cullet recovery networks.
Growth Catalysts
- Industrial Park Incentives:Ethiopian Investment Commission tax holidays and duty exemptions for industrial park tenants are pulling beverage bottler capacity expansion into Addis Ababa and Oromia corridor zones.
- Pharmaceutical Packaging Directives:Ministry of Health mandates for amber and flint glass containment of light-sensitive injectables are creating certified demand pull from domestic drug manufacturers.
- Cullet Recovery Economics:Addis Ababa municipal waste segregation pilots are improving furnace batch cost structures through higher post-consumer glass recovery rates.
Market Restraints
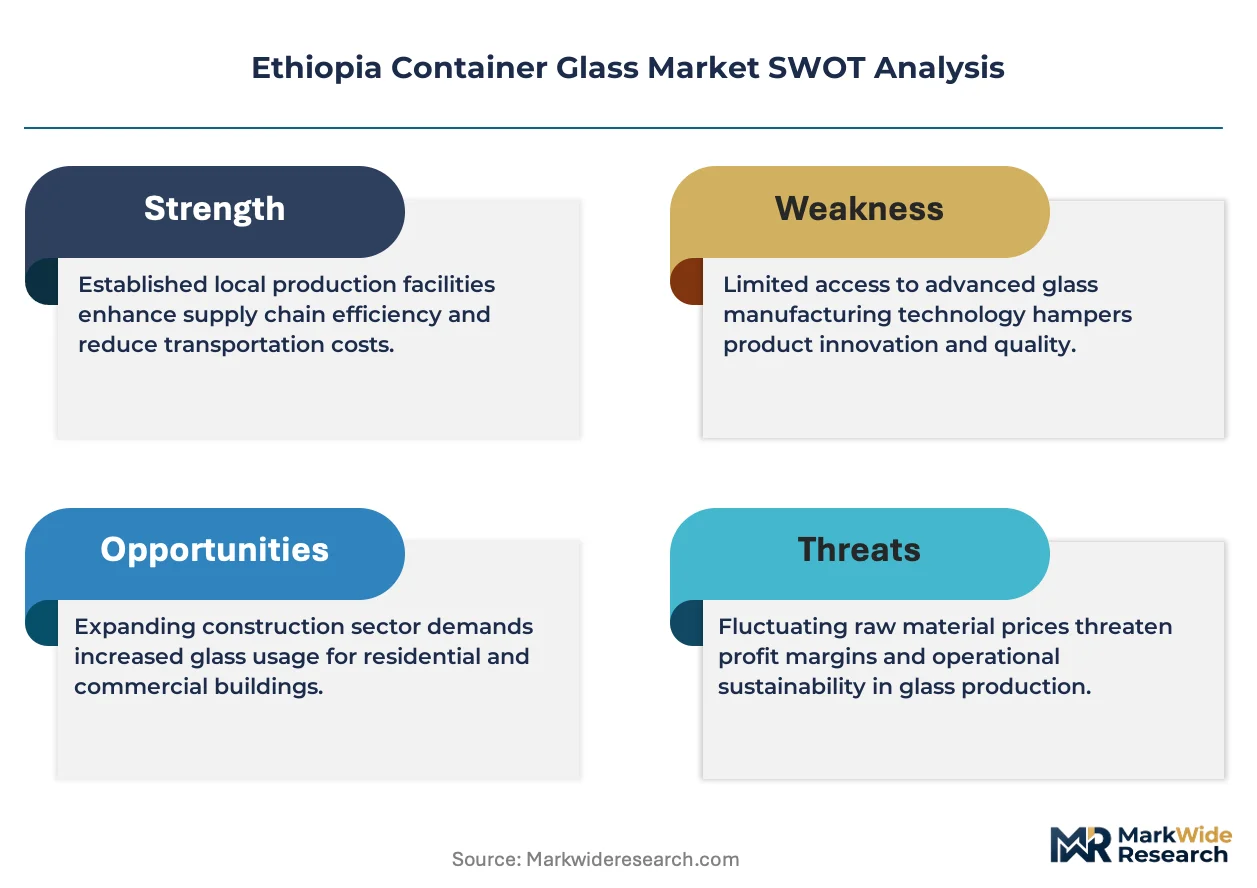
- Soda Ash Import Dependency:Ethiopia lacks domestic soda ash production, exposing furnace operators to currency-driven input cost volatility from Egyptian and Turkish suppliers.
- Furnace Scale Concentration:Container glass supply clusters around three furnace operations in Addis Ababa, creating geographic concentration risk for brewers and bottlers in regional cities.
- Plastic Substitution Threat:PET bottle imports from Gulf states are capturing share in carbonated soft drinks where UV protection requirements are minimal.
Strategic Opportunities
- Processed Food Export Packaging:Jars and jugs for spice and sauce exports to Middle Eastern diaspora markets remain underpenetrated relative to beverage bottling saturation.
- Pharmaceutical-Grade Certification:WHO-prequalification pathways for domestic glass manufacturers open tender access to African Union pooled procurement programs.
- Hybrid Solar-Thermal Furnace Trials:Converging photovoltaic and natural gas combustion technologies are piloting at smaller furnace lines to deflect energy cost pressures.
Industry Challenges
- Skilled Furnace Operations Talent:Experienced batch chemists and furnace engineers with continuous-tank expertise are scarce in domestic labor markets, forcing reliance on expatriate technical staff.
- Ethiopian Standards Agency Certification Timelines:Container specification testing protocols for new bottle formats average 14-18 months, compressing product launch windows for seasonal beverage variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethiopia Container Glass Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Carafes End User: Food and Beverage, Cosmetics, Pharmaceuticals, Household Form: Transparent, Green, Brown, Frosted Packaging Type: Bulk Packaging, Retail Packaging, Recyclable Packaging, Durable Packaging |
| Companies Covered | Addis Ababa Bottle and Glass Share Company, East African Glass, Juniper Glass Industries PLC, CONSOL Glass, Ethiopian Crown Cork and Can Manufacturing PLC, Daylight Applied Technologies, Addis Glass Manufacturing, Daylight Engineering, Roha Ventures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethiopia Container Glass Market Trends and Innovations
Lightweighting technologies and cullet-intensive batch formulations are compressing energy intensity per container, while regulatory pressure on pharmaceutical packaging integrity and municipal waste recovery targets reshape furnace economics and sourcing protocols.
Electrical boosting systems in natural gas-fired furnaces are absorbing incremental melting load to reduce carbon intensity per ton of glass produced. Brewery and soft-drink bottler technical teams are specifying these retrofits in new furnace contracts. The technology is absorbing capital allocation that previously expanded furnace tank capacity, shifting investment toward efficiency rather than volume.
Ethiopian Standards Agency container specifications are tightening dimensional tolerance and thermal shock resistance requirements for pharmaceutical-grade amber glass. Domestic manufacturers are reconfiguring annealing lehr parameters and mold cooling systems to meet these thresholds. Injectable drug packaging lines in Addis Ababa pharmaceutical parks are most affected, with buyers consolidating supplier relationships around certified furnace operators.
Beverage bottler technical procurement teams are consolidating supplier relationships around single-source furnace operators with captive silica sand mining rights. Direct contracting with integrated producers is displacing distributor-mediated purchasing for high-volume brewery accounts. This consolidation is most visible in Addis Ababa and Hawassa industrial zones where capacity expansion concentrates.
Ethiopia Container Glass Market Segmentation
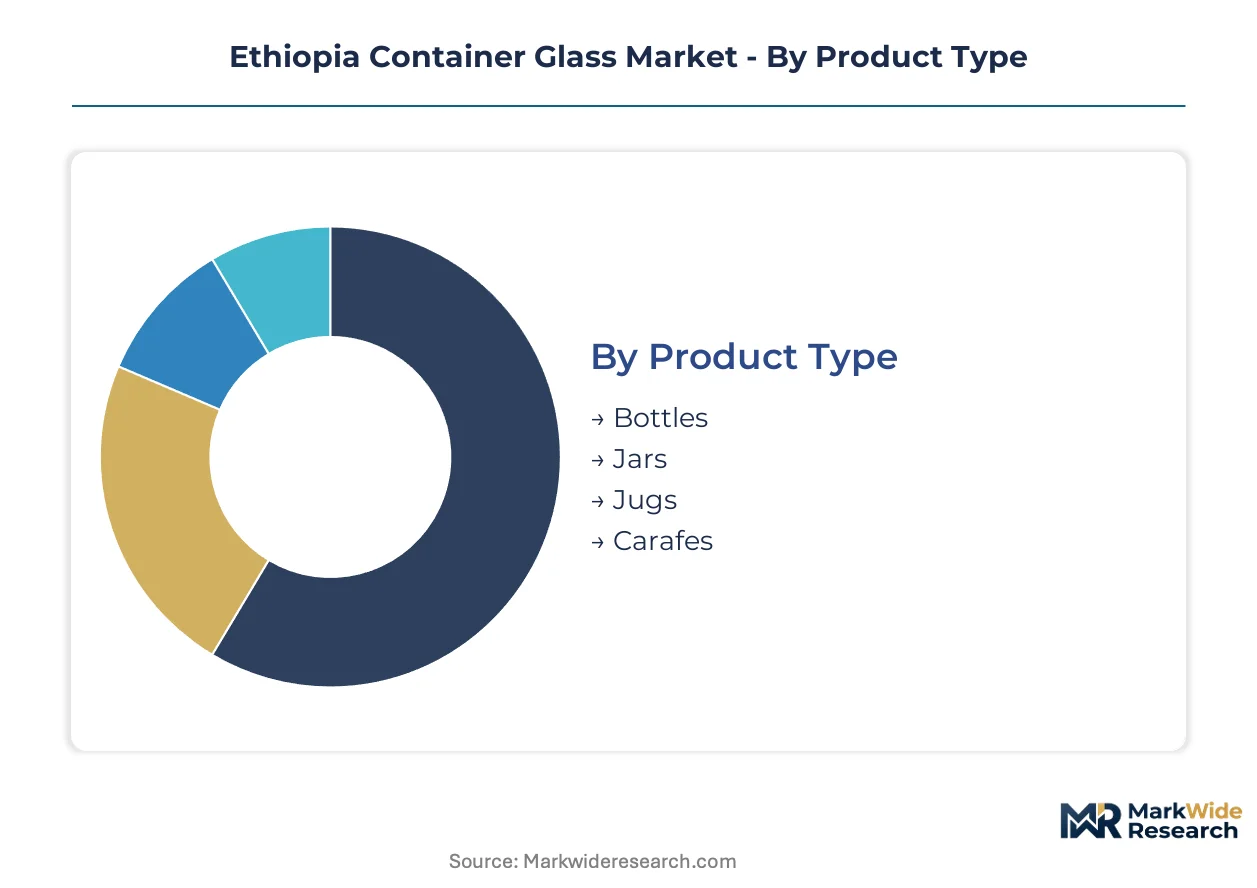
Segmentation in Ethiopia's container glass market exposes how furnace capacity, regulatory mandates, and end-use specifications concentrate value across distinct product and customer categories. Understanding these splits reveals where batch chemistry investments, certification burdens, and supply security requirements diverge most sharply.
Product Type:
Supply concentration around Addis Ababa furnace operations shapes which product formats absorb capital allocation and technical talent.
- Bottles:Hollow vessels formed via blow-and-blow or press-and-blow methods dominate silica sand consumption and furnace throughput. Brewery and soft-drink bottler procurement in Addis Ababa and Hawassa industrial corridors absorbs the bulk of flint and amber glass output, with Ethiopian Investment Commission local content mandates locking in domestic sourcing.
- Jars:Wide-mouth containers with screw-finish necks serve processed food exports and household chemical packaging. Demand from spice and sauce exporters to Middle Eastern diaspora markets is climbing fastest as Ethiopian agro-processing expands.
- Jugs:Large-format handled containers occupy narrow niches in edible oil and traditional beverage distribution. Regional city bottlers outside Addis Ababa face higher logistics costs for this lower-velocity format.
- Carafes:Decorative and premium beverage service vessels command artisanal production runs rather than continuous furnace output. Hotel and restaurant procurement in Addis Ababa drives sporadic demand.
Bottles absorb the bulk of installed capacity; jars are expanding most quickly.
End User:
Cost tier stratification across end users determines whether furnace operators pursue commodity scale or premium certification investments.
- Food and Beverage:Carbonated soft drinks, beer, wine, and spirits bottlers generate the highest volume offtake. Ethiopian brewers in Addis Ababa and Oromia industrial zones specify lightweighted flint glass with electrical boosting retrofits to meet sustainability procurement criteria.
- Pharmaceuticals:Injectable and oral dosage manufacturers require amber and flint glass with Ethiopian Standards Agency dimensional tolerance certification. Ministry of Health mandates for light-sensitive drug containment create non-substitutable demand.
- Cosmetics:Premium skincare and fragrance brands specify frosted and decorative finishes. This segment trails pharmaceutical and food volumes but commands higher per-unit margins.
- Household:Cleaning product and chemical storage containers compete with plastic alternatives on cost. PET substitution pressure is most acute here.
Food and beverage absorbs the bulk of installed capacity; pharmaceuticals is climbing the fastest on certification-driven premium pricing.
Form:
Application-specific protection requirements dictate colorant chemistry and annealing protocols across furnace lines.
- Transparent (Flint):Iron-free silica sand formulations enable premium beverage visibility branding. Brewery technical teams in Addis Ababa specify flint for clear beer and premium soft-drink presentation.
- Brown (Amber):Iron-sulfur-carbon colorant systems block UV transmission for beer and pharmaceutical protection. Ethiopian Standards Agency tightening of thermal shock resistance is forcing annealing lehr reconfigurations.
- Green:Chromium-iron colorants serve wine and certain beer segments. Niche demand concentrates in export-oriented wineries.
- Frosted:Acid-etched or mold-textured surfaces for cosmetic and premium beverage differentiation. Lower furnace throughput due to specialized finishing requirements.
Transparent glass absorbs the bulk of installed capacity; brown glass is gaining share fastest on pharmaceutical directive expansion.
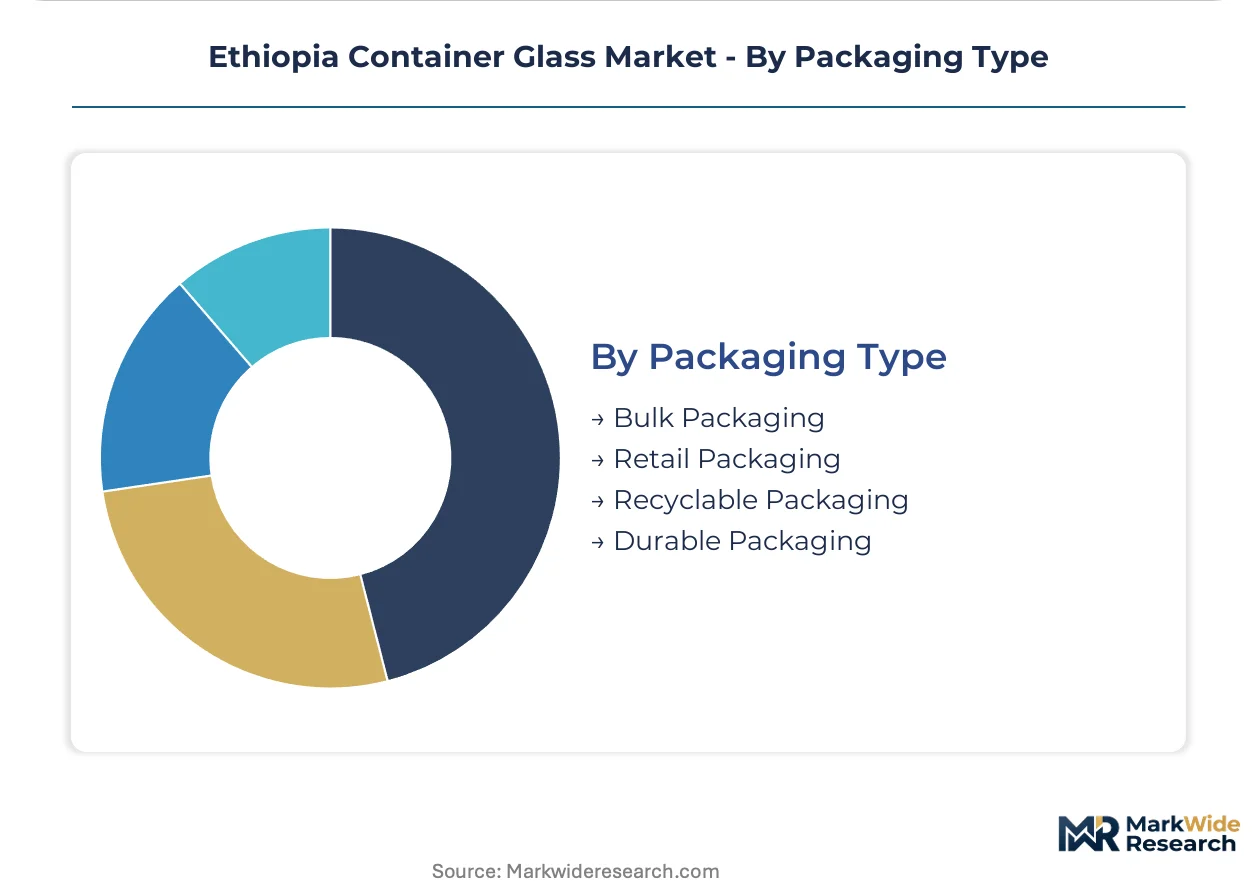
Packaging Type:
Customer type and volume scale determine whether procurement flows through distributor networks or direct furnace contracting.
- Bulk Packaging:High-volume palletized shipments for brewery and soft-drink bottler filling lines. Direct contracting with integrated producers is displacing distributor intermediation in Addis Ababa and Hawassa zones.
- Retail Packaging:Individual unit or small-case formats for pharmacy and specialty food channels. Ethiopian Standards Agency certification timelines compress product launch windows.
- Recyclable Packaging:Cullet-intensive batch formulations and post-consumer recovery integration. Addis Ababa municipal waste segregation pilots are improving furnace batch economics.
- Durable Packaging:Thicker-wall specifications for reusable bottle systems and returnable logistics. Limited penetration given single-use cost advantages.
Bulk packaging absorbs the bulk of installed capacity; recyclable packaging is expanding most quickly on cullet recovery infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Addis Ababa anchors Ethiopia's container glass production, with furnace operations clustering along the Oromia industrial corridor where Ethiopian Investment Commission incentives concentrate beverage bottler capacity expansion.
Addis Ababa
Brewery and soft-drink bottler procurement absorbs the bulk of flint and amber glass output from integrated furnace operations. Ethiopian Investment Commission local content mandates lock in domestic sourcing for industrial park tenants. Addis Ababa Bottle and Glass Share Company leverages captive silica sand access through finished bottle production to anchor supply security.
Oromia Industrial Corridor
Hawassa industrial zone bottlers drive demand for lightweighted glass with electrical boosting retrofits. Ethiopian Investment Commission tax holidays pull capacity expansion into this corridor. Furnace operators here face logistics cost premiums for regional city distribution outside the capital.
Amhara Region
Pharmaceutical packaging demand from domestic drug manufacturers creates certified amber glass offtake. Ministry of Health mandates for light-sensitive injectables enforce containment standards. Bahir Dar and Gondar pharmaceutical clusters consolidate supplier relationships around certified furnace operators.
Southern Nations, Nationalities, and Peoples' Region
Agro-processing expansion generates jar demand for spice and sauce exports to Middle Eastern diaspora markets. Ethiopian Standards Agency container specifications govern export packaging integrity. Hawassa and Sodo industrial zones concentrate processed food bottling capacity.
Tigray Region
Post-conflict reconstruction is gradually restoring beverage distribution networks. Ethiopian Customs Commission import duty differentials protect local furnace operations against dumped container imports. Mekelle's regional bottler base remains dependent on Addis Ababa supply given furnace concentration.
Ethiopia Container Glass Market Competitive Landscape
The competitive structure tilts toward vertically integrated furnace operators with captive raw material access. Three furnace operations cluster in Addis Ababa, creating geographic supply concentration. Strategic archetypes separate integrated silica sand-to-bottle producers, multi-format furnace specialists, and pharmaceutical-grade certification holders. Capacity expansion and direct contracting with brewery accounts displace distributor intermediation.
Among integrated producers, Addis Ababa Bottle and Glass Share Company anchors supply security through backward integration into silica sand mining. East African Glass occupies a position exemplifying furnace scale and multi-format flexibility. Juniper Glass Industries PLC represents the pharmaceutical-grade certification tier, specializing in borosilicate and soda-lime containers for injectable and oral dosage packaging.
| Leading Market Players |
|---|
| Addis Ababa Bottle and Glass Share Company |
| East African Glass |
| Juniper Glass Industries PLC |
| CONSOL Glass |
| Ethiopian Crown Cork and Can Manufacturing PLC |
| Daylight Applied Technologies |
| Addis Glass Manufacturing |
| Daylight Engineering |
| Roha Ventures |
| Others |
Pricing and Supply Chain Analysis
Skilled furnace operations talent scarcity in Addis Ababa and the Oromia industrial corridor widens pricing-tier spreads between certified pharmaceutical-grade output and commodity beverage bottles. Labor-cost differentials between expatriate technical staff and domestic batch chemists compress margins at smaller furnace operations while integrated producers capture premium positioning.
Pricing Analysis
Throughput-based furnace contracting anchors pricing for high-volume brewery accounts, with per-ton melting fees scaling to bottle output volumes. Ethiopian Standards Agency certification grade and captive silica sand access drive price differentiation between integrated and non-integrated suppliers. Pricing pressure stems from PET bottle imports capturing carbonated soft-drink share where UV protection requirements are minimal. Food and beverage bottlers exhibit highest price sensitivity; pharmaceutical manufacturers accept premium positioning for amber glass compliance.
Supply Chain Analysis
Soda ash supply rests on Egyptian and Turkish producers, exposing furnace operators to currency-driven input cost volatility. Silica sand draws from domestic mining concessions in the Oromia corridor, while limestone feeds from regional quarries. Single-source vulnerability concentrates in soda ash import channels given Ethiopia's lack of domestic production. Distribution runs through direct contracting with integrated producers for bulk brewery accounts, displacing distributor intermediation in Addis Ababa and Hawassa industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethiopia's container glass market represents a consolidation play as Ethiopian Investment Commission local content mandates and furnace scale economics force sub-scale operators toward exit or acquisition.
For Market Incumbents: Deploy captive silica sand mining rights to lock in supply security for brewery accounts facing procurement mandate pressure. Add electrical boosting retrofits to existing furnace lines to deflect energy cost compression while meeting sustainability procurement criteria from multinational beverage bottlers. Consolidate distributor relationships through direct contracting mechanisms in Addis Ababa and Hawassa zones. For New Entrants and Emerging Players: Ethiopian Standards Agency pharmaceutical packaging directives in Addis Ababa open a window for certified amber glass specialists targeting injectable drug manufacturers. Penetrate the processed food export jar segment serving Middle Eastern diaspora markets, where demand from spice and sauce exporters outpaces domestic beverage bottling saturation. Pursue WHO-prequalification pathways to access African Union pooled procurement programs. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade certification holders given Ministry of Health mandate expansion for light-sensitive drug containment. Long-term viability favors integrated producers with backward control over silica sand supply and furnace scale above minimum efficient thresholds. Watch Addis Ababa municipal waste segregation pilot outcomes as the signal for cullet recovery economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Mining | Addis Ababa Bottle and Glass Share Company anchors supply security through captive raw material access. |
| Electrical Boosting Retrofit Deployment | Furnace operators absorb incremental melting load to reduce carbon intensity per ton for brewery sustainability criteria. |
| Pharmaceutical-Grade Certification Investment | Juniper Glass Industries PLC secures amber glass demand from Ministry of Health injectable packaging mandates. |
| Direct Contracting with Industrial Park Tenants | Ethiopian Investment Commission local content requirements lock in domestic sourcing relationships. |
| Cullet Recovery Infrastructure Buildout | Addis Ababa municipal waste segregation pilots improve furnace batch economics through post-consumer glass recovery. |
Research Methodology
Independent corroboration across furnace operations managers, brewery procurement leads, pharmaceutical packaging specialists, and Ethiopian Investment Commission officials underwrites the qualitative findings. Primary interviews with batch chemists, annealing lehr technicians, and industrial park tenant supply chain directors combined with secondary validation from Ethiopian Standards Agency container specifications, Ethiopian Customs Commission trade data, and Ministry of Health pharmaceutical packaging directives. Bottom-up furnace capacity modeling and top-down beverage bottler offtake analysis triangulate volume estimates.
Rate-of-change decomposition across product type, end user, glass form, and packaging configuration dimensions structures the analytical framework over the projection horizon. CAGRs derive from segmented demand modeling and furnace throughput assumptions. Forecast inputs incorporate Ethiopian Investment Commission industrial park incentive uptake trajectories and soda ash import cost volatility scenarios.
Caveats apply where currency fluctuations against the Egyptian pound and Turkish lira could materially shift the outlook for soda ash input costs. Forecasts reflect assumptions around Ethiopian Standards Agency certification timeline stability and industrial park tenant expansion continuity. A small set of triggers—municipal waste segregation mandate rollout pace and pharmaceutical directive enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United States Glass Packaging Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
China Glass Container Packaging Market