
 Israel Container Glass Market | 2026-2036
Israel Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Container Glass Market Insights
Israel is fragmenting its container glass supply base as domestic converters expand furnace capacity near Haifa and Beer Sheva industrial zones. Phoenicia Glass Works leverages vertical integration from silica sourcing through finished bottle output to anchor the local market. Schott Israel specializes in pharmaceutical-grade borosilicate vials, competing on technical specifications rather than commodity volume. Frontak controls distribution channels for imported European glassware, sustaining margin through logistics efficiency rather than manufacturing scale.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at temperatures exceeding 1500°C, then formed by blow molding or press-and-blow processes into rigid, chemically inert vessels for liquid and solid storage. The beverage industry dominates volume consumption of amber and flint bottles, while pharmaceutical vials command premium pricing due to USP Type I compliance requirements. Blow molding technology leads unit throughput, though narrow neck press methods gain traction in lightweight wine bottle applications where material efficiency shapes cost structures.
The Israeli Ministry of Environmental Protection enforces packaging waste regulations that mandate minimum recycled content thresholds, while BIS-equivalent standards govern food-contact safety certification. The Standards Institution of Israel administers quality marks that determine market access for imported glass containers. Stakeholders must monitor how carbon border adjustments and energy price volatility reshape furnace economics before committing to capacity expansion decisions.
Market Dynamics
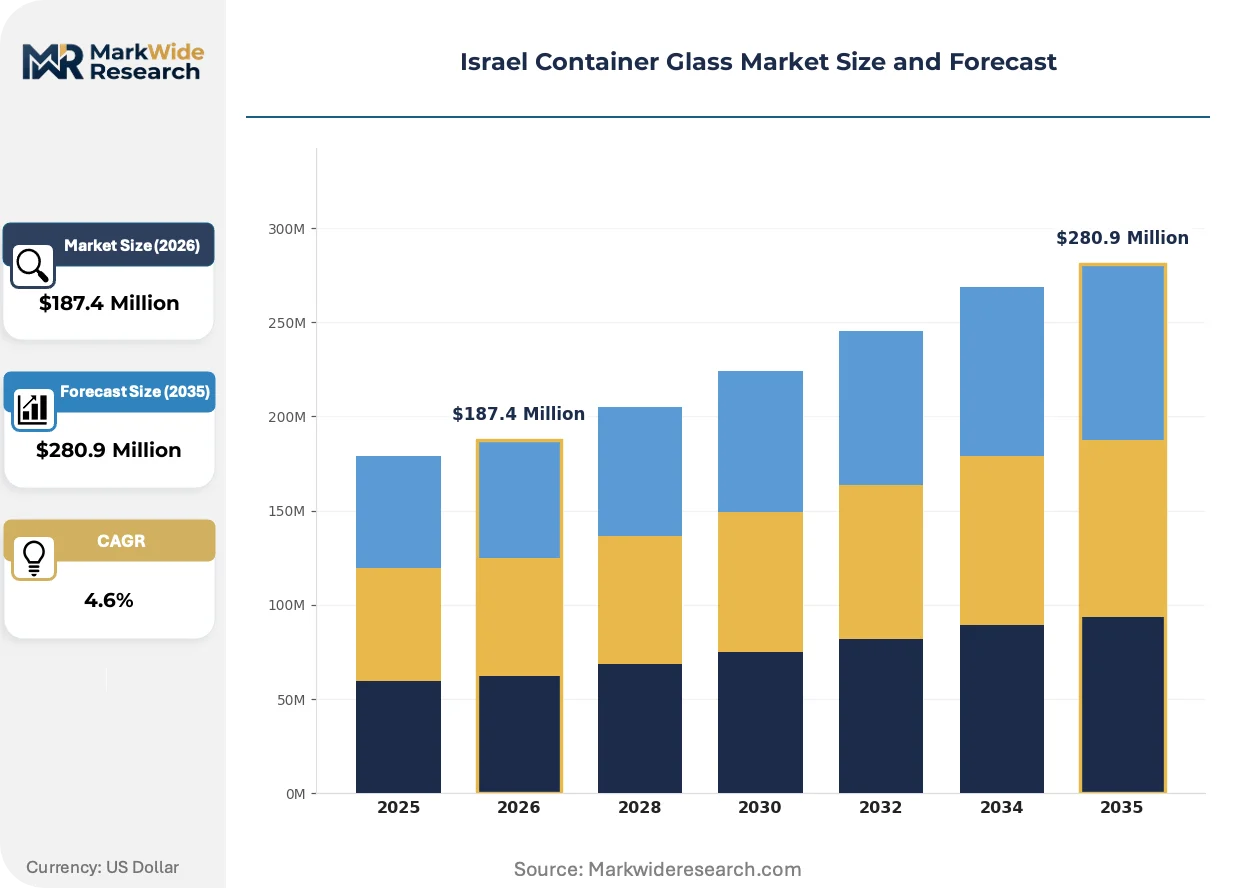
Israeli container glass producers face furnace economics compression as natural gas price volatility intersects with Ministry of Environmental Protection mandates for 30% post-consumer cullet content. This structural tension between energy-intensive melting requirements and circularity obligations defines competitive positioning across the Tel Aviv-Jerusalem corridor and emerging Haifa industrial zones.
Growth Catalysts
- Extended Producer Responsibility:The Israeli Ministry of Environmental Protection mandates minimum recycled content thresholds, compelling beverage brands to source domestic amber and flint bottles rather than imported alternatives.
- Food-tech clustering:Tel Aviv-Jerusalem corridor startups developing premium olive oils and functional beverages require pharmaceutical-grade glass packaging with USP Type I compliance.
- Natural gas infrastructure:Tamar and Leviathan field supply stability enables continuous furnace operations that intermittent renewable energy cannot yet support.
Market Restraints
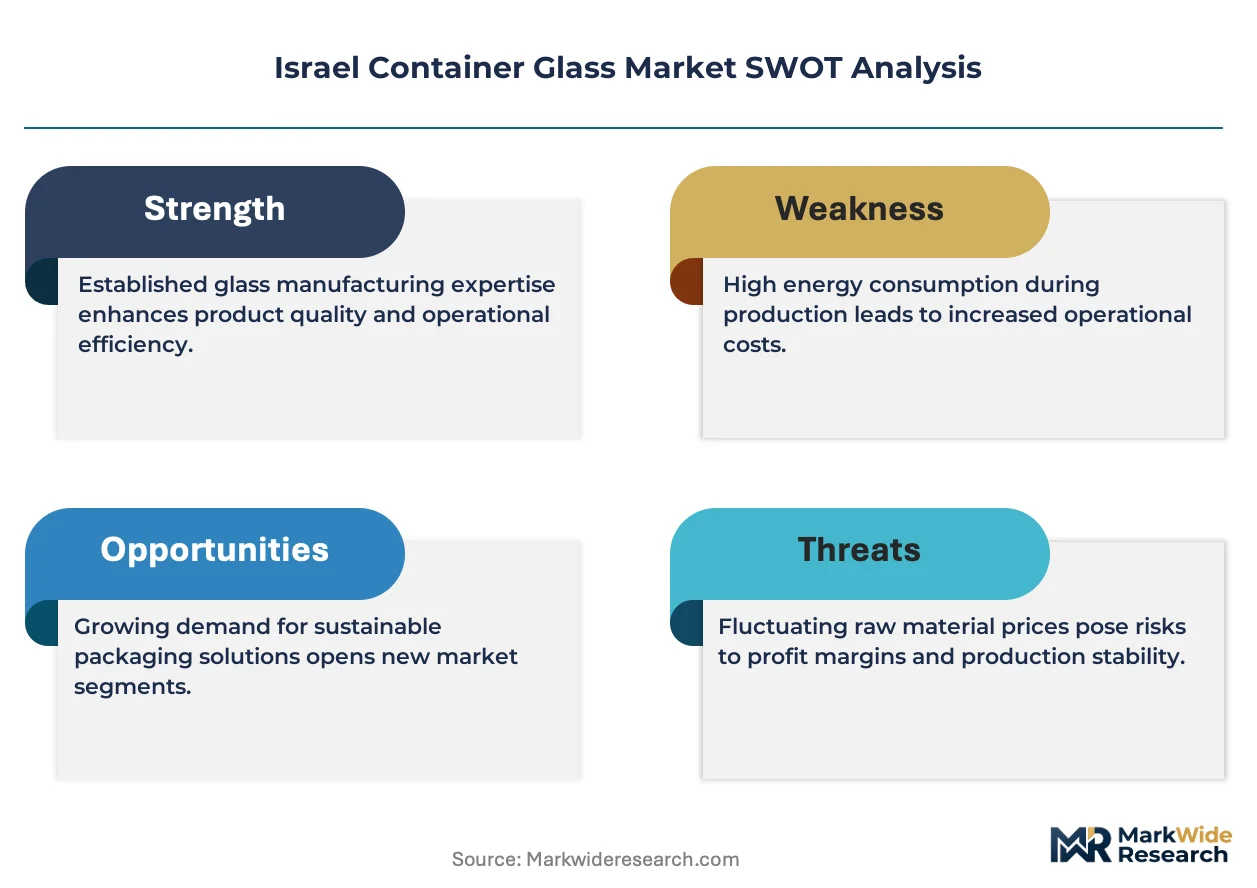
- Silica sand import dependency:High-purity silica sourcing concentrates through limited Mediterranean suppliers, exposing furnace operators to shipping cost volatility.
- Energy price exposure:Natural gas constitutes 35-40% of production costs; Israel Electric Corporation tariff fluctuations directly compress operating margins.
- Aluminum substitution:Aseptic carton and aluminum bottle formats capture share in mass-market dairy and juice segments where transparency carries less premium value.
Strategic Opportunities
- Beer Sheva industrial expansion:Negev desert tax incentives and land availability attract furnace capacity outside congested central Israel logistics corridors.
- Pharmaceutical vial specialization:Schott Israel's borosilicate expertise creates anchor demand for USP Type I compliance that commodity Asian imports cannot match.
- Dead Sea cosmetics packaging:Mineral extraction brands require amber glass with chemical inertness for high-salinity formulations, opening niche premium volumes.
Industry Challenges
- Furnace engineer scarcity:Israel lacks technical training programs for 1500°C continuous melting operations, forcing reliance on imported European specialists.
- Standards Institution certification delays:Food-contact safety mark approvals average 14-18 months, blocking new product launches for craft distillers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Container Glass Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Beverage Industry, Food Packaging, Personal Care, Pharmaceuticals Technology: Blow Molding, Press & Blow, Narrow Neck Press, Stretch Blow Molding Capacity: Small Capacity, Medium Capacity, Large Capacity, Extra-Large Capacity |
| Companies Covered | Phoenicia Glass Works, Feemio Group, Schott Israel, Frontak, Gil Plastic Products, AGI Glaspac, Hindusthan National Glass and Industries, Ardagh Group, Vidrala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Container Glass Market Trends and Innovations
Active furnace technology migration and regulatory stringency acceleration are compressing the viable competitive set. Israeli producers must simultaneously lightweight bottle designs, integrate higher cullet ratios, and certify for pharmaceutical-grade applications to defend position against European imports.
Electric boosting technology is migrating from auxiliary heating toward primary melting in Israeli container glass furnaces. Phoenicia Glass Works pilots hybrid gas-electric systems at its Haifa facility to reduce carbon intensity before anticipated carbon border adjustments. The technology is migrating from European demonstration projects into commercial-scale Israeli deployment as energy security concerns override pure cost optimization.
REACH-equivalent substance restrictions through the Israeli Ministry of Environmental Protection are tightening heavy metal thresholds in coloring agents. Cadmium and lead limitations in amber glass formulations force reformulation of traditional recipes. Pharmaceutical vial producers face the steepest compliance costs, passing certification expenses to biotechnology customers in Weizmann Institute corridor clusters.
Direct procurement relationships between craft spirit distilleries in the Golan Heights and furnace operators are displacing traditional distribution intermediaries. Frontak's logistics-centric model faces margin pressure as wineries and olive oil producers negotiate volume commitments for bespoke bottle shapes. This channel compression concentrates in premium segments where customization commands price premiums unavailable through standardized European imports.
Israel Container Glass Market Segmentation
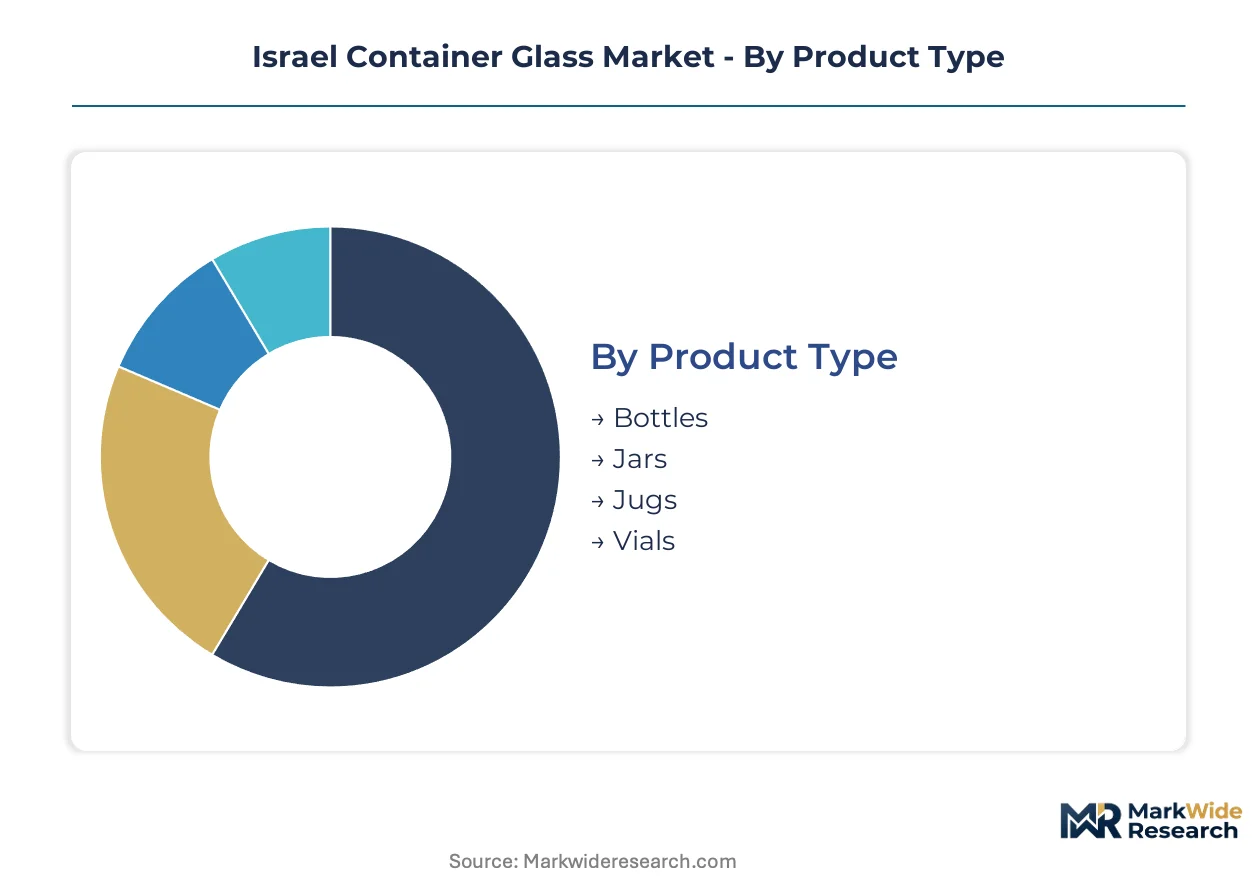
Container glass segmentation in Israel reflects furnace economics and regulatory mandates. Product type and end-user splits determine cullet ratios and compliance pathways. Technology and capacity choices anchor competitive positioning against European imports.
Product Type:
Mature formats dominate volume while specialized vessels command premium positioning in Tel Aviv-Jerusalem corridor demand clusters.
- Bottles:Amber and flint glass formulations serve beverage and pharmaceutical applications. Israeli Ministry of Environmental Protection cullet mandates concentrate procurement for amber bottles among domestic olive oil and craft spirit producers in the Golan Heights and Galilee regions.
- Vials:Borosilicate and soda-lime compositions meet USP Type I compliance for biotechnology clusters near Rehovot and Jerusalem. Schott Israel's technical specifications create import substitution barriers for pharmaceutical-grade demand.
- Jars:Wide-mouth configurations package Dead Sea cosmetics and mineral formulations requiring chemical inertness.
- Jugs:High-volume containers serve institutional food service and bulk olive oil distribution with lower per-unit margin profiles.
Bottles handle the majority of throughput; vials are climbing the fastest on share.
End User:
Cost tier stratification separates commodity volume from certification-driven premium procurement.
- Beverage Industry:Craft distilleries and premium olive oil producers in the Tel Aviv-Jerusalem corridor specify custom molds and lightweight designs. Direct furnace relationships displace distribution intermediaries for volume commitments above threshold quantities.
- Pharmaceuticals:Weizmann Institute corridor biotechnology firms require documented USP Type I compliance with heavy metal thresholds enforced through REACH-equivalent Ministry of Environmental Protection rules.
- Food Packaging:Standards Institution of Israel certification delays average 14-18 months for new container launches, blocking rapid product cycles for artisan producers.
- Personal Care:Dead Sea mineral brands source amber glass for high-salinity formulation stability, opening niche premium volumes outside commodity pricing pressure.
Beverage Industry commands volume leadership; Pharmaceuticals shows the steepest expansion trajectory.
Technology:
Application requirements dictate process selection across weight reduction and dimensional precision trade-offs.
- Blow Molding:Dominates unit throughput for standardized bottle geometries. Phoenicia Glass Works deploys hybrid gas-electric systems at Haifa to reduce carbon intensity before anticipated border adjustments.
- Narrow Neck Press:Gains traction in lightweight wine bottle applications where material efficiency shapes cost structures for export-oriented wineries.
- Press & Blow:Balances speed and precision for mid-range food jars with moderate neck finish complexity.
- Stretch Blow Molding:Limited penetration in Israel due to equipment import costs and furnace engineer scarcity forcing reliance on European specialists.
Blow Molding maintains installed base dominance; Narrow Neck Press is gaining share fastest through lightweighting mandates.
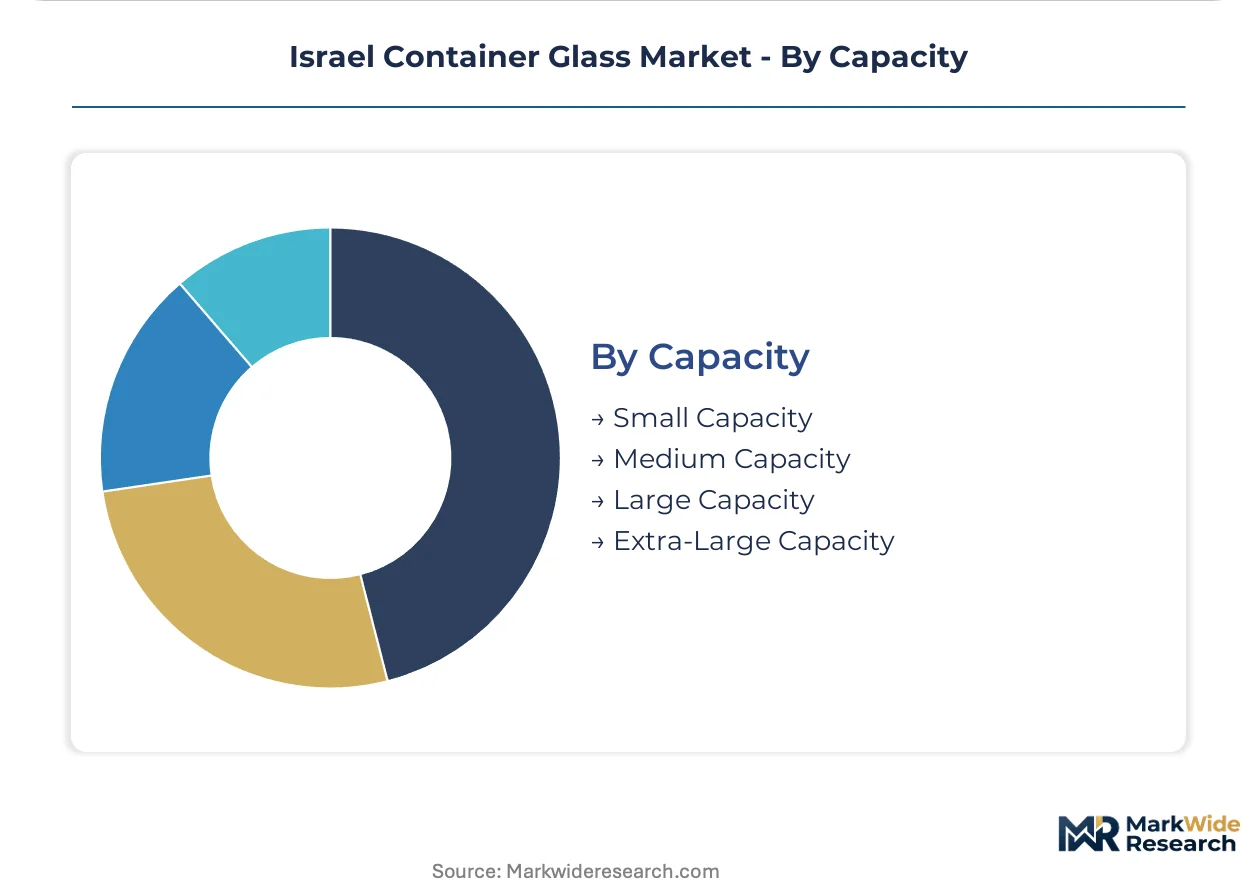
Capacity:
Customer type segmentation aligns procurement scale with logistics configuration and customization depth.
- Small Capacity:Pharmaceutical vials and sample-size cosmetics packaging command per-unit premiums through USP Type I and chemical inertness specifications.
- Medium Capacity:Standard wine and spirits bottles balance mold flexibility with furnace batch efficiency for craft producers negotiating direct procurement.
- Large Capacity:Institutional food service and bulk olive oil distribution prioritize logistics efficiency over dimensional precision.
- Extra-Large Capacity:Limited domestic demand concentrates in industrial chemical containment with specialized handling requirements.
Medium Capacity handles the majority of furnace output; Small Capacity is expanding most quickly on pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli furnace operators concentrate capacity along the coastal plain and southern industrial zones, with natural gas pipeline proximity dictating site selection. The Tel Aviv-Jerusalem corridor generates the majority of domestic demand, while emerging clusters near Haifa and Beer Sheva reshape logistics configurations.
Central District
The Tel Aviv-Jerusalem corridor anchors pharmaceutical vial demand from Weizmann Institute biotechnology clusters. The Israeli Ministry of Environmental Protection enforces extended producer responsibility rules that elevate recycled-content mandates for packaging sourced here. Food-tech startups in Rehovot and Jerusalem specify USP Type I compliant glass for functional beverage launches.
Haifa District
Phoenicia Glass Works operates integrated furnace capacity leveraging nearby port infrastructure for silica sand imports. The Standards Institution of Israel administers quality certification from its central offices, creating regulatory proximity for manufacturers. Hybrid gas-electric melting trials proceed at industrial sites seeking carbon intensity reductions before anticipated border adjustments.
Southern District
Beer Sheva industrial zones attract furnace investment through Negev desert tax incentives and land availability. The Israel Electric Corporation supplies tariff-regulated natural gas to continuous melting operations that renewable intermittency cannot yet support. Dead Sea cosmetics brands source amber glass packaging for high-salinity mineral formulations.
Northern District
Golan Heights craft distilleries negotiate direct procurement relationships with furnace operators for bespoke bottle shapes. The Ministry of Environmental Protection cullet mandates concentrate procurement for amber bottles among domestic olive oil producers in Galilee regions. Lightweight wine bottle applications gain traction among export-oriented wineries.
Israel Container Glass Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Israeli container glass market structures around three participant tiers: domestic furnace operators with captive silica sourcing, pharmaceutical-grade specialists competing on technical specifications, and logistics-centric distributors of imported European volumes. Competitive moves concentrate on hybrid furnace technology deployment and direct procurement channel compression.
Among domestic integrated producers, Phoenicia Glass Works exemplifies vertical control from raw material through finished output. Schott Israel occupies a position within the pharmaceutical-grade tier, representing technical specification competition rather than commodity volume play. Frontak sits within the distribution-focused segment, anchoring margin through logistics efficiency rather than manufacturing scale. These three archetypes illustrate how furnace economics, regulatory compliance, and channel configuration segment viable competitive positions.
| Leading Market Players |
|---|
| Phoenicia Glass Works |
| Feemio Group |
| Schott Israel |
| Frontak |
| Gil Plastic Products |
| AGI Glaspac |
| Hindusthan National Glass and Industries |
| Ardagh Group |
| Vidrala |
| Others |
Pricing and Supply Chain Analysis
Haifa industrial zone furnace capacity anchors Israeli container glass pricing power through captive silica sourcing and hybrid gas-electric melting trials. The Ministry of Environmental Protection's extended producer responsibility rules concentrate procurement among domestic producers, compressing margins on imported European alternatives that face carbon border exposure.
Pricing Analysis
The Israeli Ministry of Environmental Protection mandates dictate the pricing tier structure across pharmaceutical, beverage, and food packaging segments. Three-tier pricing stratifies across USP Type I certified vials, custom-molded craft spirit bottles, and commodity amber containers for mass-market olive oil. Price differentiation hinges on certification grade and volume scale, with pharmaceutical buyers showing least sensitivity while institutional food service procurement faces acute pressure from aluminum substitution. Cost compression in standard flint bottles is intensifying because natural gas tariff fluctuations directly transmit to furnace operating economics.
Supply Chain Analysis
High-purity silica sand feeds from Mediterranean suppliers in Egypt, Turkey, and Greece, exposing furnace operators to shipping cost volatility at Haifa port. Soda ash and limestone draw from regional chemical producers, while cullet supply hinges on domestic collection infrastructure under Ministry mandates. Single-source vulnerability concentrates in pharmaceutical-grade borosilicate expertise where Schott Israel maintains technical specification barriers. Distribution runs through direct procurement relationships displacing traditional intermediaries for premium segments, with Frontak's logistics model defending commodity import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israeli container glass fragmentation creates entry niches as food-tech clustering in the Tel Aviv-Jerusalem corridor multiplies specialized packaging demands beyond commodity furnace capacity.
For Market Incumbents: Harden furnace economics through hybrid gas-electric melting deployment at Haifa and Beer Sheva sites before anticipated carbon border adjustments compress import parity. Deepen backward integration into Dead Sea mineral extraction partnerships for amber glass niche volumes. Channel control over Golan Heights craft distillery direct procurement relationships defends margin against Frontak's logistics-centric model. For New Entrants and Emerging Players: Build out pharmaceutical vial specialization targeting Weizmann Institute corridor biotechnology clusters where USP Type I compliance creates import substitution barriers. The most penetrable white space sits in lightweight wine bottle narrow neck press capacity for export-oriented Galilee wineries. A go-to-market angle through Dead Sea cosmetics packaging partnerships leverages chemical inertness specifications unavailable from Asian commodity imports. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid furnace operators with regulatory pre-certification for carbon intensity thresholds. Long-term viability centers on electricity-forward melting architecture as renewable intermittency resolves. Acquisition targets should show captive cullet collection infrastructure and pharmaceutical-grade certification pipelines. The signal to watch is Israel Electric Corporation tariff restructuring announcements affecting continuous furnace cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Furnace Technology Deployment | Phoenicia Glass Works pilots gas-electric systems at Haifa to preempt carbon border adjustment exposure. |
| Pharmaceutical Vial Certification Investment | Schott Israel's USP Type I compliance anchors biotechnology demand from Weizmann Institute clusters. |
| Direct Procurement Channel Compression | Golan Heights distilleries negotiate bespoke molds, displacing Frontak's distribution intermediaries. |
| Dead Sea Cosmetics Packaging Partnership | Amber glass chemical inertness captures mineral formulation stability premiums outside commodity pricing. |
| Beer Sheva Industrial Zone Capacity Expansion | Negev desert tax incentives attract furnace investment outside congested central Israel logistics corridors. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, beverage procurement leads at olive oil cooperatives, pharmaceutical packaging engineers at biotechnology firms, and Standards Institution of Israel certification officers, then refined against secondary validation from customs trade records, Ministry of Environmental Protection regulatory filings, Israel Electric Corporation tariff disclosures, and container glass industry association data. Bottom-up volume modeling from individual furnace capacity and top-down demand aggregation from end-use sector consumption patterns were cross-triangulated.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, technology process, and capacity tier alongside geographic production cluster proximity to natural gas pipeline infrastructure. CAGRs were derived from trend extrapolation of furnace throughput, cullet integration rates, and end-use demand elasticity. Industry-specific forecast inputs incorporated Ministry of Environmental Protection mandate compliance timelines and carbon border adjustment implementation probability.
Sensitivities concentrate around natural gas tariff volatility, furnace engineer import dependency, and Standards Institution certification approval delays. Forecasts reflect documented assumptions regarding hybrid technology adoption curves and pharmaceutical-grade demand trajectories. Cross-checking against European container glass trade flow data and regional energy price benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Spain Packaging Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Asia Pacific Glass Packaging Market