
 Morocco Container Glass Market | 2026-2036
Morocco Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Container Glass Market Insights
Aftermarket refurbishment services for industrial molds and furnace linings is reshaping margin distribution across the value chain. Verallia SA leverages its European technical base to sustain furnace efficiency programs at Moroccan plants. Sotuver anchors domestic supply through its long-standing presence in wine and spirits bottling. Glass Plast Maroc competes by specializing in custom jar formats for the cosmetics export sector.
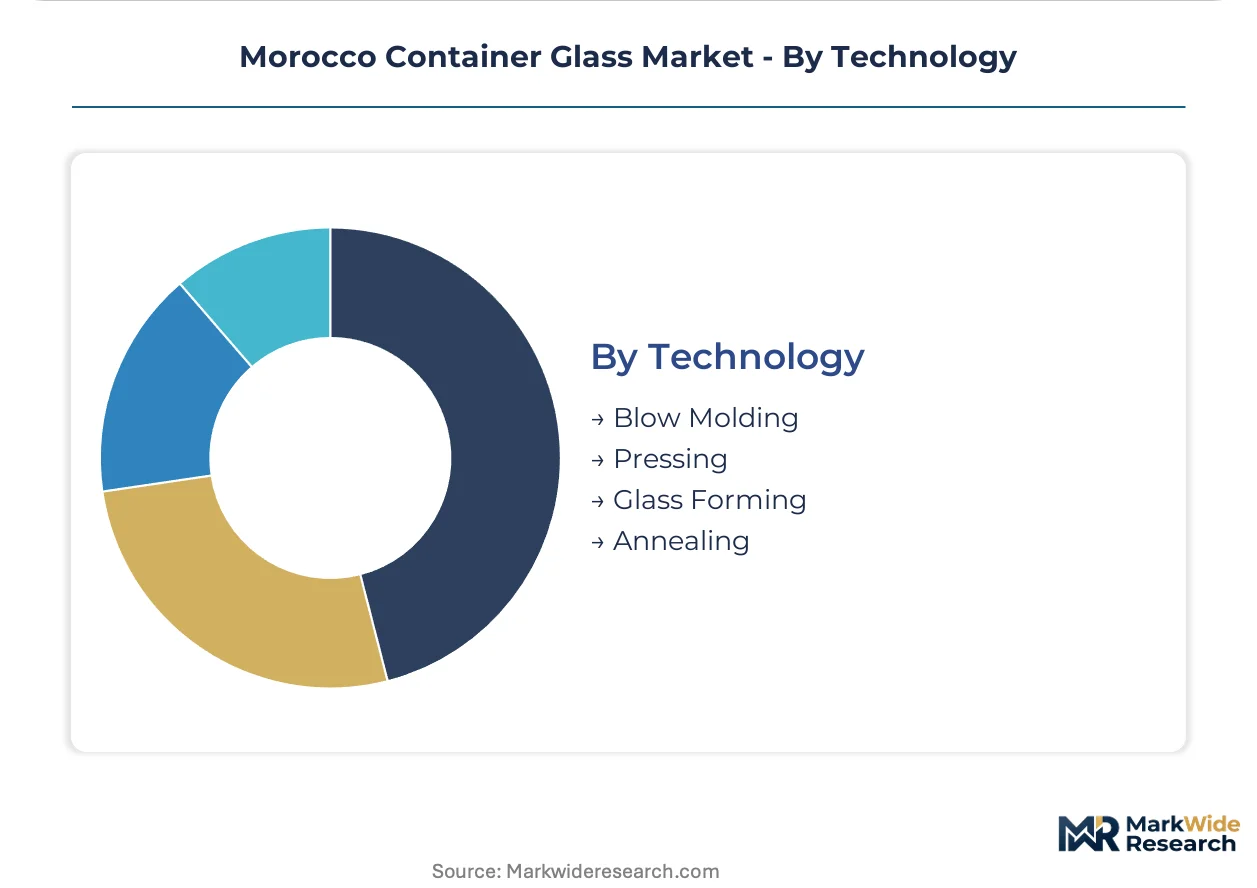
Morocco container glass comprises silica-sand-based hollowware formed at temperatures exceeding 1,500°C, then annealed to relieve thermal stress for mechanical durability in filling-line handling. The primary purpose is to provide chemically inert, impermeable packaging for consumable and pharmaceutical products requiring shelf stability and brand differentiation. Bottles dominate the product type dimension as beverage export volumes expand, while pharmaceutical vials claim the fastest structural growth due to rising local drug manufacturing. Blow molding leads the technology split for thin-walled beverage containers, though pressing retains margin concentration in thick-walled cosmetic jars where surface finish precision commands premium positioning.
Morocco's Ministry of Industry and Trade enforces conformity assessment protocols aligned with CE marking prerequisites for export-bound packaging, while the national standards body administers food-contact safety certifications that gate domestic market access. These frameworks elevate quality compliance costs but simultaneously filter out informal competitors, tightening supply concentration among certified producers. Stakeholders must monitor whether upcoming energy subsidy reforms alter natural gas pricing for furnace operations, as fuel costs dictate plant location decisions across the Moroccan industrial belt.
Market Dynamics
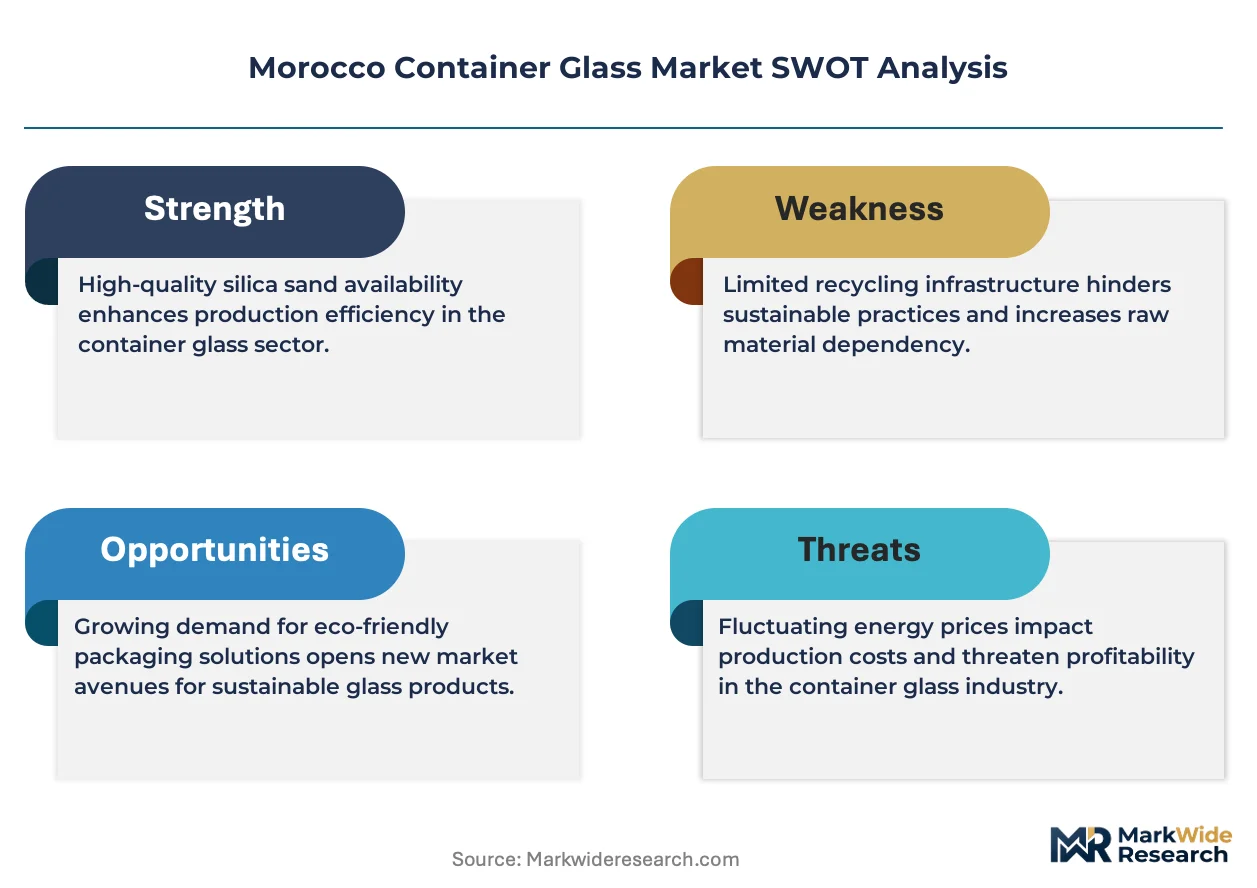
Natural gas pricing volatility and furnace efficiency mandates are compressing operating margins across Moroccan container glass production, forcing consolidation around the Casablanca-Settat corridor where infrastructure density offsets energy cost exposure.
Growth Catalysts
- Export-oriented beverage bottling:Premium spirits and olive oil producers in Rabat and Casablanca are abandoning plastic packaging to meet EU import standards and capture shelf differentiation in European retail channels.
- CE marking alignment:Morocco's conformity assessment protocols now mirror European prerequisites, enabling seamless cross-border shipment of packaged goods and eliminating redundant certification costs for exporters.
- Pharmaceutical vial demand:Local drug manufacturing expansion is accelerating orders for borosilicate glass containers capable of withstanding autoclave sterilization and cold-chain distribution.
Market Restraints
- Natural gas cost exposure:Furnace operations depend on subsidized natural gas, and pending energy subsidy reforms threaten to raise input costs by double-digit percentages for continuous-melt producers.
- Silica sand import dependence:High-purity silica reserves are concentrated in specific coastal deposits, creating geographic supply risk if extraction permits face environmental review delays.
- Aluminum can substitution:Beverage multinationals are piloting lightweight aluminum formats for carbonated soft drinks, pressuring glass volume in the mass-market tier.
Strategic Opportunities
- Cosmetics export packaging:Custom jar formats for skincare and fragrance brands targeting Middle Eastern duty-free channels remain underpenetrated relative to European competitors.
- Aftermarket furnace services:Refractory lining refurbishment and mold maintenance contracts offer recurring revenue streams detached from volatile container pricing cycles.
- BIS-aligned certification:Stricter food-contact material standards are filtering informal competitors, creating volume capture potential for certified domestic producers.
Industry Challenges
- Specialized furnace engineering talent:Glass technologists capable of optimizing combustion efficiency and defect reduction are scarce in the Moroccan labor market, requiring expensive expatriate recruitment.
- Annealing lehr capex cycles:Modernizing thermal stress relief equipment to handle thinner-walled lightweight bottles demands capital commitments that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Container Glass Market |
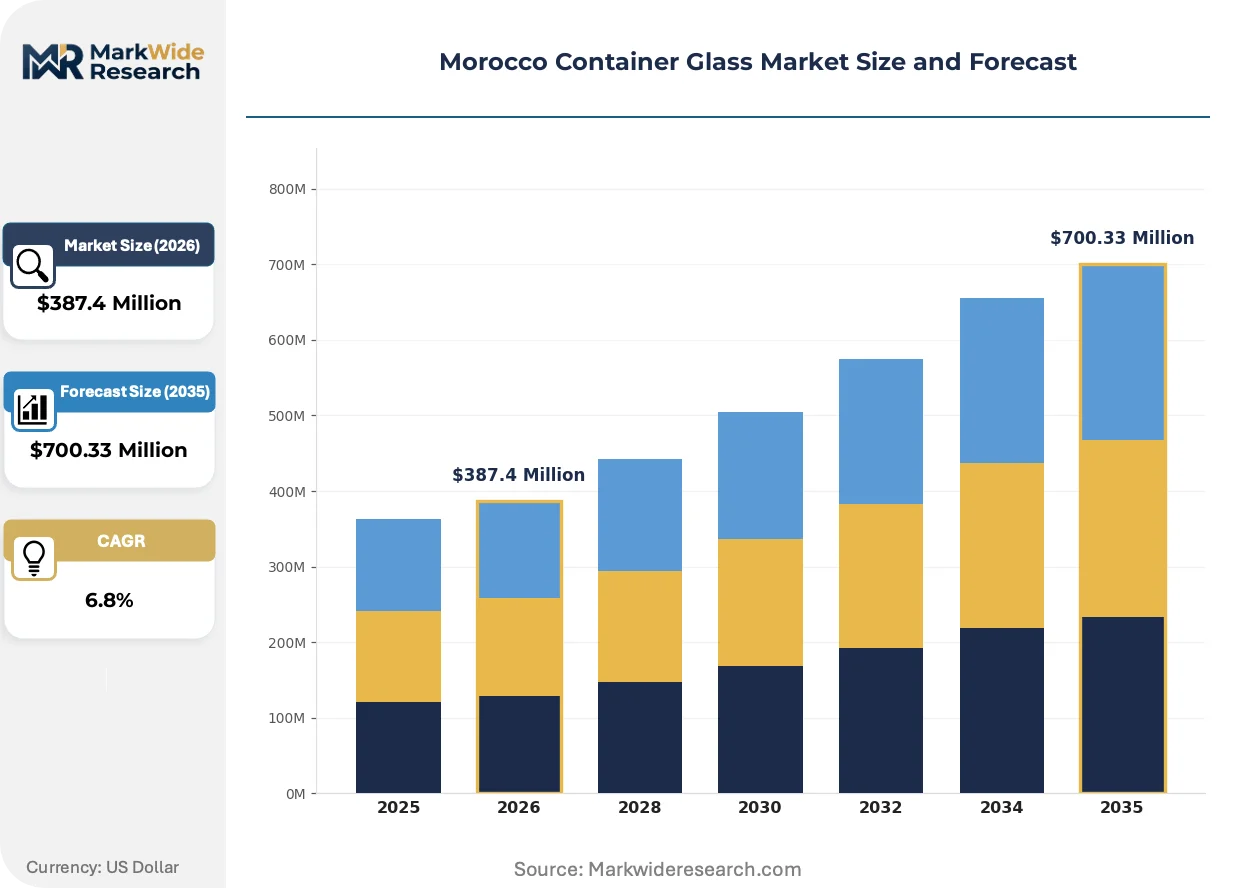
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Canisters Usage/Application: Food, Beverages, Pharmaceuticals, Cosmetics End User: Manufacturers, Retailers, Wholesalers, Distributors Technology: Blow Molding, Pressing, Glass Forming, Annealing |
| Companies Covered | Verallia SA, Glass Plast Maroc, Sotuver, Vetropack, Saverglass SAS, SEVAM, Ardagh Group S.A, MBALAJY, Feemio Group Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Container Glass Market Trends and Innovations
Electrification of melting processes and digital quality control systems are reconfiguring production economics, while regulatory alignment with European frameworks accelerates technology transfer from Mediterranean suppliers.
Oxy-fuel combustion technology is replacing traditional air-gas furnace firing in Moroccan plants, cutting nitrogen oxide emissions and improving thermal efficiency by concentrating flame temperature directly on the glass batch. Beverage exporters in Casablanca are prioritizing suppliers with oxy-fuel retrofits to preempt EU carbon border adjustments. This transition is rendering obsolete older regenerative furnace designs that cannot meet tightening emission ceilings without prohibitive scrubber investments.
BIS-aligned food-contact certification rules now govern all domestic-market glass packaging, extending testing protocols for heavy metal migration and thermal shock resistance previously limited to export shipments. The national standards body administers these assessments through accredited laboratories in Rabat and Casablanca. Pharmaceutical packaging plants face the steepest compliance burden, as vial and ampoule formats require additional sterility validation and documentation trails.
Brand owners are consolidating supplier relationships around vertically integrated partners capable of delivering decorated, labeled, and palletized finished goods rather than undecorated containers. This pattern compresses the traditional mold-maker-to-filler value chain into single-source accountability structures. Olive oil exporters in the Fes-Meknes region have been earliest adopters, demanding turnkey packaging services that eliminate intermediate handling and contamination risk.
Morocco Container Glass Market Segmentation
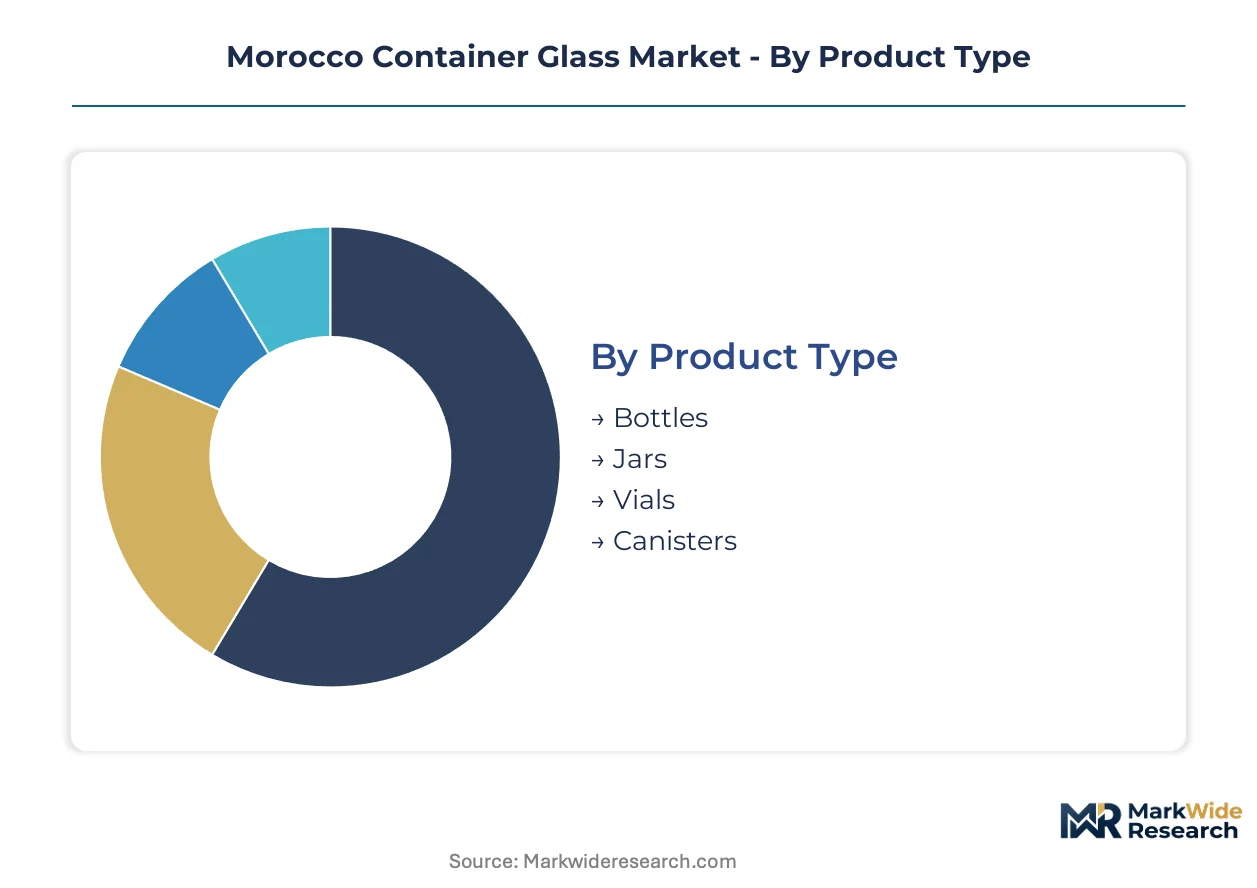
Container glass producers in Casablanca and Rabat segment output to match distinct thermal, chemical, and mechanical requirements across export-oriented bottling lines. Each dimension carries different inventory velocity, capital intensity, and regulatory compliance burdens that determine margin capture.
Product Type:
Bottles turn inventory fastest through beverage filling lines, while canisters and specialized vials sit in production queues longer due to custom mold lead times and annealing protocols.
- Bottles:Thin-walled hollowware formed via blow molding for carbonated and still beverages, with lightweighting programs reducing wall thickness to cut transport costs for olive oil and spirits exporters shipping through Casablanca port.
- Jars:Wide-mouth containers with thicker walls and precision-thread finishes, concentrating demand among cosmetics brands targeting Middle Eastern duty-free channels where surface aesthetics command premium positioning.
- Vials:Borosilicate glass ampoules and injection vials requiring autoclave sterilization tolerance, serving pharmaceutical manufacturers in the Casablanca-Settat corridor.
- Canisters:Large-format storage containers for bulk food ingredients, produced in lower volumes with extended production cycles due to specialized annealing requirements.
Bottles dominate installed base. Vials are where expansion concentrates.
Usage/Application:
Margin structure varies sharply across applications, with pharmaceutical and cosmetics packaging capturing price premiums that offset slower batch turnover compared to high-velocity beverage runs.
- Beverages:Premium spirits and olive oil bottlers in Rabat drive volume, abandoning plastic to meet EU import standards and capture shelf differentiation in European retail channels.
- Pharmaceuticals:Sterile vial and ampoule demand accelerates with local drug manufacturing expansion, requiring borosilicate glass capable of withstanding autoclave sterilization and cold-chain distribution.
- Food:Standard jars and bottles for domestic condiment and preserve markets, facing price pressure from aluminum and flexible packaging alternatives.
- Cosmetics:Custom jar formats for skincare and fragrance brands, underpenetrated relative to European competitors but growing through export-oriented production.
Beverages anchor volume throughput. Pharmaceuticals are climbing the fastest.
End User:
Procurement patterns diverge between integrated manufacturers running captive filling lines and intermediaries aggregating demand across fragmented retail networks.
- Manufacturers:Beverage and pharmaceutical producers with dedicated filling equipment, demanding turnkey decorated and palletized finished goods rather than undecorated containers.
- Retailers:Supermarket chains and specialty food stores in Casablanca and Rabat, sourcing standardized jar formats with shorter lead times and lower minimum order quantities.
- Wholesalers:Regional distributors aggregating demand from smaller olive oil producers in Fes-Meknes, placing intermittent bulk orders with limited decoration requirements.
- Distributors:Export logistics providers managing cross-border shipment compliance, prioritizing suppliers with CE marking alignment and BIS-certified food-contact documentation.
Manufacturers command capacity allocation. Distributors are gaining share fastest through export channel consolidation.
Technology:
Capital deployment and operating cost structures vary dramatically across melting and forming methods, with oxy-fuel retrofits reshaping competitive positioning among furnace operators.
- Blow Molding:Compressed air expansion of molten glass parisons into thin-walled beverage containers, enabling high-speed production lines that serve carbonated soft drink and spirits bottlers.
- Pressing:Mechanical plunger forming for thick-walled cosmetic jars where surface finish precision and thread integrity command premium pricing from skincare brands.
- Glass Forming:Combined blow-and-blow or press-and-blow techniques for intermediate complexity shapes, balancing throughput with dimensional tolerance requirements.
- Annealing:Controlled cooling through lehr tunnels to relieve thermal stress, with modernizing equipment demands straining mid-tier producers seeking to handle thinner-walled lightweight bottles.
Blow molding dominates installed furnace capacity. Annealing technology upgrades are where capital deployment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Moroccan container glass demand centers. Beverage exporters in Casablanca absorb premium pricing for certified packaging, while domestic food processors in secondary cities remain highly sensitive to input cost fluctuations.
Casablanca-Settat
Premium spirits bottlers and olive oil exporters cluster along the Atlantic corridor, driving demand for lightweight bottles with CE-marked certification. The Ministry of Industry and Trade operates conformity assessment laboratories here, streamlining export documentation. Verallia SA maintains furnace operations in this zone, leveraging port access for European shipment.
Rabat-Salé-Kénitra
Pharmaceutical packaging plants concentrate in the administrative capital, sourcing borosilicate vials for autoclave-sterilized drug products. The national standards body administers BIS-aligned food-contact certifications through accredited facilities in Rabat. Local drug manufacturers are expanding cold-chain distribution capacity, accelerating sterile container orders.
Fes-Meknes
Olive oil producers in this northern agricultural belt are consolidating supplier relationships around turnkey packaging services. Stricter food-contact material standards under updated certification rules are filtering informal competitors. Regional bottlers now demand decorated, labeled, and palletized finished goods rather than undecorated containers.
Tangier-Tetouan-Al Hoceima
Cosmetics exporters targeting Middle Eastern duty-free channels are emerging as a specialized demand pocket. The northern port infrastructure supports fragrance and skincare brands requiring custom jar formats with premium surface finishes. Glass Plast Maroc competes in this segment through specialization in decorative hollowware.
Marrakesh-Safi
Domestic beverage and condiment markets in this central region face persistent price pressure from aluminum and flexible packaging alternatives. Energy subsidy reforms threaten to raise natural gas costs for furnace-dependent suppliers serving this price-sensitive tier. Mid-tier producers here lack capital for oxy-fuel retrofit investments.
Morocco Container Glass Market Competitive Landscape
Capability concentration sits with multinational furnace operators; scale advantage sits with domestic incumbents rooted in long-standing bottler relationships. The market structures around three tiers: European-headquartered technical specialists, Morocco-anchored volume producers, and regional niche players serving cosmetics export channels. Consolidation pressure is mounting as natural gas pricing volatility compresses margins among undifferentiated producers. Strategic moves center on furnace efficiency partnerships and backward integration into silica sand sourcing.
Among European-headquartered specialists, Verallia SA and Saverglass SAS exemplify the technical-capability tier, leveraging continental engineering resources to sustain furnace efficiency programs. Sotuver anchors domestic supply through established relationships with wine and spirits bottlers. Glass Plast Maroc occupies a position within the specialization tier, competing through custom formats rather than scale.
| Leading Market Players |
|---|
| Verallia SA |
| Glass Plast Maroc |
| Sotuver |
| Vetropack |
| Saverglass SAS |
| SEVAM |
| Ardagh Group S.A |
| MBALAJY |
| Feemio Group Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Casablanca-Settat furnace concentration grants certified producers pricing leverage over exporters seeking CE-marked packaging for EU-bound spirits and olive oil shipments. Natural gas subsidy exposure and silica sand import dependence create cost volatility that compresses margins among undifferentiated competitors outside this corridor.
Pricing Analysis
Aftermarket furnace services and mold maintenance contracts generate recurring revenue streams detached from volatile container spot pricing. Pricing stratifies across premium certified tiers, standard domestic grades, and economy undecorated formats based on BIS-aligned food-contact certification status and decoration complexity. Cost compression in the mass-market beverage tier is intensifying because aluminum can substitution pilots threaten glass volume. Domestic food processors in secondary cities exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for autoclave-sterilized borosilicate vials.
Supply Chain Analysis
EU carbon border adjustment mechanisms and CE marking alignment requirements restrict technology flows to oxy-fuel retrofitted furnace operators. High-purity silica sand draws from coastal Moroccan deposits, European refractory engineering, and Egyptian soda ash feedstocks. Single-source vulnerability concentrates in natural gas supply contracts tied to pending subsidy reforms. Distribution runs through port-integrated logistics providers managing Casablanca-Rabat export documentation and cold-chain pharmaceutical handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's container glass sector sits at a platform-economics inflection where turnkey packaging services—combining decoration, labeling, and palletization—are displacing traditional mold-maker-to-filler value chains. Interoperability between CE marking protocols and BIS-aligned domestic certification is collapsing redundant compliance layers for exporters.
For Market Incumbents: Insulate margin position through captive silica sand sourcing agreements and oxy-fuel furnace efficiency partnerships that preempt EU carbon border adjustments. Aluminum can substitution in carbonated beverages demands defensive certification investments to lock pharmaceutical and premium spirits accounts. Backward integration into coastal sand extraction permits filters supply risk from environmental review delays. For New Entrants and Emerging Players: Establish a beachhead in cosmetics export packaging for Middle Eastern duty-free channels, where custom jar formats remain underpenetrated relative to European competitors. Pharmaceutical vial demand accelerates fastest but requires sterile validation infrastructure; cosmetics offers lower barrier entry with premium surface finish differentiation. Target turnkey service bundling to capture olive oil exporters consolidating supplier relationships in Fes-Meknes. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage consolidation play because BIS-aligned certification filters informal competitors and concentrates volume among certified producers. Acquisition targets should display oxy-fuel retrofit completion and established CE marking documentation capabilities. Watch natural gas subsidy reform timing as the inflection signal that reshapes plant location economics across the Moroccan industrial belt.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Verallia SA leverages European engineering to cut nitrogen oxide emissions and preempt EU carbon border adjustments. |
| Backward Integration into Silica Sand | Sotuver secures coastal extraction permits to reduce geographic supply risk from environmental review delays. |
| Turnkey Packaging Service Launch | Glass Plast Maroc bundles decoration and palletization to capture cosmetics exporters consolidating supplier relationships. |
| BIS-Aligned Certification Investment | Certified producers capture volume from informal competitors filtered by stricter food-contact material standards. |
| Aftermarket Furnace Services Expansion | Refractory lining refurbishment contracts generate recurring revenue detached from volatile container pricing cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with furnace operations managers, pharmaceutical packaging plant engineers, olive oil exporter procurement leads, and cosmetics brand supply chain directors. Secondary validation drew from Moroccan Ministry of Industry conformity assessment protocols, CE marking documentation databases, BIS-aligned food-contact certification records, and natural gas pricing regulatory filings. Bottom-up volume triangulation across product types and applications was cross-checked against top-down industrial production capacity estimates.
Calibration anchored installed furnace capacity, export shipment volumes through Casablanca port, and pharmaceutical manufacturing expansion trajectories across the analysis window. Segmentation dimensions modeled include product type, application, end-user procurement pattern, and forming technology. CAGRs were derived from slope analysis of capacity utilization trends and export certification velocity. Oxy-fuel adoption rates and BIS certification penetration served as industry-specific forecast inputs.
Stress conditions across natural gas subsidy reform scenarios, silica sand extraction permit delays, and aluminum substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about furnace efficiency improvement trajectories and export demand elasticity. Material shifts in EU carbon border adjustment implementation timelines or Moroccan energy pricing reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Container Glass in the UAE Market