
 India Glass Packaging Market | 2026-2036
India Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Glass Packaging Market Foresight
Plastic Waste Management Rules is consolidating compliance costs for converters while elevating glass as the preferred substitute in regulated categories. Haldyn Glass Limited leverages captive silica sand mining and furnace scale to dominate western India supply. SGD Pharma India Limited specializes in Type I borosilicate vials for injectable pharmaceuticals, sustaining premium positioning through pharmacopeia-grade certification. AGI Greenpac Limited anchors the domestic beverage segment with lightweight bottle lines that compete on unit economics against imports.
India Glass Packaging encompasses soda-lime, borosilicate, and treated glass vessels manufactured through blow-and-blow or press-and-blow forming, with wall thickness and thermal shock resistance calibrated to contents ranging from carbonated beverages to lyophilized drugs. Bottles command the largest volume share in beverage packaging, though medical packaging for pharmaceuticals records the fastest value growth as biologics proliferation drives demand for barrier-coated and amber glass. Jars and containers in food packaging occupy mature margin pools where scale and logistics integration determine supplier viability.
BIS enforces IS 15682 standards for food-contact glass, while CDSCO mandates DMF-linked packaging for drug approval, and the PLI scheme for specialty steel and glass incentivizes capital investment in advanced furnace technology. Regulatory stringency is forcing mid-tier converters toward technical upgrades or exit, concentrating supply among certified national players. Stakeholders must monitor BIS notification cycles and state-level plastic bans to anticipate demand inflections for glass alternatives.
Market Dynamics
BIS certification mandates for food-contact glass are forcing mid-tier converters toward technical upgrades or exit, concentrating supply among certified national players with furnace modernization capabilities.
Growth Catalysts
- PLI scheme for specialty steel and glass:Capital investment in advanced furnace technology accelerates as fiscal incentives reduce payback periods for borosilicate and treated glass lines.
- Pharmaceutical parenteral drug output:Rising biologics production pulls demand for Type I borosilicate vials and barrier-coated amber glass across Maharashtra and Gujarat manufacturing clusters.
- Plastic Waste Management Rules:Compliance cost consolidation for plastic converters elevates glass substitution in regulated beverage and food categories where BIS standards apply.
Market Restraints
- Silica sand supply concentration:Western India captive mining rights held by integrated players create input access barriers for new entrants in soda-lime container glass.
- Fuel cost volatility:Natural gas and furnace oil price swings compress margin pools for float and container glass operations lacking long-term supply contracts.
- Technical limitation in thin-walling:Lightweight bottle production below 180 grams for carbonated beverages remains constrained by thermal shock resistance thresholds in domestic furnace configurations.
Strategic Opportunities
- Eastern and northeastern state penetration:Beverage and pharmaceutical distribution networks remain underdeveloped in Odisha, Bihar, and Assam relative to western India density.
- CDSCO DMF-linked packaging mandate:Drug approval requirements for pharmacopeia-grade certification create premium positioning opportunities for converters with Type I borosilicate capability.
- Channel consolidation in organized retail:Modern trade and e-commerce grocery platforms favor standardized palletization and SKU rationalization that rewards scale glass suppliers.
Industry Challenges
- Furnace refractory engineering talent scarcity:Specialized skills for oxy-fuel and electric melting conversions remain concentrated among legacy plant operators, slowing technology adoption timelines.
- BIS notification cycle unpredictability:IS 15682 standard revision timelines create inventory and certification planning friction for converters serving multiple end-use verticals.
- Legacy batch house integration:Automated cullet handling and raw material dosing systems require retrofit compatibility with 1980s-era plant footprints common in mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Glass Packaging Market |
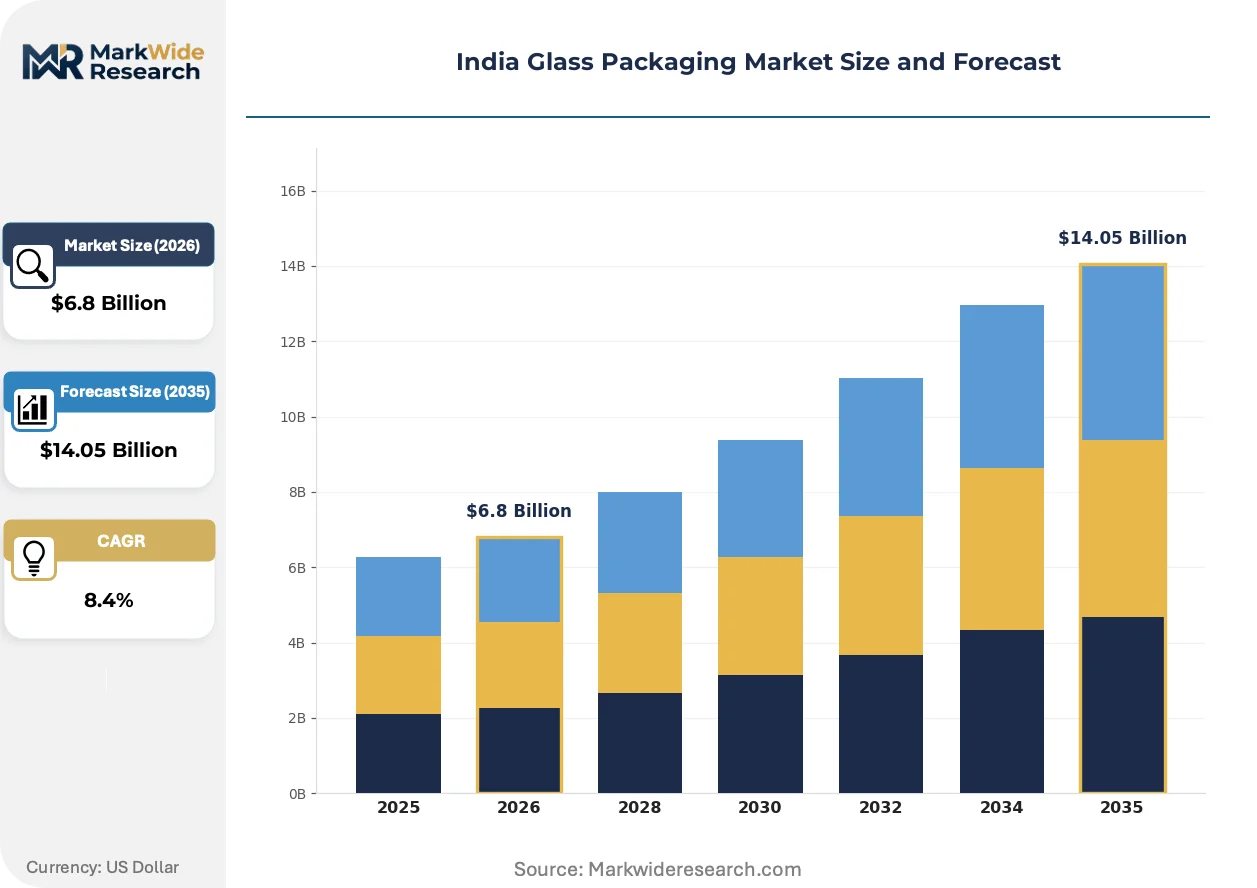
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Blisters End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Application: Beverage Packaging, Food Packaging, Medical Packaging, Personal Care Packaging Sales Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | Haldyn Glass Limited, SGD Pharma India Limited, AGI Greenpac Limited, Ajanta Bottle Private Limited, Borosil Glass Works Limited, Hindustan National Glass and Industries Limited, Gerresheimer AG, Schott Kaisha Private Limited, Piramal Glass Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Glass Packaging Market Shifts & Advancements
Digital furnace control and forming automation are compressing defect rates while regulatory stringency around drug-contact materials accelerates pharmacopeia-grade investment cycles.
Electrical boosting and oxy-fuel combustion systems are automating temperature precision across melting and conditioning zones. Pharmaceutical vial manufacturers in Gujarat adopt these retrofits fastest, driven by CDSCO batch consistency requirements. The technology is automating real-time viscosity adjustment that previously required manual operator intervention, reducing thermal shock rejection rates in borosilicate forming.
BIS notification cycles for IS 15682 food-contact standards are tightening heavy metal migration thresholds and surface finish specifications. Compliance deadlines force converters to upgrade annealing lehr configurations or exit certified supplier lists. Beverage packaging lines in Maharashtra face the steepest requalification burden as FSSAI enforcement intensifies ahead of state-level plastic ban expansions.
Buyer consolidation among multinational pharmaceutical contract manufacturers is compressing supplier qualification timelines and unbundling technical service from unit pricing. Domestic injectables producers now demand dedicated quality agreement frameworks and audit transparency that displace transactional spot purchasing. This pattern concentrates procurement leverage in the Mumbai-Pune corridor where biologics fill-finish capacity clusters most densely.
India Glass Packaging Market Segmentation
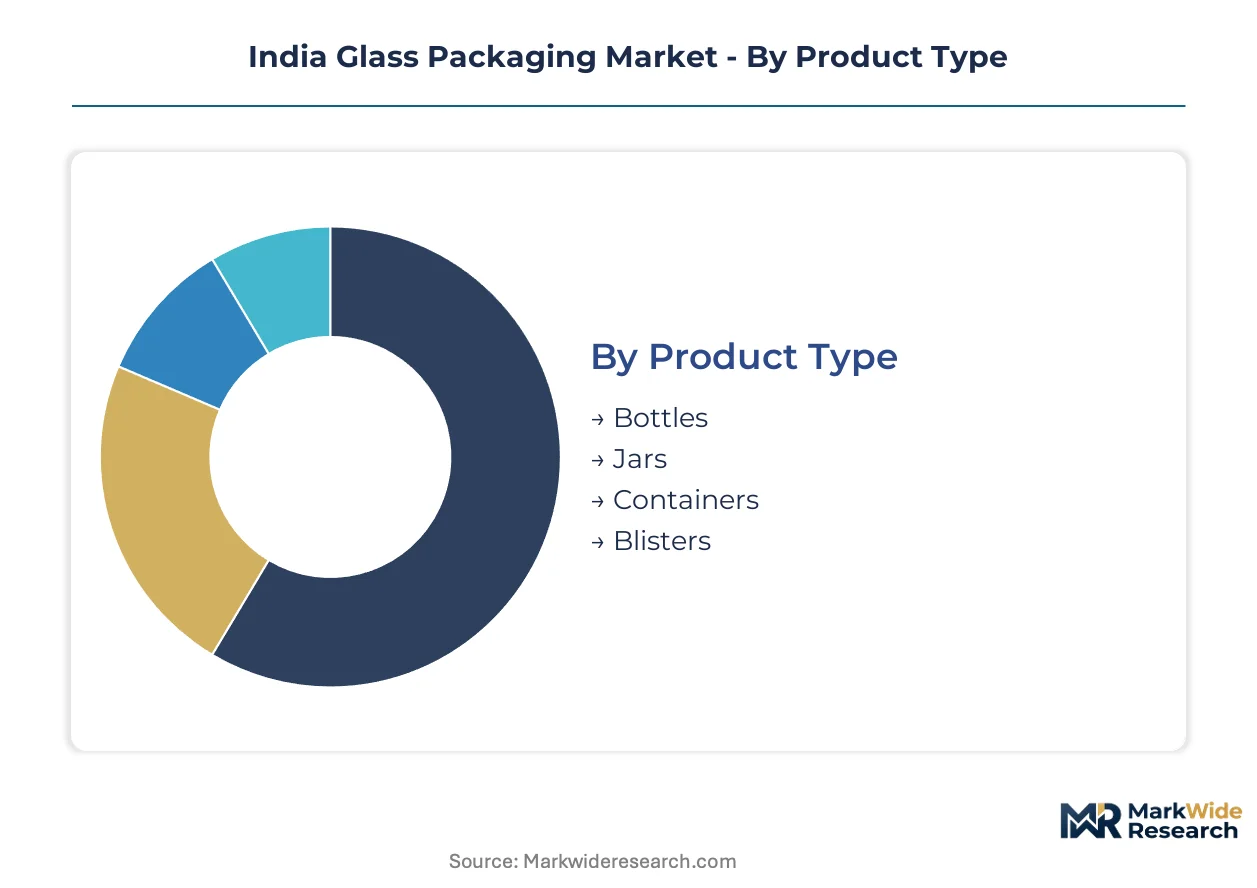
Glass packaging segmentation in India reflects divergent certification burdens across pharmaceutical, food-contact, and beverage applications. BIS, CDSCO, and FSSAI mandates create tiered compliance costs that reshape supplier viability by segment.
Product Type:
BIS IS 15682 certification applies universally across food-contact formats, while CDSCO DMF-linkage restricts pharmaceutical-grade production to converters with Type I borosilicate furnace capability.
- Bottles:Soda-lime and borosilicate configurations dominate beverage and pharmaceutical filling lines respectively. Maharashtra and Gujarat beverage clusters pull lightweight sub-200-gram formats for carbonated drinks, though thermal shock resistance thresholds constrain thin-walling below 180 grams in domestic furnace configurations.
- Jars:Wide-mouth soda-lime vessels for food preservation face tightening heavy metal migration thresholds under revised BIS notification cycles. FSSAI enforcement intensifies ahead of state-level plastic ban expansions, forcing annealing lehr upgrades or exit from certified supplier lists.
- Containers:General-purpose storage formats occupy mature margin pools where logistics integration and cullet-handling automation determine viability.
- Blisters:Thermoformed barrier formats for unit-dose pharmaceuticals require pharmacopeia-grade certification that concentrates supply among Gujarat-based converters with dedicated quality agreement frameworks.
Leading the category by volume: Bottles. Growing fastest: Blisters.
End User:
Customer procurement patterns split between transactional spot purchasing in beverages and audit-intensive partnership frameworks in pharmaceuticals.
- Food & Beverage:Organized retail and e-commerce grocery platforms favor standardized palletization that rewards scale suppliers with automated batch house systems.
- Pharmaceuticals:Type I borosilicate vials for parenteral drugs command premium positioning through CDSCO-mandated DMF linkage. Mumbai-Pune corridor biologics fill-finish capacity concentrates demand for barrier-coated and amber glass with dedicated quality agreements and audit transparency requirements.
- Cosmetics:Decorative flint and colored glass for premium positioning faces import competition in fragrance and skincare segments.
- Household Products:Standard soda-lime containers for cleaning agents compete on unit economics against plastic alternatives with lower compliance burdens.
Dominating procurement spend: Pharmaceuticals. Expanding most quickly: Food & Beverage substitution from plastic bans.
Application:
Application-level demand maps directly to state-level industrial clustering and regulatory enforcement intensity.
- Beverage Packaging:Carbonated soft drink and alcoholic beverage bottling concentrates in Maharashtra where captive silica sand mining rights create input access barriers for new entrants.
- Food Packaging:Preserved foods and condiments drive jar demand with BIS certification timelines creating inventory planning friction for multi-vertical converters.
- Medical Packaging:Injectable pharmaceuticals and lyophilized biologics require barrier-coated amber glass with thermal shock resistance calibrated to autoclave sterilization cycles. Gujarat manufacturers adopt oxy-fuel and electric melting retrofits fastest to meet CDSCO batch consistency requirements.
- Personal Care Packaging:Cosmetic flint bottles and jars occupy mid-tier margin pools between pharmaceutical premiums and commodity beverage economics.
Highest volume throughput: Beverage Packaging. Steepest value expansion trajectory: Medical Packaging.
Sales Channel:
Channel structure reflects customer scale and specification complexity, from standardized pallet loads to customized quality frameworks.
- Online Retail:Direct-to-consumer glass packaging for artisanal food and cosmetic brands remains nascent with fragmented order sizes.
- Wholesale:Distributor networks serve mid-tier beverage and food processors with standardized SKU catalogs and volume-based pricing.
- Direct Sales:Multinational pharmaceutical contract manufacturers compress supplier qualification timelines and unbundle technical service from unit pricing through dedicated quality agreements.
- Supermarkets:Modern trade private label programs favor scale suppliers with palletization compatibility and SKU rationalization capabilities.
Primary volume flow: Wholesale. Gaining share fastest: Direct Sales into pharmaceutical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level industrial incentives and SEZ status concentrate glass packaging capacity in western India, while eastern and northeastern states present underdeveloped distribution networks for beverage and pharmaceutical supply.
Maharashtra
Mumbai-Pune corridor biologics fill-finish capacity drives Type I borosilicate vial demand for parenteral drugs. BIS IS 15682 enforcement through FSSAI intensifies ahead of state plastic ban expansions. Nashik and Aurangabad beverage clusters pull lightweight soda-lime bottles from captive silica sand operations.
Gujarat
Pharmaceutical contract manufacturers cluster around Ahmedabad and Vadodara for CDSCO-mandated DMF-linked packaging. PLI scheme incentives accelerate oxy-fuel furnace retrofits for batch consistency compliance. Mundra and Hazira port access supports export-oriented borosilicate vial production.
Telangana
Hyderabad vaccine and injectables manufacturing creates emerging demand for amber glass and barrier-coated vials. State industrial policy offers capital subsidies for pharmaceutical packaging ancillaries. Genome Valley biotech corridor remains underserved by domestic Type I glass suppliers.
Tamil Nadu
Sriperumbudur electronics and automotive corridors spill over into cosmetic and household glass packaging demand. Chennai port infrastructure enables imported cullet and specialty raw material access. Organized retail expansion in Coimbatore drives jar demand for processed foods under BIS certification.
West Bengal
Kolkata metropolitan beverage bottling operates at lower scale than western India clusters, creating logistics cost disadvantages. FSSAI enforcement of food-contact standards lags Maharashtra and Gujarat timelines. Haldia port chemical industry generates niche demand for industrial glass containers.
India Glass Packaging Market Competitive Landscape
Western India producers anchor the integrated tier; specialized pharmaceutical converters hold premium positioning through pharmacopeia certification. Market structure concentrates among national-scale furnace operators with BIS compliance capability and regional mid-tier converters facing exit pressure. Three archetypes dominate: captive mining-integrated soda-lime specialists, CDSCO-certified borosilicate manufacturers, and diversified packaging conglomerates with cross-material portfolios. Competitive moves center on furnace modernization for IS 15682 compliance and direct sales partnerships with multinational pharmaceutical contract manufacturers.
Within the integrated western tier, Haldyn Glass Limited and AGI Greenpac Limited exemplify scale-driven soda-lime production anchored to beverage and food packaging demand. SGD Pharma India Limited occupies the pharmaceutical-specialist position through Type I borosilicate capability and CDSCO-linked quality frameworks. These three entities represent the dominant competitive archetypes: mining-integrated volume production, lightweight bottle innovation, and pharmacopeia-grade medical packaging respectively.
| Leading Market Players |
|---|
| Haldyn Glass Limited |
| SGD Pharma India Limited |
| AGI Greenpac Limited |
| Ajanta Bottle Private Limited |
| Borosil Glass Works Limited |
| Hindustan National Glass and Industries Limited |
| Gerresheimer AG |
| Schott Kaisha Private Limited |
| Piramal Glass Private Limited |
| Others |
Supply & Pricing Matrix
Silica sand benchmark fluctuations cascade through Maharashtra and Gujarat furnace operations, compressing margin pools for non-integrated converters while amplifying pricing power for captive mining holders across pharmaceutical and beverage supply tiers.
Pricing Analysis
Lead-time premiums for pharmacopeia-grade borosilicate vials command substantial markups over spot inventory in Gujarat pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-certified Type I glass from BIS-compliant food-contact grades and commodity soda-lime beverage formats. Cost compression in lightweight bottle segments intensifies because thermal shock resistance constraints limit thin-walling below 180 grams. Multinational pharmaceutical contract manufacturers exhibit lowest price sensitivity due to audit-intensive partnership frameworks, while mid-tier beverage processors face acute spot-market pressure.
Supply Chain Analysis
CDSCO DMF-linkage and BIS IS 15682 certification gate supply participation, concentrating viable production among furnace operators with pharmacopeia-grade capability. Manufacturing gravity centers on India, with secondary dependencies on specialty raw material imports for borosilicate formulations. Raw material sourcing draws from captive silica sand mining in western India, imported soda ash, and domestic limestone deposits. Single-source vulnerability permeates oxy-fuel furnace refractory engineering talent pools. Distribution runs through direct sales partnerships with multinational pharmaceutical contract manufacturers and wholesale networks serving mid-tier beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS notification cycles for IS 15682 standards erect compliance moats that filter mid-tier converters from certified supplier lists, concentrating viable participation among furnace modernization-capable national players.
For Market Incumbents: To counter margin erosion from fuel cost volatility, Haldyn Glass Limited and AGI Greenpac Limited should deepen captive silica sand integration and secure long-term natural gas supply contracts. Furnace refractory engineering talent scarcity threatens technology adoption timelines; incumbents must lock specialized oxy-fuel conversion expertise through retention premiums or acquisition of legacy plant operator technical teams. For New Entrants and Emerging Players: E-commerce grocery platform procurement channels offer white-space penetration for standardized jar and container formats in underdeveloped eastern state markets. Odisha and Bihar beverage distribution networks remain sparse relative to western India density. Genome Valley biotech corridor vaccine manufacturing creates unmet demand for amber glass and barrier-coated vials. Target direct sales partnerships with Hyderabad-based injectables producers seeking domestic Type I borosilicate alternatives to import dependency. For Investors and Strategic Acquirers: Distressed-cycle entries favor CDSCO-certified borosilicate specialists in Gujarat with underutilized furnace capacity and pharmacopeia-grade quality frameworks. Long-term viability hinges on PLI scheme incentive capture and sustained biologics fill-finish capacity expansion across the Mumbai-Pune corridor. Monitor BIS notification cycles for IS 15682 heavy metal migration threshold revisions as inflection indicators for forced exit waves among non-compliant mid-tier converters.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Modernization for BIS Compliance | IS 15682 certification upgrades filter non-compliant competitors from FSSAI-regulated food-contact supply. |
| Backward Integration into Silica Sand Mining | Captive western India mining rights neutralize input cost volatility and create supply security moats. |
| Oxy-Fuel Combustion Retrofit | Electric melting conversions meet CDSCO batch consistency demands for Type I borosilicate pharmaceutical output. |
| Direct Sales Partnership with Pharma Contract Manufacturers | Dedicated quality agreements unbundle technical service from unit pricing in Mumbai-Pune biologics clusters. |
| Eastern State Distribution Network Expansion | Odisha and Bihar beverage bottling penetration captures substitution demand from state-level plastic ban enforcement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this India glass packaging assessment. Primary interviews with furnace operations managers, pharmaceutical packaging procurement leads, FSSAI compliance officers, and beverage bottler supply chain directors combined with BIS notification archives, CDSCO drug approval databases, and PLI scheme disclosure documents. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Data-stream reconciliation across furnace throughput metrics, pharmaceutical vial procurement patterns, and state-level industrial policy incentives shaped the analytical framework. Segmentation modeling captured product type, end user vertical, application, and sales channel dimensions alongside regional regulatory enforcement intensity variations. CAGRs derived from installed capacity expansion timelines, biologics fill-finish capacity buildout rates, and substitution elasticity estimates from plastic ban implementation phases.
Inputs from BIS, CDSCO, and FSSAI were available through the study window; gaps in real-time furnace fuel cost contract terms introduce uncertainty bands around margin projections. Forecasts reflect assumptions on PLI scheme incentive continuity and state-level plastic ban expansion sequencing. A model refresh is warranted upon material change in BIS IS 15682 notification timelines or CDSCO DMF-linkage requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Indonesia Container Glass Market