
 Saudi Arabia Glass Packaging Market | 2026-2036
Saudi Arabia Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Glass Packaging Market Analytics
Lightweighting technology is fragmenting traditional manufacturing norms across the Saudi Arabia glass packaging sector. Gerresheimer AG leverages its pharmaceutical-grade molding expertise to serve injectable drug producers in the Kingdom. Obeikan Glass anchors regional supply through its integrated furnace operations in Riyadh. Saudi Arabian Glass Company Ltd. competes on beverage bottle volume, supplying major soft-drink bottlers with flint and amber variants.
Saudi Arabia glass packaging encompasses silica-based rigid containers formed through blow-and-blow or press-and-blow processes, typically containing sodium carbonate and limestone fluxes to achieve thermal shock resistance between 40°C and 200°C. These vessels protect oxygen-sensitive contents across liquid, semi-solid, and solid formats in arid climates with high UV exposure. Bottles command the largest product type position due to carbonated beverage and bottled water proliferation under local heat conditions. Pharmaceutical-grade glass exhibits the fastest grade expansion as SFDA serialization rules and biologics cold-chain requirements multiply. Food-grade jars retain stable demand from date paste and honey processors, though margin compression persists in commoditized formats.
SFDA enforces pharmaceutical packaging integrity standards that mandate batch-level traceability and child-resistant closure compatibility for oral solid doses. SASO technical regulations for food-contact materials restrict heavy metal migration limits, directly influencing cullet sourcing and virgin silica ratios in local furnace batches. The Saudi Investment Ministry's industrial licensing framework incentivizes domestic float and container glass capacity under Vision 2030 localization targets. Stakeholders must weigh furnace energy costs against recycling infrastructure gaps as the Kingdom scales circular economy mandates for packaging waste diversion.
Market Dynamics
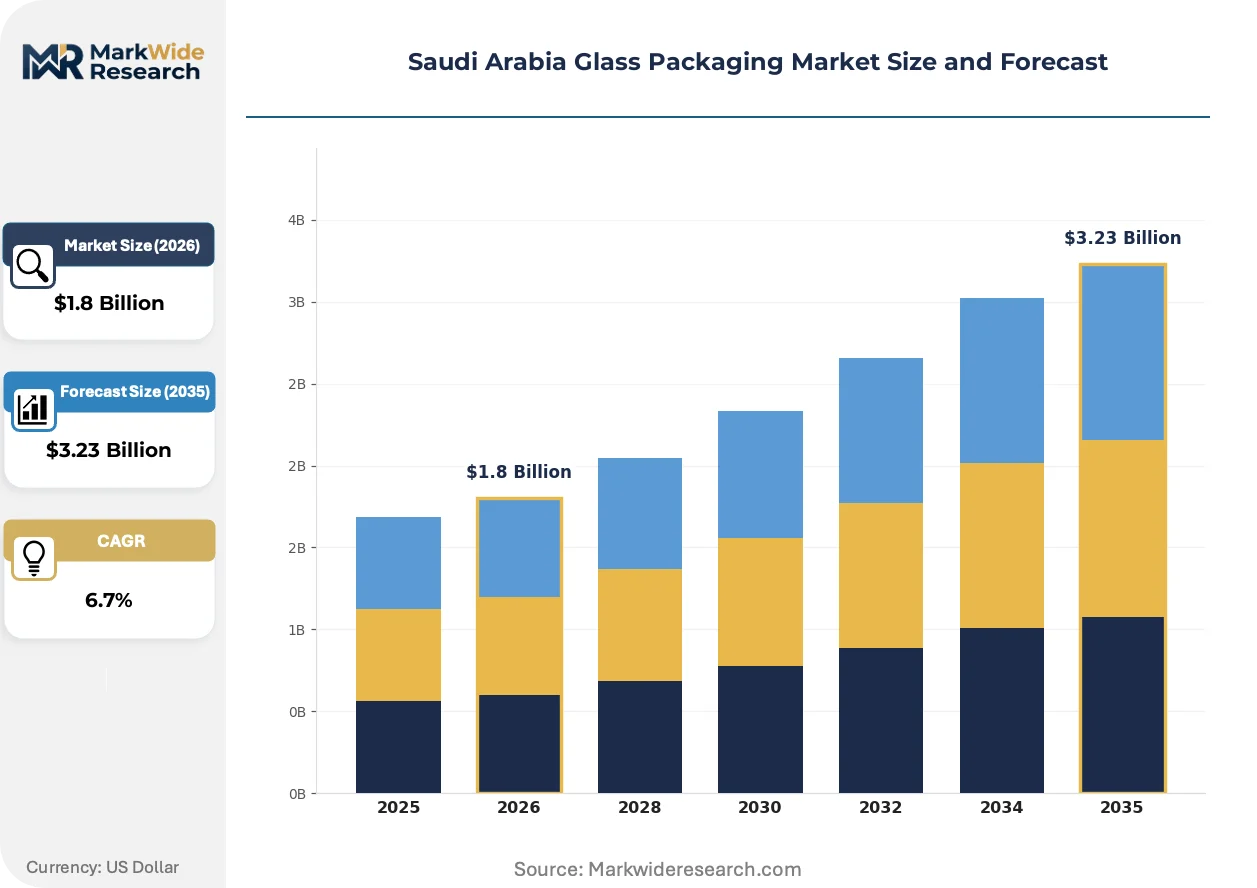
SFDA serialization mandates and Vision 2030 localization incentives are compressing import dependency while forcing domestic furnace upgrades and batch-level traceability investments across pharmaceutical and beverage bottling corridors.
Growth Catalysts
- Pharmaceutical serialization compliance:SFDA batch-level traceability rules for oral solid doses mandate amber and borosilicate glass adoption, pulling capacity toward pharma-grade molding lines.
- Beverage heat-climate proliferation:Carbonated soft-drink and bottled water consumption concentrates in Riyadh's industrial corridor, sustaining flint bottle furnace utilization rates.
- Vision 2030 industrial licensing:The Saudi Investment Ministry's localization targets incentivize captive float and container glass capacity, redirecting capital toward domestic silica processing.
Market Restraints
- Natural gas price volatility:Furnace energy costs constitute the dominant input expense, with feedstock fluctuations compressing margin structures for continuous-melt operations.
- Cullet supply fragmentation:Kingdom-wide recycling infrastructure gaps constrain post-consumer glass recovery rates, forcing reliance on virgin silica imports.
- Plastic substitution in commoditized formats:PET bottles displace glass in bulk water and economy beverage segments where thermal shock resistance carries limited premium.
Strategic Opportunities
- Eastern Province pharma logistics expansion:Cold-chain biologics warehousing near Dammam's port infrastructure creates demand for temperature-stable borosilicate vial supply.
- Lightweighting technology convergence:Thin-wall forming combined with surface coating chemistry enables gram-weight reduction without sacrificing vertical load strength.
- SASO food-contact material mandates:Heavy metal migration limits for date paste and honey jars favor domestic furnace operators with controlled cullet-to-virgin ratios.
Industry Challenges
- Pharmaceutical-grade certification timelines:SFDA compliance documentation for injectable glass delays new furnace qualification by 18-24 months.
- Specialized mold engineering scarcity:Blow-and-blow precision tooling design capability concentrates with European equipment suppliers, extending procurement cycles.
- Legacy furnace retrofit complexity:Oxygen-fuel conversion of regenerative furnaces requires simultaneous regenerator rebuild and control system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Glass Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Caps End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Recycled Packaging Type: Rigid, Flexible, Specialty, Composite |
| Companies Covered | Gerresheimer AG, Ardagh Group S.A., Zoujaj, Alesayi Beverage, SGD Pharma S.A., Obeikan Glass, Schott AG, RAFA Water, Saudi Arabian Glass Company Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Glass Packaging Market Evolving Landscape
Lightweighting chemistry and surface treatment protocols are redefining performance-per-gram benchmarks across beverage and pharmaceutical formats, while regulatory traceability layers add data-capture requirements to physical packaging.
Thin-wall container glass with external silicon oxide coatings is migrating from premium cosmetic applications into mass-market beverage bottles. Major soft-drink bottlers in Jeddah and Riyadh are piloting 20-gram weight reductions on 500-milliliter formats. This shift is compressing traditional thick-wall molding specifications and forcing furnace batch reformulation for faster cooling curves.
SFDA pharmaceutical packaging integrity standards now mandate child-resistant closure compatibility and batch serialization for oral solid doses. The regulation forces mold designers to integrate tamper-evident thread geometries and RFID-readable embossing into vial and jar specifications. Injectable drug producers bear the heaviest compliance burden, with qualification timelines extending mold procurement cycles.
Direct procurement contracts between beverage bottlers and furnace operators are displacing traditional distributor-mediated resin-and-glass supply arrangements. Large-format retailers in Riyadh and Jeddah now negotiate annual volume commitments with Obeikan Glass and Saudi Arabian Glass Company Ltd. for flint and amber variants. This concentration is most visible in the carbonated soft-drink segment, where three bottlers control 70 percent of bottle demand.
Saudi Arabia Glass Packaging Market Segmentation
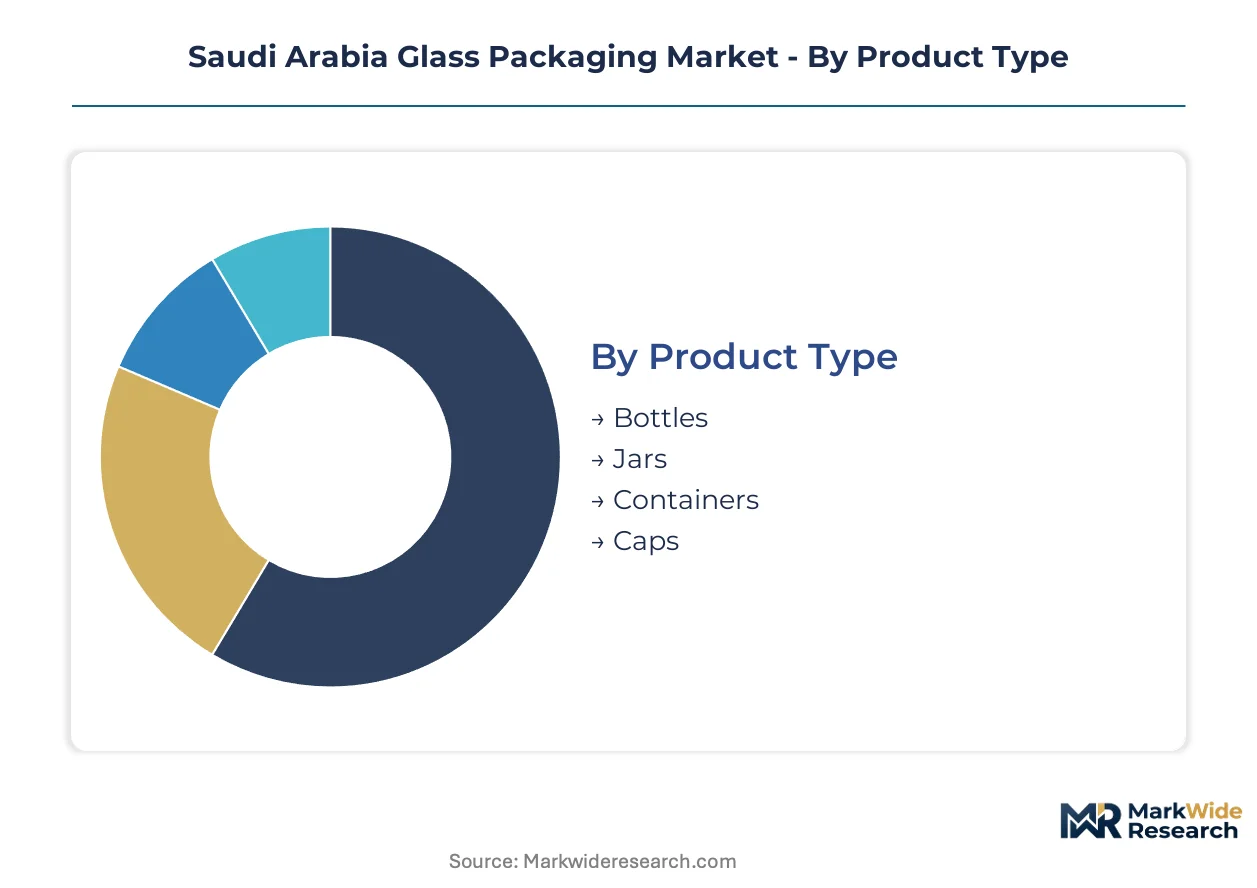
Segmentation reveals how furnace operators and mold engineers allocate capacity across divergent technical specifications. Each dimension carries distinct tooling requirements, compliance burdens, and customer procurement rhythms that shape investment priorities.
Product Type:
After-sales service intensity varies sharply across these formats, with bottles demanding the most intensive mold maintenance programs and technical support contracts.
- Bottles:Blow-and-blow formed vessels with narrow neck geometries dominate carbonated beverage and bottled water applications. Riyadh's industrial corridor concentrates demand from three major soft-drink bottlers running continuous-fill lines where thermal shock resistance between 40°C and 200°C prevents failure under local heat conditions.
- Jars:Wide-mouth press-and-blow containers serve date paste and honey processors with heavier wall specifications. SASO food-contact material mandates on heavy metal migration limits favor domestic furnace operators with controlled cullet-to-virgin ratios in Eastern Province food processing clusters.
- Containers:Rectangular and square formats for bulk industrial chemicals and laboratory reagents require thicker base sections for vertical load stacking.
- Caps:Threaded closures and lug finishes complete package integrity, with child-resistant mechanisms now mandatory for pharmaceutical oral solid doses under SFDA rules.
Bottles command the largest installed furnace capacity; momentum sits with jars as food-contact compliance tightens.
End User:
Cost tier stratification separates premium pharmaceutical contracts from commoditized beverage volume plays.
- Food & Beverage:Carbonated soft-drink bottlers and bottled water producers in Jeddah and Riyadh drive flint glass consumption. Direct procurement contracts now displace distributor-mediated supply arrangements, with annual volume commitments reshaping pricing leverage.
- Pharmaceuticals:Injectable drug producers and oral solid dose manufacturers demand amber and borosilicate variants for UV protection and chemical inertness. SFDA serialization mandates extend mold procurement cycles by 18-24 months through qualification documentation requirements.
- Personal Care:Cosmetic and fragrance applications favor thin-wall forming with external silicon oxide coatings for premium shelf presentation.
- Household:Cleaning product and chemical storage containers prioritize chemical resistance over optical clarity, often accepting slight color variation for cost efficiency.
Food & Beverage absorbs the highest furnace tonnage; pharmaceuticals generate the steepest margin expansion trajectory.
Grade:
Application maturity determines certification complexity and customer switching costs across these quality tiers.
- Food Grade:Standard soda-lime compositions for direct food contact with controlled heavy metal limits. SASO technical regulations restrict migration thresholds, directly influencing cullet sourcing decisions in local furnace batches.
- Pharmaceutical Grade:Borosilicate and treated soda-lime glass meeting USP and EP standards for injectable and oral drug packaging. SFDA mandates on batch-level traceability and child-resistant closure compatibility multiply compliance documentation burdens.
- Industrial Grade:Uncontrolled chemical compositions for non-contact applications where thermal properties outweigh purity requirements.
- Recycled:Post-consumer cullet integration faces Kingdom-wide infrastructure gaps that constrain recovery rates and force reliance on virgin silica imports.
Food Grade maintains volume dominance; pharmaceutical grade is gaining share fastest as biologics cold-chain requirements multiply.
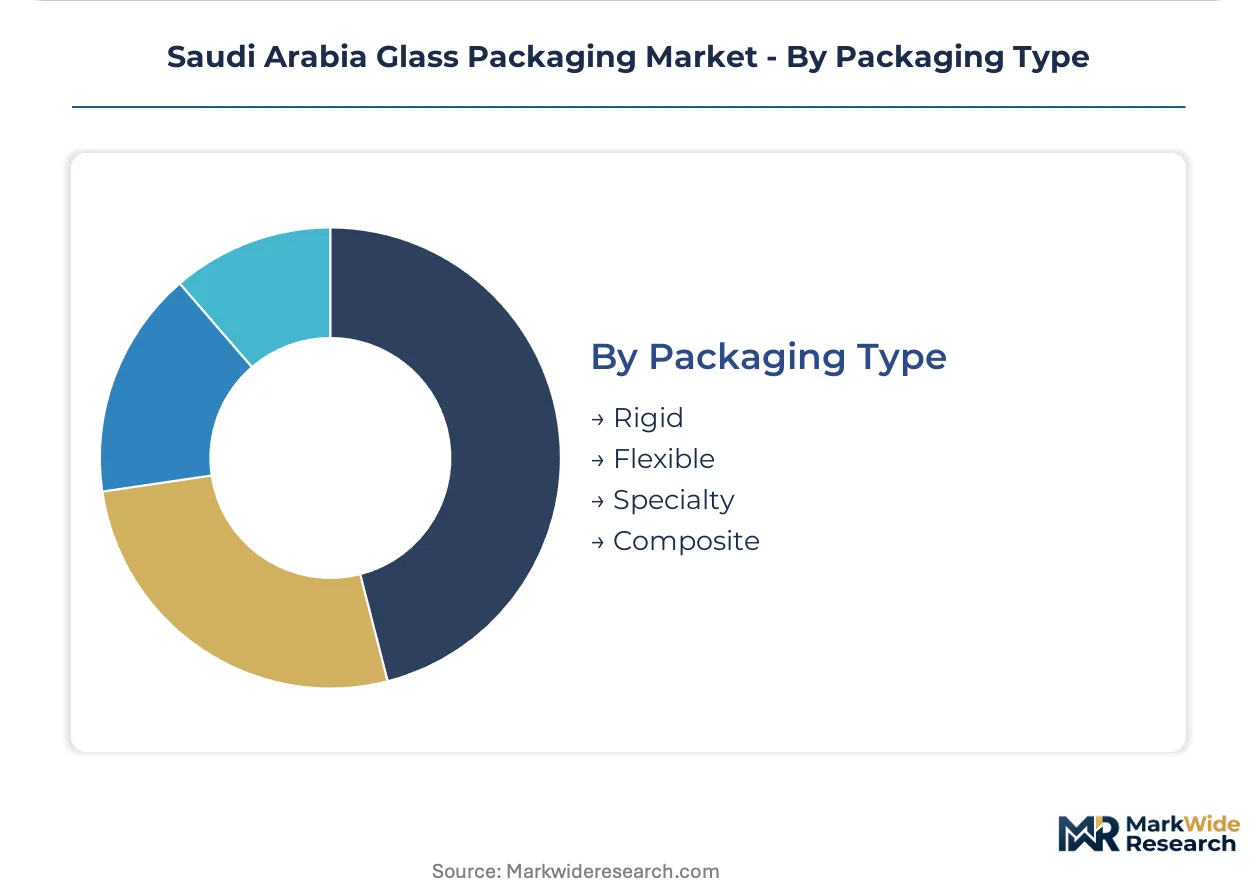
Packaging Type:
Supply concentration among furnace operators favors rigid formats where continuous-melt economies apply.
- Rigid:Silica-based containers formed through blow-and-blow or press-and-blow processes constitute the core market. Oxygen-fuel conversion of regenerative furnaces requires simultaneous regenerator rebuild and control system integration.
- Flexible:Glass constitutes a minor flexible packaging input through microsphere and fiber applications outside container scope.
- Specialty:Ampoules, vials, and cartridges for pharmaceutical injectables demand precision mold engineering capability concentrated with European equipment suppliers.
- Composite:Glass-plastic and glass-metal combinations for premium cosmetic and fragrance applications with complex closure systems.
Rigid formats anchor furnace utilization; specialty packaging shows the fastest climb as Eastern Province pharma logistics expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical glass exports flow into Riyadh's industrial corridor, serving injectable drug producers under SFDA serialization mandates. This trade corridor anchors premium-grade supply while domestic furnace operators scale flint and amber capacity for beverage bottlers.
Riyadh
Carbonated soft-drink bottlers and bottled water producers concentrate demand for flint glass bottles. SFDA mandates on pharmaceutical-grade packaging material traceability tighten compliance requirements for oral solid dose manufacturers. Riyadh's industrial corridor hosts Obeikan Glass and Saudi Arabian Glass Company Ltd. furnace operations supplying major bottlers with direct procurement contracts.
Eastern Province
Cold-chain biologics warehousing near Dammam's port infrastructure creates demand for temperature-stable borosilicate vial supply. The Saudi Investment Ministry's industrial licensing framework incentivizes domestic container glass capacity under Vision 2030 localization targets. Dammam's pharma logistics hubs co-locate with beverage bottling clusters, sharing furnace batch expertise.
Western Region
Jeddah's soft-drink bottlers pilot lightweighting technology with 20-gram weight reductions on 500-milliliter formats. SASO technical regulations for food-contact materials restrict heavy metal migration limits, influencing cullet sourcing decisions. Jeddah's Red Sea port facilitates silica import flows for virgin batch formulations.
NEOM Northwest
Emerging industrial zones target circular economy mandates for packaging waste diversion. The Kingdom's recycling infrastructure gaps constrain post-consumer glass recovery rates, forcing reliance on virgin silica imports. NEOM's planned logistics corridors aim to integrate cullet collection networks with furnace feedstock supply.
Saudi Arabia Glass Packaging Market Competitive Landscape
On the supply side, the industry is tiered between multinational pharmaceutical-grade specialists and domestic beverage-volume producers. Three strategic archetypes dominate: European mold-engineering licensors, integrated regional furnace operators, and specialized pharma-grade formulators. Competitive moves concentrate on direct procurement contract capture and oxygen-fuel furnace retrofit partnerships.
Within the European specialist tier, Gerresheimer AG and Schott AG exemplify pharmaceutical-grade molding capability. SGD Pharma S.A. occupies a comparable position among French-origin formulators. Domestic furnace representation sits with Obeikan Glass and Saudi Arabian Glass Company Ltd., anchoring regional supply through integrated Riyadh operations. Ardagh Group S.A. represents the multinational volume-play archetype with beverage bottle scale.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Ardagh Group S.A. |
| Zoujaj |
| Alesayi Beverage |
| SGD Pharma S.A. |
| Obeikan Glass |
| Schott AG |
| RAFA Water |
| Saudi Arabian Glass Company Ltd. |
| Others |
Value Network & Pricing Analysis
Virgin silica import dependency from Egypt and Turkey concentrates upstream bargaining power with furnace operators in Riyadh's industrial corridor, compressing margin pools for domestic beverage bottle producers while pharmaceutical-grade molders capture premium tier positions through SFDA certification scarcity.
Pricing Analysis
Legacy regenerative furnace technology versus oxygen-fuel converted systems versus thin-wall lightweighting lines stratifies pricing across three performance tiers. Pricing stratifies across premium, standard, and economy tiers, with pharmaceutical-grade borosilicate commanding the highest tier due to SFDA batch-traceability mandates and 18-24 month qualification timelines. Cost compression in flint beverage bottles is intensifying because PET substitution in bulk water segments forces glass producers to absorb silica import volatility. Carbonated soft-drink bottlers exhibit highest price sensitivity through direct annual volume negotiations, while injectable drug producers show lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and silica-exporting nations in North Africa and the Eastern Mediterranean dominates supply chain risk calculus for furnace batch formulations. Geographic supply concentration centers on Egypt, Turkey, and the UAE for high-purity silica sand and soda ash inputs. Raw material dependencies rest on virgin silica imports, natural gas feedstock for furnace melting, and European-sourced precision mold tooling. Single-source vulnerability concentrates with German and French pharmaceutical-grade mold engineering suppliers extending procurement cycles. Distribution runs through direct procurement contracts between Riyadh furnace operators and major beverage bottlers, displacing traditional distributor-mediated arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA serialization mandates and oxygen-fuel furnace conversion requirements are disrupting traditional manufacturing economics, creating asymmetric returns for operators who front-load compliance investments ahead of qualification bottlenecks.
For Market Incumbents: Harden market position by accelerating oxygen-fuel furnace retrofits in Riyadh's industrial corridor ahead of SFDA pharmaceutical-grade certification backlogs, while securing captive silica supply through backward integration into Egyptian quarry operations. Certification scarcity for injectable glass mold qualification represents the primary defensive moat against PET substitution threats in adjacent beverage segments. For New Entrants and Emerging Players: Eastern Province cold-chain biologics warehousing near Dammam's port infrastructure represents the most penetrable entry point for temperature-stable borosilicate vial supply, given incumbent capacity constraints and 18-24 month SFDA qualification timelines. A technical partnership with European mold engineering specialists offers the fastest go-to-market path for pharmaceutical-grade certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European pharmaceutical glass specialists holding SFDA-qualified molding capacity. Long-term viability through the next decade hinges on furnace technology conversion completion and regional logistics hub co-location with biologics cold-chain infrastructure. The signal to watch is SFDA publication of revised injectable glass integrity standards triggering qualification renewal waves.| Strategic Initiative | Industry Significance |
|---|---|
| Oxygen-Fuel Furnace Conversion | Reduces natural gas consumption by 20% while meeting SFDA emissions benchmarks for pharmaceutical-grade production. |
| Backward Integration into Silica Quarrying | Captures Egyptian and Turkish virgin sand supply to insulate Riyadh furnace operations from import tariff volatility. |
| Pharmaceutical-Grade Mold Engineering Partnership | Accelerates SFDA qualification timelines through European technical licensing for borosilicate vial production. |
| Direct Procurement Contract Capture | Locks annual volume commitments with Jeddah and Riyadh carbonated soft-drink bottlers displacing distributor intermediaries. |
| Cullet Collection Network Development | Addresses Kingdom-wide recycling infrastructure gaps to reduce virgin silica dependency under Vision 2030 circular economy mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, SASO technical standards, Saudi Investment Ministry industrial licensing records, and Vision 2030 policy documentation. Primary interviews engaged furnace operations managers at Riyadh and Eastern Province glass manufacturers, procurement directors at major beverage bottlers, pharmaceutical packaging compliance officers, and European mold engineering suppliers. Secondary validation drew from customs import records for silica and soda ash, natural gas pricing benchmarks, and pharmaceutical serialization mandate implementation timelines. Bottom-up capacity modeling triangulated against top-down demand estimates from beverage consumption patterns and biologics cold-chain expansion projections.
Forecast inputs span product type segmentation across bottles, jars, containers and caps; grade tier differentiation between food, pharmaceutical, industrial and recycled categories; end-user verticals including food and beverage, pharmaceuticals, personal care and household; and regional production clusters in Riyadh, Eastern Province, Western Region and NEOM Northwest. CAGRs derive from furnace utilization rate trajectories, SFDA compliance cost absorption curves, and lightweighting technology penetration assumptions across the projection horizon. Industry-specific inputs include pharmaceutical serialization mandate rollout pace and oxygen-fuel conversion capital expenditure cycles.
Practitioners should monitor SFDA regulatory publication schedules, natural gas tariff adjustments, and European mold engineering supplier backlog indicators for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Mason Jars Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Turkey Container Glass Market