
 Dosage Cups Market | 2026-2036
Dosage Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Dosage Cups Market Analysis
EU MDR and FDA 21 CFR Part 211 requirements on dosing accuracy is recalibrating material selection across dosage cup supply chains. Comar leverages captive resin processing capabilities to control polypropylene purity for pharmaceutical-grade cups. Gerresheimer AG anchors European hospital demand through calibrated glass and plastic dosing portfolios. Berry Global competes on thermoforming scale across retail pharmacy channels in North America.
Dosage cups are precision-measured dispensing vessels, typically molded from polypropylene, polystyrene, or amber glass, with graduated markings calibrated to deliver oral liquid medications within milliliter tolerances. Manufacturing employs injection molding or thermoforming with in-line vision systems verifying dimensional accuracy against pharmacopeial standards. Plastic material dominates hospital and pharmacy procurement due to breakage resistance and unit-cost economics, while glass retains share in light-sensitive formulations where chemical inertness commands priority. The 10ml and 20ml size brackets carry the volume base as standard pediatric and adult antibiotic suspensions concentrate demand, though 5ml precision cups for concentrated pediatric therapies are gaining fastest.
FDA compliance mandates, EU MDR technical documentation requirements, and ISO 15378 pharmaceutical packaging standards collectively govern material biocompatibility, dimensional tolerance, and child-resistant closure integration. These frameworks elevate barrier-to-entry for uncertified converters while rewarding suppliers with validated quality management systems and established regulatory dossiers. Stakeholders must monitor evolving USP <661> plastic packaging standards and state-level pharmaceutical waste regulations that could mandate recyclable or bio-based material transitions.
Market Dynamics
Calibration mandates from FDA 21 CFR Part 211 and EU MDR are compressing supplier qualification timelines while forcing converters to validate dimensional tolerances within millimeter precision. This regulatory tightening is restructuring procurement relationships as hospitals and pharmacies consolidate vendor panels around certified manufacturers with established quality management systems.
Growth Catalysts
- FDA 21 CFR Part 211:Dosing accuracy requirements for oral liquid medications are expanding validation protocols across hospital formularies. Pharmacy procurement teams now require documented calibration certificates for all graduated dispensing vessels.
- Polystyrene-to-polypropylene substitution:Material conversion programs in pediatric hospitals are accelerating due to breakage resistance and sterilization compatibility. Thermoforming scale economies are compressing unit costs for high-volume antibiotic dispensing.
- United States hospital consolidation:Integrated delivery networks are standardizing dosage cup specifications across affiliated facilities. Volume procurement contracts now specify pharmacopeial-grade dimensional tolerances as baseline requirements.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with propylene monomer supply from Gulf Coast petrochemical complexes. Converters lack pricing power to pass through input spikes to contracted health system customers.
- Glass retention in light-sensitive segments:Amber glass dosage cups retain share in oncology and vitamin formulations where UV protection commands priority. Plastic converters cannot replicate chemical inertness for photosensitive APIs.
- ISO 15378 certification timelines:Pharmaceutical packaging standards require 12-18 month validation cycles for new manufacturing lines. Uncertified regional converters face exclusion from hospital procurement panels.
Strategic Opportunities
- Home healthcare expansion:Discharge protocols in United States acute care facilities are extending calibrated dispensing to outpatient medication management. Retail pharmacy chains are developing co-branded dosage cup programs for chronic disease patients.
- Child-resistant closure integration:FDA pediatric poisoning prevention guidelines are creating demand for tamper-evident cup-cap combinations. Molded-in locking mechanisms represent a design white space beyond standard open-vessel formats.
- Bio-based polypropylene pilot programs:United States state-level pharmaceutical waste regulations in California and Washington are probing renewable content mandates. Early movers in mass-balance certified resins can secure preferred supplier status with sustainability-committing health systems.
Industry Challenges
- Vision system technician scarcity:In-line dimensional verification requires operators trained in machine vision calibration and pharmacopeial tolerance interpretation. Community colleges lack specialized curricula for pharmaceutical packaging quality control.
- Legacy mold requalification:Existing injection tooling requires recertification under revised USP plastic packaging standards. Tooling modification timelines extend 6-9 months, compressing production windows during regulatory transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosage Cups Market |
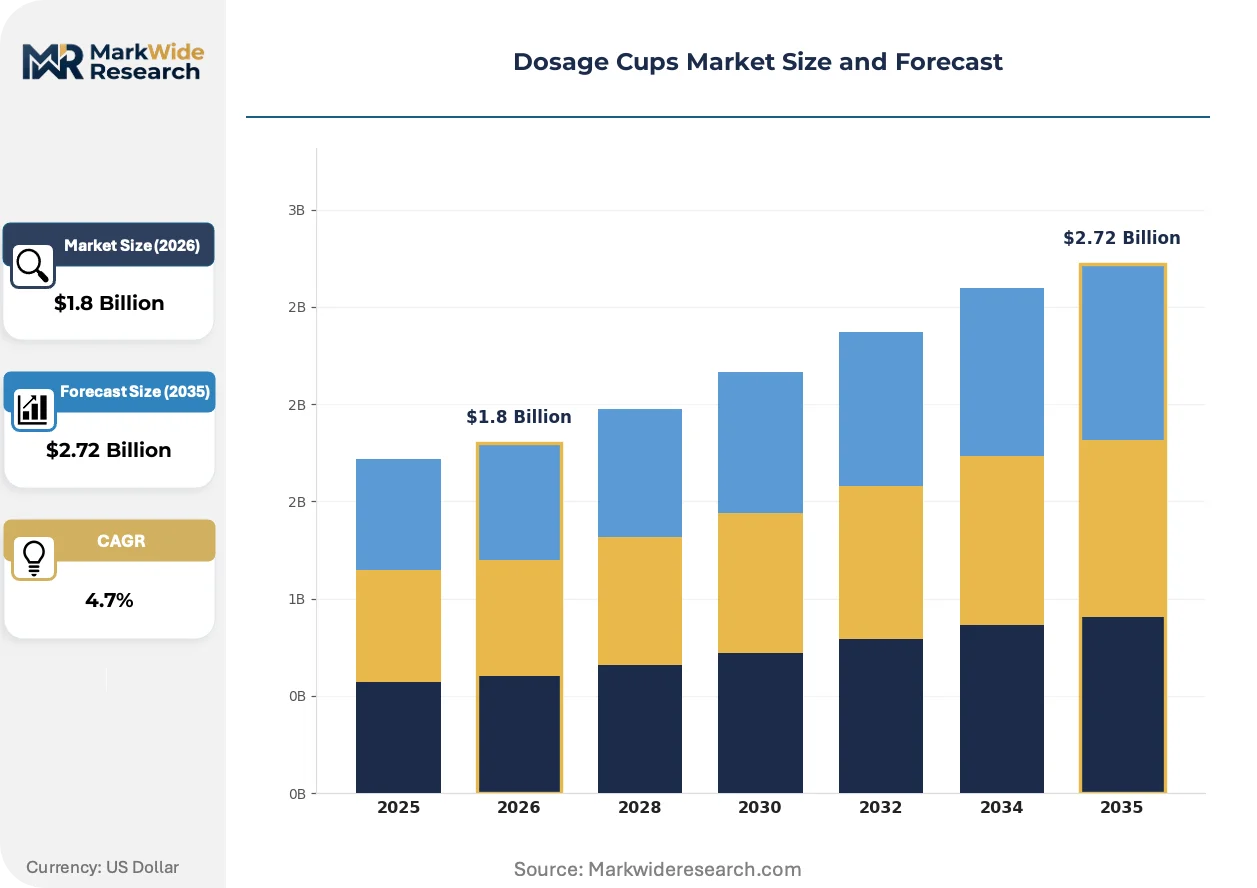
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Glass, Paper, Silicone Size: 5ml, 10ml, 20ml, 30ml End User: Pharmacies, Hospitals, Homecare, Laboratories Distribution Channel: Online Retail, Supermarkets, Drugstores, Wholesalers |
| Companies Covered | Comar, Gerresheimer AG, Berry Global, Sonoco Products Company, Medline Industries, Origin Pharma Packaging, Qosina, AptarGroup, Adelphi Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosage Cups Market Emerging Trajectories
Automation of quality verification and material traceability is compressing defect rates while elevating barrier-to-entry for manual-process competitors. These shifts are reshaping capital deployment priorities across pharmaceutical packaging converters.
Machine vision systems with sub-millimeter resolution are automating dimensional inspection of graduated markings during continuous thermoforming operations. Hospital procurement teams now specify 100% in-line verification as a contract requirement. This technology is automating the elimination of manual sampling protocols that previously accepted statistical quality levels.
EU MDR technical documentation requirements are mandating material biocompatibility testing beyond previous CE marking thresholds. Converters must generate clinical evaluation reports for polymer leachables in oral contact applications. European hospital tenders now exclude suppliers lacking notified body certification for pharmaceutical primary packaging.
Consolidated buying by United States pharmacy benefit managers is compressing vendor panels for over-the-counter liquid medications. Retail chains are specifying direct-to-distributor fulfillment models that bypass traditional medical supply intermediaries. This channel restructuring is most visible in pediatric cough and cold segments where private-label dosage cups now ship direct to distribution centers.
Dosage Cups Market Segmentation
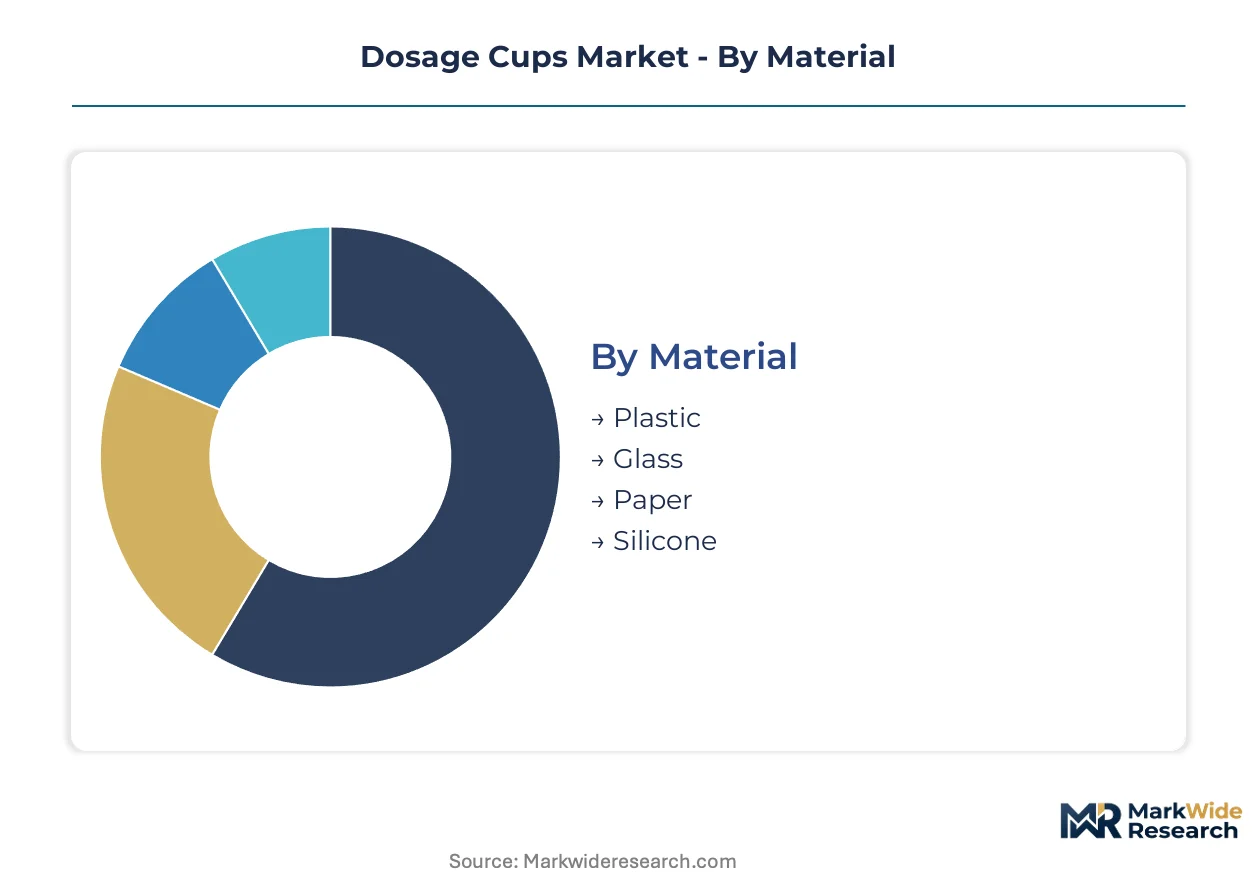
Dosage cup procurement varies sharply by clinical setting, with hospitals demanding pharmacopeial-grade calibration while retail channels prioritize cost efficiency. Material selection and dimensional precision requirements diverge across these use cases, creating distinct supplier qualification tiers.
Material:
Polypropylene dominates hospital procurement for its sterilization compatibility, while amber glass retains specialized applications where light protection commands priority.
- Plastic:Polypropylene and polystyrene formulations account for the bulk of hospital and pharmacy dispensing. Thermoforming scale economies compress unit costs for high-volume antibiotic suspensions, with United States integrated delivery networks specifying pharmacopeial-grade dimensional tolerances as baseline contract requirements.
- Glass:Amber glass dosage cups serve oncology and vitamin formulations where UV protection and chemical inertness outweigh breakage risks. EMA technical documentation mandates material biocompatibility testing beyond previous CE marking thresholds, elevating barrier-to-entry for uncertified European converters.
- Paper:Single-use biodegradable alternatives pilot in sustainability-committing health systems, though moisture resistance limitations constrain liquid medication applications.
- Silicone:Flexible molded cups address specialized pediatric and geriatric compliance needs, with softness reducing oral injury risks during self-administration.
Leading the category by volume: Plastic. Growing fastest: Silicone.
Size:
Standardization concentrates procurement around pediatric and adult antibiotic volumes, though precision dosing for concentrated therapies is gaining traction.
- 10ml:The workhorse specification for standard pediatric antibiotic suspensions. Hospital formularies specify this capacity for amoxicillin and similar common prescriptions, with FDA 21 CFR Part 211 calibration mandates expanding validation protocols across procurement teams.
- 20ml:Adult liquid medication dispensing defaults to this capacity for cough suppressants and analgesic suspensions. United States retail pharmacy chains specify direct-to-distributor fulfillment models that bypass traditional medical supply intermediaries for this high-turnover segment.
- 5ml:Concentrated pediatric therapies and geriatric micro-dosing drive precision requirements. EU MDR technical documentation and ISO 15378 certification timelines compress supplier qualification windows for this high-accuracy segment.
- 30ml:Extended-release formulations and veterinary crossover applications sustain niche demand outside standard human pharmaceutical procurement.
10ml and 20ml specifications command procurement volume. 5ml precision cups expand most quickly.
End User:
Institutional procurement consolidates around certified manufacturers, while homecare channels fragment across retail and direct-to-patient models.
- Hospitals:Integrated delivery networks standardize specifications across affiliated facilities. Machine vision systems with sub-millimeter resolution are automating dimensional inspection, with procurement teams now specifying 100% in-line verification as contract requirements.
- Pharmacies:Retail chains develop co-branded dosage cup programs for chronic disease patients, with consolidated buying by pharmacy benefit managers compressing vendor panels for over-the-counter liquid medications.
- Homecare:Discharge protocols extend calibrated dispensing to outpatient medication management. Child-resistant closure integration addresses FDA pediatric poisoning prevention guidelines.
- Laboratories:Research and quality control applications demand higher precision tolerances than clinical dispensing, with specialized calibration certificates required for analytical use.
Hospitals anchor procurement volume. Homecare channels climb the fastest.
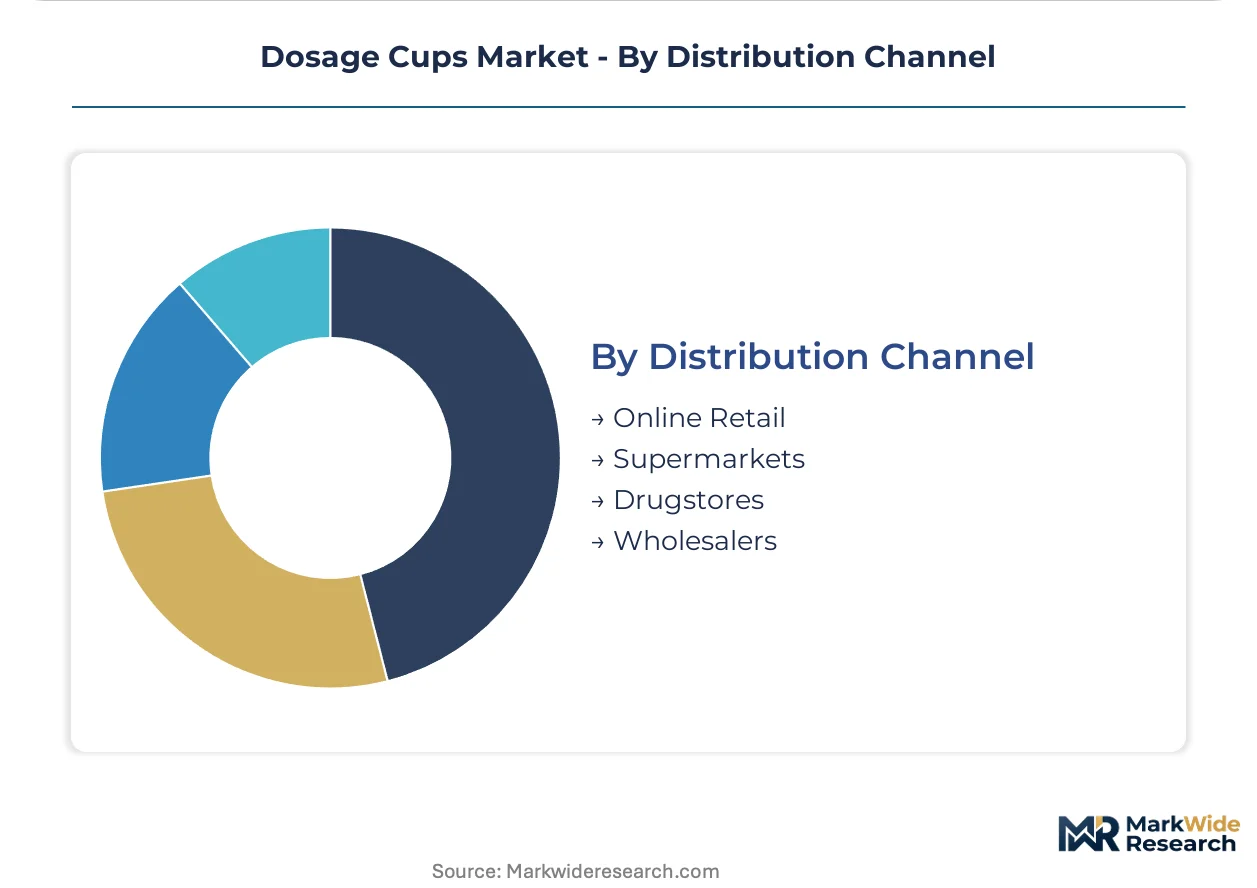
Distribution Channel:
Channel restructuring bypasses traditional intermediaries where volume scale permits direct fulfillment economics.
- Wholesalers:Medical supply distributors retain dominance in hospital procurement, with established quality management systems and regulatory dossiers qualifying vendors for institutional panels.
- Drugstores:Private-label dosage cups for pediatric cough and cold segments ship direct to distribution centers, eliminating traditional supply chain layers.
- Online Retail:E-commerce platforms serve homecare and chronic disease management segments, with patient-direct fulfillment expanding post-discharge.
- Supermarkets:Mass-market over-the-counter liquid medication bundling sustains commoditized open-stock procurement for standard household use.
Wholesalers retain institutional dominance. Online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's pharmaceutical corridor anchors dosage cup procurement volume, with integrated health systems and contract manufacturers clustering around Newark-Elizabeth port infrastructure and Princeton research zones.
United States
Integrated delivery networks in Texas and California consolidate procurement through standardized formularies. FDA 21 CFR Part 211 calibration mandates expand validation protocols across hospital systems. Chicago-area distributors maintain regional warehousing for Midwest health system contracts.
Germany
EMA technical documentation requirements compress supplier qualification timelines for amber glass and polymer dosing portfolios. EU MDR biocompatibility testing elevates barrier-to-entry for uncertified converters. Baden-Württemberg's precision molding clusters supply calibrated vessels to European hospital networks.
China
NMPA pharmaceutical packaging standards tighten material specifications for export-oriented manufacturers. Yangtze River Delta injection molders scale polypropylene production for antibiotic suspension dispensing. Shanghai's medical device free trade zone accelerates quality system certification for international procurement.
India
CDSCO pharmaceutical packaging regulations align with USP dimensional tolerance standards for export compliance. Gujarat's polymer processing corridor expands thermoforming capacity for pediatric antibiotic cups. Mumbai-Pune pharmaceutical belt drives demand for calibrated 5ml precision vessels.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains pharmacopeial alignment with EU standards. NHS procurement frameworks consolidate vendor panels around ISO 15378-certified manufacturers. Midlands packaging clusters supply calibrated dosing solutions to hospital pharmacies.
Dosage Cups Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and regulatory dossier completeness. The market structures around three tiers: multinational converters with captive resin processing, regional thermoformers serving retail pharmacy chains, and specialized glass molders for light-sensitive formulations. Consolidation pressures favor manufacturers with validated quality management systems. Two dominant competitive moves are emerging: backward integration into resin compounding to control polypropylene purity, and geographic expansion through notified body certification in multiple jurisdictions.
Within the multinational converter tier, Comar and Gerresheimer AG exemplify divergent material strategies. Comar represents North American captive resin processing capabilities. Gerresheimer AG anchors European demand through diversified polymer and glass portfolios. Berry Global occupies a position among scale-driven thermoformers competing on unit-cost economics across retail channels.
| Leading Market Players |
|---|
| Comar |
| Gerresheimer AG |
| Berry Global |
| Sonoco Products Company |
| Medline Industries |
| Origin Pharma Packaging |
| Qosina |
| AptarGroup |
| Adelphi Healthcare Packaging |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmacopeial-validated and uncertified converters manifests in both pricing power and supply chain tiering. FDA 21 CFR Part 211 and EU MDR compliance costs compress margins at commodity thermoformers while rewarding certified manufacturers with multi-year hospital contracts. This bifurcation concentrates procurement relationships around validated quality management systems and established regulatory dossiers.
Pricing Analysis
Value-based pricing anchors on ISO 15378 certification tier and machine vision verification capability. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-grade calibrated cups from retail pharmacy generics. Cost compression in polystyrene-to-polypropylene conversion programs is intensifying because integrated delivery networks demand documented calibration certificates. Retail pharmacy chains exhibit highest price sensitivity, while hospital procurement teams prioritize dimensional tolerance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast propylene monomer supply feeding North American polypropylene production. Manufacturing draws from resin compounding in the United States, thermoforming scale in China, and precision molding clusters in Germany. Tariff exposure on medical-grade polymer imports threatens cost structures for regional converters. Distribution runs through medical supply wholesalers for institutional procurement and direct-to-distributor fulfillment for retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as ISO 15378 certification timelines exclude uncertified regional converters from hospital procurement panels. Regulatory tightening forces weaker players toward acquisition or exit.
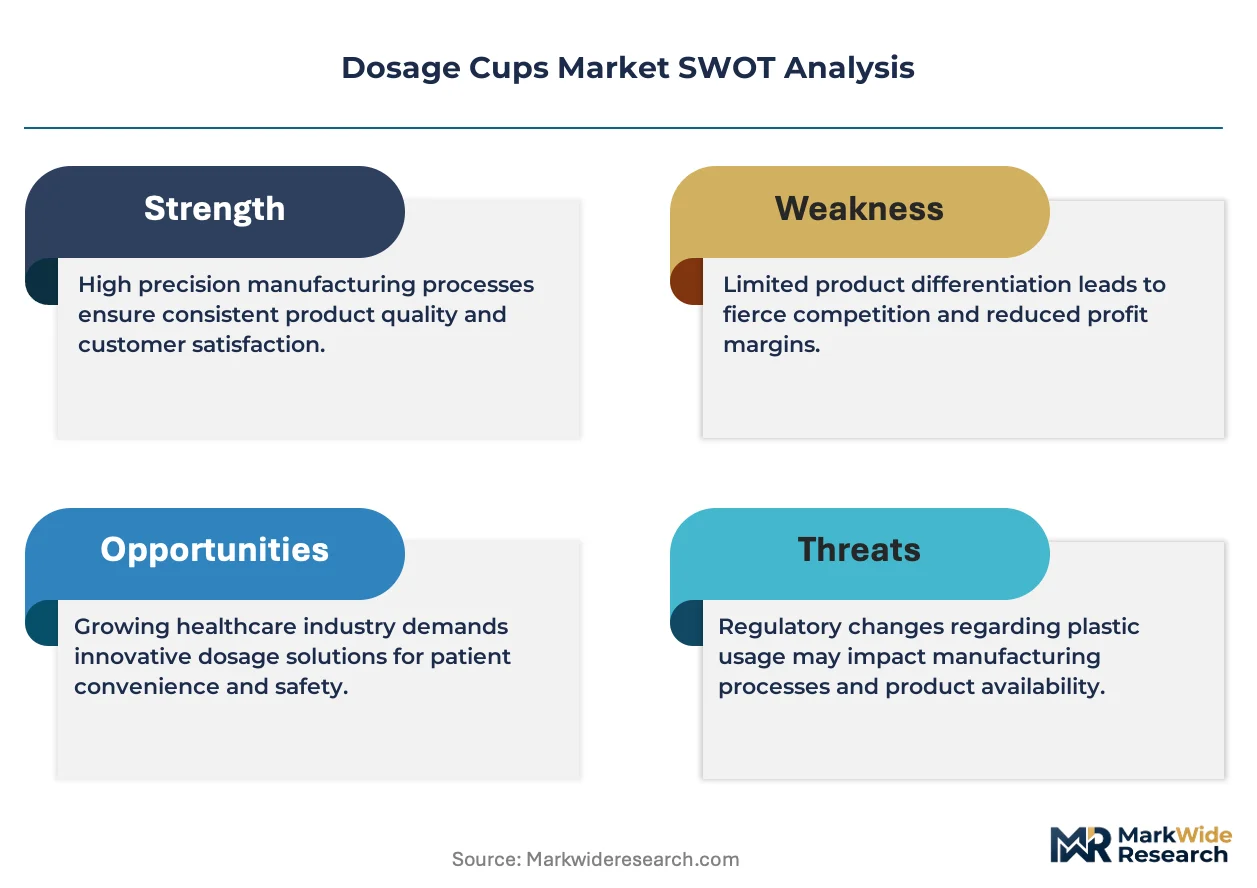
For Market Incumbents: Acquire machine vision calibration capabilities and notified body certification dossiers to defend against emerging Asian thermoformers. Backward integration into captive resin processing controls polypropylene purity and insulates margin compression from propylene monomer volatility. Expand capacity in Baden-Württemberg precision molding clusters to anchor European hospital network contracts. For New Entrants and Emerging Players: The price-point gap between premium pharmacopeial-grade and economy retail pharmacy tiers creates entry space for mid-market certified converters. Target homecare channels and online retail fulfillment models where procurement panels remain fragmented. Pursue mass-balance certified bio-based polypropylene pilot programs to secure preferred supplier status with sustainability-committing health systems in California and Washington. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap thermoformers possessing ISO 15378 certification and established hospital procurement relationships given EU MDR technical documentation requirements. Long-term viability hinges on regulatory dossier completeness rather than unit-cost scale. Watch for state-level pharmaceutical waste regulations mandating renewable content as an inflection signal for bio-based material transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene purity control insulates margin pressure from Gulf Coast propylene volatility. |
| Machine Vision System Deployment | Sub-millimeter dimensional verification satisfies hospital procurement requirements for 100% in-line inspection. |
| Notified Body Certification Expansion | EU MDR technical documentation compliance opens European hospital tenders to non-European manufacturers. |
| Child-Resistant Closure Integration | FDA pediatric poisoning prevention guidelines create design white space beyond standard open-vessel formats. |
| Bio-Based Polypropylene Pilot Programs | Mass-balance certified resins secure preferred supplier status with sustainability-committing integrated delivery networks. |
Methodological Framework
Independent corroboration across pharmaceutical packaging executives, hospital procurement managers, regulatory affairs specialists, and thermoforming operations directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EMA submission databases, USP packaging standards documentation, and hospital GPO contract records. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across material, size, and end-use segments.
Rate-of-change decomposition isolates volume drivers from price-mix effects across the projection horizon. Segmentation modeling incorporates material grade tier, end-use clinical setting, calibration precision level, and regional regulatory cluster. CAGRs derive from iterative convergence between supply-side capacity buildouts and demand-side procurement contract visibility. Forecast inputs include resin price indices, hospital consolidation trajectories, and certification timeline data from notified bodies.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time contract renewal data introduce uncertainty bands around vendor share projections. Forecasts reflect documented assumptions regarding FDA enforcement continuity and EU MDR implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
VCI Bags Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Can Holders Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Telescope Box Market
Packaging Containers
Correx Trays Market
Packaging Containers
Portion Packs Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Plasma Bottle Market