
 Glass Bottles and Jars Decoration Market | 2026-2036
Glass Bottles and Jars Decoration Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Bottles and Jars Decoration Market Foresight
The EU Green Deal is rebalancing procurement priorities across European cosmetics and beverage packaging supply chains, forcing converters to certify recycled glass content in decorated formats. Gerresheimer leverages its pharmaceutical glass expertise to sustain high-margin decorated vial programs for injectable cosmetics. Owens-Illinois anchors North American food and beverage demand through scaled screen-printing operations on returnable bottles. Saverglass differentiates through premium etched and painted finishes for spirits and wine clients in France and export markets.
Glass bottles and jars decoration encompasses surface enhancement processes—screen printing, acid etching, ceramic painting, and applied labels—performed on soda-lime or borosilicate containers typically ranging from 50 ml to 5 liters, serving brand differentiation and regulatory labeling requirements. Screen printing dominates volume among decoration types due to its durability on curved substrates and compatibility with high-speed filling lines. The cosmetics end-user segment commands the richest margin pools as fragrance and skincare houses commission limited-edition painted and etched designs. Retail packaging applications absorb the largest share of unit volume, though gift packaging formats generate superior per-unit value through multi-process decoration.
The European Chemicals Agency enforces REACH compliance on decorative inks and coatings, while the EU F-Gas Regulation shapes energy-intensive furnace operations that supply decorated container feedstock. FDA labeling rules in the United States mandate specific durability standards for screen-printed pharmaceutical and food-contact glass. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and emerging state-level recycled-content mandates in California and New York to anticipate compliance-driven sourcing shifts.
Market Dynamics
The EU Green Deal's circularity mandates are compressing virgin glass sourcing and forcing converters to reengineer decoration chemistries around certified recycled content, rewiring procurement relationships across cosmetics and beverage supply chains.
Growth Catalysts
- Premium cosmetics expansion:Fragrance and skincare houses in Western Europe commission limited-edition painted and etched designs, expanding per-unit decoration spend.
- EU F-Gas Regulation:Energy-intensive furnace operations face tightening emissions caps, accelerating investment in oxy-fuel and electric melting technologies that supply decorated container feedstock.
- Champagne-Ardenne cluster concentration:France's glassmaking hub anchors specialized etching and ceramic painting capabilities for spirits and wine export markets.
Market Restraints
- Recycled cullet quality variance:Post-consumer glass feedstock exhibits color inconsistency and contamination, degrading optical clarity required for premium decorated finishes.
- ECHA REACH compliance costs:Decorative inks and coatings face escalating registration and substitution requirements, extending formulation approval timelines.
- Aluminum and PET substitution:Lightweight beverage cans and rPET bottles capture share in mass-market segments where decoration durability matters less.
Strategic Opportunities
- California recycled-content mandates:Emerging state-level requirements create first-mover advantage for converters certifying post-consumer glass in decorated formats.
- Digital inkjet convergence:Hybrid screen-digital systems enable short-run customization for craft spirits and seasonal cosmetics launches.
- Extended producer responsibility frameworks:EU packaging levy structures reward decoration formats that preserve container recyclability, favoring laser etching over applied labels.
Industry Challenges
- Specialized technician scarcity:Acid etching and ceramic firing require craft skills with limited training pipeline replacement.
- Multi-process integration complexity:Sequencing screen printing, firing, and inspection on high-speed lines demands precision timing engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Bottles and Jars Decoration Market |
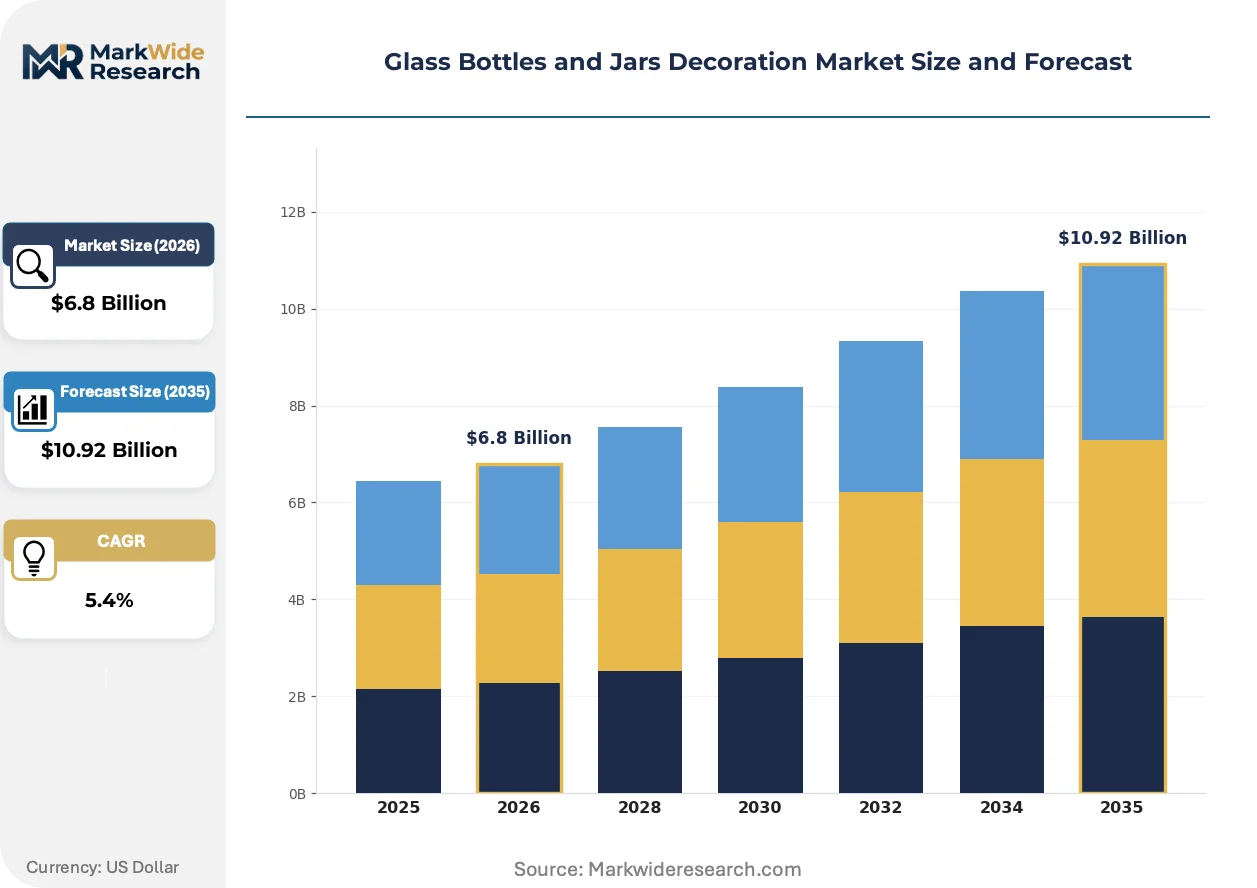
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Decoration Type: Screen Printing, Labels, Etching, Painting End User: Food & Beverage, Cosmetics, Pharmaceuticals, Home Decor Material Type: Glass, Plastic, Metal, Wood Application: Event Decoration, Retail Packaging, Gift Packaging, Promotional Items |
| Companies Covered | Crown Holdings, Gerresheimer, Owens-Illinois, Piramal Glass, Saverglass, Ardagh Group, Amcor, Nampak, Verallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Bottles and Jars Decoration Market Shifts & Advancements
Decoration technology is pivoting from volume-standardized output toward agile, short-run customization while regulatory chemistry constraints and buyer sustainability mandates reshape process selection.
UV-curable inkjet printing is absorbing share in mid-volume spirits and cosmetics applications where design refresh cycles compress. Premium brands in France and Italy adopt hybrid digital-screen lines for seasonal limited editions. The technology is absorbing decoration volume that previously required dedicated screen cylinders, collapsing minimum order quantities from tens of thousands to hundreds of units.
REACH authorization lists are expanding restricted substances in decorative coatings, compelling reformulation around bio-based binders and mineral pigments. The European Chemicals Agency's SVHC candidate list now captures several legacy ceramic colorants. Cosmetics packaging converters face accelerated substitution timelines, with fragrance houses demanding third-party certification of ink compliance.
Direct brand-to-converter relationships are displacing traditional trading house intermediaries in wine and spirits procurement. Large maisons in Champagne-Ardenne and Cognac now specify decoration protocols directly, unbundling design specification from container supply. This pattern concentrates most visibly in French luxury spirits, where heritage glassworks negotiate multi-year decoration partnerships bypassing legacy distributors.
Glass Bottles and Jars Decoration Market Segmentation
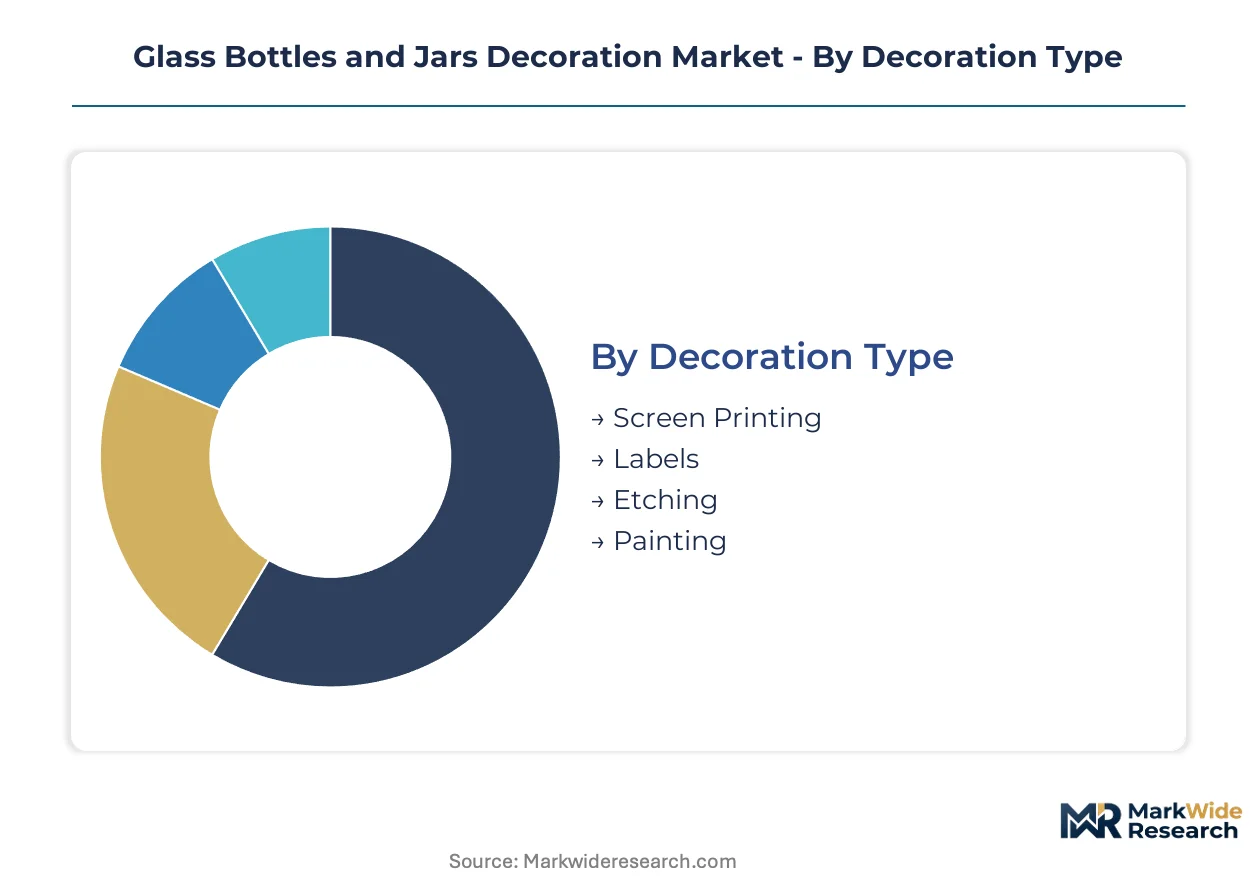
Decoration procurement decisions in this market hinge on durability requirements, regulatory compliance burdens, and the technical constraints of curved substrates. Each segmentation dimension reveals distinct margin structures and capability dependencies that reshape converter specialization.
Decoration Type:
Supply concentration in screen printing equipment and consumables anchors procurement economics, while emerging digital technologies fragment the vendor base.
- Screen Printing:Ceramic and organic inks cured through thermal or UV processes deliver abrasion resistance essential for returnable beverage bottles. Demand concentrates in Germany's Rhineland bottling corridor, where high-speed rotary presses serve carbonated soft drink and mineral water clients facing strict refill-cycle durability standards.
- Etching:Acid-based surface frosting and laser ablation create tactile premium finishes without applied materials that compromise recycling streams. Champagne-Ardenne glassworks in France anchor specialized etching capacity for spirits export markets, though REACH restrictions on hydrofluoric acid formulations extend approval timelines for new chemistry introductions.
- Labels:Pressure-sensitive and shrink-sleeve formats enable multi-language regulatory compliance with lower capital intensity than direct decoration.
- Painting:Spray-applied ceramic and organic coatings support complex color gradients and metallic effects for limited-edition cosmetics releases.
Today's leader: Screen Printing. Tomorrow's challenger: Etching.
End User:
Margin stratification across end-use segments follows regulatory burden intensity and per-unit value concentration.
- Cosmetics:Fragrance houses and skincare brands commission multi-process decoration combining etching, painting, and metallic finishing for shelf differentiation. France and Italy dominate procurement, where heritage maisons specify direct converter relationships bypassing traditional distributors.
- Food & Beverage:Returnable bottle programs in Germany and refillable wine formats in Spain drive volume demand for screen-printed durability.
- Pharmaceuticals:Injectable vials and oral dose bottles require FDA-validated ink systems with documented extractables profiles.
- Home Decor:Decorative storage and candle vessels absorb mid-volume production with shorter run lengths and lower specification rigor.
Premium-mid-economy pricing differentiation separates cosmetics from foodservice applications.
Material Type:
Substrate selection determines decoration chemistry compatibility and furnace energy intensity under tightening emissions frameworks.
- Glass:Soda-lime and borosilicate compositions dominate, with decoration processes calibrated to thermal expansion coefficients and surface energy profiles.
- Plastic:PET and HDPE substrates require plasma pretreatment and specialized ink adhesion promoters absent from glass protocols.
- Metal:Aluminum beverage cans and tinplate containers support comparable printing technologies with modified curing parameters.
- Wood:Niche applications in gift packaging demand moisture-barrier coatings prior to decoration application.
Glass commands the steepest expansion trajectory as EU circularity mandates compress virgin plastic sourcing.
Application:
Run length economics and customization depth vary sharply across use-case contexts.
- Retail Packaging:High-volume standardized formats with extended design lifecycles favor amortized screen cylinder investments.
- Gift Packaging:Multi-process decoration combining etching, painting, and applied elements generates superior per-unit value through seasonal and occasion-based customization.
- Event Decoration:Short-run digital production accommodates personalized messaging for corporate and wedding markets.
- Promotional Items:Branded merchandise programs balance unit cost with visual impact across limited campaign durations.
Retail Packaging absorbs volume concentration. Gift Packaging captures value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bohemian glassmaking traditions established Czechia as the historical epicenter of decorative crystal production, with artisan techniques migrating westward to France and Germany during the nineteenth century. This heritage infrastructure now supports industrial-scale decorated container manufacturing across Central and Western Europe.
France
Champagne-Ardenne hosts the densest concentration of specialized etching and ceramic painting capacity for luxury spirits export markets. The EU Green Deal's circularity mandates compel converters near Reims to certify recycled cullet content in decorated formats. Verallia operates integrated furnace and decoration facilities serving heritage maisons in Cognac and Épernay.
Germany
The Rhineland bottling corridor sustains high-volume rotary screen printing for returnable mineral water and carbonated soft drink programs. The EU F-Gas Regulation accelerates furnace electrification investments at sites supplying decorated feedstock. Gerresheimer leverages pharmaceutical glass expertise from Düsseldorf-area facilities to sustain high-margin decorated vial production.
United States
California's emerging recycled-content mandates create compliance-driven demand for certified post-consumer glass decoration. FDA labeling rules mandate specific durability standards for screen-printed pharmaceutical and food-contact containers. Owens-Illinois anchors North American volume through scaled operations in the Midwest and Pacific states.
Italy
Fragrance houses in Lombardy and Emilia-Romagna commission multi-process decoration combining etching, painting, and metallic finishing for shelf differentiation. ECHA REACH compliance costs escalate registration requirements for decorative inks entering cosmetics packaging. Specialized glassworks near Venice preserve craft firing techniques for limited-edition releases.
China
Yangtze River Delta converters supply mid-volume decorated containers for domestic cosmetics and export beverage markets. The country's dual carbon goals tighten emissions standards for energy-intensive furnace operations feeding decoration lines. Piramal Glass maintains pharmaceutical-grade decoration capabilities for injectable cosmetics destined for European markets.
Glass Bottles and Jars Decoration Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated glass manufacturers control furnace feedstock and specialized decorators capture premium finishing margins. The vendor base stratifies into three tiers: multinational packaging conglomerates with captive decoration assets, regional specialists concentrated in European wine and spirits clusters, and independent decorators serving short-run cosmetics programs. Dominant competitive moves include backward integration into recycled cullet sourcing and technology licensing partnerships for hybrid digital-screen systems.
Among integrated packaging conglomerates, Crown Holdings and Ardagh Group exemplify scale-driven archetypes with furnace-to-decoration vertical control. Saverglass occupies a distinct position within the premium-tier specialist segment, anchoring heritage etching and ceramic painting capabilities for French luxury spirits. These three represent contrasting strategic postures: global volume leverage versus regional craft specialization.
| Leading Market Players |
|---|
| Crown Holdings |
| Gerresheimer |
| Owens-Illinois |
| Piramal Glass |
| Saverglass |
| Ardagh Group |
| Amcor |
| Nampak |
| Verallia |
| Others |
Supply & Pricing Matrix
The EU Green Deal's circularity mandates now gate qualified supply access and premium-tier pricing power, as converters certifying post-consumer cullet content command pricing premiums from cosmetics and beverage brands while uncertified competitors face margin compression from compliance-driven procurement shifts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage maisons commissioning multi-process etching and ceramic painting from mass-market beverage clients sourcing screen-printed durability. Price differentiation rests on certification grade—REACH-compliant ink systems and recycled content verification—and volume scale, with short-run digital customization commanding per-unit premiums. Cost compression in the standard tier is intensifying because aluminum and rPET substitutes capture share in refill-cycle applications. Mass-market beverage brands exhibit highest price sensitivity, while fragrance houses in France and Italy demonstrate lowest sensitivity given shelf differentiation imperatives.
Supply Chain Analysis
Single-source vulnerability sits with France's Champagne-Ardenne cluster, where specialized acid etching and ceramic firing capabilities for luxury spirits concentrate among heritage glassworks. Feedstock draws from Germany's Rhineland furnace corridor and Italy's Lombardy decoration facilities, with ceramic colorants and UV-curable inks sourced from concentrated chemical suppliers. Tariff exposure on REACH-compliant decorative coatings from non-EU sources threatens formulation cost stability. Distribution runs through direct brand-to-converter relationships displacing traditional trading house intermediaries in wine and spirits procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, where the EU F-Gas Regulation's tightening emissions caps on furnace operations continuously revalue efficient feedstock supply and premium decoration capabilities.
For Market Incumbents: Deepen backward integration into certified recycled cullet sourcing to defend margin position against REACH compliance cost escalation and aluminum substitution threats. Anchor capacity expansion in France and Germany to capture proximity premiums from Champagne-Ardenne maisons and Rhineland bottling corridors. Prioritize hybrid digital-screen system investments to collapse minimum order quantities and retain craft spirits clients. For New Entrants and Emerging Players: Direct-to-brand digital platforms enable short-run customization entry without amortized screen cylinder infrastructure. Target California's emerging recycled-content mandate compliance market, where certified post-consumer glass decoration faces limited qualified supply. Pursue craft spirits and seasonal cosmetics launches as the most penetrable segment, leveraging agile production against incumbent volume-scale rigidities. For Investors and Strategic Acquirers: Roll-up economics work for regional decoration specialists because ECHA REACH compliance costs and specialized technician scarcity create defensive moats around certified facilities. Five-to-ten year viability favors converters with furnace-adjacent locations and direct brand relationships bypassing distributors. Monitor California and New York state-level recycled-content mandate progression as the critical inflection signal for North American compliance-driven demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Cullet Sourcing | Secures qualified feedstock under EU Green Deal circularity mandates while capturing premium-tier pricing access. |
| Hybrid Digital-Screen Technology Licensing | Enables short-run agility for Saverglass and Verallia to serve craft spirits limited editions without volume penalties. |
| REACH-Compliant Ink System Certification | Accelerates formulation approval timelines for decorative coatings facing ECHA SVHC substitution requirements. |
| Direct Brand Partnership Structuring | Bypasses legacy trading house intermediaries in French luxury spirits procurement, concentrating margin with converters. |
| Oxy-Fuel and Electric Melting Conversion | Aligns furnace operations with EU F-Gas Regulation emissions caps supplying decorated container feedstock. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with furnace operations managers, decoration line engineers, cosmetics packaging procurement leads, and regulatory compliance officers with secondary validation from ECHA REACH registration databases, EU customs trade flows, and SEC filings of listed packaging conglomerates. Bottom-up volume modeling across screen printing, etching, painting, and label decoration types triangulated against top-down macroeconomic indicators.
Historical reference periods anchored the projection horizon, with CAGRs derived from segmented growth trajectories across decoration type, end-user industry, material substrate, and application format. The analytical framework incorporated furnace energy intensity parameters under EU F-Gas Regulation scenarios, recycled cullet quality variance assumptions, and digital inkjet adoption curves in mid-volume spirits and cosmetics segments.
The model assumes a particular technology adoption path; alternative pathways for electric melting furnace penetration or laser etching substitution would alter the outlook. Forecasts reflect assumptions regarding REACH authorization timeline progression, state-level mandate adoption in North America, and aluminum substitution elasticity in mass-market beverage applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Austria Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Turkey Container Glass Market