
 North America Pharmaceutical Contract Packaging Market | 2026-2036
North America Pharmaceutical Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Contract Packaging Market Intelligence
The United States is fragmenting its pharmaceutical contract packaging capacity across multiple state-level manufacturing corridors. Amcor PLC leverages its flexible packaging technology leadership to anchor large-volume oral solid dose programs for North American pharma clients. PCI Pharma Services competes through specialized cold-chain infrastructure for biologics, while WestRock Company sustains dominance in printed folding carton supply to major branded drug manufacturers.
North America pharmaceutical contract packaging encompasses the outsourced assembly, labeling, and secondary packaging of prescription drugs, biologics, and over-the-counter products under contract to pharmaceutical sponsors, typically performed in FDA-registered facilities with validated lines for serialization, aggregation, and tamper-evident sealing. Blister packs remain the dominant product type due to their child-resistance capabilities and compliance-prompting format for chronic medications, though flexible packaging formats are gaining share in biologics and injectable portfolios where pouch-based sterile barriers reduce material waste. Direct shipping delivery modes capture the largest volume as manufacturers seek to bypass distribution center handling, while digital packaging—incorporating QR-linked patient adherence tools—represents the fastest-growing delivery mode segment as brands differentiate through connected health integrations.
FDA Current Good Manufacturing Practice regulations, USP <660> and <661> container closure standards, and Drug Supply Chain Security Act serialization requirements collectively elevate barrier-to-entry for new contract packaging entrants while driving incumbent facility reinvestment. Health Canada and PMRA standards in Canada create additional compliance layers for cross-border packaging programs serving dual-market products. Stakeholders must monitor evolving EPA guidelines for pharmaceutical packaging waste and state-level extended producer responsibility laws that will reshape material selection and recovery economics across the region.
Market Dynamics
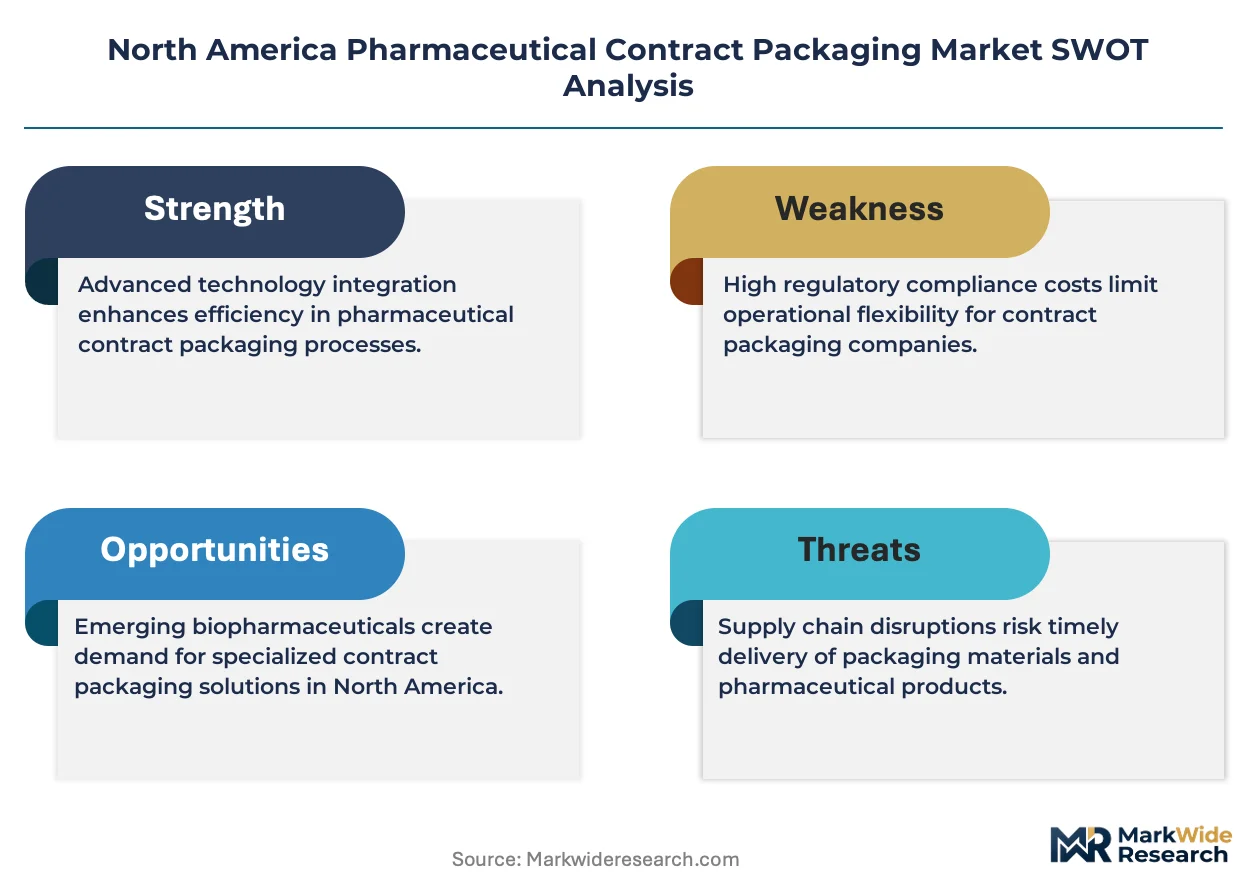
FDA serialization mandates and USP container closure standards are compressing vendor timelines while forcing incumbent contract packagers to reinvest in validated line infrastructure across New Jersey and Massachusetts manufacturing clusters.
Growth Catalysts
- Biologics cold-chain expansion:Biotech sponsors in Massachusetts and California are outsourcing temperature-sensitive packaging for monoclonal antibodies and cell therapies, requiring specialized infrastructure that contract providers are racing to install.
- Drug Supply Chain Security Act compliance:FDA aggregation and serialization requirements are compelling mid-sized pharma sponsors to abandon in-house packaging lines in favor of contract partners with pre-validated track-and-trace capabilities.
- Flexible barrier adoption:Pouch-based sterile formats are displacing rigid containers for injectable portfolios, reducing material waste while meeting USP <661> plastic packaging standards for biologics stability.
Market Restraints
- Specialized equipment capex concentration:Cold-chain biologics lines require capital outlays that concentrate viable supply among large integrated providers, squeezing regional mid-cap competitors in the Northeast.
- Resin and aluminum input volatility:Blister pack substrates face price pressure from pharmaceutical-grade PVC and foil supply constraints, compressing margin structures for oral solid dose contract programs.
- Cross-border regulatory friction:Health Canada PMRA serialization standards diverge from FDA DSCSA timelines, complicating unified packaging runs for dual-market products manufactured in Buffalo or Detroit corridors.
Strategic Opportunities
- Digital packaging patient adherence tools:QR-linked medication reminders and connected health integrations represent unpenetrated white space for branded sponsors seeking differentiation in chronic disease categories.
- Mexico nearshoring expansion:Baja California and Querétaro pharmaceutical manufacturing zones offer tariff-advantaged capacity for US sponsors seeking geographic diversification beyond domestic Northeast clusters.
- State extended producer responsibility laws:California and New York packaging waste regulations are creating first-mover advantages for contract providers with certified recyclable barrier technologies and closed-loop recovery partnerships.
Industry Challenges
- Serialized line validation timelines:FDA 21 CFR Part 11 electronic records compliance for new aggregation equipment extends facility qualification periods, delaying program onboarding for sponsor clients.
- Biologics handling certification gaps:Cold-chain technician training and GDP (Good Distribution Practice) credentialing lag demand in secondary markets, constraining capacity expansion outside established Northeast and California hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Contract Packaging Market |
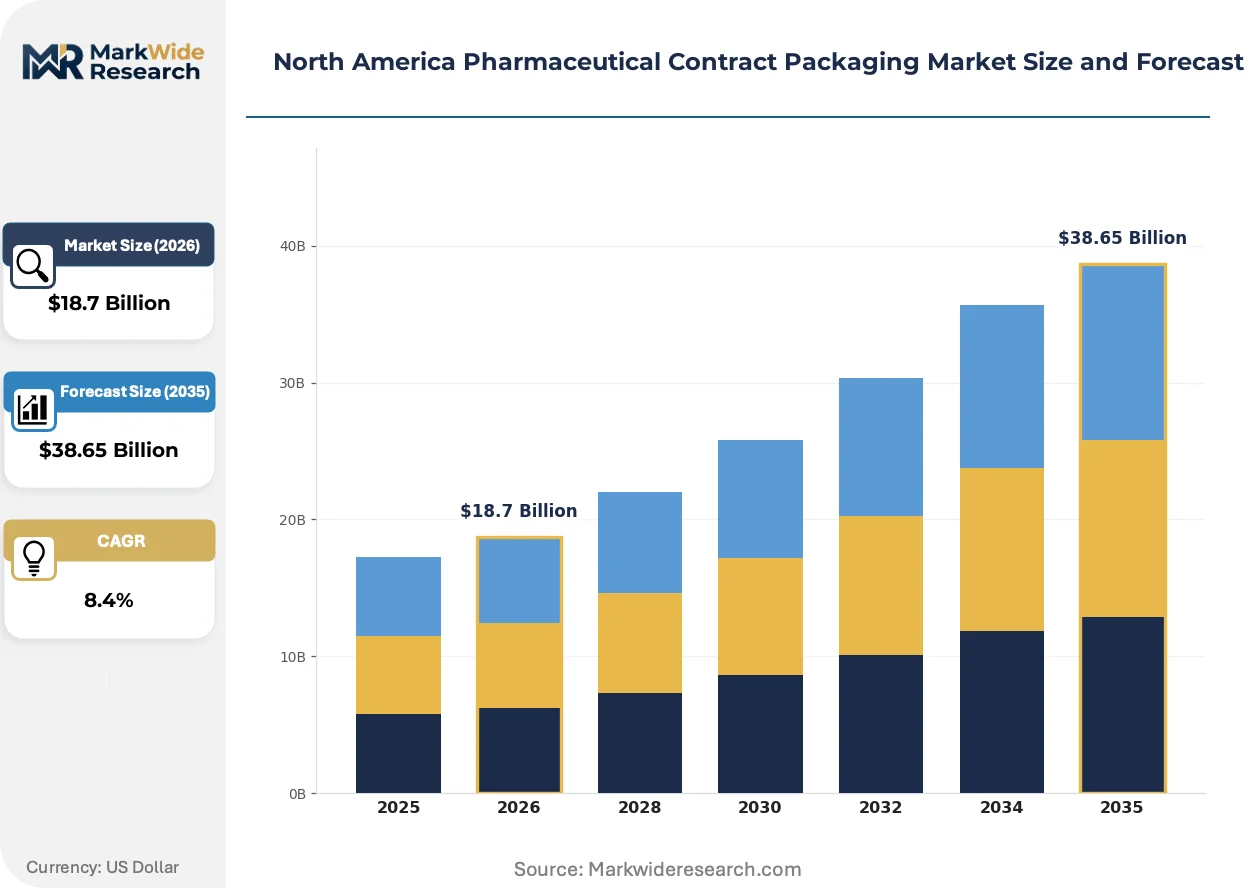
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Labels, Pouches Delivery Mode: Direct Shipping, Third-Party Logistics, On-Site Packaging, Digital Packaging End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Over-the-Counter Providers Packaging Type: Vacuum Sealed, Eco-Friendly, Rigid Containers, Flexible Packaging |
| Companies Covered | Amcor PLC, WestRock Company, PCI Pharma Services, Aphena Pharma Solutions, Patheon, Baxter BioPharma Solutions, Celestica, Inc., Thermo-Pak Co., Inc., Sharp Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Contract Packaging Market Strategic Shifts & Innovations
Contract packaging operations across the United States and Canada are converging on three structural shifts: connected packaging technologies, evolving serialization architectures, and compressed sponsor procurement cycles that favor integrated service providers over single-capability vendors.
Near-field communication (NFC) tags embedded in folding cartons and blister lidding are digitizing patient engagement workflows for chronic medication categories. Branded pharmaceutical sponsors in diabetes and cardiovascular therapeutic areas are piloting NFC-enabled adherence monitoring with contract partners in New Jersey. This connectivity layer is digitizing the traditional patient-package relationship, creating data assets that sponsors monetize through payer contracting.
FDA DSCSA enhanced drug distribution security provisions are mandating unit-level traceability for all prescription products by November 2024, forcing contract packagers to complete aggregation infrastructure upgrades. The regulation is compressing implementation timelines for oral solid dose and injectable lines alike. Small-molecule generic manufacturers with legacy packaging assets are accelerating outsourcing decisions to avoid compliance penalties.
Sponsor procurement of packaging services is consolidating under enterprise agreements that bundle secondary packaging with serialization, stability testing, and distribution. Biotech venture-backed sponsors in Boston and San Francisco are displacing transactional vendor relationships with multi-year platform contracts. This pattern is most visible in Phase III commercial readiness programs where timing risk tolerance has collapsed.
North America Pharmaceutical Contract Packaging Market Segmentation
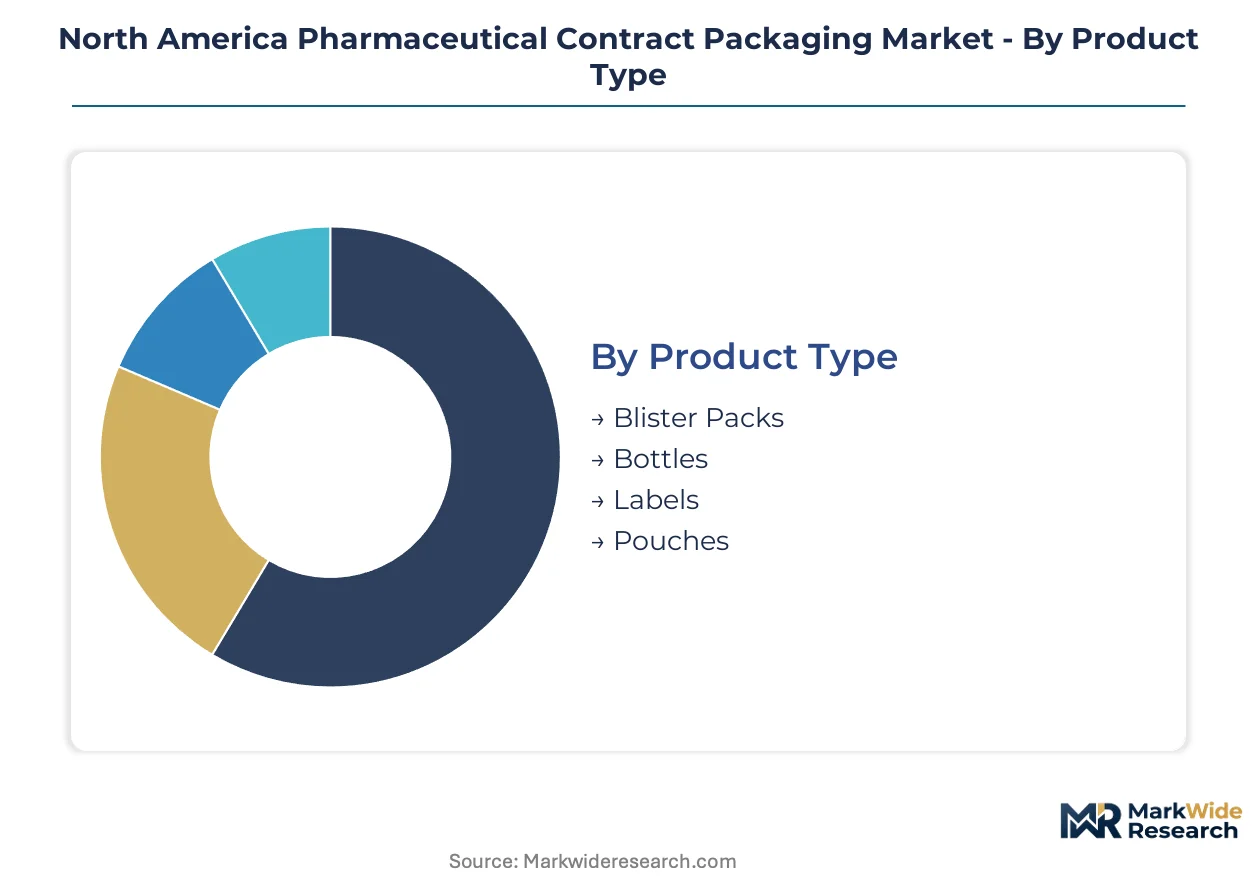
Segmentation in pharmaceutical contract packaging reveals how technical specifications, regulatory pathways, and sponsor risk tolerance stratify procurement decisions across North America. Contract packagers configure facility investments around these divisions, with cycle times and validation burdens varying sharply between segments.
Product Type:
Blister packs turn over fastest in high-volume oral solid dose programs, while pouches require longer validation cycles for sterile barrier qualification.
- Blister Packs:Thermoformed PVC or aluminum-barrier cavities with push-through or peel-open lidding dominate chronic medication compliance packaging. Demand concentrates in New Jersey manufacturing corridors where FDA-registered lines service large branded sponsors requiring child-resistant senior-friendly formats.
- Pouches:Multi-layer flexible sterile barriers with peelable seals are displacing rigid formats for biologics stability. Massachusetts biotech clusters drive adoption where pouch-based formats reduce material waste while meeting USP 661 plastic packaging standards for monoclonal antibodies.
- Bottles:HDPE or PET containers with induction-sealed closures remain standard for high-count oral solid prescriptions.
- Labels:Pressure-sensitive or booklet formats incorporating serialization codes and tamper-evident features.
Blister packs dominate installed base. Pouches are where expansion concentrates.
Delivery Mode:
Cost tiers separate capital-light digital integrations from infrastructure-heavy physical distribution models.
- Direct Shipping:Finished packaged goods bypass distributor handling through validated cold-chain or ambient lanes from contract packager to pharmacy or patient. Sponsors in California and Texas biotech corridors favor this mode to reduce touchpoints and DSCSA aggregation complexity.
- Digital Packaging:NFC-enabled cartons and QR-linked blister lidding embed patient adherence tools and authentication features. Branded diabetes and cardiovascular sponsors in the Northeast pilot these connected formats for payer differentiation and real-world evidence generation.
- Third-Party Logistics:Outsourced warehousing and distribution through specialized pharmaceutical 3PL networks.
- On-Site Packaging:Contract packager personnel and equipment deployed at sponsor manufacturing facilities.
Direct Shipping anchors volume economics. Digital Packaging is climbing the fastest.
End User:
Customer type determines contract structure, with biotech venture-backed sponsors demanding platform flexibility that pharmaceutical majors trade for scale pricing.
- Pharmaceutical Companies:Large branded and generic manufacturers outsourcing serialization-compliant secondary packaging for established portfolios. These sponsors concentrate volume in New Jersey and Puerto Rico corridors where FDA inspection history supports abbreviated vendor qualification.
- Biotech Firms:Venture-backed developers of monoclonal antibodies, cell therapies, and gene therapies requiring cold-chain infrastructure and rapid scale-up flexibility. Boston and San Francisco clusters drive demand for multi-year platform contracts covering clinical through commercial phases.
- Contract Manufacturers:CDMOs bundling packaging with API synthesis or fill-finish services.
- Over-the-Counter Providers:Consumer health brands requiring retail-ready merchandising formats.
Pharmaceutical Companies anchor contract value. Biotech Firms are gaining share fastest.
Packaging Type:
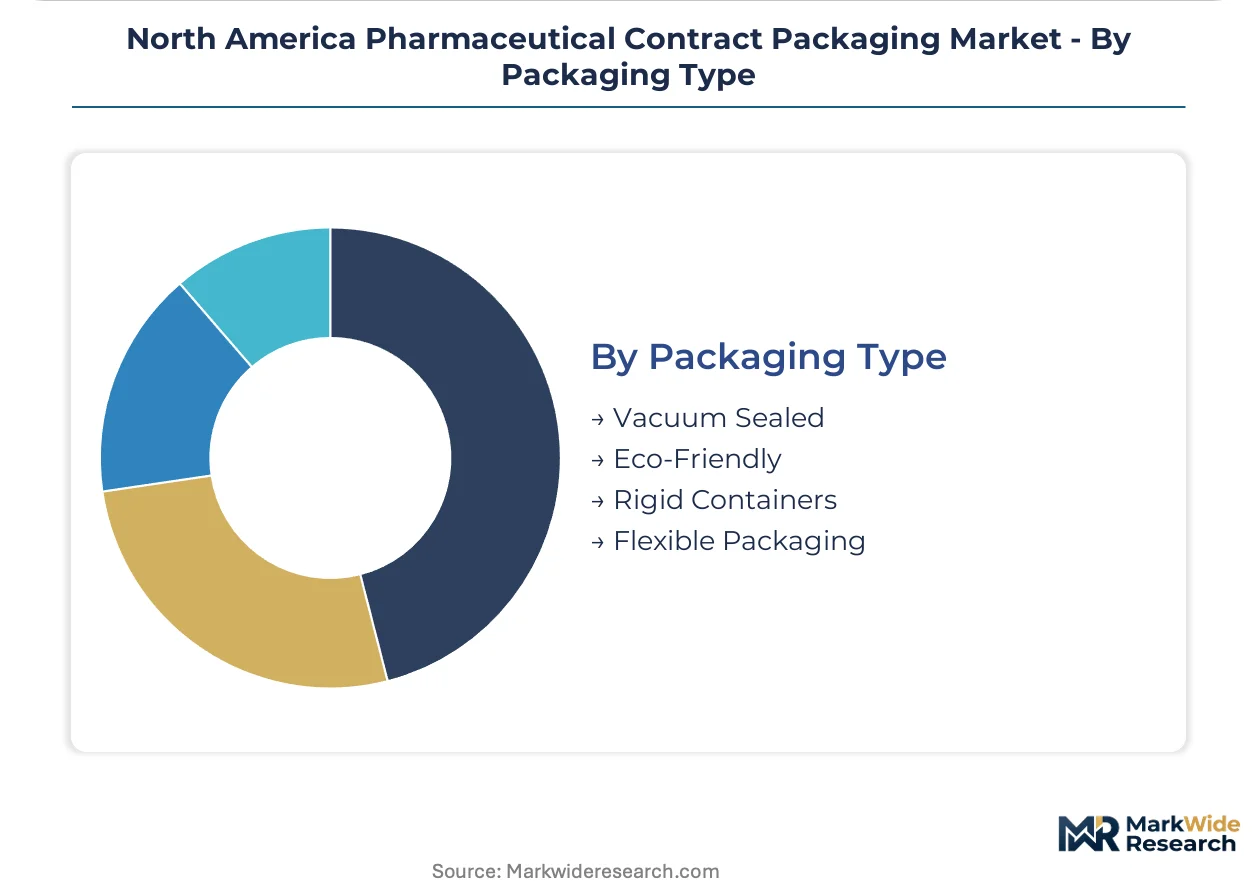
Margin structures diverge between commodity rigid formats and certified sustainable barriers commanding sustainability premiums.
- Flexible Packaging:Multi-layer films and laminates offering sterile barriers with reduced material mass versus rigid alternatives. Demand concentrates in California biologics manufacturing where sponsors face state extended producer responsibility mandates.
- Eco-Friendly:Recyclable mono-material barriers, bio-based films, and certified post-consumer content meeting California and New York packaging waste regulations. Early-mover contract packagers with closed-loop recovery partnerships capture sustainability-driven sponsor procurement.
- Vacuum Sealed:Modified atmosphere packaging for oxygen-sensitive APIs and probiotic formulations.
- Rigid Containers:Glass vials, pre-filled syringes, and injection-molded plastic bottles for standard stability requirements.
Flexible Packaging leads technology investment. Eco-Friendly is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and USP container closure standards anchor United States pharmaceutical contract packaging demand, with compliance requirements cascading across Canadian and Mexican manufacturing corridors serving North American sponsors.
United States
New Jersey and Massachusetts pharmaceutical manufacturing clusters drive contract packaging volume for oral solid dose and biologics programs. FDA Drug Supply Chain Security Act aggregation requirements compress vendor qualification timelines for sponsors seeking pre-validated track-and-trace capabilities. Boston biotech sponsors outsource cold-chain packaging for monoclonal antibodies to specialized providers with GDP-certified infrastructure.
Canada
Health Canada PMRA serialization standards create compliance layers for dual-market products manufactured in cross-border Buffalo and Detroit corridors. Ontario pharmaceutical packaging facilities service US sponsors seeking geographic diversification while maintaining FDA-registered quality systems. Toronto-area contract packagers invest in aggregation line upgrades to bridge FDA DSCSA and PMRA traceability timelines.
Mexico
Baja California and Querétaro pharmaceutical manufacturing zones offer tariff-advantaged capacity for US sponsors nearshoring beyond domestic Northeast clusters. Mexican contract packaging facilities leverage USMCA trade provisions to serve California and Texas biotech sponsors with reduced customs friction. Monterrey corridor providers expand sterile barrier capabilities for injectable portfolios requiring USP 661 compliance.
North America Pharmaceutical Contract Packaging Market Key Industry Players
Integrated packaging conglomerates and specialized cold-chain service providers split the North America pharmaceutical contract packaging market across capability tiers. Large multinational material science companies anchor high-volume oral solid dose programs through flexible barrier technologies. Mid-cap regional specialists compete on biologics handling certifications and rapid scale-up flexibility for venture-backed sponsors. Competitive moves concentrate on serialization infrastructure partnerships and sustainable material certification programs.
Within the integrated packaging tier, Amcor PLC and WestRock Company exemplify scale-driven archetypes with material science foundations spanning flexible films and printed folding cartons. PCI Pharma Services occupies a specialized position emphasizing cold-chain infrastructure for temperature-sensitive biologics. These three entities represent contrasting strategic postures: material-led vertical integration versus service-led clinical-to-commercial platform models.
| Leading Market Players |
|---|
| Amcor PLC |
| WestRock Company |
| PCI Pharma Services |
| Aphena Pharma Solutions |
| Patheon |
| Baxter BioPharma Solutions |
| Celestica, Inc. |
| Thermo-Pak Co., Inc. |
| Sharp Packaging |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade PVC and aluminum foil supply concentration in China and Germany directly determines where margin pools accumulate for North American contract packagers, with resin price volatility compressing oral solid dose economics while sterile barrier laminations command premiums downstream.
Pricing Analysis
Price spreads between New Jersey and Baja California manufacturing corridors reflect a three-tier pricing structure across premium, standard, and economy levels. Cold-chain biologics packaging with GDP certification commands substantial premiums over ambient oral solid dose programs. Cost compression in blister pack substrates is intensifying because of pharmaceutical-grade PVC supply constraints. Generic manufacturers exhibit highest price sensitivity, while venture-backed biotech sponsors prioritize speed-to-validation over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for pharmaceutical packaging substrates. Raw material sourcing draws from China for PVC and aluminum foil, Germany for specialized barrier films, and domestic suppliers for HDPE containers. Single-source vulnerability concentrates in pharmaceutical-grade resin grades qualified for FDA submissions. Distribution runs through direct-to-pharmacy lanes for serialized products and 3PL networks for retail-bound over-the-counter formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA validation history creates switching costs that entrench incumbents and complicate new entrant qualification timelines.
For Market Incumbents: Harden serialization infrastructure through aggregation line upgrades in New Jersey and Massachusetts corridors to preempt DSCSA compliance failures. Deepen backward integration into pharmaceutical-grade film extrusion to capture resin margin compression. Cold-chain certification gaps among regional competitors present expansion leverage for GDP-credentialed facilities. For New Entrants and Emerging Players: Build out sterile barrier pouch capabilities for Massachusetts biotech clusters where incumbent capacity constraints delay program onboarding. Mexico nearshoring corridors offer tariff-advantaged entry points for California and Texas sponsors seeking geographic diversification. Position around rapid scale-up flexibility for Phase III commercial readiness programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract packagers holding FDA inspection histories in Puerto Rico and New Jersey. Long-term viability hinges on serialization infrastructure completion and sustainable material certification positioning. Watch for DSCSA enforcement actions as inflection indicators for sponsor outsourcing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Upgrade | FDA DSCSA aggregation compliance anchors sponsor retention for oral solid dose and injectable lines. |
| Cold-Chain Certification Investment | GDP-credentialed facilities capture biologics outsourcing from Boston and San Francisco venture-backed sponsors. |
| Sustainable Material Certification | California and New York extended producer responsibility laws create first-mover advantages for recyclable barrier providers. |
| Mexico Nearshoring Expansion | Baja California and Querétaro zones leverage USMCA provisions to serve tariff-sensitive California biotech sponsors. |
| Digital Packaging Integration | NFC-enabled cartons and QR-linked adherence tools differentiate branded sponsors in diabetes and cardiovascular categories. |
Research Approach
The analysis maps oral solid dose, biologics, and injectable packaging sub-sectors, each validated through contract packaging executives, regulatory affairs leads at sponsor firms, and cold-chain logistics specialists. Primary interviews with facility operations directors and biotech supply chain managers combined with secondary validation from FDA 483 inspection databases, DSCSA guidance documents, and USP packaging standards. Bottom-up capacity modeling and top-down sponsor procurement spend triangulation anchored volume estimates.
Assumption sets held FDA enforcement intensity and resin price trajectories fixed while varying biologics pipeline advancement rates and state-level extended producer responsibility adoption timing across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user archetype, and regional regulatory cluster. CAGRs derived from facility capacity expansion announcements cross-referenced against sponsor outsourcing intent surveys. Industry-specific inputs incorporated serialization equipment deployment timelines and cold-chain technician certification lag data.
Stress conditions across resin price volatility bands, DSCSA enforcement delay scenarios, and biologics approval acceleration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and sponsor risk tolerance. Macroeconomic contraction, FDA inspection backlog expansion, or breakthrough sterile barrier material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market