
 Germany Glass Packaging Market | 2026-2036
Germany Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Glass Packaging Market Foresight
Lightweighting and modular bottle formats is shifting how beverage and cosmetic buyers configure their packaging portfolios. Verallia Deutschland AG anchors its position through extensive furnace networks across eastern Germany. Gerresheimer AG specializes in pharmaceutical-grade borosilicate vials for injectable drug delivery. Wiegand-Glas Holding GmbH competes through returnable bottle systems that serve domestic mineral water brands.
Germany glass packaging comprises silica-soda-lime formulations formed through blow-and-blow or press-and-blow processes, with wall thickness typically ranging from 2.5 to 5.0 mm depending on application stress requirements. The primary purpose is to provide chemically inert, infinitely recyclable containment for consumable and industrial products. Amber glass dominates pharmaceutical applications due to UV-blocking properties that protect light-sensitive formulations. Bottles command the largest volume share across beverage and food channels, while vials capture concentrated margin pools in parenteral drug packaging.
KBA enforces strict vehicle-type approval frameworks that indirectly shape logistics packaging standards for automotive chemical transport, while the EU Green Deal mandates recycled content thresholds that glass manufacturers must integrate into furnace feedstock. Germany's Packaging Act imposes dual-system participation fees that incentivize lighter, returnable glass designs over single-use alternatives. Stakeholders must monitor how tightening EU ETS carbon costs will reshape furnace energy economics and regional production competitiveness.
Market Dynamics
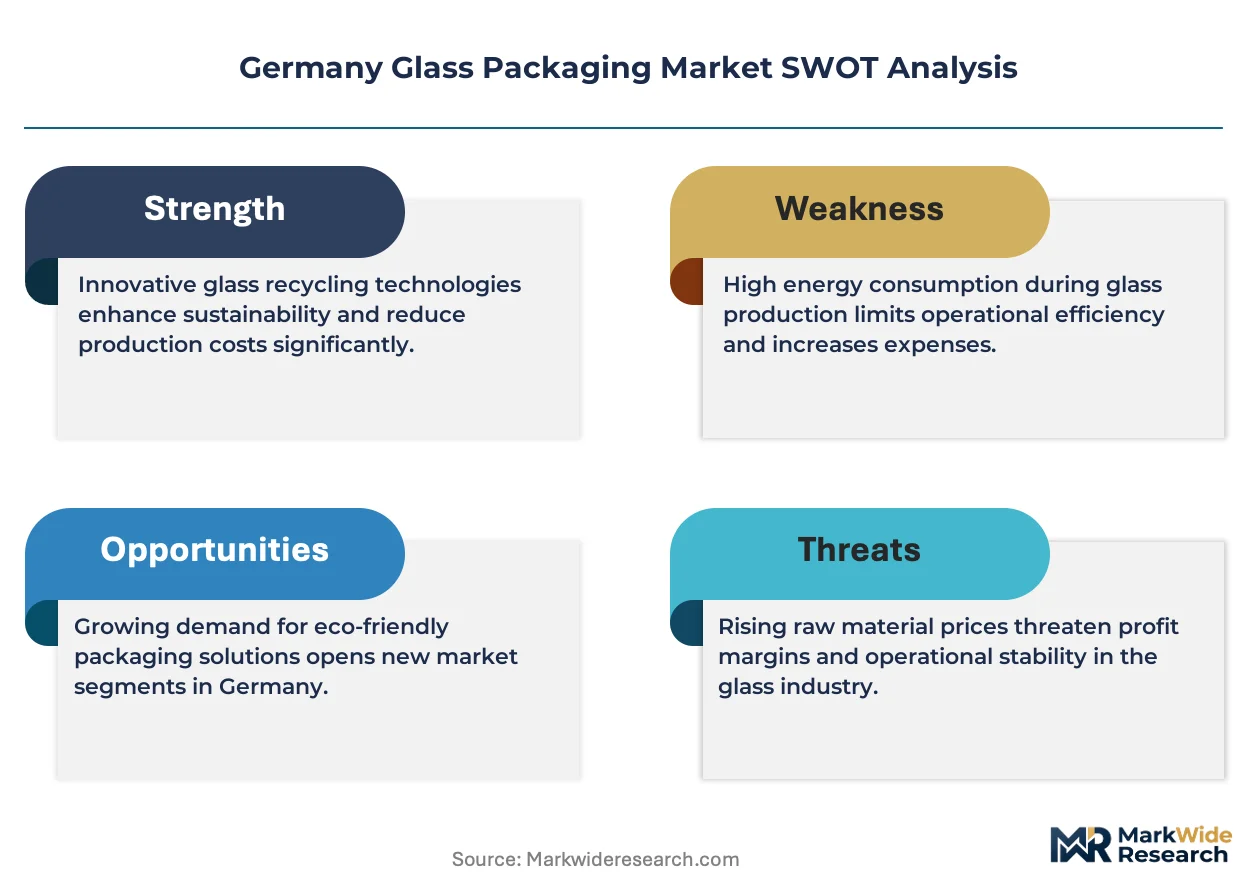
The EU Green Deal's recycled content mandates are compressing furnace feedstock economics and forcing rapid reconfiguration of batch chemistry across German glassworks.
Growth Catalysts
- Returnable bottle systems:Premium mineral water and craft beverage brands are expanding refillable glass loops, cutting per-use material intensity.
- Germany's Packaging Act:Dual-system participation fees penalize single-use packaging, tilting cost structures toward reusable glass formats.
- Borosilicate vial demand:Injectable drug delivery requirements from Bavarian pharmaceutical clusters are pulling specialized capacity expansion.
Market Restraints
- Natural gas price volatility:Furnace operations depend on piped gas feedstock, exposing margins to energy cost swings.
- Furnace concentration in eastern Germany:Production clusters near Saxony and Thuringia create geographic supply risk.
- Aluminum can substitution:Beverage brands facing logistics weight constraints are shifting portion of volume to metal formats.
Strategic Opportunities
- North Rhine-Westphalia cosmetic brands:Underpenetrated demand for premium glass jars in skincare packaging offers white space.
- EU ETS carbon cost integration:Early adoption of electric melting pilots positions operators ahead of tightening emissions pricing.
- Lightweighting technology convergence:Thin-wall forming is converging with surface coating advances to cut transport costs without strength loss.
Industry Challenges
- Furnace rebuild cycles:Decadal refractory replacement demands capital lock-up during margin compression.
- Pharmaceutical colorimetric certification:Amber glass UV-blocking specifications require extended compliance timelines for new product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Glass Packaging Market |
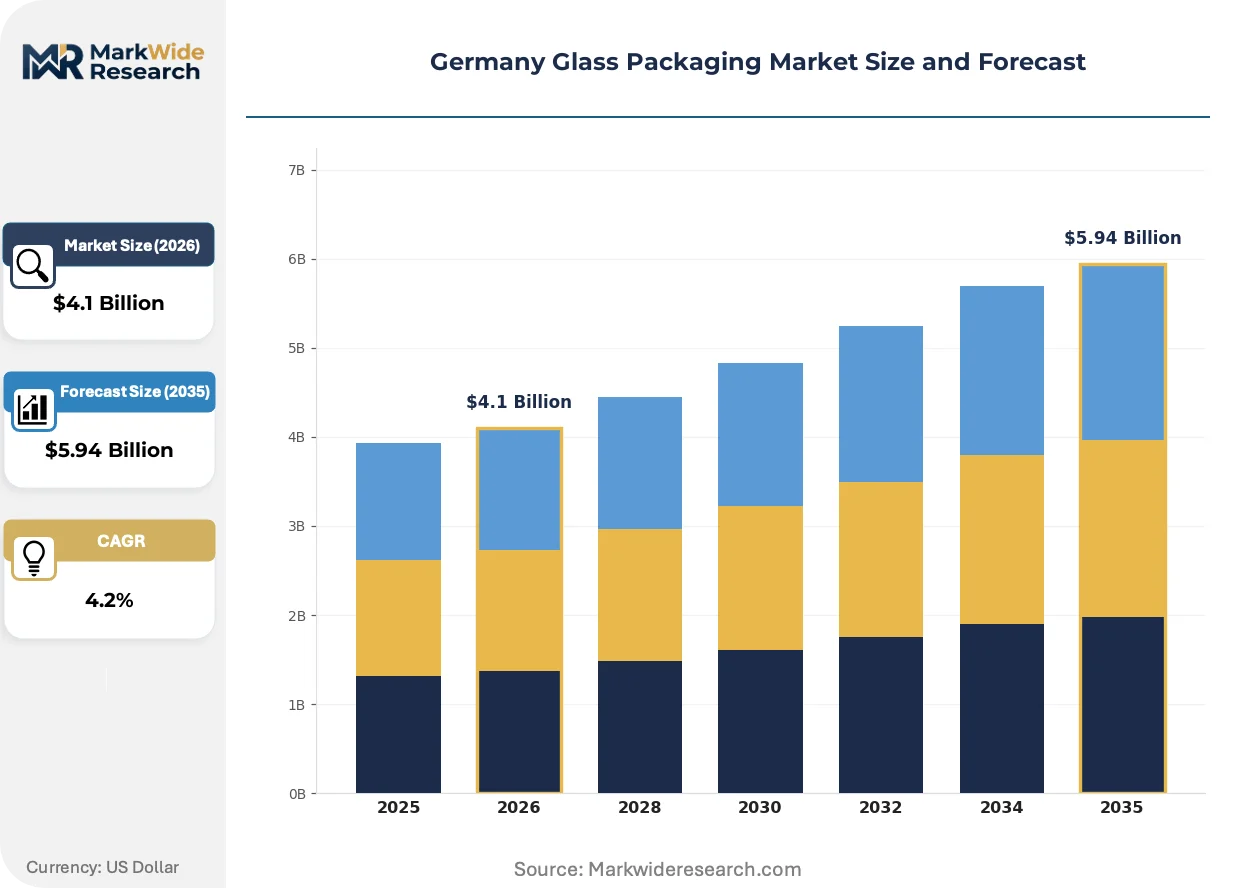
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Containers, Tubes Material Grade: Flint Glass, Amber Glass, Green Glass, Cobalt Glass, Cranberry Glass Application: Beverages, Pharmaceuticals, Cosmetics, Foodstuff, Chemicals Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Wholesale Distributors, Direct Sales |
| Companies Covered | Schott AG, Verallia Deutschland AG, Gerresheimer AG, BA Glass BV, Stolzle Glass Group, Ardagh Group S.A., Wiegand-Glas Holding GmbH, Heinz-Glas GmbH, O-I Glass Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Glass Packaging Market Shifts & Advancements
Digital furnace control and closed-loop cullet recovery are compressing energy intensity and batch variability in German glassworks.
Laser inspection systems for micro-crack detection are converging with real-time furnace feedback loops, enabling predictive quality intervention. Pharmaceutical and premium beverage producers are adopting this at pilot scale. The technology is converging with automated sorting to compress rejection rates and cut manual inspection labor.
Germany's Packaging Act imposes escalating dual-system fees on non-recyclable formats, forcing brand owners to redesign for returnability. Glass manufacturers must now certify minimum recycled content thresholds to maintain supplier status. Beverage and food segments are responding by specifying lighter, standardized bottle formats compatible with existing washing infrastructure.
Consolidated procurement by retail chains is compressing supplier counts and extending contract durations. Mid-sized mineral water brands are losing direct supplier relationships as buying concentrates through beverage distribution cooperatives. Bavarian production clusters are most exposed to this channel consolidation.
Germany Glass Packaging Market Segmentation
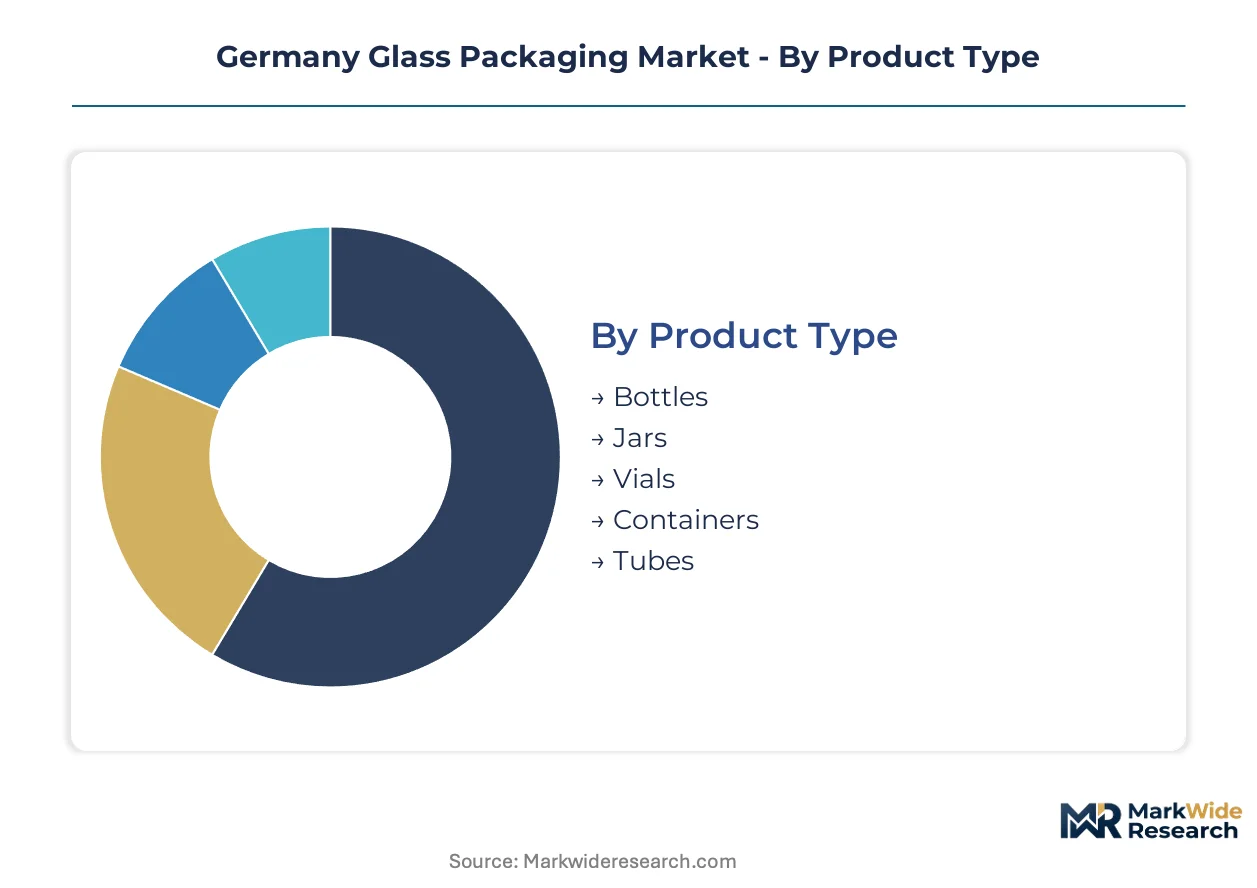
Glass packaging segmentation in Germany reflects divergent certification burdens across pharmaceutical, food contact, and cosmetic applications. Material grade specifications and returnability requirements create distinct margin tiers that reshape supplier priorities.
Product Type:
Pharmaceutical-grade vials demand EMA compliance and borosilicate certification, while beverage bottles navigate Germany's Packaging Act returnability mandates.
- Bottles:Silica-soda-lime formulations dominate beverage and mineral water applications. Bavarian mineral water brands drive demand for standardized returnable formats compatible with existing washing infrastructure. The EU Green Deal's recycled content thresholds compress batch chemistry economics for flint and colored variants.
- Vials:Borosilicate construction withstands thermal shock during sterilization cycles. Injectable drug delivery from Bavarian pharmaceutical clusters pulls specialized capacity expansion, with amber variants requiring extended colorimetric certification timelines.
- Jars:Wide-mouth configurations serve premium cosmetic and food preservation segments. North Rhine-Westphalia skincare brands specify thick-wall designs for tactile premium positioning.
- Containers:Rectangular and cylindrical formats accommodate chemical transport logistics under KBA vehicle-type approval frameworks. Eastern German production clusters concentrate capacity for industrial chemical containment.
- Tubes:Narrow-diameter extrusions serve pharmaceutical ointment and cosmetic cream dispensing. Limited domestic capacity forces reliance on imported borosilicate feedstock.
Leading the category by volume: Bottles. Growing fastest: Vials.
Material Grade:
Colorimetric properties determine UV protection tiers and pharmaceutical eligibility, with amber and flint commanding divergent certification pathways.
- Flint Glass:Clear silica-soda-lime formulation maximizes product visibility for premium beverage and cosmetic applications. Supermarket private-label mineral water brands specify flint for shelf differentiation, though higher iron content tolerance complicates cullet recycling streams.
- Amber Glass:Iron-sulfur coloration blocks UV wavelengths below 450nm. Parenteral drug packaging mandates amber for light-sensitive formulations, with EMA stability studies extending qualification timelines.
- Green Glass:Chromium oxide tinting provides moderate UV attenuation at lower cost than amber. Wine and beer applications concentrate demand in Rhineland-Palatinate and Baden-Württemberg production zones.
- Cobalt Glass:Deep blue coloration serves decorative cosmetic and limited pharmaceutical specialty segments. Niche volume restricts furnace campaign economics to multi-color batch scheduling.
- Cranberry Glass:Gold chloride-derived pink tinting occupies ultra-premium cosmetic gifting niches. Hand-blown production in Saxon artisan workshops limits scale.
Volume concentration: Flint Glass. Steepest expansion trajectory: Amber Glass.
Application:
End-use certification tiers separate pharmaceutical GMP requirements from food contact compliance and cosmetic safety standards.
- Beverages:Returnable mineral water and craft beer formats dominate volume. Germany's Packaging Act dual-system fees penalize single-use alternatives, reinforcing refillable glass loop economics.
- Pharmaceuticals:Injectable and oral solid dosage containment demands EMA-certified borosilicate capacity. Bavarian pharmaceutical clusters anchor specialized vial and ampoule demand.
- Cosmetics:Premium skincare jars and fragrance bottles prioritize tactile weight and optical clarity. North Rhine-Westphalia brand headquarters drive specification trends.
- Foodstuff:Preserves, sauces, and condiments require migration-tested formulations. Retail chain consolidated procurement compresses supplier counts.
- Chemicals:Laboratory and industrial chemical containment navigates KBA transport packaging standards. Eastern German furnace networks serve automotive chemical logistics.
Category leader by throughput: Beverages. Gaining share fastest: Pharmaceuticals.
Distribution Channel:
Channel concentration shapes order fragmentation and contract duration, with retail consolidation extending payment terms.
- Supermarkets:Discounter and hypermarket chains dominate beverage bottle procurement. Buying cooperative concentration forces standardized format acceptance.
- Wholesale Distributors:Beverage and foodservice intermediaries aggregate fragmented brand demand. Saxony and Thuringia production clusters maintain direct distributor relationships.
- Specialty Stores:Premium cosmetic and artisan food retailers specify small-batch colored glass. Higher per-unit margins offset volume inefficiency.
- Online Retail:Direct-to-consumer cosmetic glass expands, though breakage rates elevate packaging costs. Fragile goods logistics constraints limit beverage applicability.
- Direct Sales:Pharmaceutical manufacturers contract furnace capacity for captive vial supply. Gerresheimer and Verallia anchor long-term direct agreements.
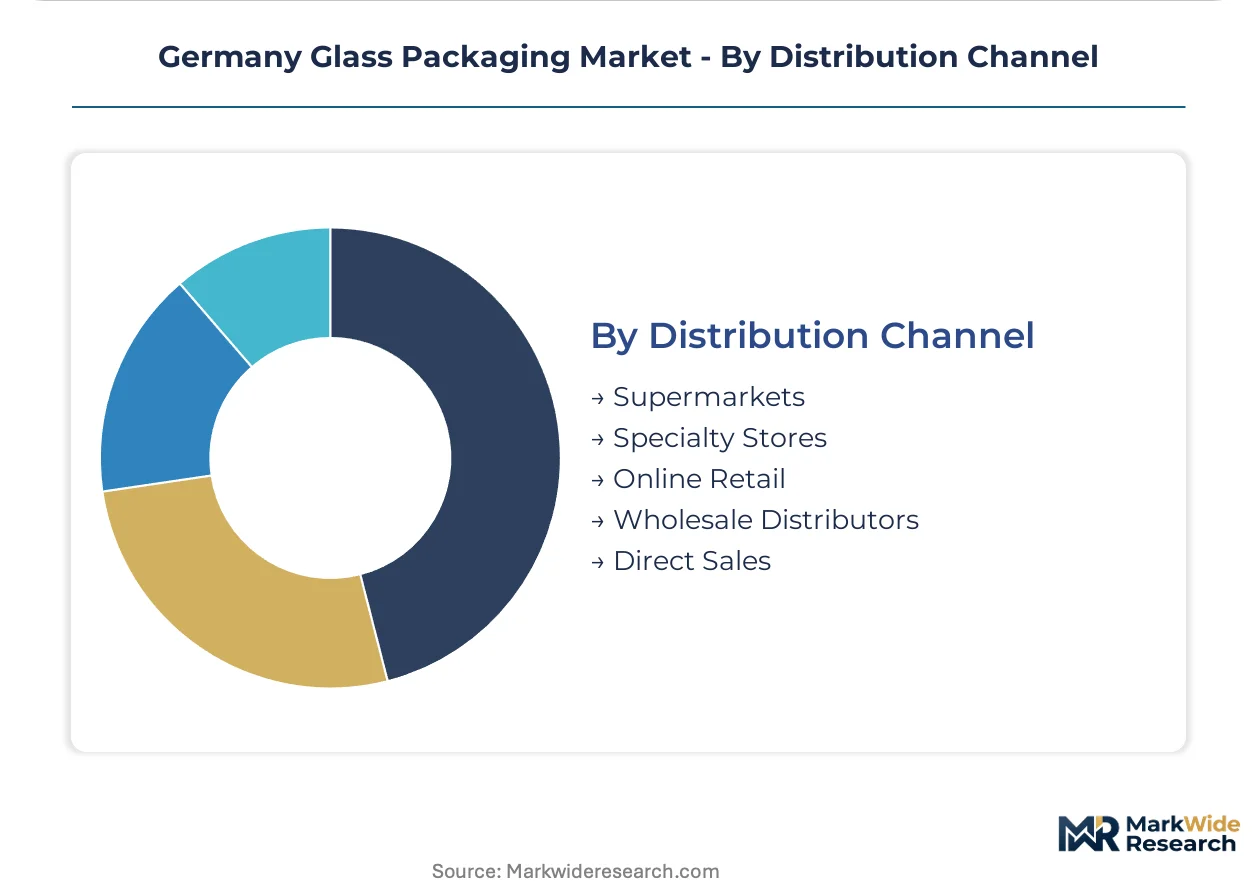
Highest volume flow: Supermarkets. Expanding most quickly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's pharmaceutical tax incentives and North Rhine-Westphalia's chemical industry clusters concentrate German glass packaging demand. Eastern furnace networks in Saxony and Thuringia supply returnable bottle systems. Sub-regional specialization shapes competitive positioning across mineral water, pharmaceutical, and cosmetic segments.
Bavaria
Injectable drug delivery from Munich and Nuremberg pharmaceutical clusters pulls specialized borosilicate vial capacity. EMA stability studies for amber glass UV-blocking extend qualification timelines for new suppliers. Gerresheimer AG anchors pharmaceutical-grade production in Franconia with dedicated furnace campaigns for parenteral packaging.
North Rhine-Westphalia
Premium skincare brands in Düsseldorf and Cologne specify thick-wall glass jars for tactile differentiation. Germany's Packaging Act dual-system fees incentivize lighter, returnable designs over single-use alternatives. Verallia Deutschland AG operates extensive furnace networks serving cosmetic and beverage procurement from regional headquarters.
Baden-Württemberg
Wine and craft beer producers in Stuttgart and Freiburg drive demand for green and flint glass bottles. EU Green Deal recycled content mandates compress batch chemistry economics for colored variants. Stolzle Glass Group maintains specialty capacity for premium beverage applications in the Upper Rhine Valley.
Saxony
Industrial chemical containment for automotive logistics clusters near Leipzig and Dresden. KBA vehicle-type approval frameworks shape packaging standards for hazardous material transport. Wiegand-Glas Holding GmbH concentrates returnable bottle furnace capacity for domestic mineral water brands in the region.
Hesse
Frankfurt's pharmaceutical distribution hubs consolidate procurement for amber glass oral solid dosage packaging. Central location enables efficient logistics to Bavarian and North Rhine-Westphalia production zones. Mid-sized generic drug manufacturers specify standardized vial formats to reduce supplier qualification burden.
Germany Glass Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's glass packaging sector. The vendor base organizes around three strategic archetypes: integrated multinational furnace operators, regional returnable bottle specialists, and pharmaceutical-grade borosilicate manufacturers. Capacity expansion and lightweighting technology licensing represent the dominant competitive moves as energy costs reshape furnace economics.
Among Germany-based specialists, Schott AG exemplifies pharmaceutical-grade borosilicate positioning, while Verallia Deutschland AG and Wiegand-Glas Holding GmbH occupy distinct tiers within beverage and returnable system supply. These three entities represent divergent scale profiles and end-use concentrations without overlapping core segments.
| Leading Market Players |
|---|
| Schott AG |
| Verallia Deutschland AG |
| Gerresheimer AG |
| BA Glass BV |
| Stolzle Glass Group |
| Ardagh Group S.A. |
| Wiegand-Glas Holding GmbH |
| Heinz-Glas GmbH |
| O-I Glass Inc. |
| Others |
Supply & Pricing Matrix
Skilled furnace operators concentrated in Saxony and Thuringia drive labor-cost differentials that widen pricing-tier spreads between premium pharmaceutical-grade output and commodity beverage formats. These regional wage premiums compound with natural gas feedstock exposure to stratify glass packaging economics across Germany's production clusters.
Pricing Analysis
Short lead-time premiums command pricing power as pharmaceutical manufacturers pay surcharges for EMA-certified borosilicate vials with sub-quarter qualification timelines. Contract-based long-term offtake dominates, with price differentiation resting on certification grade and volume scale. Pricing pressure stems from EU ETS carbon cost integration squeezing furnace margins. Generic drug manufacturers exhibit highest price sensitivity, while injectable biologics producers absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Dual-sourcing mandates from Bavarian pharmaceutical clusters require buyers to qualify minimum two amber glass suppliers, fragmenting procurement across Gerresheimer and Schott AG furnace networks. Geographic supply concentrates in Germany, Czech Republic, and Poland for silica sand and soda ash feedstock. Raw material dependencies center on high-purity silica, sodium carbonate, and limestone. Single-source vulnerability looms in specialized borosilicate feedstock for pharmaceutical tubing. Distribution runs through beverage distribution cooperatives and direct pharmaceutical manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's glass packaging sector is consolidating as EU Green Deal recycled content mandates force sub-scale furnace operators into capital-intensive rebuild cycles that weaker players cannot fund.
For Market Incumbents: Hedge against natural gas price volatility through electric melting pilot investments ahead of tightening EU ETS carbon costs. Lock in long-term pharmaceutical direct sales contracts before generic drug procurement consolidation accelerates. Vertical integration into cullet recovery networks secures feedstock against tightening batch chemistry standards.
For New Entrants and Emerging Players: Laser inspection systems for micro-crack detection offer a technology-first wedge into quality-sensitive pharmaceutical segments where incumbent inspection labor costs are sticky. North Rhine-Westphalia cosmetic brands present the most penetrable white space, with premium skincare jars commanding margins that amortize new furnace capital. Pursue private-label partnerships with Düsseldorf brand headquarters rather than competing for supermarket cooperative volume.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap returnable bottle specialists given Germany's Packaging Act dual-system fee escalation tilting demand toward reusable formats. Long-term viability favors operators with eastern German furnace assets proximate to automotive chemical logistics clusters. Monitor EU ETS carbon price trajectory as the inflection signal for electric melting economics crossover.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Pilot Deployment | EU ETS carbon cost integration threatens natural gas furnace economics across Saxony and Thuringia. |
| Pharmaceutical Direct Sales Contract Extension | Bavarian injectable drug clusters anchor specialized borosilicate vial demand with multi-year visibility. |
| Cullet Recovery Network Integration | Germany's Packaging Act recycled content thresholds compress batch chemistry economics for non-compliant feedstock. |
| Laser Inspection System Adoption | Real-time micro-crack detection converges with automated sorting to cut pharmaceutical rejection rates. |
| Lightweighting Technology Licensing | Thin-wall forming advances cut transport costs for North Rhine-Westphalia cosmetic brand logistics. |
Research Methodology
Trade association filings, customs records, and furnace operator capacity disclosures formed the secondary backbone, cross-referenced with primary interviews involving furnace operations managers, pharmaceutical procurement directors, beverage brand supply chain leads, and dual-system compliance officers. Bottom-up and top-down triangulation validated production volume estimates against downstream demand aggregation.
Bottom-up modeling tracked individual furnace campaign outputs across eastern German production clusters, while top-down analysis anchored aggregate market sizing to EU packaging waste directive compliance data. Segmentation dimensions spanned product type, material grade, application, and distribution channel complexity. CAGRs derived from production capacity expansion announcements, regulatory timeline enforcement, and end-use demand elasticity across beverage, pharmaceutical, and cosmetic verticals. Natural gas price scenarios and EU ETS carbon cost curves informed margin compression assumptions.
Several conditions sit outside the modeled scope, including unannounced furnace mothballing decisions, abrupt pharmaceutical regulatory pathway shifts, and geopolitical disruption to soda ash feedstock trade flows. Forecasts reflect documented assumptions about dual-system fee escalation trajectories and electric melting technology cost curves. Deviation in EU ETS carbon price velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Germany Container Glass Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
France Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market