
 China Glass Container Packaging Market | 2026-2036
China Glass Container Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Glass Container Packaging Market Outlook
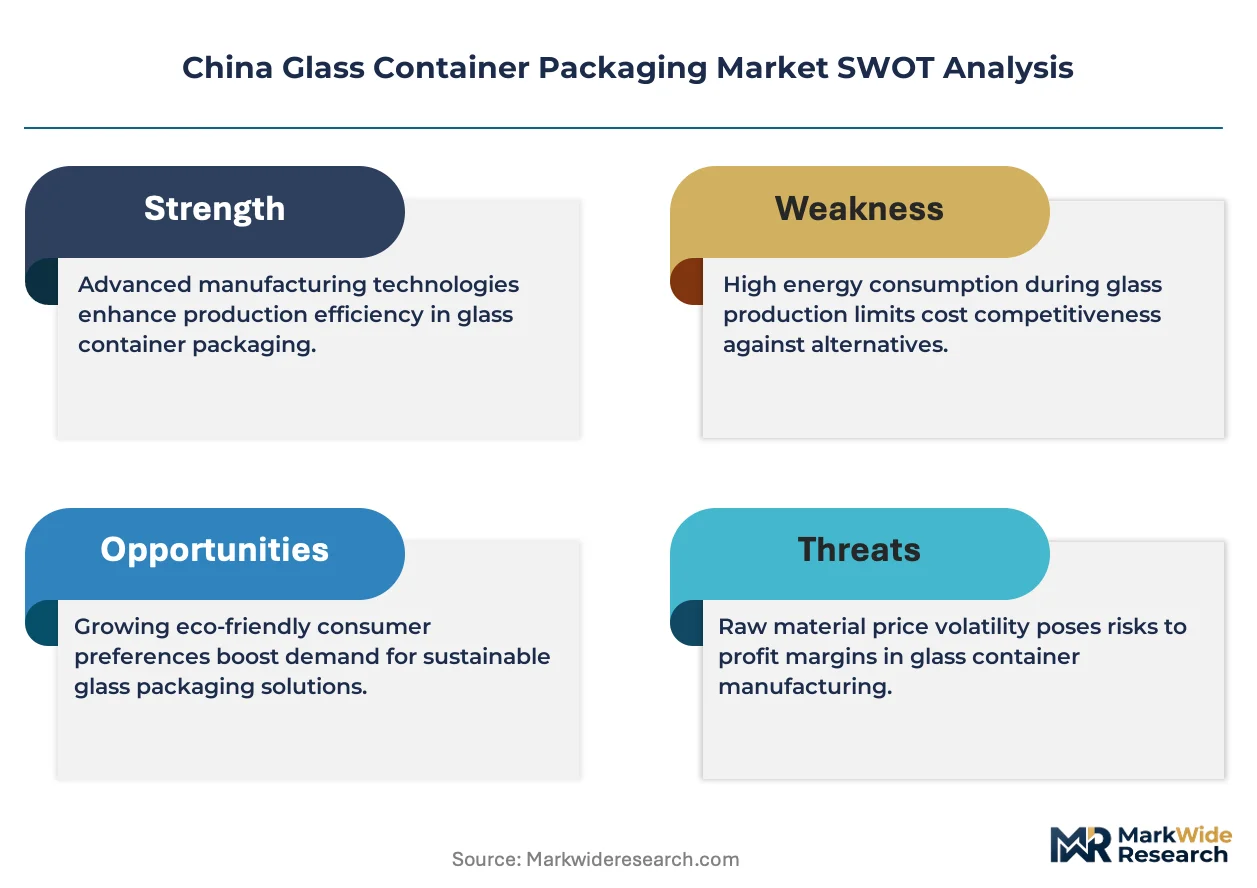
Premium beverage brands is reorganizing procurement priorities across China's glass container sector. Kibing Group leverages its furnace scale to dominate high-volume contracts for beer and spirits clients. Jinjing Group anchors its position through specialized borosilicate capacity serving pharmaceutical vial demand. Taiwan Glass Ind. Corp. competes on decorative and customized design types for cosmetics houses seeking differentiation.
China glass container packaging encompasses silica-soda-lime formulations formed through blow-and-blow or press-and-blow processes, typically achieving wall thickness tolerances within 0.5 millimeters for controlled thermal shock resistance. These vessels serve as chemically inert barriers for oxygen-sensitive contents across food, pharmaceutical, and personal care supply chains. Bottles command the largest volume share within product type segmentation, while vials capture concentrated margin pools from injectable drug serialization requirements. The 100-500ml capacity band generates the densest order flow from condiment and sauce producers in Shandong and Guangdong provinces.
China's Ministry of Ecology and Environment enforces dual carbon targets that elevate energy costs for soda-lime furnace operations, while SAMR mandates GB standards for food-contact glass leachate thresholds. BIS-aligned import protocols for pharmaceutical glass add compliance layers for export-oriented manufacturers. Stakeholders must monitor furnace fuel-switching economics and GB standard revision cycles to time capacity investments.
Market Dynamics
China's dual carbon goals are forcing furnace fuel-switching economics to the center of capacity planning decisions. MEE emissions standards now condition operating permits on natural gas conversion timelines, reshaping where soda-lime production remains viable.
Growth Catalysts
- Dual carbon compliance deadlines:MEE enforcement tightens emissions thresholds for coal-fired furnaces, accelerating capital deployment into natural gas and electric melting technologies.
- Pharmaceutical serialization mandates:NMPA track-and-trace requirements for injectable drugs expand demand for borosilicate vial capacity with embedded serialization compatibility.
- Coastal cluster concentration:Jiangsu and Zhejiang food and beverage procurement volumes concentrate order flow, enabling furnace scale economies that inland competitors cannot replicate.
Market Restraints
- Soda ash price volatility:Domestic synthetic soda ash production faces feedstock cost pressure from coal price swings, compressing furnace operating margins.
- Single-source silica sand dependence:High-purity silica deposits concentrate in northern Anhui and eastern Inner Mongolia, creating geographic supply risk for premium container glass.
- Aluminum can substitution:Lightweight metal packaging captures share in mass-market beer segments where transport cost sensitivity outweighs premium glass positioning.
Strategic Opportunities
- Western province underpenetration:Sichuan and Shaanxi condiment production clusters lack localized glass supply, creating greenfield furnace opportunities.
- Cosmetics decorative glass:Domestic beauty brands seek differentiated bottle designs previously imported from Italy and France.
- GB standard harmonization:SAMR alignment with Codex food-contact protocols opens export pathways to ASEAN markets.
Industry Challenges
- Furnace engineer scarcity:Electric melting and oxy-fuel conversion expertise concentrates at state-owned research institutes, constraining private sector retrofit timelines.
- Pharmaceutical glass certification lag:USP Type I and EP 3.2.1 compliance testing extends new product qualification cycles beyond eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Glass Container Packaging Market |
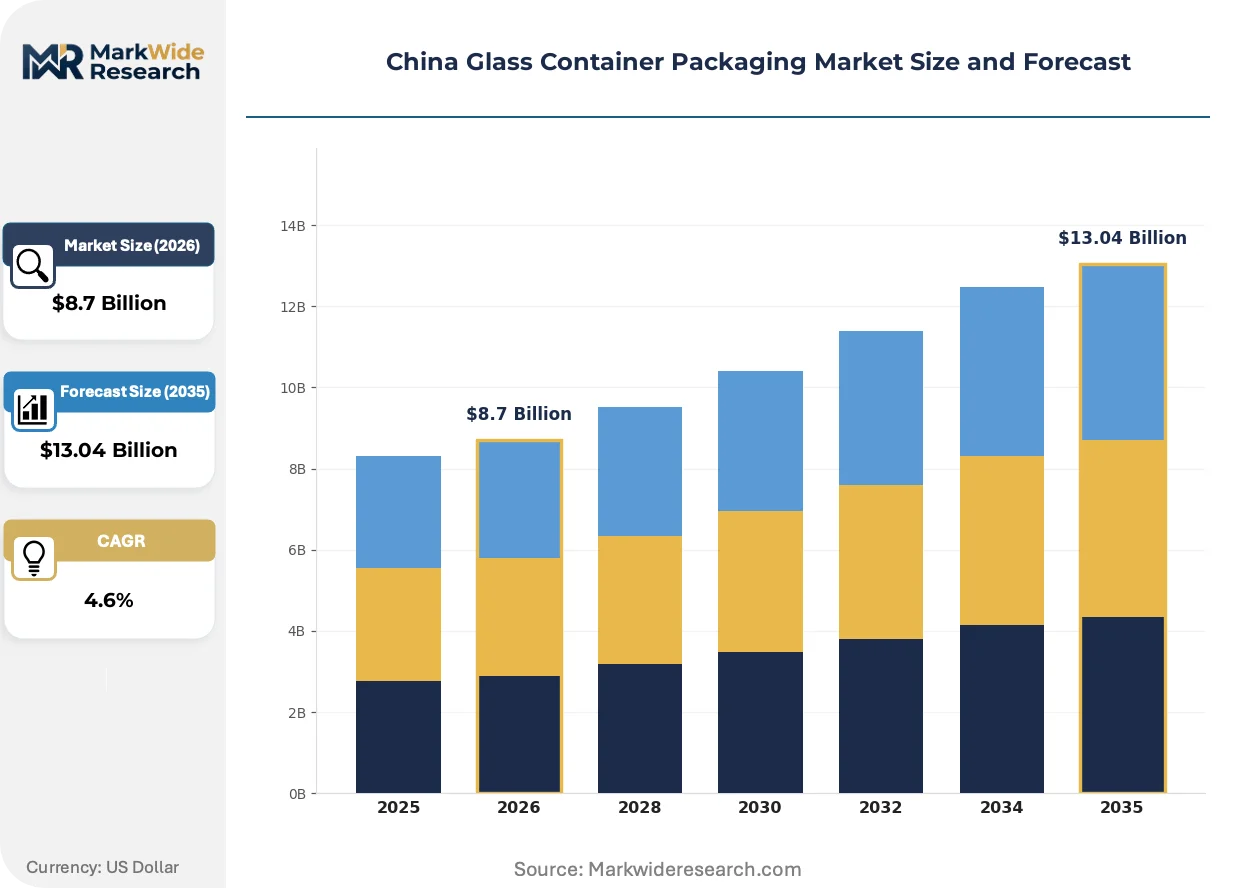
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Tumblers End Use: Food & Beverage, Personal Care, Pharmaceuticals, Household Design Type: Customized, Standard, Decorative, Functional Capacity: Below 100ml, 100-500ml, 500-1000ml, Above 1000ml |
| Companies Covered | Kibing Group, Jinjing Group, Taiwan Glass Ind. Corp. (TG), Saint-Gobain China, Fuyao Glass Industry Group Co., Ltd., China Glass Holdings Limited, Xinyi Glass Holdings Limited, LUCK GLASS, CSG Holding Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Glass Container Packaging Market Strategic Shifts
Electrification of melting technology intersects with digital process control to redefine furnace economics. These shifts compress the viable operating window for legacy fuel configurations.
Oxy-fuel combustion retrofit kits are fragmenting the installed base of air-fuel furnaces. Spirits producers in Sichuan and Guizhou adopt oxy-fuel systems to meet provincial emissions audits while preserving amber glass color consistency. This technology is fragmenting supplier tiers, separating furnace builders with combustion engineering capabilities from pure equipment installers.
MEE carbon intensity benchmarks now condition environmental compliance permits on verified emissions reductions. Soda-lime producers face stepped natural gas conversion mandates through 2027. Coastal provinces with pipeline access respond fastest; inland operators confront stranded asset risk.
Direct mill procurement contracts displace distributor intermediaries in condiment and sauce segments. Shandong and Guangdong processors now negotiate annual volume commitments with furnace operators, bypassing regional glass merchants. This channel compression concentrates pricing power with top-five container manufacturers.
China Glass Container Packaging Market Segmentation
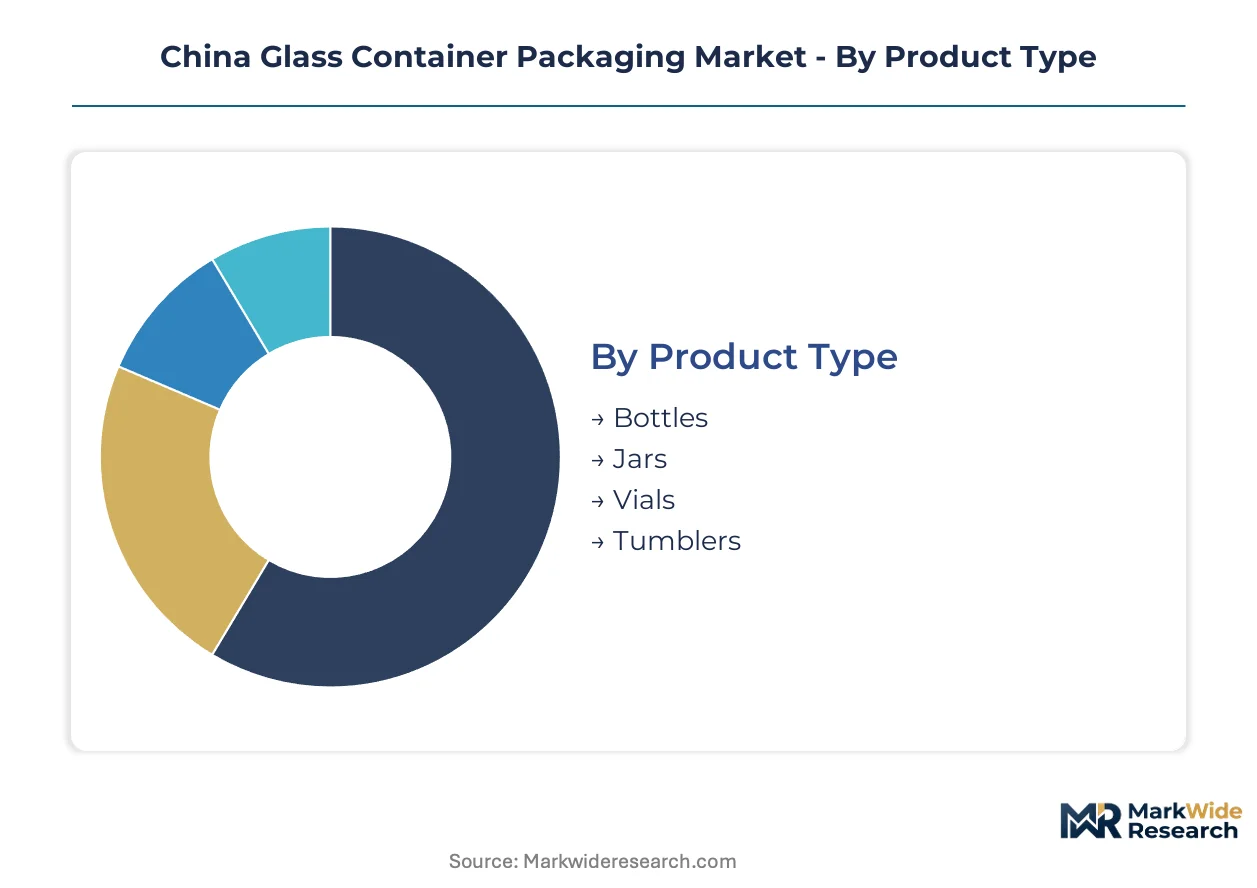
Segmentation in China's glass container packaging market reveals distinct procurement patterns between domestic consumption corridors and export manufacturing zones. Coastal provinces concentrate demand for premium formats serving international brands, while inland production clusters favor standardized vessels for mass-market condiments and beverages.
Product Type:
Domestic procurement concentrates in Jiangsu and Zhejiang for high-volume beer and spirits bottles, while export-oriented vial production clusters near Shanghai pharmaceutical corridors. The cost tier spans commodity soda-lime vessels to specialized borosilicate formats.
- Bottles:Silica-soda-lime formulations dominate beer and spirits packaging through blow-and-blow forming, achieving wall thickness tolerances within 0.5 millimeters. Shandong and Guangdong condiment producers drive dense order flow in the 100-500ml range, though aluminum can substitution erodes share in transport-cost-sensitive beer segments.
- Vials:Borosilicate glass withstands thermal shock for autoclave sterilization cycles required in injectable drug packaging. NMPA serialization mandates for track-and-trace compatibility concentrate demand expansion in Jiangsu pharmaceutical manufacturing zones, where eighteen-month USP Type I qualification cycles constrain new supplier entry.
- Jars:Wide-mouth configurations serve pickled vegetable and sauce preservation needs across northern China food processing clusters.
- Tumblers:Drinking vessels and candle containers occupy lower-margin decorative segments with fragmented supplier bases.
Bottles command the established base. The steepest expansion runs through vials.
End Use:
Application maturity varies sharply: food and beverage represents legacy volume, while pharmaceutical formats climb fastest on regulatory compliance investments.
- Food & Beverage:Oxygen-sensitive condiments and sauces in Shandong and Guangdong provinces generate the densest procurement volumes. Direct mill contracts now displace distributor intermediaries, concentrating pricing power with top-five furnace operators.
- Pharmaceuticals:Injectable drug serialization requirements under NMPA mandates expand borosilicate vial demand. BIS-aligned import protocols add compliance layers for export-oriented manufacturers targeting ASEAN markets.
- Personal Care:Domestic beauty brands seek differentiated decorative bottles previously imported from Italy and France.
- Household:Standardized storage containers serve mass-market retail channels with thin margin profiles.
Food and beverage anchors volume concentration. Pharmaceuticals deliver the margin expansion trajectory.
Design Type:
Customer type stratification separates premium cosmetics houses seeking differentiation from commodity food processors prioritizing unit economics.
- Customized:Spirits producers in Sichuan and Guizhou specify amber color consistency through oxy-fuel combustion retrofits to meet provincial MEE emissions audits.
- Decorative:Taiwan Glass Ind. Corp. competes on surface treatment and embossing for cosmetics differentiation.
- Standard:Mass-market condiment and sauce segments prioritize interchangeability and supply security over aesthetic variation.
- Functional:Child-resistant closures and pour-control features command specification premiums in pharmaceutical and household chemical applications.
Standard designs dominate procurement tonnage. Customized formats capture the pricing premium expansion.
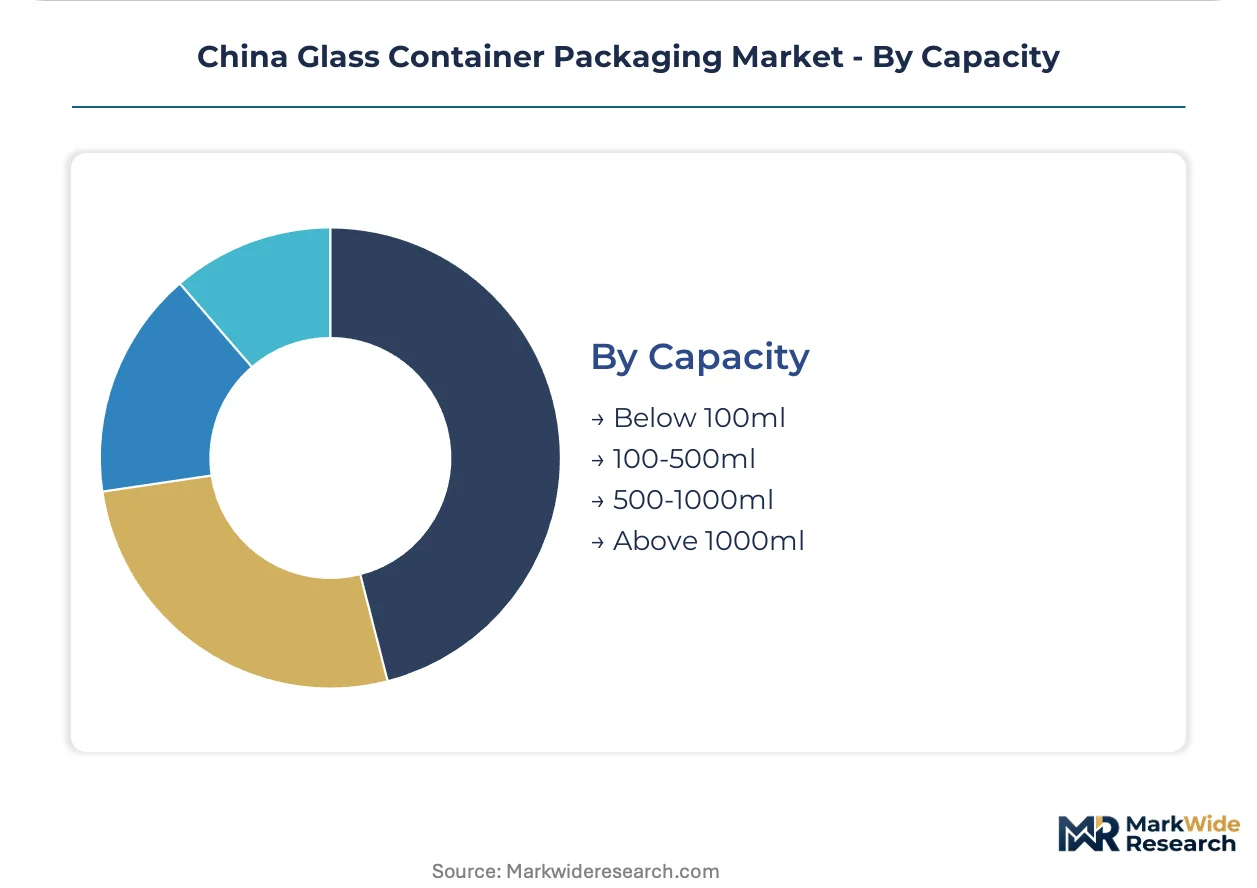
Capacity:
Volume concentration patterns reflect regional cuisine preferences and distribution logistics constraints across Chinese provinces.
- 100-500ml:The densest order flow originates from condiment and sauce producers in Shandong and Guangdong, matching single-meal and small-household consumption patterns.
- Below 100ml:Pharmaceutical vials and premium cosmetic samples concentrate in Jiangsu and Zhejiang export manufacturing zones.
- 500-1000ml:Family-size beverage and cooking oil formats serve supermarket retail channels.
- Above 1000ml:Institutional food service and bulk industrial containers face competition from plastic alternatives on transport efficiency.
The 100-500ml band anchors procurement volume. Below 100ml formats gain share fastest on pharmaceutical serialization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's glass container exports flow predominantly toward ASEAN markets, where BIS-aligned import protocols create compliance gateways for pharmaceutical and food-contact formats. Domestic procurement concentrates in coastal manufacturing corridors with pipeline natural gas access.
Jiangsu Province
Pharmaceutical serialization mandates under NMPA track-and-trace requirements drive borosilicate vial demand expansion. MEE emissions audits condition operating permits on verified furnace fuel-switching timelines. The Suzhou-Nantong corridor hosts concentrated injectable drug manufacturing clusters where eighteen-month USP Type I qualification cycles constrain new supplier entry.
Zhejiang Province
Food and beverage procurement volumes generate dense order flow for premium spirits and condiment bottles. SAMR GB standards for food-contact glass leachate thresholds elevate quality compliance investments. The Ningbo-Shaoxing manufacturing belt anchors furnace scale economies that inland competitors cannot replicate.
Shandong Province
Condiment and sauce producers in the 100-500ml capacity band drive standardized vessel procurement at volume scale. Direct mill contracts now displace regional distributor intermediaries. The Weifang-Qingdao processing corridor concentrates pickling and sauce preservation operations requiring wide-mouth jar configurations.
Guangdong Province
Single-meal and small-household consumption patterns sustain 100-500ml format demand from sauce and cooking oil packers. Dual carbon compliance deadlines accelerate capital deployment into electric melting technologies. The Guangzhou-Foshan logistics hub enables just-in-time glass supply to Pearl River Delta food processors.
Sichuan Province
Spirits producers specify amber glass color consistency through oxy-fuel combustion retrofits to meet provincial MEE emissions audits. Western province underpenetration creates greenfield furnace opportunities for localized condiment glass supply. The Chengdu-Chongqing corridor lacks captive container glass capacity relative to its beverage production scale.
China Glass Container Packaging Market Competitive Environment
Player mix skews toward state-influenced conglomerates with captive furnace assets and furnace-scale private operators serving branded beverage accounts. Market structure exhibits tiered consolidation: top-five container manufacturers concentrate pricing power through direct mill procurement contracts, while mid-tier operators compete on regional logistics proximity. Two strategic archetypes dominate—scale-driven furnace operators leveraging natural gas conversion timelines, and specialized borosilicate producers serving pharmaceutical serialization requirements. Competitive moves center on oxy-fuel combustion retrofit deployment and backward integration into high-purity silica sand sourcing.
Among furnace-scale specialists, Kibing Group and Jinjing Group occupy positions reflecting divergent capability investments. Kibing exemplifies the high-volume beer and spirits contract archetype through furnace scale deployment. Jinjing represents specialized borosilicate capacity positioning for pharmaceutical vial demand. Taiwan Glass Ind. Corp. sits within the decorative differentiation tier, serving cosmetics houses seeking design alternatives to European imports.
| Leading Market Players |
|---|
| Kibing Group |
| Jinjing Group |
| Taiwan Glass Ind. Corp. (TG) |
| Saint-Gobain China |
| Fuyao Glass Industry Group Co., Ltd. |
| China Glass Holdings Limited |
| Xinyi Glass Holdings Limited |
| LUCK GLASS |
| CSG Holding Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Direct mill procurement contracts lock in multi-year volume commitments that secure furnace capacity for Shandong condiment processors while fixing soda-lime input costs against spot market volatility. This structure concentrates pricing power with Kibing Group and Jinjing Group as regional distributors lose intermediary margins.
Pricing Analysis
Legacy air-fuel furnace output commands discount tiers against oxy-fuel and electric melting premiums. Pricing stratifies across borosilicate certification grades, USP Type I qualification status, and natural gas pipeline proximity. Cost compression in commodity soda-lime vessels stems from aluminum can substitution in mass-market beer. Mass-market condiment packers exhibit highest price sensitivity; pharmaceutical serialization mandates render borosilicate buyers least elastic.
Supply Chain Analysis
High-purity silica sand deposits in northern Anhui and eastern Inner Mongolia tether container glass output to geographic concentration risk. Furnace operations draw from synthetic soda ash, natural gas feedstock, and boron oxide for pharmaceutical grades. Single-source silica dependence creates vulnerability to provincial mining permit revisions. Distribution runs through direct mill contracts bypassing merchant intermediaries in coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's glass container sector enters recovery phase as MEE emissions deadlines force furnace upgrade cycles that consolidate viable capacity. Dual carbon compliance timelines function as the cyclical driver, compressing operating permits for legacy fuel configurations.
For Market Incumbents: Shield market share by accelerating oxy-fuel retrofits ahead of 2027 MEE enforcement windows. Secure captive silica sand offtake from Anhui deposits before provincial mining quotas tighten. Backward integration into high-purity feedstock buffers against single-source geographic risk.
For New Entrants and Emerging Players: Pharmaceutical serialization service gaps in Sichuan and Shaanxi offer white-space entry points where USP Type I qualification scarcity delays incumbent expansion. Target western province condiment clusters lacking localized furnace supply. Lead with electric melting greenfield sites that bypass stranded coal asset exposure.
For Investors and Strategic Acquirers: Specialized borosilicate producers with NMPA track-and-trace compatibility represent the acquisition archetype with durable margin profiles. Long-term viability hinges on fuel-switching completion rates across the analysis window. Monitor MEE permit revocation announcements as inflection signals for capacity rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | MEE emissions audits condition operating permits on verified fuel-switching timelines in Sichuan and Guizhou. |
| Backward Silica Sand Integration | Anhui deposit control secures feedstock against provincial mining quota restrictions. |
| Pharmaceutical Serialization Capacity | NMPA track-and-trace mandates expand borosilicate vial demand in Jiangsu manufacturing corridors. |
| Direct Mill Contract Expansion | Shandong condiment processors bypass distributors to lock annual volume with top-five furnace operators. |
| Electric Melting Greenfield Deployment | Coastal pipeline access enables carbon-compliant capacity without stranded coal asset liability. |
Study Parameters
A spread of perspectives from furnace operations managers, pharmaceutical packaging procurement leads, condiment processor supply chain directors, and MEE regional enforcement officers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from SAMR GB standard filings, NMPA serialization mandate documentation, and coastal province industrial cluster databases. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Segmentation dimensions modeled encompass product type, end-use application, design customization level, and capacity band across the projection horizon. CAGRs derived from furnace investment cycle analysis and fuel-switching compliance timelines. Borosilicate qualification cycle duration and soda ash feedstock cost trajectories served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in MEE emissions enforcement and SAMR food-contact protocols; material policy shifts would require re-modeling. Soda ash price volatility and silica sand mining permit revisions represent specific risk factors that could revise trajectory assumptions. Practitioners should keep alternative scenarios live as dual carbon implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Kenya Container Glass Market