
 Cameroon Container Glass Market | 2026-2036
Cameroon Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Cameroon Container Glass Market Insights
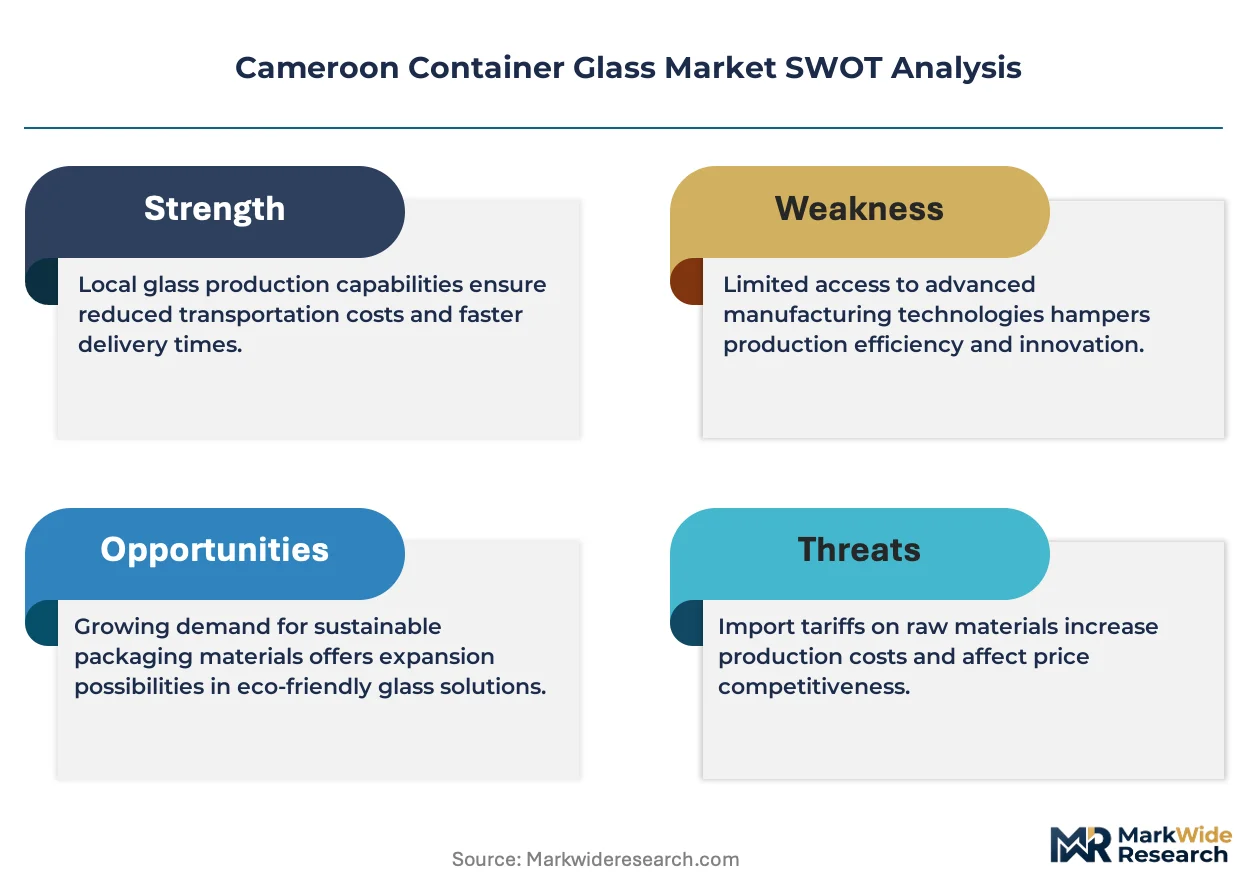
Beverage bottlers are bifurcating from pharmaceutical buyers as the dominant demand archetype in Cameroon's container glass sector. SOCAVER leverages its integrated furnace operations to serve brewery contracts across the Littoral region. CAMGLASS anchors production capacity through specialized amber glass lines for chemical storage applications.
Container glass denotes silica-based packaging formed through blow molding or pressing processes, typically comprising soda-lime compositions with thermal resistance thresholds suited for pasteurization cycles. Its primary purpose centers on preserving product integrity while enabling brand differentiation through shape and color customization. Bottles occupy the largest volume share within product type segments, while pharmaceutical vials generate premium margin pools due to borosilicate-grade requirements. Food and beverage end users drive baseline demand, though cosmetics applications are expanding through lightweight jar innovations.
Cameroon's national standards body enforces food-contact material specifications, while the country's pharmaceutical regulator mandates compliance with drug packaging integrity protocols for imported and locally produced medicines. The Ministry of Industry oversees manufacturing process certifications that affect furnace emissions and worker safety standards. Stakeholders must monitor evolving packaging waste regulations and assess furnace energy efficiency investments before competitor capacity expansions reshape supply availability.
Market Dynamics
Beverage bottling clusters in Douala's industrial corridor are consolidating procurement volumes, forcing container glass producers to rationalize furnace output around fewer, larger contracts while pharmaceutical packaging specifications diverge toward borosilicate-grade standards.
Growth Catalysts
- Food-contact compliance mandates:Cameroon's national standards body enforces quality benchmarks that disqualify inferior imports, insulating domestic furnace operators from price-based competition.
- Pharmaceutical packaging migration:Domestic drug manufacturers are adopting amber glass vials for light-sensitive formulations, creating pull-through demand for specialized melting capacity.
- Douala corridor concentration:Brewery and soft-drink bottling operations cluster within 50 kilometers of port infrastructure, reducing logistics friction for heavy, fragile container shipments.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported fuel feedstock, exposing margin structures to currency-driven cost spikes.
- Raw material import dependency:High-purity silica sand and soda ash arrive through Douala port, creating single-point-of-failure risk in supply continuity.
- Plastic substitution pressure:PET bottle alternatives capture share in non-pasteurized beverage segments where thermal resistance requirements relax.
Strategic Opportunities
- Yaoundé pharmaceutical corridor:Underdeveloped glass packaging supply to the capital region's emerging generic drug production creates geographic white space.
- Lightweighting technology convergence:Thin-wall forming techniques combined with surface coating innovations enable material reduction without strength compromise.
- Extended producer responsibility frameworks:Anticipated packaging waste regulations will favor closed-loop glass recycling economics over single-use alternatives.
Industry Challenges
- Specialized furnace engineering talent:Shortage of technicians trained in regenerative burner optimization and crown refractory maintenance constrains operational uptime.
- Pharmaceutical certification timelines:Drug packaging integrity protocols require 18-24 month validation cycles that delay revenue recognition on new amber glass lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cameroon Container Glass Market |
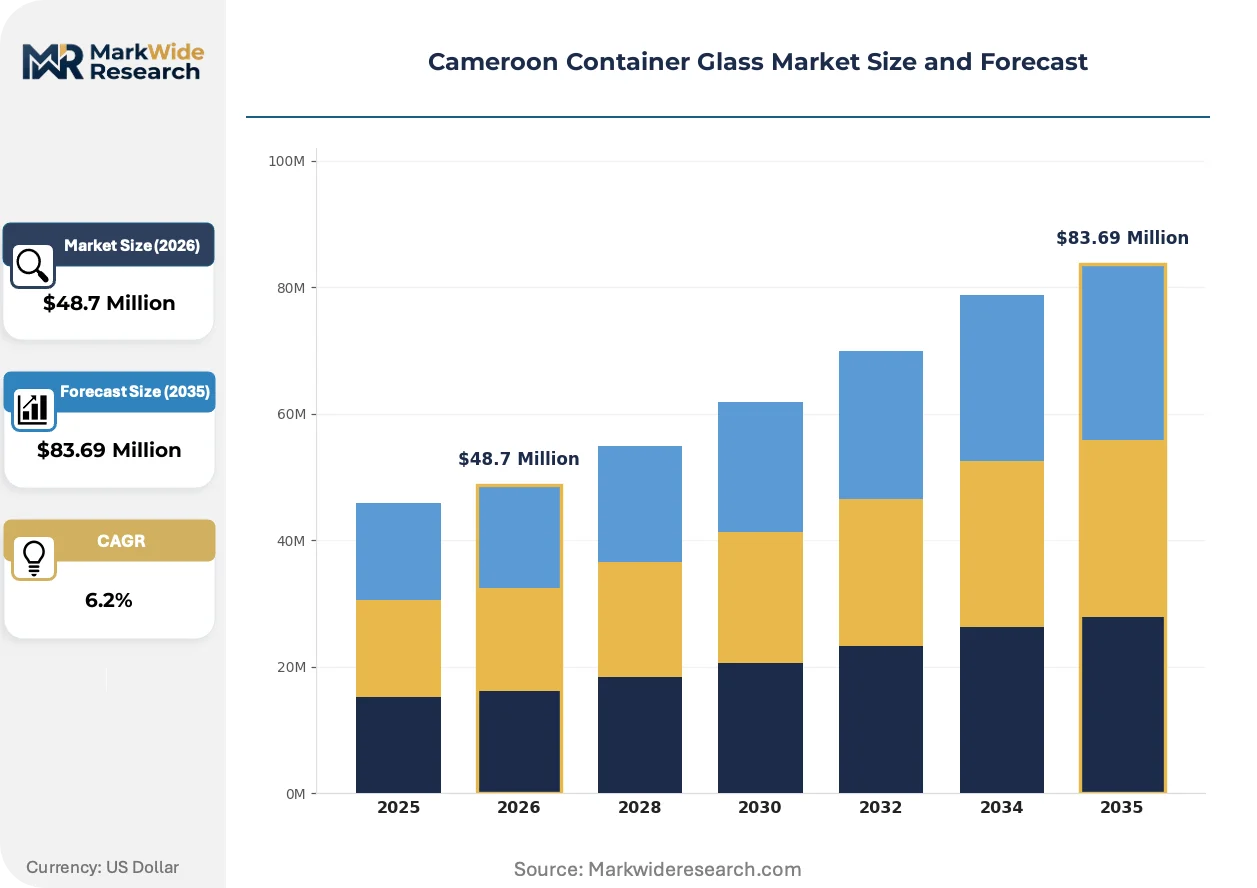
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Manufacturing Process: Blow Molding, Pressing, Reheating, Forming Size: Small, Medium, Large, Extra Large |
| Companies Covered | Société Camerounaise de Verrerie (SOCAVER), Cameroon Glass Factory (CAMGLASS), Société de Développement du Verre (SODEV), Guinness Cameroon Glass Division, Central African Glass Industries, Cameroon Industrial Glass, Regional Glass Consortium, Societe des Verres du Cameroun, Cameroon Glass Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cameroon Container Glass Market Trends and Innovations
Container glass manufacturing in Cameroon is pivoting toward energy efficiency and product differentiation as furnace operators confront fuel cost pressures while beverage and pharmaceutical buyers diverge on performance specifications.
Electric boosting systems are supplementing conventional fossil-fired melting, cutting specific energy consumption per ton of glass pulled. Breweries with pasteurization requirements are piloting these hybrid furnaces to secure supply continuity during gas price spikes. The technology is miniaturizing modular furnace footprints, enabling smaller production runs without catastrophic thermal inefficiency.
Cameroon's national standards body is tightening food-contact material specifications, requiring migration testing documentation for imported colorants and coatings. Domestic producers with in-house laboratory capabilities are capturing contract renewals from multinational beverage brands. Compliance investments now separate viable suppliers from trading operations dependent on undocumented third-country imports.
Beverage bottlers are compressing supplier rosters from five-plus vendors to two approved sources per container format. Procurement teams now bundle volume across multiple SKUs to extract furnace dedication commitments. Yaoundé-based pharmaceutical manufacturers are resisting this consolidation, maintaining fragmented sourcing to secure borosilicate-grade supply security for temperature-sensitive biologics.
Cameroon Container Glass Market Segmentation
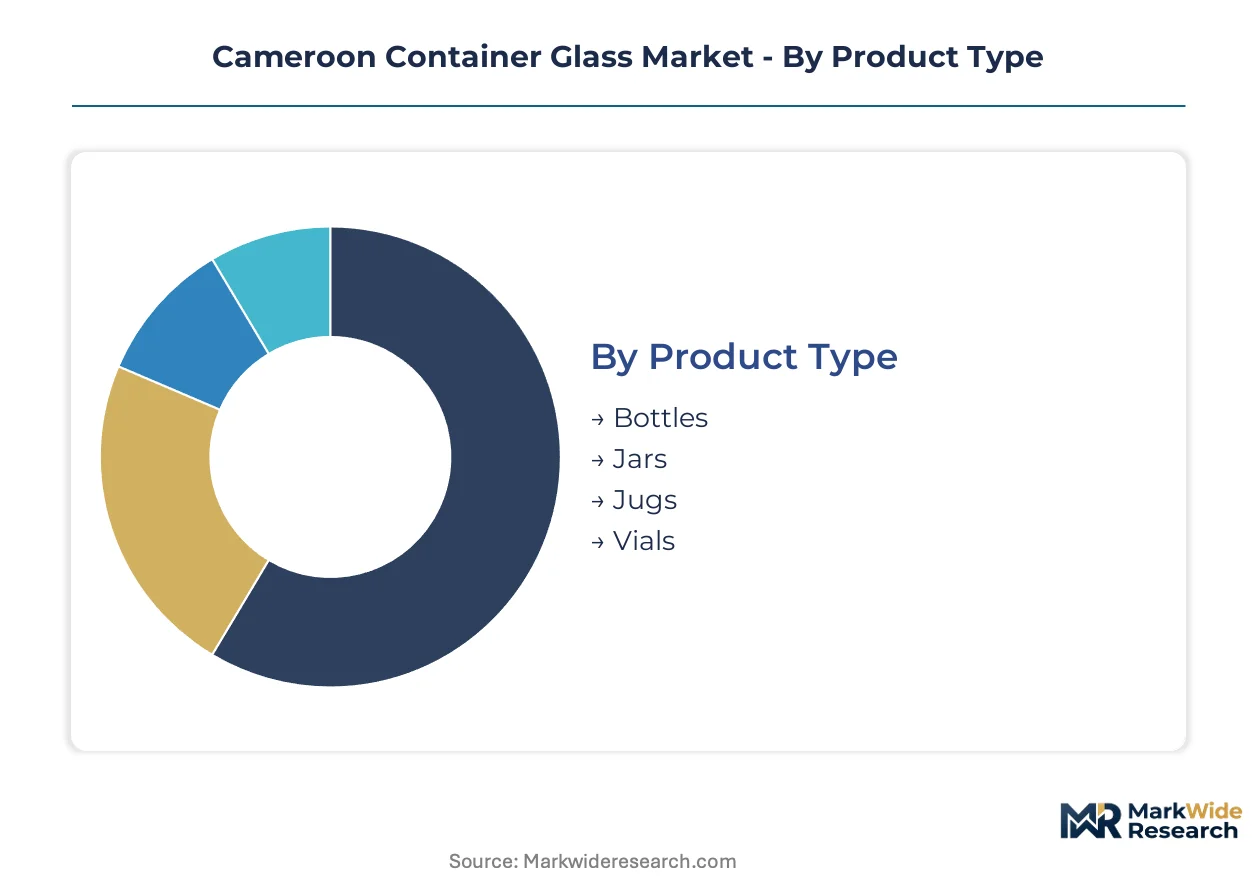
Cameroon's container glass market fragments across four distinct dimensions, each dictating furnace configuration, tooling investment, and customer procurement patterns. Understanding where margin pools concentrate within each category enables producers to prioritize capacity allocation amid competing demand signals from Douala beverage clusters and Yaoundé pharmaceutical corridors.
Product Type:
Premium margin pools concentrate in pharmaceutical-grade formats requiring borosilicate melting capacity, while high-volume beverage contracts dominate tonnage throughput.
- Bottles:Soda-lime silica compositions with thermal resistance thresholds suited for pasteurization cycles anchor brewery procurement in Douala's industrial corridor. SOCAVER and CAMGLASS compete for furnace dedication commitments from consolidated bottler rosters.
- Vials:Borosilicate-grade requirements for light-sensitive drug formulations command specialized amber glass melting lines. Domestic pharmaceutical manufacturers in Yaoundé drive pull-through demand despite 18-24 month certification timelines.
- Jars:Wide-mouth configurations serve cosmetics lightweighting innovations and food preservation applications with reduced thermal stress specifications.
- Jugs:Large-format pressed glass handles chemical storage and industrial fluid containment with thicker wall structures.
The dominant share belongs to bottles, while vials is closing the gap fastest.
End User:
Customer concentration patterns split between consolidated beverage procurement teams and fragmented pharmaceutical quality assurance departments.
- Food & Beverage:Pasteurization requirements from Douala brewery clusters sustain baseline furnace utilization. Procurement bundling across multiple SKUs extracts volume discounts and supply security commitments.
- Pharmaceuticals:Light-sensitive generic drug production in Yaoundé creates geographic white space for amber glass supply. Cameroon's pharmaceutical regulator mandates drug packaging integrity protocols that favor domestic certified suppliers.
- Cosmetics:Lightweight jar innovations for premium skincare brands expand addressable market beyond traditional thermal resistance applications.
- Chemicals:CAMGLASS anchors specialized capacity through amber glass lines for storage applications requiring chemical compatibility certification.
Food and beverage commands installed furnace capacity, though pharmaceuticals is expanding most quickly.
Manufacturing Process:
Energy intensity varies dramatically across thermal processing stages, with melting operations consuming 60-70% of total production energy.
- Blow Molding:Compressed air forming of parisons into hollow containers dominates beverage bottle production with high-speed rotary machine compatibility.
- Pressing:Mechanical plunger forming produces wide-mouth jars and jugs with precise wall thickness control for chemical resistance specifications.
- Reheating:Intermediate thermal conditioning enables complex shape formation and stress relief prior to final forming operations.
- Forming:Final dimensional stabilization includes neck finish precision critical for capping line compatibility in automated bottling facilities.
Blow molding retains volume leadership, while pressing gains share in specialized chemical and cosmetic applications.
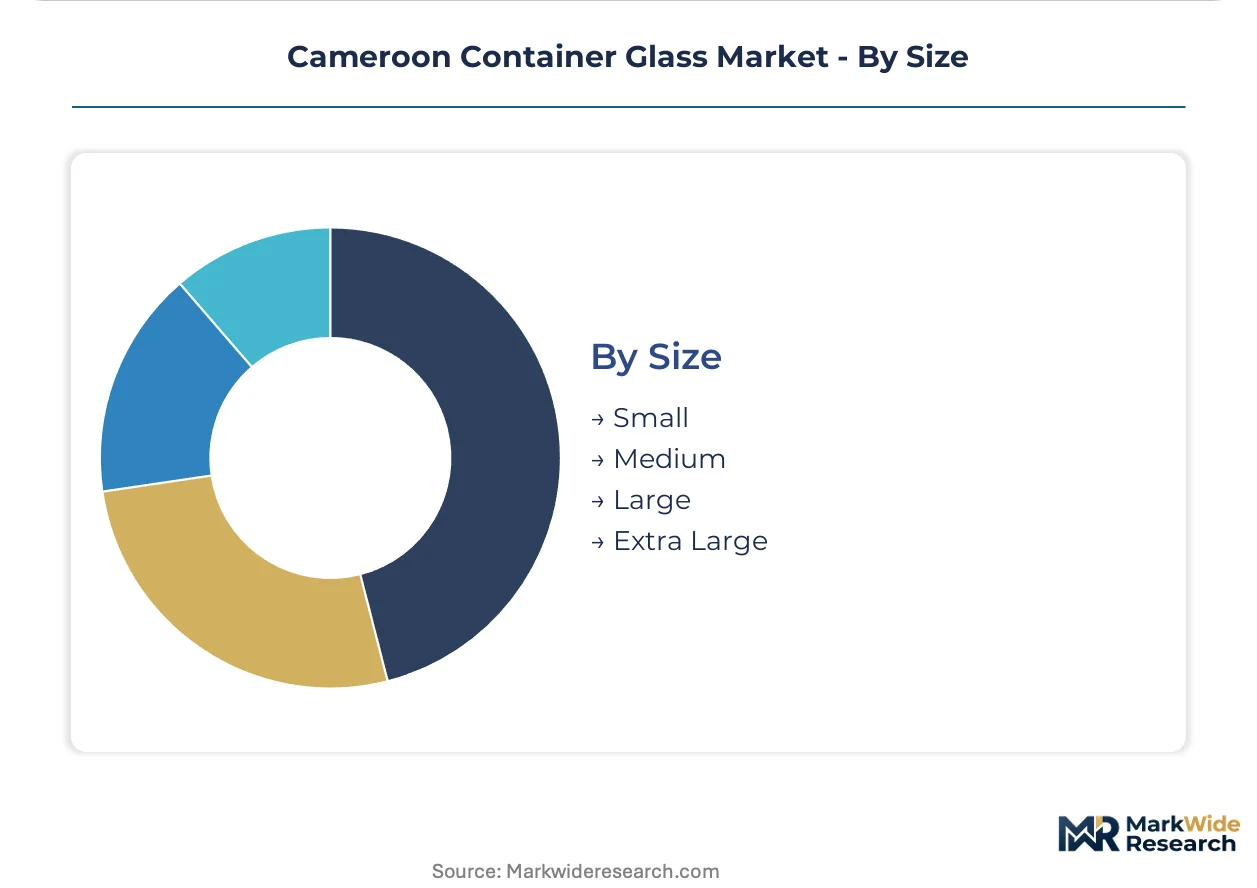
Size:
Logistics economics favor standardized pallet configurations, with medium formats optimizing container shipping density from Douala port infrastructure.
- Small:Pharmaceutical vials and sample containers minimize material per unit while maximizing laboratory and clinical distribution efficiency.
- Medium:Standard beverage bottles and food jars align with retail shelf spacing and automated filling line throughput specifications.
- Large:Family-size beverage containers and institutional food service formats test logistics weight limits for fragile glass shipments.
- Extra Large:Industrial chemical jugs and bulk storage containers require reinforced palletization and specialized handling equipment.
Medium formats dominate procurement volumes, while small sizes command premium unit economics in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and pharmaceutical buyers concentrate demand in distinct geographic corridors, with furnace operators calibrating output around Douala's brewery clusters and Yaoundé's emerging drug packaging requirements.
Littoral Region
Douala's industrial corridor hosts brewery and soft-drink bottling operations within 50 kilometers of port infrastructure. Cameroon's national standards body enforces food-contact material specifications that favor domestic furnace operators over undocumented imports. SOCAVER leverages integrated furnace operations to serve consolidated procurement volumes from beverage clients clustering around the Wouri River logistics hub.
Centre Region
Yaoundé's pharmaceutical corridor generates pull-through demand for amber glass vials as domestic generic drug production expands. The country's pharmaceutical regulator mandates drug packaging integrity protocols that require 18-24 month certification cycles. Fragmented sourcing patterns among quality assurance departments resist the supplier consolidation seen in beverage procurement.
South-West Region
Buea and Limbe municipalities anchor chemical storage applications requiring specialized amber glass compatibility certification. The Ministry of Industry oversees manufacturing process certifications affecting furnace emissions in this secondary industrial zone. CAMGLASS maintains production capacity through dedicated lines serving industrial fluid containment specifications.
West Region
Bafoussam's agro-processing facilities create demand for food preservation jars with reduced thermal stress requirements. Regional logistics networks connect this highland production zone to Douala port infrastructure for silica sand and soda ash feedstock delivery. Lightweighting innovations in wide-mouth configurations serve cosmetics applications expanding beyond traditional thermal resistance segments.
North-West Region
Bamenda's smaller-scale bottling operations test modular furnace economics for miniaturized production runs. Electric boosting systems supplement conventional fossil-fired melting to cut specific energy consumption per ton pulled. Hybrid furnace technology enables supply continuity during natural gas price volatility affecting imported fuel feedstock.
Cameroon Container Glass Market Competitive Landscape
Player mix skews toward integrated furnace operators with captive silica processing capabilities and specialized melting lines for borosilicate-grade requirements. The supplier base concentrates around two dominant archetypes: beverage-focused volume producers securing multi-year brewery contracts, and pharmaceutical-grade specialists absorbing extended certification timelines for amber glass validation. Strategic moves center on furnace dedication commitments extracted through procurement bundling, and geographic expansion into undercapitalized corridors where demand outpaces certified supply.
Within the integrated operator tier, Société Camerounaise de Verrerie (SOCAVER) and Cameroon Glass Factory (CAMGLASS) occupy positions exemplifying divergent specialization vectors. SOCAVER represents the beverage-contract archetype with furnace output rationalized around Douala corridor consolidation. CAMGLASS anchors the chemical-pharmaceutical niche through amber glass capacity serving storage applications and emerging drug packaging demand. Société de Développement du Verre (SODEV) sits within the development-focused segment, reflecting broader industrial policy support for domestic glass manufacturing capability.
| Leading Market Players |
|---|
| Société Camerounaise de Verrerie (SOCAVER) |
| Cameroon Glass Factory (CAMGLASS) |
| Société de Développement du Verre (SODEV) |
| Guinness Cameroon Glass Division |
| Central African Glass Industries |
| Cameroon Industrial Glass |
| Regional Glass Consortium |
| Societe des Verres du Cameroun |
| Cameroon Glass Company |
| Others |
Pricing and Supply Chain Analysis
Long-term furnace dedication contracts with natural gas indexation lock in supply access for Douala beverage bottlers while insulating SOCAVER and CAMGLASS from spot fuel price spikes. These agreements bundle multi-SKU procurement across pasteurization-grade bottles, embedding price visibility through the analysis window while concentrating buyer power among consolidated brewery clusters.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate procurement between Douala beverage clusters and integrated furnace operators. Price differentiation separates borosilicate-grade pharmaceutical vials from soda-lime beverage bottles, with certification tier and volume scale as primary drivers. Pricing pressure stems from PET substitution in non-pasteurized segments, compressing margins on standard bottle formats. Food and beverage buyers exhibit highest price sensitivity, while pharmaceutical quality assurance departments prioritize supply security over unit cost.
Supply Chain Analysis
Douala port clearance underwrites silica sand and soda ash feedstock delivery for Cameroon's container glass sector. Raw material sourcing draws from Egypt, Turkey, and Morocco for high-purity silica, while soda ash arrives through European trading hubs. Single-point-of-failure risk concentrates in maritime logistics chokepoints affecting furnace continuity. Distribution runs through brewery clusters within 50 kilometers of port infrastructure, minimizing handling costs for fragile finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cameroon's container glass sector sits at a platform-economics inflection where furnace operators must choose between beverage volume consolidation and pharmaceutical certification interoperability. The divergence between pasteurization-grade standards and borosilicate-grade requirements creates incompatible production ecosystems.
For Market Incumbents: Secure multi-year furnace dedication commitments from Douala brewery procurement teams before competitor capacity expansions reshape supply availability. Backward integration into captive silica processing insulates margin structures from currency-driven import cost spikes. Pharmaceutical certification investments separate viable suppliers from trading operations dependent on undocumented third-country imports. For New Entrants and Emerging Players: Drug packaging integrity fast-track programs offer entry into Yaoundé's pharmaceutical corridor where fragmented sourcing resists beverage-style consolidation. Lightweighting technology convergence in cosmetics applications presents the most penetrable white space, with thin-wall forming techniques enabling material reduction without strength compromise. Go-to-market positioning should target quality assurance departments prioritizing borosilicate-grade supply security over volume discounts. For Investors and Strategic Acquirers: Capital is best deployed toward integrated furnace operators with captive laboratory capabilities and in-process migration testing documentation. Long-term viability over the projection horizon hinges on regulatory compliance separation from import-dependent trading operations. Watch for packaging waste regulation announcements as the signal indicating closed-loop glass recycling economics favoring domestic furnace operators over single-use alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Processing | Captive feedstock supply insulates SOCAVER from Douala port disruption and currency volatility. |
| Pharmaceutical Certification Fast-Track | Amber glass validation compresses 18-24 month timelines for Yaoundé generic drug producers. |
| Electric Boosting System Deployment | Hybrid furnace technology cuts specific energy consumption per ton during natural gas price spikes. |
| Lightweighting Technology Convergence | Thin-wall forming with surface coating innovations enables material reduction without strength compromise. |
| Extended Producer Responsibility Alignment | Anticipated packaging waste regulations favor closed-loop glass recycling economics over PET alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, brewery procurement directors, pharmaceutical quality assurance leads, and Ministry of Industry certification officers and refined through secondary validation. Trade data from Douala port authorities, manufacturing process certifications from the national standards body, and energy consumption disclosures from integrated operators anchored quantitative sizing. Bottom-up tonnage estimates from individual furnace outputs triangulated against top-down demand aggregation from beverage and pharmaceutical end-use sectors.
Variance decomposition across product type, end-use industry, manufacturing process, and geographic corridor dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included natural gas price trajectory assumptions, pharmaceutical production capacity buildout in Yaoundé, and PET substitution elasticity in non-pasteurized beverage segments across the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of continued brewery cluster consolidation and stable regulatory compliance timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as packaging waste regulation evolution and furnace technology substitution economics shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Panama Container Glass Market