
 United Arab Emirates Glass Packaging Market | 2026-2036
United Arab Emirates Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Glass Packaging Market Analytics
The UAE glass packaging market is shifting along a widening fault line between premium pharmaceutical-grade borosilicate and commodity soda-lime containers for mass-market beverages. RAK Ghani Glass leverages captive sand reserves and furnace scale to dominate the commodity tier across the northern emirates. Emirates Glass differentiates through decorative coating capabilities that serve cosmetics houses seeking shelf differentiation in Dubai's retail channels. Frigo Glass specializes in temperature-stable pharmaceutical formats that sustain compliance with Gulf health authority cold-chain mandates.
Glass packaging denotes rigid containers formed from silica, sodium carbonate, and calcium oxide melted at temperatures exceeding 1500°C, then molded into bottles, jars, or tubes for product protection, shelf stability, and consumer safety. The material's chemical inertness makes it indispensable for oxygen-sensitive pharmaceuticals and acidic food preserves. Bottles and jars anchor the product mix, with pharmaceutical tubes representing the fastest-expanding margin pool as biologic injectables gain formulary share in the UAE. Food and beverages still occupy the largest end-user volume, though cosmetics applications are concentrating in high-value fragrance and serum segments where amber and cobalt glass command price premiums.
MOHAP enforces pharmaceutical packaging standards that align with Gulf Central Committee for Drug Registration guidelines, while the Emirates Authority for Standardization and Metrology certifies food-contact glass under UAE-specific conformity schemes. These frameworks compel importers to maintain batch-level traceability and heavy-metal testing documentation, effectively raising barriers for uncertified Asian suppliers. Stakeholders must monitor how Abu Dhabi's industrial diversification agenda reshapes local furnace investment timelines and whether Saudi Arabia's emerging glass capacity redirects GCC trade flows away from UAE ports.
Market Dynamics
MOHAP's tightened material-safety protocols for injectable pharmaceuticals are compressing procurement timelines and forcing manufacturers to pre-qualify borosilicate suppliers before formulary approval, creating a structural bottleneck that favors certified domestic furnace operators over opportunistic importers.
Growth Catalysts
- Biologics cold-chain mandates:MOHAP's traceability requirements for temperature-stable vials are pulling pharmaceutical-grade borosilicate demand into the Jebel Ali corridor, where logistics infrastructure supports just-in-time GCC delivery.
- Emirates Authority for Standardization and Metrology food-contact certification:Batch-level heavy-metal testing documentation requirements are raising barriers for uncertified Asian suppliers, securing market share for UAE-based furnace operators.
- Cosmetics shelf differentiation:Decorative coating capabilities are capturing premium fragrance and serum segments where amber and cobalt glass command price premiums in Dubai's retail channels.
Market Restraints
- Natural gas input volatility:Furnace operations depend on subsidized UAE gas feedstock; any tariff recalibration would compress margins for energy-intensive soda-lime commodity production.
- Captive sand reserve concentration:Northern emirates' silica deposits are controlled by legacy operators, limiting new entrant access to low-cost raw material inputs.
- Aluminum and polymer substitution:Lightweight beverage cans and barrier plastics are displacing glass in mass-market carbonated drinks, constraining volume growth in the largest end-use category.
Strategic Opportunities
- Abu Dhabi industrial diversification incentives:The emirate's manufacturing localization agenda is channeling capital toward new furnace investments that could rebalance production gravity away from Ras Al Khaimah.
- Pharmaceutical tube convergence with prefilled syringes:Biologic delivery formats are merging glass primary packaging with polymer plunger systems, opening technical partnerships between glass specialists and medical device engineers.
- E-commerce direct-to-consumer fragrance channels:Unboxing aesthetics and breakage-resistant secondary packaging are driving demand for decorated glass with reinforced shipping profiles.
Industry Challenges
- Borosilicate furnace engineering talent scarcity:Specialized high-temperature process engineers with pharmaceutical-grade certification experience are concentrated among a handful of incumbent operators.
- MOHAP batch traceability system integration:Legacy ERP platforms at mid-tier converters require costly upgrades to achieve real-time serialization compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Glass Packaging Market |
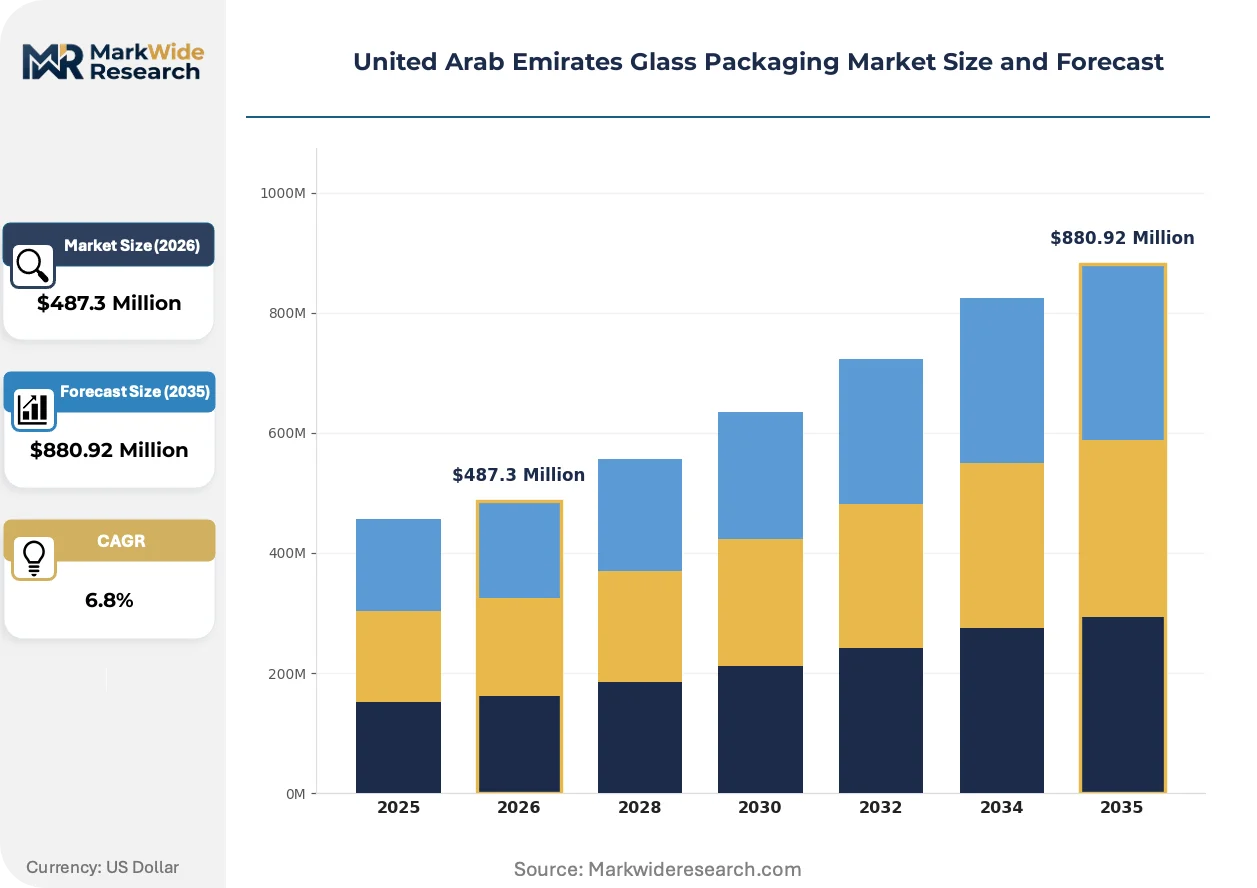
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Pans, Tubes End User: Food, Beverages, Pharmaceuticals, Cosmetics Packaging Type: Container, Closure, Blister Pack, Sleeve Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | RAK Ghani Glass, Nipro Corporation, Frigo Glass, Emirates Glass, Al Tajir Glass Industries, Saverglass, Beatson Clark, National Glass Industry, Corning Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Glass Packaging Market Evolving Landscape
Digital furnace control systems and automated inspection technologies are compressing defect rates while enabling smaller production runs, allowing UAE operators to serve niche pharmaceutical and cosmetics segments without sacrificing economies of scale.
Electrochemical glass toughening is decentralizing production flexibility across the Emirates. This ion-exchange surface compression technology strengthens thin-walled pharmaceutical vials against thermal shock. Dubai-based cosmetics houses are adopting it for premium serum bottles that travel through GCC distribution networks. The process is decentralizing quality control from centralized European licensors to local furnace operators who can now certify in-house.
MOHAP's alignment with Gulf Central Committee for Drug Registration guidelines is tightening documentation burdens for imported glass. The framework now mandates batch-level heavy-metal certificates and sterilization validation records. Pharmaceutical manufacturers are responding by consolidating supplier panels around UAE-based borosilicate producers who maintain integrated testing laboratories.
Hospital procurement consortia are compressing supplier qualification cycles from multi-year frameworks to annual performance reviews. Group purchasing organizations in Abu Dhabi and Dubai are aggregating demand across private healthcare networks. This concentration is favoring glass converters with dedicated pharmaceutical account teams and localized technical service capabilities over distant European exporters.
United Arab Emirates Glass Packaging Market Segmentation
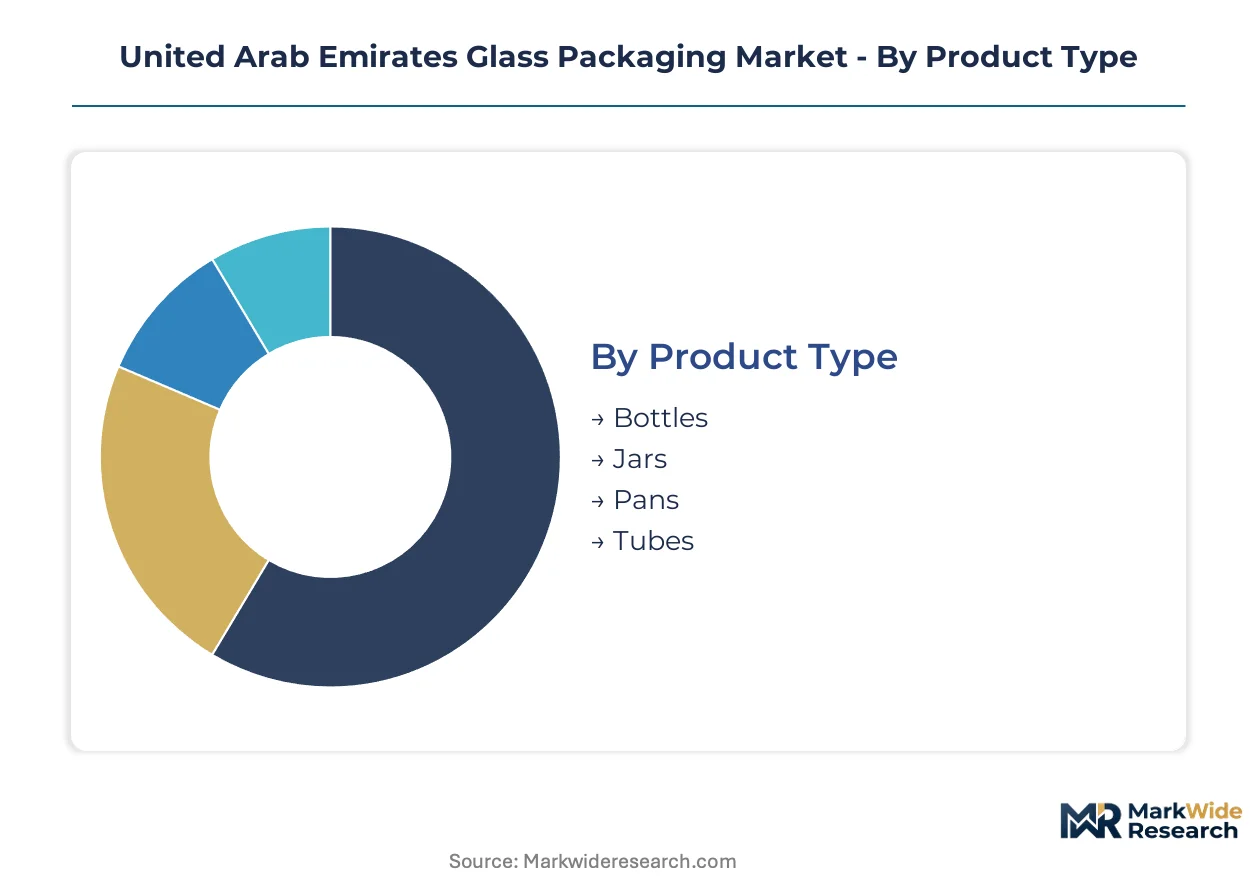
Glass packaging procurement in the UAE diverges sharply across certification tiers. Pharmaceutical formats demand MOHAP-validated borosilicate traceability, while food-contact applications operate under Emirates Authority for Standardization and Metrology conformity schemes. Understanding these regulatory boundaries determines supplier qualification pathways and margin capture potential.
Product Type:
MOHAP mandates distinguish borosilicate pharmaceutical formats from soda-lime commodity containers, with certification burdens falling heaviest on temperature-stable vials and least on standard beverage bottles.
- Bottles:Soda-lime silica composition dominates mass-market beverage and food preserve applications. Demand concentrates in Dubai's retail channels where amber and cobalt tinting commands shelf differentiation premiums for premium spirits and olive oils. Emirates Authority for Standardization and Metrology food-contact certification applies.
- Tubes:Borosilicate construction withstands thermal shock during sterilization cycles for biologic injectables. MOHAP's traceability protocols and Gulf Central Committee for Drug Registration alignment force pre-qualification of suppliers before formulary approval, creating structural bottlenecks.
- Jars:Wide-mouth soda-lime formats serve honey, preserves, and cosmetics cream segments with lower certification thresholds than pharmaceutical grades.
- Pans:Shallow-profile borosilicate dishes target laboratory and specialized pharmaceutical preparation uses requiring chemical inertness.
Leading the category by volume: Bottles. Growing fastest: Tubes.
End User:
Cost tiers separate premium pharmaceutical validation from commodity food-contact compliance, with cosmetics occupying a mid-tier position where decorative capabilities justify price premiums.
- Pharmaceuticals:Injectable biologics drive borosilicate vial demand under MOHAP cold-chain mandates. Batch-level heavy-metal testing and sterilization validation records consolidate procurement around UAE-based furnace operators with integrated laboratories. Jebel Ali logistics infrastructure supports just-in-time GCC delivery.
- Food:Soda-lime jars and bottles for preserves, sauces, and condiments represent the largest volume pool. Emirates Authority for Standardization and Metrology certification requirements raise barriers for uncertified Asian suppliers, protecting domestic furnace share.
- Cosmetics:Decorative coating capabilities for fragrance and serum segments command price premiums in Dubai's retail channels. Electrochemical toughening enables thin-walled premium formats.
- Beverages:Mass-market carbonated drinks face aluminum can and polymer substitution pressure, constraining glass volume growth despite captive sand reserve advantages in northern emirates.
Volume leadership: Food. Steepest expansion trajectory: Pharmaceuticals.
Packaging Type:
Application requirements dictate material specification, with primary containers facing stricter regulatory burdens than secondary closure and sleeve components.
- Container:Primary glass bottles and jars constitute the core revenue pool across all end-use segments, with pharmaceutical grades requiring borosilicate certification.
- Closure:Aluminum and polymer caps, stoppers, and seals interface with glass neck finishes; less stringent than primary container standards.
- Blister Pack:Thermoformed polymer cavities with lidding films compete with glass for unit-dose pharmaceutical applications.
- Sleeve:Shrink-label and decorative secondary packaging adds shelf differentiation without direct food-contact or pharmaceutical compliance burdens.
Dominant by revenue: Container. Gaining technical investment: Closure systems integrating with prefilled syringe formats.
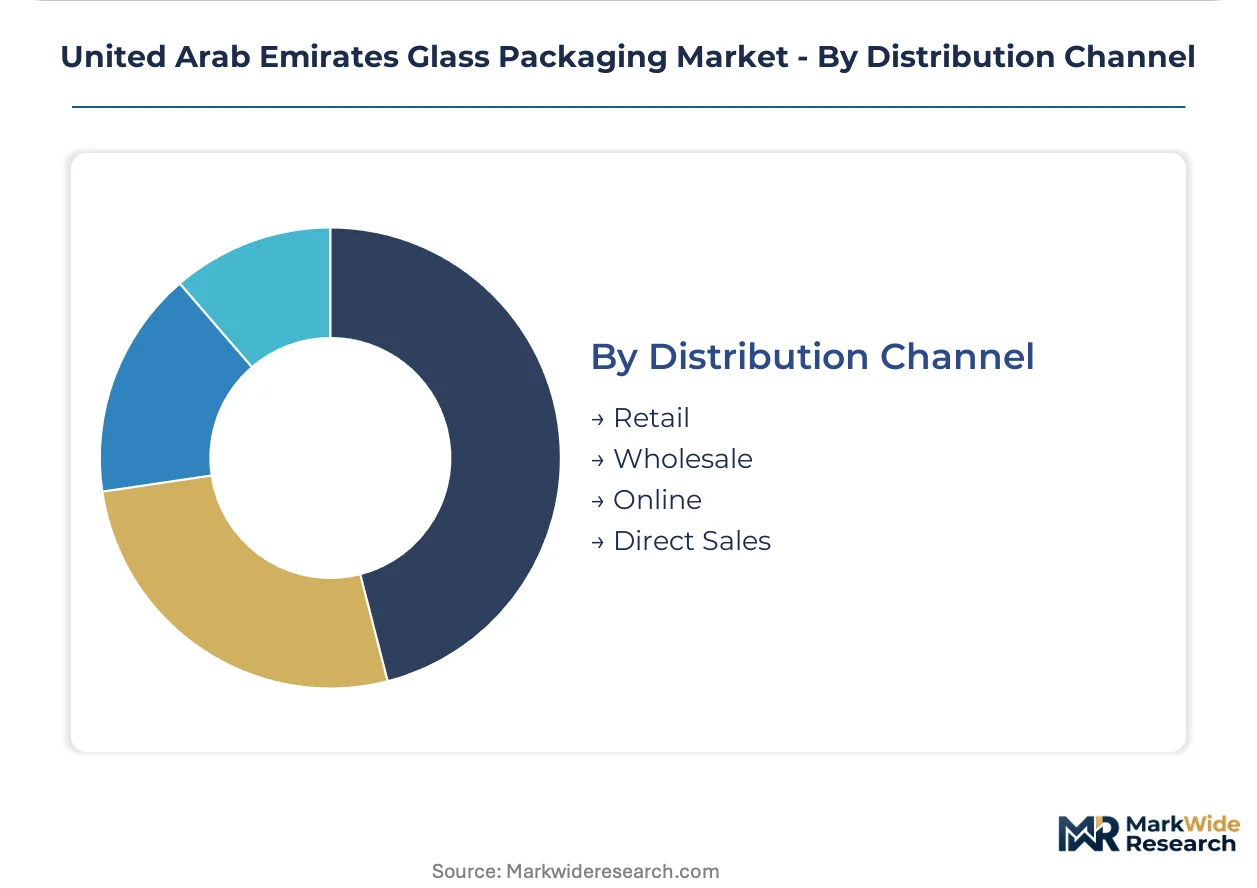
Distribution Channel:
Customer type determines service intensity, with direct pharmaceutical procurement requiring technical account teams and wholesale beverage channels prioritizing logistics efficiency.
- Wholesale:Bulk beverage and food container movement through Jebel Ali corridor to GCC markets leverages economies of scale and just-in-time delivery infrastructure.
- Direct Sales:Pharmaceutical manufacturers and cosmetics houses demand localized technical service, batch traceability integration, and annual performance reviews through hospital procurement consortia.
- Retail:Supermarket and hypermarket channels for premium spirits, olive oils, and cosmetics gift sets.
- Online:E-commerce fragrance direct-to-consumer growth drives demand for breakage-resistant secondary packaging and unboxing aesthetics.
Volume concentration: Wholesale. Fastest channel expansion: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali anchors UAE glass packaging logistics, with its port infrastructure enabling just-in-time pharmaceutical delivery across Gulf Cooperation Council markets. The corridor's cold-chain capabilities support MOHAP-mandated borosilicate distribution for temperature-sensitive biologics.
Dubai
Pharmaceutical-grade borosilicate demand concentrates in Dubai's Jebel Ali industrial zone, where logistics infrastructure supports just-in-time delivery to Saudi Arabia and Kuwait. MOHAP's traceability protocols for injectables force pre-qualification of suppliers before formulary approval. Cosmetics houses in Dubai's retail channels drive decorative coating demand for amber and cobalt glass in premium fragrance segments.
Abu Dhabi
Hospital procurement consortia in Abu Dhabi aggregate glass packaging demand across private healthcare networks, compressing supplier qualification cycles to annual performance reviews. The emirate's industrial diversification agenda channels capital toward new furnace investments. Khalifa Industrial Zone is emerging as a secondary production node with subsidized utility tariffs for energy-intensive soda-lime operations.
Ras Al Khaimah
Captive silica sand reserves in the northern emirates anchor commodity-grade soda-lime production for mass-market beverages and food preserves. RAK Ghani Glass leverages these deposits to dominate standard container output. Emirates Authority for Standardization and Metrology certification requirements protect domestic furnace operators from uncertified Asian import competition.
Sharjah
Mid-tier glass converters in Sharjah's industrial areas face ERP upgrade costs to achieve MOHAP batch traceability compliance. The emirate's logistics positioning between Dubai and northern production centers supports distribution efficiency for wholesale beverage channels. Electrochemical toughening technology adoption is decentralizing quality control from European licensors to local operators.
Northern Emirates
Ajman and Umm Al Quwain host smaller converters serving regional food-contact markets with lower certification thresholds than pharmaceutical grades. These operations benefit from proximity to Ras Al Khaimah sand reserves while avoiding premium real estate costs. Natural gas subsidy dependence creates margin vulnerability if federal tariff structures recalibrate.
United Arab Emirates Glass Packaging Market Competitive Landscape
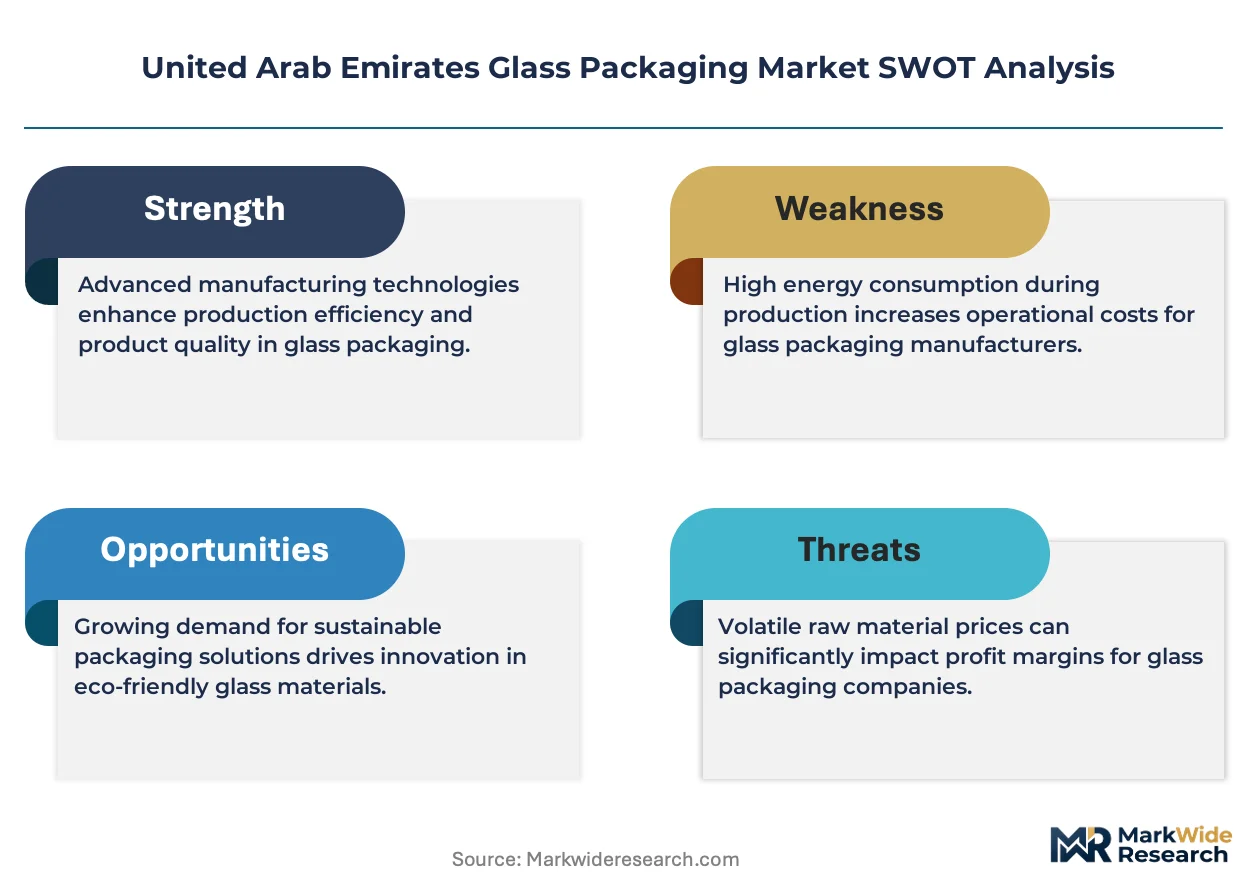
Premium-margin players sit above commodity-margin players across certification tiers, with MOHAP-validated borosilicate specialists commanding structural scarcity rents while soda-lime commodity producers compete on captive sand access and furnace scale. The market structures around three archetypes: integrated furnace operators with captive raw material reserves, specialized pharmaceutical-grade converters with laboratory certification capabilities, and decorative coating specialists serving cosmetics shelf differentiation. Dominant competitive moves include backward integration into silica sand mining and technology licensing partnerships for electrochemical toughening processes.
Among UAE-based integrated operators, RAK Ghani Glass exemplifies the commodity-tier archetype through its control of northern emirates sand reserves, while Emirates Glass occupies a position in decorative coating capabilities for premium retail channels. Frigo Glass represents the pharmaceutical-specialist vector with temperature-stable format expertise aligned to MOHAP cold-chain mandates. Nipro Corporation, a Japanese Co., Ltd., anchors the multinational certified-supplier tier serving hospital procurement consortia with integrated testing documentation.
| Leading Market Players |
|---|
| RAK Ghani Glass |
| Nipro Corporation |
| Frigo Glass |
| Emirates Glass |
| Al Tajir Glass Industries |
| Saverglass |
| Beatson Clark |
| National Glass Industry |
| Corning Incorporated |
| Others |
Value Network & Pricing Analysis
MOHAP's batch traceability mandates for pharmaceutical-grade borosilicate gate both qualified supply access and premium-tier pricing power, forcing buyers to pay certification premiums for furnace operators with integrated testing laboratories while marginalizing uncertified importers from Asian markets.
Pricing Analysis
Outcome-based pricing anchors pharmaceutical vial procurement, where per-unit costs scale with sterilization validation documentation and cold-chain performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates MOHAP-validated borosilicate from Emirates Authority for Standardization and Metrology-certified food-contact grades and commodity soda-lime beverage containers. Cost compression in mass-market soda-lime runs through aluminum can substitution and captive sand reserve concentration among northern emirates legacy operators. Beverage bottlers exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for traceability assurance.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle temperature-sensitive biologics demand, with Jebel Ali logistics infrastructure enabling just-in-time GCC delivery. Geographic supply concentration centers on Ras Al Khaimah's captive silica deposits, Dubai's pharmaceutical-grade converter corridor, and Abu Dhabi's emerging Khalifa Industrial Zone furnace investments. Raw material dependencies draw from UAE natural gas feedstock subsidies, European borosilicate furnace engineering talent, and specialized ion-exchange toughening chemistry. Single-source vulnerability in pharmaceutical-grade borosilicate certification expertise creates structural bottlenecks. Distribution runs through wholesale bulk beverage movement and direct technical account teams for cosmetics houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where MOHAP's tightened material-safety protocols for injectables erect a barrier-to-entry moat that consolidates procurement around certified domestic furnace operators.
For Market Incumbents: Extend laboratory certification capabilities to capture hospital procurement consortia's compressed supplier qualification cycles. Deepen backward integration into northern emirates silica sand reserves to defend against emerging Abu Dhabi furnace investments. Aluminum and polymer substitution in carbonated beverages threatens soda-lime volume; redirect capacity toward pharmaceutical tube and electrochemical toughening cosmetics formats.
For New Entrants and Emerging Players: Begin with mid-tier cosmetics coating services in Sharjah's industrial zones, where decorative capabilities command price premiums without MOHAP pharmaceutical validation burdens. Target e-commerce direct-to-consumer fragrance channels demanding breakage-resistant secondary packaging and unboxing aesthetics. Partner with European licensors for electrochemical toughening technology transfer rather than competing on furnace scale.
For Investors and Strategic Acquirers: Abu Dhabi industrial diversification capital commitments are the leading indicator that production gravity will rebalance away from Ras Al Khaimah sand reserve concentration. Five-to-ten year viability favors integrated operators with captive raw material access and pharmaceutical certification capabilities. Watch for MOHAP alignment with Gulf Central Committee for Drug Registration guidelines as the signal for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Mining | Captive supply of northern emirates reserves secures cost advantage against Abu Dhabi entrants. |
| Electrochemical Toughening Technology Licensing | Ion-exchange surface compression enables thin-walled pharmaceutical vial certification in-house. |
| MOHAP Batch Traceability System Integration | Real-time serialization compliance qualifies operators for hospital procurement consortia panels. |
| Pharmaceutical Tube-Prefilled Syringe Convergence | Technical partnerships with medical device engineers open biologic delivery format opportunities. |
| E-commerce Breakage-Resistant Secondary Packaging | Reinforced shipping profiles capture direct-to-consumer fragrance channel expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across furnace operations managers, pharmaceutical procurement directors, cosmetics brand supply chain leads, and Emirates Authority for Standardization and Metrology certification officers. Bottom-up modeling of installed furnace capacity and throughput rates triangulated against top-down consumption estimates from MOHAP pharmaceutical packaging registrations and food-contact import volumes.
Segment-level granularity modeled product type splits across borosilicate pharmaceutical formats and soda-lime commodity containers, end-user divergence between cold-chain biologics and mass-market beverages, and distribution channel differentiation between wholesale GCC logistics and direct technical account service. CAGRs were derived from trend extrapolation of certification burden intensification and substitution elasticity in beverage applications. Forecast inputs incorporated natural gas tariff policy scenarios and Saudi Arabia emerging glass capacity trade flow redirection risks.
Underlying measurement precision varies by segment; pharmaceutical-grade borosilicate carries tighter precision than commodity soda-lime given consolidated supplier panels and mandatory registration data. Forecasts reflect assumptions around MOHAP enforcement continuity, Gulf Central Committee for Drug Registration alignment timelines, and northern emirates sand reserve depletion curves. Periodic stress-testing of base assumptions is recommended against regulatory recalibration or federal energy subsidy restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Russia Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Spain Packaging Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Dosing Bottles Market