
 Foam Bottle Technology Market | 2026-2036
Foam Bottle Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Bottle Technology Market Foresight
Premium-grade airless foam specifications is collapsing the gap between mass-market dispensers and pharmaceutical-grade delivery systems. XINGYUAN leverages its integrated PET blow-molding capacity to supply Korean and Southeast Asian cosmetics contract manufacturers. Guangzhou Talents Cosmetics Packaging anchors its position through dedicated micro-foam generation R&D for skincare mousse applications. Alpla competes by extending its European blow-molding network into foam-specific neck finishes and actuator designs.
Foam bottle technology encompasses pressurized and non-pressurized container systems engineered to transform liquid formulations into stable, dispensed foam through mechanical agitation, gas propellant, or airless pump mechanisms, typically operating at 1.5–3.5 bar internal pressure with foam densities between 0.05–0.25 g/cm³ for controlled dosing in personal care and industrial applications. Pressurized systems dominate current volume owing to mature aerosol infrastructure and lower unit conversion costs for legacy brands, while airless pump technology captures expanding margin pools as cosmetic houses reformulate around preservative-free and oxygen-sensitive actives. Pharmaceutical dispensing applications represent the fastest-growing segment as metered-dose foam bottles gain traction for topical hormone therapies and dermatological treatments requiring precise volumetric delivery.
FDA's combination product regulations govern foam-dispensed drug formulations in the United States, requiring container closure system validation that extends development timelines and elevates barrier-to-entry for new entrants. REACH restrictions on fluorinated propellants and the EU F-Gas Regulation are forcing European manufacturers toward mechanical foaming and compressed gas alternatives, reshaping material selection and valve engineering specifications. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables testing, as regulatory convergence between FDA and EMA on container qualification protocols will determine which packaging technologies secure multi-region drug product approvals.
Market Dynamics
Airless pump mechanisms are compressing the traditional divide between cosmetic and pharmaceutical dispensing systems, forcing material suppliers and contract manufacturers to recalibrate barrier specifications and validation protocols simultaneously.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants accelerates European conversion toward mechanical foaming systems, opening contract manufacturing slots for compressed gas valve engineering specialists.
- Topical hormone therapies:Metered-dose foam bottles for dermatological and transdermal drug delivery command premium qualification fees, pulling pharmaceutical packagers into multi-layer barrier development.
- Rhine-Main corridor concentration:Germany's contract packaging cluster serves pan-European personal care multinationals, generating economies of scale in foam-specific blow-molding and actuator assembly.
Market Restraints
- Fluorinated propellant phaseout costs:REACH restrictions on per- and polyfluoroalkyl substances force reformulation of legacy aerosol products, stranding existing valve inventories and specialized filling equipment.
- Barrier resin concentration:Cyclic olefin copolymer and high-density polyethylene supply for pharmaceutical-grade bottles clusters with Asian petrochemical processors, exposing European converters to freight and tariff volatility.
- FDA combination product timelines:Container closure system validation for drug-device foam dispensers extends development cycles by 18-36 months versus cosmetic equivalents, freezing capital in qualification protocols.
Strategic Opportunities
- South Korean premium skincare:Seoul-based cosmetics houses are specifying airless micro-foam dispensers for preservative-free essences, creating demand for precision-molded PET-G bottles with sub-milliliter dosing accuracy.
- EMA-FDA regulatory convergence:Harmonized extractables and leachables testing protocols for multi-region drug approvals reward packagers with dual-qualified quality systems and pre-validated master files.
- Biopolymer integration:Fermentation-derived polyhydroxyalkanoates and chemically recycled PET are converging in pilot foam bottle programs targeting brand sustainability commitments and EU Packaging and Packaging Waste Regulation material recovery thresholds.
Industry Challenges
- Multilayer co-injection molding expertise:The scarcity of technicians trained in EVOH barrier layer distribution control within PET bottles limits European and North American capacity expansion for oxygen-sensitive pharmaceutical foams.
- Legacy aerosol line retrofitting:Mechanical foaming equipment requires incompatible filling pressures and capping torques versus traditional bag-on-valve systems, forcing contract packagers to duplicate infrastructure or abandon mixed-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Bottle Technology Market |
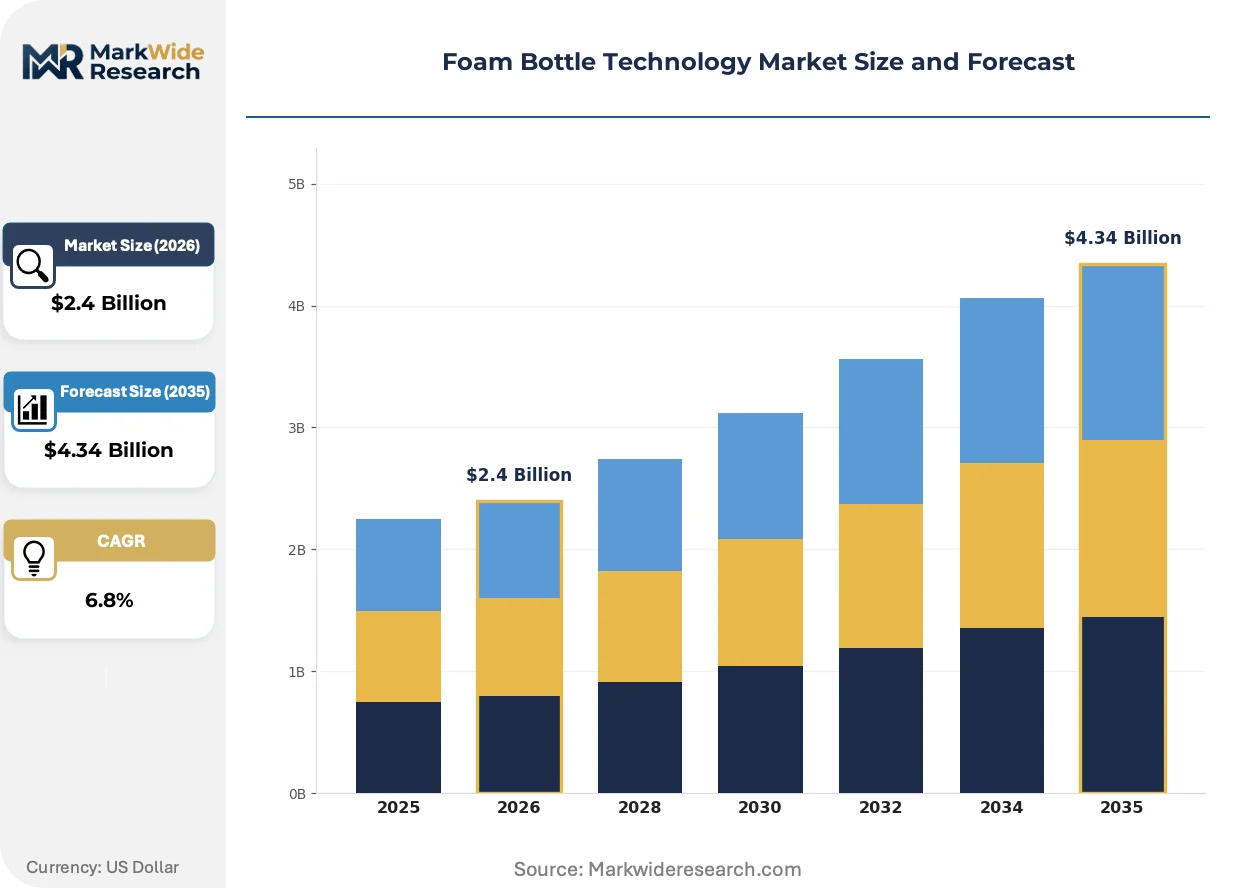
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressurized, Non-Pressurized, Powder Dispensing, Trigger Foam, Combination Foam, Others Technology: Micro-foam Generation, Electrostatic Foam, Mechanical Foaming, Airless Pump, Trigger Spray, Metered Dose Application: Cosmetics, Personal Hygiene, Industrial Cleaning, Food Service, Pharmaceutical Dispensing, Pet Care End User: Contract Manufacturers, Retail Chains, Wholesalers, Specialty Stores, Online Vendors, Distributors |
| Companies Covered | XINGYUAN, Guangzhou Talents Cosmetics Packaging, Choebe, Yuhuan Chumen Micro-Sprayer, Yuheng Plastic, Yuhua Packing, DAISHO GLASS Co.,Ltd, Alpla, Jebsen & Jessen Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Bottle Technology Market Shifts & Advancements
Reformulation around oxygen-sensitive actives and preservative-free claims is rewiring material selection and barrier engineering priorities across personal care and pharmaceutical segments simultaneously.
Airless foam generation technology is bifurcating the dispenser market into two distinct performance tiers. High-precision piston pump systems with metal-free fluid paths now serve South Korean skincare brands demanding sub-0.1 ml dose consistency for mousse-textured essences. This technical specification compression is collapsing the historical gap between cosmetic novelty dispensers and validated pharmaceutical delivery systems, forcing shared suppliers to maintain dual quality management systems.
REACH restrictions on fluorinated propellants are compelling European manufacturers toward compressed gas and mechanical alternatives. The EU F-Gas Regulation's phasedown schedule accelerates valve engineering redesigns for hydrocarbon and nitrogen-powered foam systems. Personal care brands with pan-European distribution are most exposed, responding with accelerated qualification of bag-in-bottle and piston pump architectures that bypass propellant chemistry entirely.
Cosmetics procurement teams now specify foam bottle systems through dedicated packaging innovation labs rather than traditional component catalogs. Seoul and Tokyo-based beauty conglomerates embed technical packaging directors within formulation development teams, collapsing the sequential development timeline. This integration pattern is most visible in South Korea, where MFDS cosmetic safety reporting requirements and brand sustainability pledges converge to demand pre-validated, documentation-ready airless systems at concept stage.
Foam Bottle Technology Market Segmentation
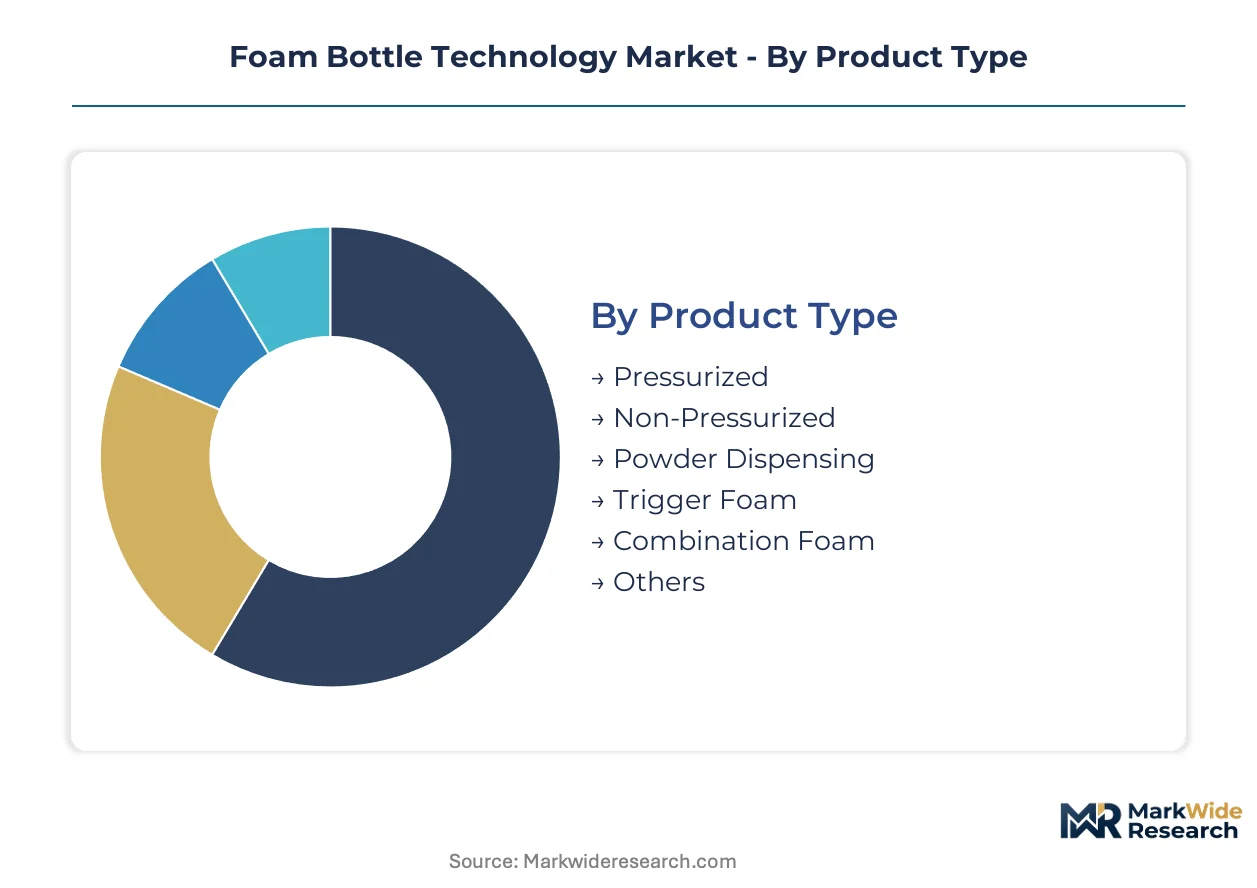
Foam bottle technology segments along four intersecting dimensions: pressure mechanics, generation methods, use cases, and procurement channels. Each dimension carries distinct regulatory, technical, and margin characteristics that determine competitive positioning and qualification requirements.
Product Type:
FDA combination product rules and REACH propellant restrictions split this category into regulated pharmaceutical-grade systems and consumer-grade alternatives with divergent validation burdens.
- Pressurized:Traditional aerosol systems using hydrocarbon or compressed gas propellants operate at 1.5–3.5 bar internal pressure. Demand concentrates in legacy personal care brands serving pan-European distribution, though EU F-Gas Regulation phasedown is forcing valve engineering redesigns and equipment replacement cycles.
- Non-Pressurized:Mechanical and airless pump systems eliminate propellant chemistry entirely through piston or bag-in-bottle architectures. South Korean cosmetics houses specify these for preservative-free essences, collapsing development timelines by embedding technical packaging directors within formulation teams.
- Powder Dispensing:Dual-chamber systems combine liquid and powder components at point of use for effervescent or reactive formulations.
- Trigger Foam:Hand-actuated pump mechanisms for high-volume household and industrial applications with lower precision requirements.
- Combination Foam:Hybrid architectures integrating multiple dispensing modes within single container systems for multi-phase products.
- Others:Specialty formats including squeeze-foam and wipe-dispensing configurations for niche veterinary and medical applications.
Established volume favors Pressurized; emerging adoption favors Non-Pressurized.
Technology:
Cost tiers separate precision-molded pharmaceutical systems from commodity consumer dispensers, with barrier specifications and metal-free fluid paths commanding qualification premiums.
- Micro-foam Generation:Precision-molded PET-G bottles with sub-milliliter dosing accuracy achieve foam densities between 0.05–0.25 g/cm³ through controlled mechanical agitation. Seoul-based beauty conglomerates specify these for mousse-textured essences, demanding documentation-ready systems at concept stage to satisfy MFDS cosmetic safety reporting.
- Metered Dose:Volumetrically precise delivery systems for topical hormone therapies and dermatological treatments requiring validated container closure systems under FDA combination product regulations. The 18-36 month qualification timeline elevates barriers to entry and freezes capital in protocol documentation.
- Electrostatic Foam:Charged particle systems for specialized industrial coating and adhesive applications with limited personal care penetration.
- Mechanical Foaming:Compressed gas and nitrogen-powered alternatives replacing fluorinated propellants under EU F-Gas Regulation phasedown schedules.
- Airless Pump:Piston-based systems with oxygen exclusion for preserv-free and active-sensitive formulations across cosmetics and pharmaceuticals.
- Trigger Spray:Cost-optimized hand-pump architectures for high-volume household cleaning and food service sanitation.
Commodity scale concentrates in Trigger Spray and Mechanical Foaming; margin expansion concentrates in Micro-foam Generation and Metered Dose.
Application:
Customer procurement patterns diverge between regulated pharmaceutical channels and fast-moving consumer goods with distinct validation and speed-to-market requirements.
- Pharmaceutical Dispensing:Metered-dose foam bottles for transdermal drug delivery command premium qualification fees and require EVOH barrier layers for oxygen-sensitive actives. EMA-FDA regulatory convergence on extractables and leachables testing rewards packagers with dual-qualified quality systems.
- Cosmetics:Airless micro-foam dispensers for premium skincare routines anchor demand in South Korea, where brand sustainability pledges and regulatory requirements converge to pre-validate packaging at concept stage.
- Personal Hygiene:Mass-market hand soap and body wash applications with standardized actuator specifications and compressed production cycles.
- Industrial Cleaning:High-chemical-resistance containers for solvent-based foaming agents with reduced barrier requirements.
- Food Service:Sanitation and cleaning applications governed by national food safety regulators with surface contact and residue specifications.
- Pet Care:Veterinary dermatology and grooming formulations with intermediate regulatory scrutiny between pharmaceutical and cosmetic tiers.
Regulatory complexity peaks in Pharmaceutical Dispensing; volume velocity peaks in Personal Hygiene.
End User:
Supply chain configuration determines whether foam bottle procurement flows through integrated manufacturing or fragmented distribution intermediaries.
- Contract Manufacturers:Germany's Rhine-Main corridor hosts packagers serving pharmaceutical and personal care multinationals with integrated blow-molding and actuator assembly. These operators generate economies of scale in foam-specific neck finishes while maintaining dual quality management systems for cosmetic and pharmaceutical specifications.
- Retail Chains:Mass-market personal care brands with standardized specifications and compressed development timelines.
- Wholesalers:Intermediate distributors serving regional and independent brand portfolios with limited technical specification control.
- Specialty Stores:Premium and professional-grade product channels with customized packaging requirements and smaller batch scales.
- Online Vendors:Direct-to-consumer brands with rapid iteration cycles and sustainability-forward material specifications.
- Distributors:Logistics-focused intermediaries with limited influence over technical packaging decisions.
Technical capability concentrates in Contract Manufacturers; channel fragmentation concentrates in Wholesalers and Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packaging capacity clusters along Germany's Rhine-Main corridor, where integrated blow-molding and actuator assembly serve pharmaceutical and personal care multinationals. Korean cosmetics houses drive airless micro-foam specifications through Seoul-based innovation labs. Regulatory divergence between FDA combination product rules and EMA extractables protocols shapes qualification strategies.
Germany
Rhine-Main manufacturing hosts packagers supplying pan-European personal care brands with foam-specific neck finishes. EU F-Gas Regulation phasedown accelerates valve engineering redesigns toward compressed gas alternatives. Frankfurt-Darmstadt contract manufacturers generate economies of scale in EVOH barrier layer distribution for oxygen-sensitive pharmaceutical foams.
South Korea
Seoul-based beauty conglomerates embed technical packaging directors within formulation teams, collapsing sequential development timelines. MFDS cosmetic safety reporting requirements converge with brand sustainability pledges to demand pre-validated airless systems at concept stage. Busan-Ulsan corridor converters supply precision-molded PET-G bottles with sub-milliliter dosing accuracy for mousse-textured essences.
United States
FDA combination product regulations govern foam-dispensed drug formulations, requiring container closure system validation that extends development timelines. Topical hormone therapies and dermatological treatments pull pharmaceutical packagers into multi-layer barrier development. New Jersey and Pennsylvania pharmaceutical packaging clusters specialize in metered-dose qualification protocols.
China
Guangzhou and Zhejiang province PET blow-molding capacity supplies Korean and Southeast Asian cosmetics contract manufacturers. REACH-aligned export requirements reshape material selection for European-bound production. Yangtze River Delta converters face freight and tariff volatility exposure on cyclic olefin copolymer and high-density polyethylene resin imports.
Switzerland
Swissmedic pharmaceutical packaging standards anchor premium qualification requirements for transdermal drug delivery systems. Dual-qualified quality systems serving EMA-FDA regulatory convergence reward packagers with pre-validated master files. Basel-region technical centers specialize in extractables and leachables testing protocol harmonization.
Foam Bottle Technology Market Competitive Landscape
Concentration sits with integrated blow-molding specialists and dedicated cosmetics packaging engineers. The supplier base segments into three archetypes: multinational rigid packaging networks with foam-specific actuator capabilities, Asian contract manufacturers with PET-G precision molding expertise, and regional glass and plastic converters serving niche pharmaceutical applications. Dominant competitive moves include capacity expansion in airless pump assembly lines and strategic partnerships between resin suppliers and valve engineering specialists.
Among Chinese fabricators, XINGYUAN and Guangzhou Talents Cosmetics Packaging exemplify the integrated PET blow-molding archetype serving Korean cosmetics contract manufacturers. Alpla occupies a position within the multinational rigid packaging tier, extending European blow-molding networks into foam-specific neck finishes. These three anchors represent distinct geographic and capability positions without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| XINGYUAN |
| Guangzhou Talents Cosmetics Packaging |
| Choebe |
| Yuhuan Chumen Micro-Sprayer |
| Yuheng Plastic |
| Yuhua Packing |
| DAISHO GLASS Co.,Ltd |
| Alpla |
| Jebsen & Jessen Packaging |
| Others |
Supply & Pricing Matrix
FDA combination product validation and EU F-Gas Regulation phasedown gates both supply qualification and price differentiation simultaneously, forcing contract packagers to maintain dual quality systems while absorbing stranded equipment costs from legacy aerosol lines.
Pricing Analysis
FDA combination product rules dictate the pricing tier structure across pharmaceutical-grade and consumer-grade foam bottle systems. Three-tier pricing structure across premium, standard, and economy levels separates validated metered-dose containers with 18-36 month qualification timelines from rapid-cycle cosmetic dispensers and commodity trigger formats. Cost compression in standard-tier mechanical foaming equipment is intensifying because REACH restrictions on fluorinated propellants force simultaneous valve redesign and filling line replacement. Retail chains and mass-market personal hygiene brands exhibit the highest price sensitivity, while pharmaceutical contract manufacturers accept premium qualification fees for dual EMA-FDA compliant barrier systems.
Supply Chain Analysis
China and South Korea anchor PET blow-molding capacity and precision-molded actuator assembly for foam bottle production. Germany's Rhine-Main corridor draws from this Asian resin and component base while adding EVOH barrier layer distribution control for oxygen-sensitive pharmaceutical applications. Single-source vulnerability concentrates in cyclic olefin copolymer and high-density polyethylene resin streams from Asian petrochemical processors, exposing European converters to freight and tariff volatility. Distribution runs through integrated contract manufacturers with captive blow-molding and actuator assembly capabilities rather than fragmented wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as airless pump technology collapses the historical divide between cosmetic novelty dispensers and pharmaceutical delivery systems, creating niche entry points for specialists with dual-qualified quality systems.
For Market Incumbents: Compound barrier resin expertise and EVOH co-injection molding capabilities to defend against Asian PET-G precision molders encroaching on European pharmaceutical qualification business. Prioritize capacity addition in Germany's Rhine-Main corridor where pan-European personal care multinationals concentrate procurement. Investment in pre-validated master files for EMA-FDA regulatory convergence captures premium qualification fees before harmonized extractables protocols commoditize compliance.
For New Entrants and Emerging Players: Lead with compressed gas valve engineering and mechanical foaming system design to capture contract manufacturing slots vacated by legacy aerosol packagers facing fluorinated propellant phaseout. Target South Korean cosmetics contract manufacturers specifying airless micro-foam dispensers for preservative-free essences, where MFDS cosmetic safety reporting requirements and brand sustainability pledges converge to demand documentation-ready systems at concept stage. Go-to-market through Seoul-based packaging innovation labs rather than traditional component catalogs.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown reshapes the acquisition landscape toward compressed gas and mechanical foaming specialists with viable alternatives to stranded aerosol infrastructure. Long-term viability over the next decade hinges on positioning upstream of regulatory convergence between FDA and EMA on container closure system validation protocols. Acquisition target archetype: mid-cap European contract packagers with integrated blow-molding and dual-qualified quality systems serving both cosmetic and pharmaceutical specifications. Signal to watch: EMA adoption of FDA-equivalent extractables and leachables testing timelines as inflection indicator for multi-region approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Airless Pump Assembly Capacity Expansion | Captures margin pools from South Korean cosmetics houses reformulating around preservative-free claims. |
| EVOH Barrier Layer Co-Injection Investment | Secures pharmaceutical qualification business for oxygen-sensitive topical hormone therapies. |
| Compressed Gas Valve Engineering Partnership | Accelerates European conversion from fluorinated propellants under EU F-Gas Regulation phasedown. |
| Dual-Qualified Quality System Certification | Rewards packagers with pre-validated master files as EMA-FDA regulatory convergence advances. |
| Biopolymer Integration Pilot Programs | Aligns with EU Packaging and Packaging Waste Regulation material recovery thresholds for brand sustainability commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging innovation directors at Seoul-based beauty conglomerates, technical procurement leads at German contract manufacturers, regulatory affairs specialists navigating FDA combination product rules, and valve engineering specialists redesigning for EU F-Gas Regulation compliance. Secondary validation drew from EMA guidance documents on extractables and leachables, FDA container closure system validation protocols, MFDS cosmetic safety reporting requirements, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up triangulation across production capacity disclosures and top-down reconciliation against end-use demand patterns anchored segmentation-specific estimates.
Across the analysis window, value and volume outputs reflect disaggregated modeling by pressure mechanics, generation technology, application segment, and procurement channel. Segmentation dimensions included pressurized versus non-pressurized architectures, micro-foam generation versus metered-dose precision tiers, pharmaceutical dispensing versus cosmetics versus personal hygiene end-uses, and contract manufacturer versus retail chain versus online vendor procurement patterns. CAGRs were derived from slope-intercept calibration against historical adoption curves for analogous packaging technology transitions, with specific inputs from propellant phaseout schedules and dual-regulatory qualification timeline compression.
Forecasts assume regulatory continuity in FDA combination product validation and EU F-Gas Regulation phasedown; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated REACH restrictions on per- and polyfluoroalkyl substances, unilateral EMA departure from FDA-aligned extractables protocols, or breakthrough biopolymer scale-up disrupting barrier resin economics. Recalibration cycles align with material shifts in named regulatory and technological drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Bulb Packaging Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Strip Pack Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
PCR Packaging Market