
 Glass Decanters Market | 2026-2036
Glass Decanters Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Decanters Market Foresight
Aftermarket service revenue is fragmenting across repair, recutting, and recertification channels as collectors seek to extend heirloom piece longevity. Riedel leverages its Austrian manufacturing heritage to sustain premium positioning in sommelier-directed channels. Bormioli Luigi anchors European hospitality supply through scale production of lead-free crystal lines. Waterford Crystal competes in the heritage segment with hand-cutting specialization that commands artisan pricing tiers.
Glass decanters are vessels engineered from silica-based formulations, typically with wall thicknesses of 2–4 millimeters and stopper tolerances within 0.5 millimeters, designed to accelerate wine aeration through controlled oxygen exposure while preventing sediment disturbance. The hospitality sector dominates volume procurement, with crystal decanters capturing the highest margin pool due to perceived prestige and durability requirements. Hand-blown variants represent the fastest-growing product type as consumers prioritize provenance narratives and small-batch craftsmanship over mass-produced alternatives.
REACH restrictions on lead crystal migration limits and FDA food-contact surface standards shape material selection across export-oriented manufacturers, with compliance costs favoring larger producers capable of batch certification. California Proposition 65 labeling requirements add a secondary compliance layer for brands distributing through US retail channels. Stakeholders must monitor evolving state-level chemical disclosure rules and hospitality sector sustainability procurement criteria to anticipate which material formulations will retain market access.
Market Dynamics
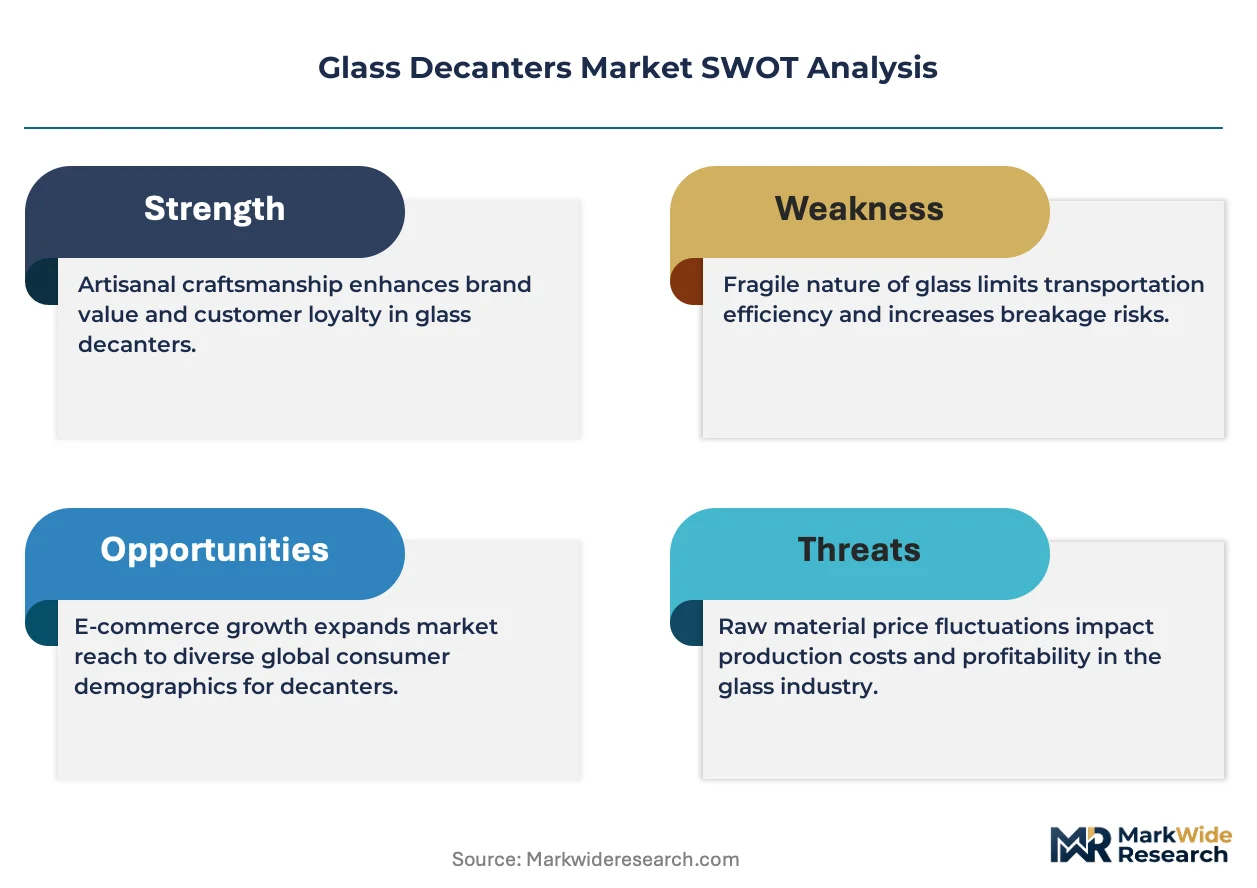
REACH migration limits on lead crystal and California Proposition 65 disclosure mandates are forcing manufacturers to abandon traditional formulations, redirecting investment toward borosilicate and soda-lime alternatives while artisan clusters in Italy's Veneto and Bohemia's Czech districts absorb compliance costs through premium positioning.
Growth Catalysts
- Tableside wine service expansion:Premium hospitality venues across North America and Europe are deploying crystal decanter programs as experiential dining differentiators, creating pull for hand-finished inventory with provenance documentation.
- REACH lead migration thresholds:ECHA-enforced limits on lead crystal leaching are accelerating R&D into barium-zinc and titanium oxide substitutes that replicate refractive properties without compliance liabilities.
- Artisan cluster concentration:Glassmaking districts in Murano and Nový Bor are leveraging centuries of craft heritage to command price premiums from collectors seeking small-batch authenticity over industrial output.
Market Restraints
- Silica sand supply volatility:High-purity silica extraction costs are rising as Ukrainian and Egyptian deposits face logistical constraints, compressing margins for soda-lime manufacturers without captive mining operations.
- Substitution by aeration devices:Electric wine aerators and instant decanting pumps are capturing convenience-oriented buyers in North American retail channels, displacing vessel-based solutions in sub-premium segments.
- Lead-free reformulation capex:Batch furnace retrofits required for borosilicate production demand seven-figure capital commitments that exclude smaller Czech and Portuguese producers from export certification.
Strategic Opportunities
- Direct-to-collector digital channels:Murano ateliers and Bohemian workshops are bypassing wholesale distributors through Instagram-native sales and NFT-linked provenance certificates, capturing margin previously lost to retail markups.
- Hospitality sustainability procurement:EU Green Deal-aligned tender criteria are creating preference windows for manufacturers offering carbon-footprint disclosures and closed-loop recycling programs.
- Barium-titanium crystal convergence:Hybrid formulations combining barium oxide clarity with titanium durability are opening positioning space between mass-market soda-lime and heritage lead crystal.
Industry Challenges
- Master glassblower attrition:Apprenticeship pipelines in Murano and Jablonec are failing to replace retiring artisans, constraining hand-blown output expansion despite price inelasticity at the top tier.
- Multi-jurisdiction certification lag:Simultaneous FDA food-contact approval, ECHA REACH batch testing, and California Proposition 65 labeling create 18-24 month product launch timelines that freeze formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Decanters Market |
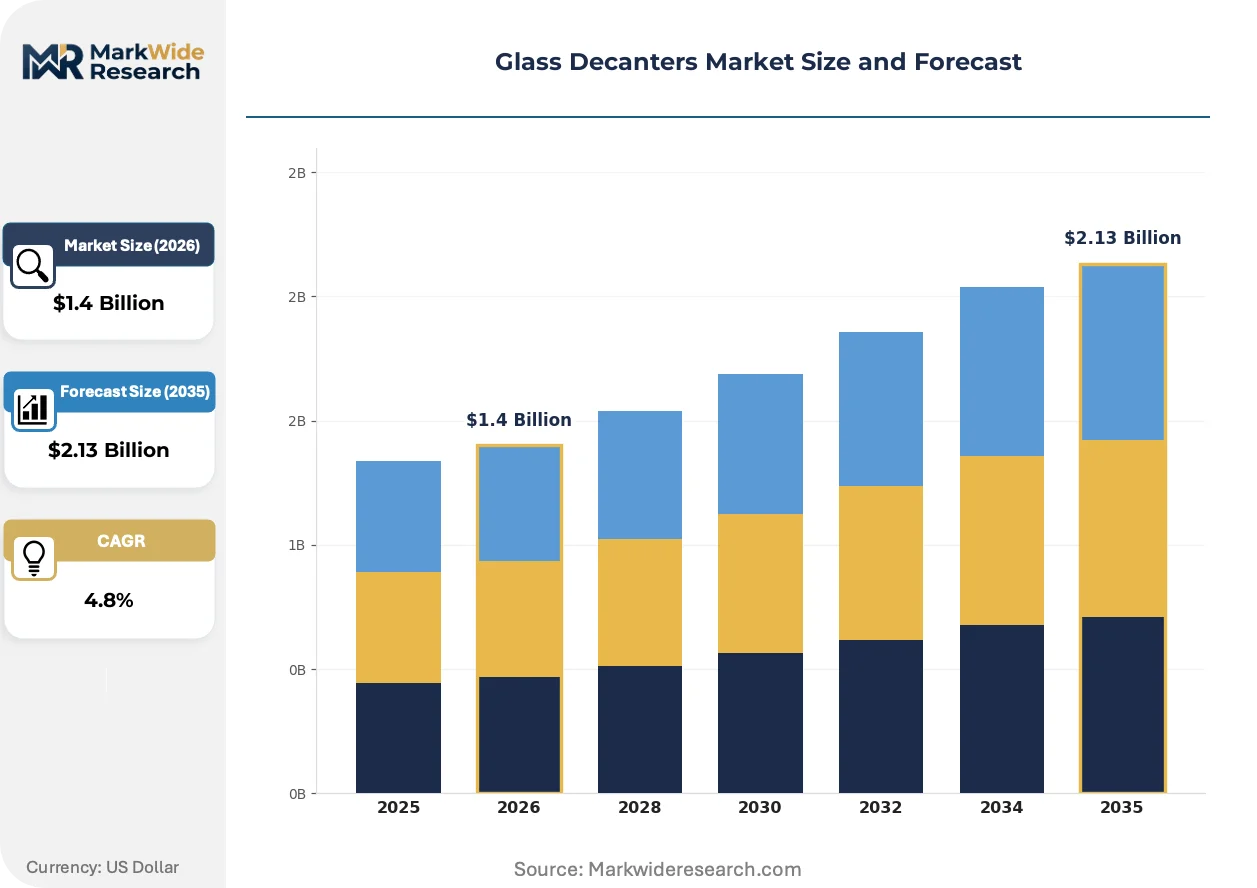
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Contemporary, Crystal, Hand-Blown, Vintage Application: Wine Service, Whiskey Aging, Olive Oil Storage, Decorative Display, Perfume Presentation Material: Lead-Free Glass, Borosilicate Glass, Soda Lime Glass, Recycled Glass, Colored Glass End User: Hospitality Sector, Retailers, Private Collectors, Event Planners, Artisans |
| Companies Covered | Ravenscroft Crystal, Bormioli Luigi, Prestige Decanters, Riedel, Schott Zwiesel, Waterford Crystal, O I Packaging, Saver Glass, Spiegelau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Decanters Market Shifts & Advancements
Formulation chemistry and digital provenance systems are converging to redefine value capture in glass decanter production, with regulatory pressure acting as the primary accelerant rather than end-user demand alone.
Laser-etched internal aeration channels are hybridizing traditional vessel geometry with engineered fluid dynamics. High-end hospitality procurement teams in Copenhagen and Singapore are specifying these designs for by-the-glass programs. The technology is compressing the functional gap between passive decanting and active aeration without electrical components.
California Proposition 65 warning label mandates are reshaping US retail packaging requirements. Brands distributing through Amazon and Williams Sonoma must now display chemical disclosure tags that erode shelf appeal for lead-containing inventory. Italian exporters are responding by accelerating barium-crystal SKU transitions ahead of formal regulatory deadlines.
Collector preference for documented provenance is fragmenting wholesale relationships. Direct studio sales through Shopify-powered storefronts are displacing traditional gallery representation in the heirloom segment. This pattern concentrates in German-speaking markets where heritage authentication commands decisive purchase influence.
Glass Decanters Market Segmentation
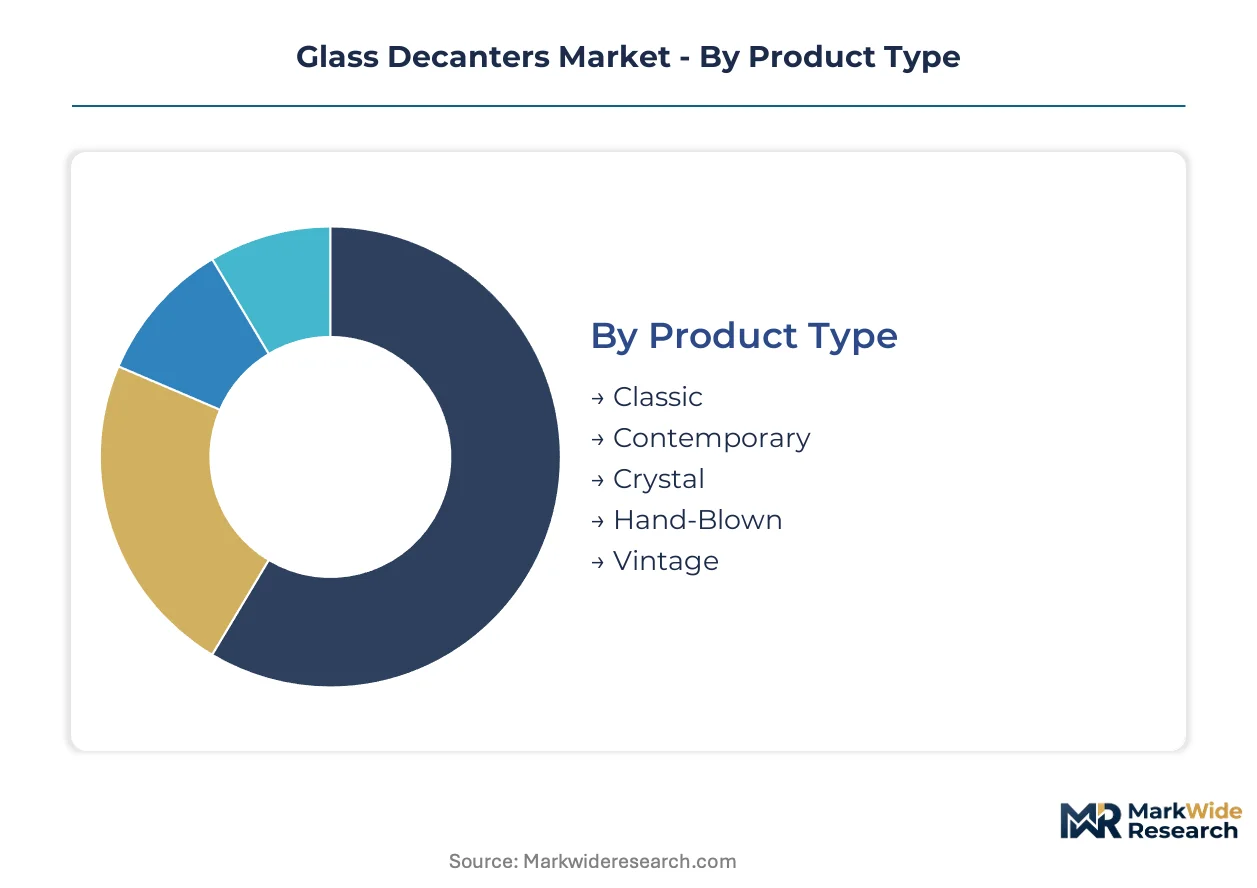
Aftermarket service intensity varies sharply across glass decanter segments, with heirloom-grade crystal commanding recutting and recertification workflows while mass-market soda-lime variants face replacement economics. Segmentation strategy must account for these divergent post-purchase revenue streams alongside initial procurement patterns.
Product Type:
After-sales-service intensity peaks with hand-finished inventory requiring specialized repair networks and provenance documentation maintenance.
- Classic:Traditional silhouettes with standardized neck diameters and ground-glass stopper interfaces dominate institutional hospitality procurement. European heritage hotels in Austria and Germany specify these for banquet service continuity.
- Contemporary:Angular geometries and asymmetric profiles target design-forward hospitality venues in Copenhagen and Singapore seeking Instagram-differentiated tableside presentation.
- Crystal:Lead-free and barium-zinc formulations deliver refractive clarity for sommelier-directed programs. REACH-compliant batches from Bohemian workshops command premium positioning in certified channels.
- Hand-Blown:Murano and Nový Bor ateliers produce small-batch inventory with documented artisan provenance. Collector demand concentrates in German-speaking markets where authentication drives purchase decisions.
- Vintage:Secondary market circulation of pre-REACH lead crystal requires recertification services. Auction houses in London and New York manage authentication and condition grading workflows.
By volume, Classic leads hospitality procurement. By growth pace, Hand-Blown is ahead.
Application:
Cost tier stratification separates vessel-grade specifications from display-oriented aesthetics across end-use contexts.
- Wine Service:Functional aeration geometry with sediment-control shoulders defines professional procurement standards. Copenhagen's Michelin-tier venues specify laser-etched internal channels for by-the-glass programs.
- Whiskey Aging:Tight stopper tolerances within 0.5 millimeters prevent oxidation loss during extended maturation. Japanese whisky bars in Tokyo and Osaka drive demand for heavy-base crystal designs.
- Olive Oil Storage:UV-blocking formulations and pour-control spouts address rancidity prevention. Italian agritourism retail channels in Tuscany and Puglia favor dark-tinted borosilicate variants.
- Decorative Display:Form prioritizes visual impact over functional precision. Hotel lobby installations in Dubai and Miami source oversized statement pieces from Murano studios.
- Perfume Presentation:Miniature scale with ground-glass stopper seals serves luxury fragrance houses. Grasse-based ateliers commission custom colored-glass runs for limited-edition releases.
By margin contribution, Wine Service dominates. By expansion trajectory, Whiskey Aging is climbing the fastest.
Material:
Supply concentration in Italian and Czech glassmaking districts shapes material availability and certification timelines.
- Lead-Free Glass:Barium oxide and titanium oxide substitutes replicate traditional crystal refractive index without REACH migration liabilities. ECHA batch testing requirements favor producers with captive laboratory capacity.
- Borosilicate Glass:Thermal shock resistance supports temperature-variable applications from whiskey service to laboratory-adjacent uses. German manufacturers in Thuringia leverage pharmaceutical-grade production infrastructure.
- Soda Lime Glass:Volume production economics serve mass-market hospitality replacement cycles. Egyptian and Ukrainian silica sand supply volatility compresses margins for non-integrated producers.
- Recycled Glass:EU Green Deal procurement criteria create preference windows for closed-loop material flows. Veneto region workshops market carbon-footprint disclosures to sustainability-tendered contracts.
- Colored Glass:Mineral oxide dosing achieves hue consistency across production batches. Perfume and decorative segments drive specialized runs from Murano color masters.
By procurement volume, Soda Lime Glass leads. By regulatory tailwind, Lead-Free Glass is gaining share fastest.
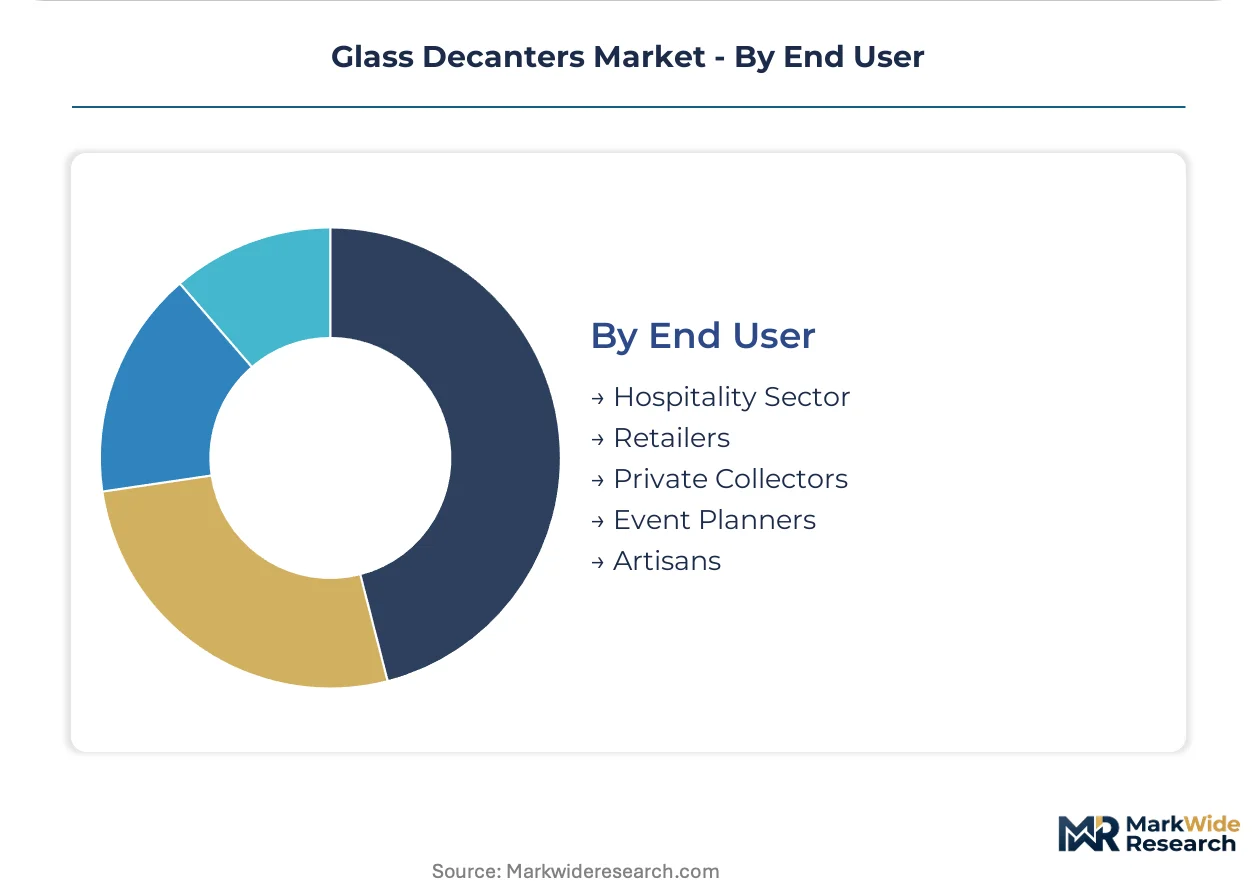
End User:
Customer type determines pricing architecture, with hospitality sector tenders favoring scale discounts and collector channels capturing full margin.
- Hospitality Sector:Premium venues across France, Italy, and Spain deploy crystal decanter programs as experiential dining differentiators. Procurement teams specify provenance documentation for inventory audit trails.
- Retailers:Multi-brand distributors manage California Proposition 65 labeling compliance for US market access. Williams Sonoma and Amazon channels require chemical disclosure tag integration.
- Private Collectors:Direct studio sales through Shopify-powered storefronts displace traditional gallery representation. NFT-linked provenance certificates emerge in German-speaking markets.
- Event Planners:Rental inventory economics favor durable soda-lime formulations with standardized replacement sourcing. Corporate hospitality programs in London and Frankfurt drive seasonal demand spikes.
- Artisans:Studio glassblowers in Jablonec and Murano sell through Instagram-native channels with master-creator attribution. Apprenticeship pipeline failures constrain output expansion despite price inelasticity.
By revenue concentration, Hospitality Sector leads. By margin capture, Private Collectors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Czech glassmaking districts anchor artisan-grade supply, while hospitality procurement concentrates in Western European and North American metropolitan markets. Regulatory divergence between ECHA REACH enforcement and FDA food-contact standards fragments certification pathways. Demand clusters in Michelin-tier dining cities and collector markets across German-speaking regions.
Italy
Veneto's Murano ateliers supply hand-blown inventory to luxury hospitality venues in Milan and Rome. ECHA REACH migration limits on lead crystal redirect formulation investments toward barium-oxide substitutes. Tuscany's agritourism retail channels favor UV-blocking borosilicate variants for olive oil storage applications.
Czech Republic
Bohemian workshops in Nový Bor and Jablonec command collector premiums through documented artisan provenance. REACH batch testing requirements favor producers with captive laboratory capacity in Prague. Apprenticeship pipeline failures constrain hand-blown output expansion despite price inelasticity at the heritage tier.
Germany
Thuringia's pharmaceutical-grade borosilicate infrastructure serves temperature-variable whiskey aging applications. EU Green Deal procurement criteria create preference windows for closed-loop recycling programs from Veneto suppliers. Berlin and Frankfurt hospitality procurement teams specify carbon-footprint disclosures for tender compliance.
United States
California Proposition 65 labeling mandates reshape Amazon and Williams Sonoma channel requirements for chemical disclosure tags. FDA food-contact surface standards add secondary compliance layers for Italian and Czech exporters. New York and San Francisco premium venues deploy crystal decanter programs as experiential dining differentiators.
Japan
Tokyo and Osaka whisky bars drive demand for heavy-base crystal designs with tight stopper tolerances. METI standards on food-contact materials align with FDA benchmarks, simplifying import pathways for European manufacturers. Osaka's design-forward hospitality sector specifies angular contemporary geometries for Instagram-differentiated presentation.
Glass Decanters Market Competitive Landscape
Heritage crystal houses and scale-oriented hospitality suppliers split the market into divergent margin architectures. Italian and Austrian ateliers capture collector premiums through provenance documentation, while German and French fabricators dominate institutional procurement through batch certification efficiency. Two strategic archetypes predominate: artisan studios leveraging centuries of craft heritage, and integrated manufacturers with captive laboratory capacity for multi-jurisdiction compliance. Competitive moves center on direct-to-collector digital channel expansion and sustainability certification alignment with EU Green Deal tender criteria.
Within the heritage artisan tier, Waterford Crystal and Riedel exemplify positioning strategies built on geographic manufacturing legacy and sommelier-directed channel relationships. Bormioli Luigi occupies a position bridging scale production and lead-free crystal innovation for European hospitality supply. These three entities represent the spectrum from hand-cutting specialization to batch furnace efficiency, each anchoring distinct price-performance coordinates without overlapping core customer segments.
| Leading Market Players |
|---|
| Ravenscroft Crystal |
| Bormioli Luigi |
| Prestige Decanters |
| Riedel |
| Schott Zwiesel |
| Waterford Crystal |
| O I Packaging |
| Saver Glass |
| Spiegelau |
| Others |
Supply & Pricing Matrix
Murano and Nový Bor glassmaking clusters anchor artisan-grade capacity, translating centuries of craft heritage into pricing power that mass-market soda-lime producers cannot replicate. Their small-batch output commands collector premiums while integrated hospitality suppliers capture scale efficiencies through batch certification.
Pricing Analysis
Aftermarket service revenue from recutting, repair, and recertification drives lifetime value in heirloom-grade segments. Three-tier pricing structure across hand-blown artisan, lead-free crystal, and mass-market soda-lime levels separates provenance-documented inventory from commodity replacements. Cost compression in soda-lime tiers is intensifying because Egyptian and Ukrainian silica sand supply volatility squeezes non-integrated manufacturers. Hospitality procurement teams exhibit lowest price sensitivity for REACH-compliant crystal with carbon-footprint disclosures, while event rental operators face replacement economics that prioritize unit cost over durability.
Supply Chain Analysis
High-purity silica sand deposits in Egypt and Ukraine feed furnace operations across Italian and Czech glassmaking districts. Borosilicate production draws from Thuringia's pharmaceutical-grade infrastructure, while barium oxide and titanium oxide substitutes for lead crystal rest on specialized chemical supply chains. Single-source vulnerability concentrates in master glassblower talent pools where apprenticeship pipeline failures constrain Murano and Jablonec output expansion. Distribution runs through hospitality sector tenders, direct-to-collector digital storefronts, and multi-brand retail channels requiring California Proposition 65 compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects compliant incumbents from smaller competitors unable to absorb multi-jurisdiction certification costs.
For Market Incumbents: Entrench positioning by deepening backward integration into captive silica sand sourcing to buffer Egyptian and Ukrainian supply volatility. Accelerate barium-titanium crystal R&D to capture positioning space between heritage lead crystal and mass-market soda-lime. Vertical integration into Prague-based laboratory capacity secures REACH batch testing efficiency that excludes smaller Bohemian competitors.
For New Entrants and Emerging Players: German-speaking collector markets in Austria and Switzerland show underpenetration for NFT-linked provenance certificates that Murano atelies are only beginning to deploy. Direct studio sales through Instagram-native channels bypass wholesale markups and capture margin previously lost to gallery representation. Sustainability-tendered EU Green Deal contracts create entry windows for closed-loop recycling programs from Veneto region workshops.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because master glassblower attrition and seven-figure furnace retrofit costs will force smaller Czech and Portuguese producers toward distressed exit. Target integrated manufacturers with captive laboratory capacity for multi-jurisdiction compliance. Watch apprenticeship pipeline enrollment rates in Murano and Jablonec as inflection indicator for hand-blown output constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Crystal Formulation Transition | REACH migration limits and California Proposition 65 mandates redirect R&D toward barium-zinc substitutes. |
| Direct-to-Collector Digital Channel Expansion | Murano and Bohemian workshops bypass wholesale distributors through Shopify-powered storefronts and NFT provenance. |
| Sustainability Certification Alignment | EU Green Deal tender criteria create preference windows for carbon-footprint disclosures and closed-loop recycling. |
| Master Glassblower Apprenticeship Investment | Jablonec and Murano pipeline failures constrain hand-blown output despite price inelasticity at heritage tier. |
| Multi-Jurisdiction Laboratory Capacity Buildout | Prague-based captive testing facilities compress 18-24 month FDA-ECHA-Proposition 65 launch timelines. |
Research Methodology
The analysis maps hand-blown artisan, lead-free crystal, and mass-market soda-lime segments, each validated through primary interviews with master glassblowers, hospitality procurement directors, and regulatory compliance officers. Secondary sources include ECHA REACH batch testing records, FDA food-contact surface filings, and EU Green Deal tender documentation. Bottom-up volume estimates from Italian and Czech production clusters triangulate against top-down hospitality sector spend analysis.
Assumptions held fixed include ECHA enforcement intensity on lead crystal migration limits and California Proposition 65 labeling requirements throughout the projection horizon. The modeling framework varies material formulation adoption curves, artisan output expansion rates, and sustainability procurement weighting across hospitality tenders. CAGRs derive from segment-level volume trajectories weighted by price-per-unit differentials between crystal grades.
Practitioners should monitor silica sand supply disruptions, apprenticeship enrollment trends, and state-level chemical disclosure rule expansions for early signals requiring forecast revision. Cross-checking against hospitality sector capital expenditure disclosures and collector auction volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Angola Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
United Arab Emirates Glass Packaging Market