
 Egypt Glass Packaging Market | 2026-2036
Egypt Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Glass Packaging Market Foresight
Modular bottle-and-closure configurations is repositioning buyer choice across Egypt's beverage and pharmaceutical sectors. Kandil Glass leverages backward integration into raw material sourcing to control cost volatility. SGD Pharma Egypt specializes in Type I borosilicate vial production for injectable drug clients. Misr Glass Manufacturing Company SAE anchors its position through furnace-scale operations serving multinational FMCG brands.
Egypt glass packaging comprises silica-soda-lime formulations molded into rigid, chemically inert containers with thermal shock resistance spanning 40–200 degrees Celsius, primarily preserving product integrity across food, pharmaceutical, and cosmetic supply chains. Bottles dominate volume throughput due to carbonated soft drink and bottled water demand, while vials command premium positioning through pharmaceutical serialization requirements and compliance with injectable drug standards. Cosmetic jars represent a concentrated margin pool where specialty decoration and small-batch finishing differentiate regional suppliers.
Egypt's Ministry of Environment enforces packaging waste regulations requiring recycled glass content benchmarks, while the Egyptian Organization for Standardization and Quality (EOS) mandates dimensional and chemical stability standards for pharmaceutical contact materials. The Central Administration of Pharmaceutical Affairs (CAPA) under the Ministry of Health governs drug container qualification, directly shaping vial demand specifications and supplier certification requirements. Stakeholders must monitor enforcement timelines for extended producer responsibility rules and align furnace investments with anticipated recycled cullet supply chain maturation.
Market Dynamics
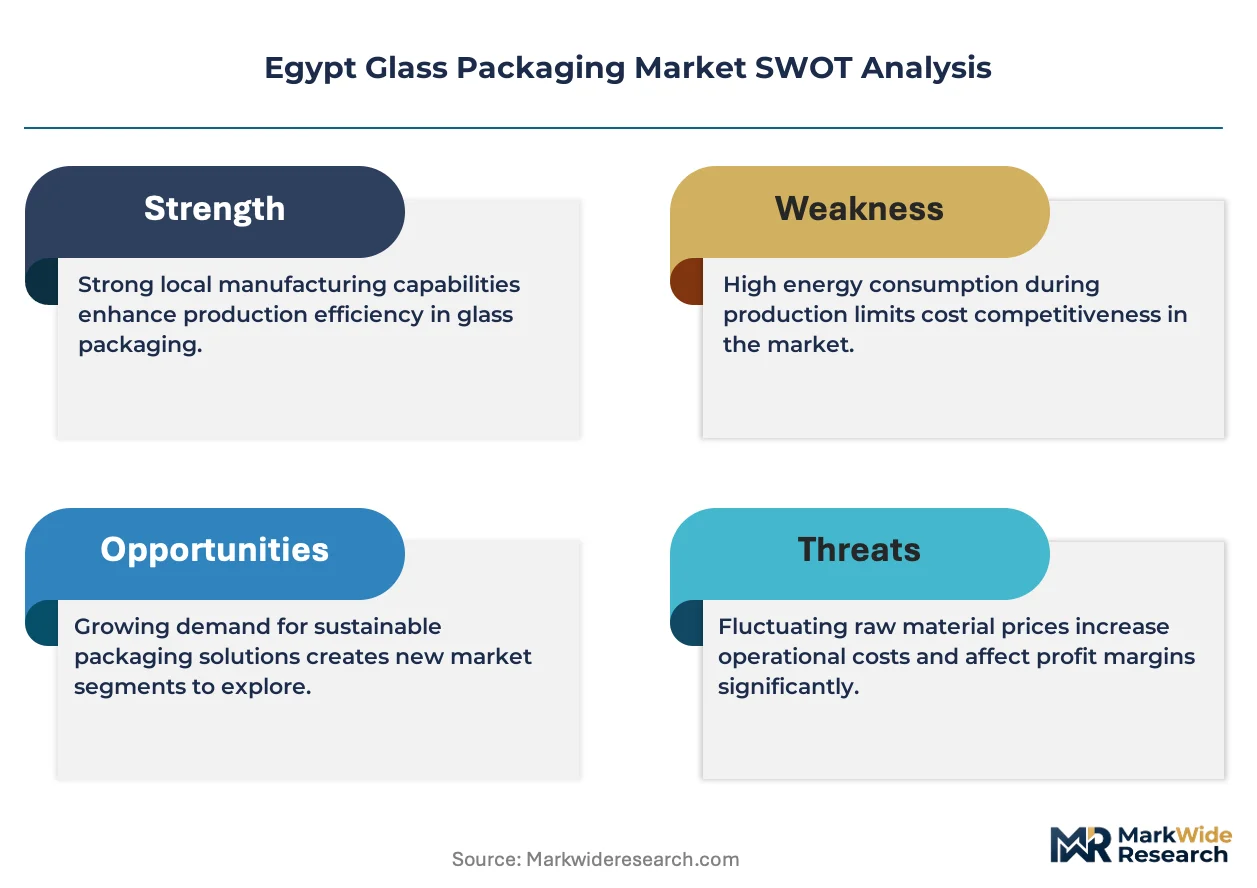
Egypt's glass packaging sector faces a structural squeeze between the Ministry of Environment's escalating recycled content mandates and the domestic cullet supply chain's immaturity. Furnace operators must simultaneously decarbonize energy inputs while scaling Type I borosilicate capacity for pharmaceutical serialization requirements.
Growth Catalysts
- CAPA pharmaceutical serialization rules:Injectable drug manufacturers in Greater Cairo are expanding glass vial procurement to meet track-and-trace mandates, directly lifting demand for chemically stable container formats.
- Beverage bottler concentration in 6th of October City:Carbonated soft drink and bottled water producers cluster along the industrial corridor, creating localized demand density that justifies furnace capacity expansion.
- Silica-soda-lime thermal shock resistance:Formulation improvements spanning 40–200 degrees Celsius enable single-container platforms across hot-fill and cold-chain applications, reducing SKU proliferation costs.
Market Restraints
- Natural gas price volatility:Furnace operations depend on Egyptian Natural Gas Holding Company (EGAS) supply contracts, with energy representing the dominant opex component subject to subsidy reform pressures.
- Recycled cullet quality inconsistency:Post-consumer glass collection networks remain fragmented, forcing manufacturers to import higher-grade recycled feedstock at premium landed costs.
- Aluminum can substitution in CSD segments:Beverage multinationals are piloting metal alternatives for single-serve formats, threatening volume share in Egypt's highest-throughput packaging category.
Strategic Opportunities
- Extended producer responsibility maturation:The Ministry of Environment's waste regulations will formalize reverse logistics infrastructure, enabling integrated producers to capture closed-loop material cost advantages.
- Cosmetic jar decoration specialization:Small-batch finishing capabilities for premium skincare brands in New Cairo represent underdeveloped margin pools distinct from commodity beverage volumes.
- Pharmaceutical export corridor expansion:North African and Levantine drug manufacturers are qualifying Egyptian Type I vial suppliers as secondary sourcing alternatives to European glasshouses.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical contact material qualification requires 18–24 month validation cycles, compressing supplier switching flexibility for drug manufacturers.
- Furnace rebuild capex intensity:Glass melting asset replacement demands $50–80 million per installation, constraining mid-scale producers from capacity modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Glass Packaging Market |
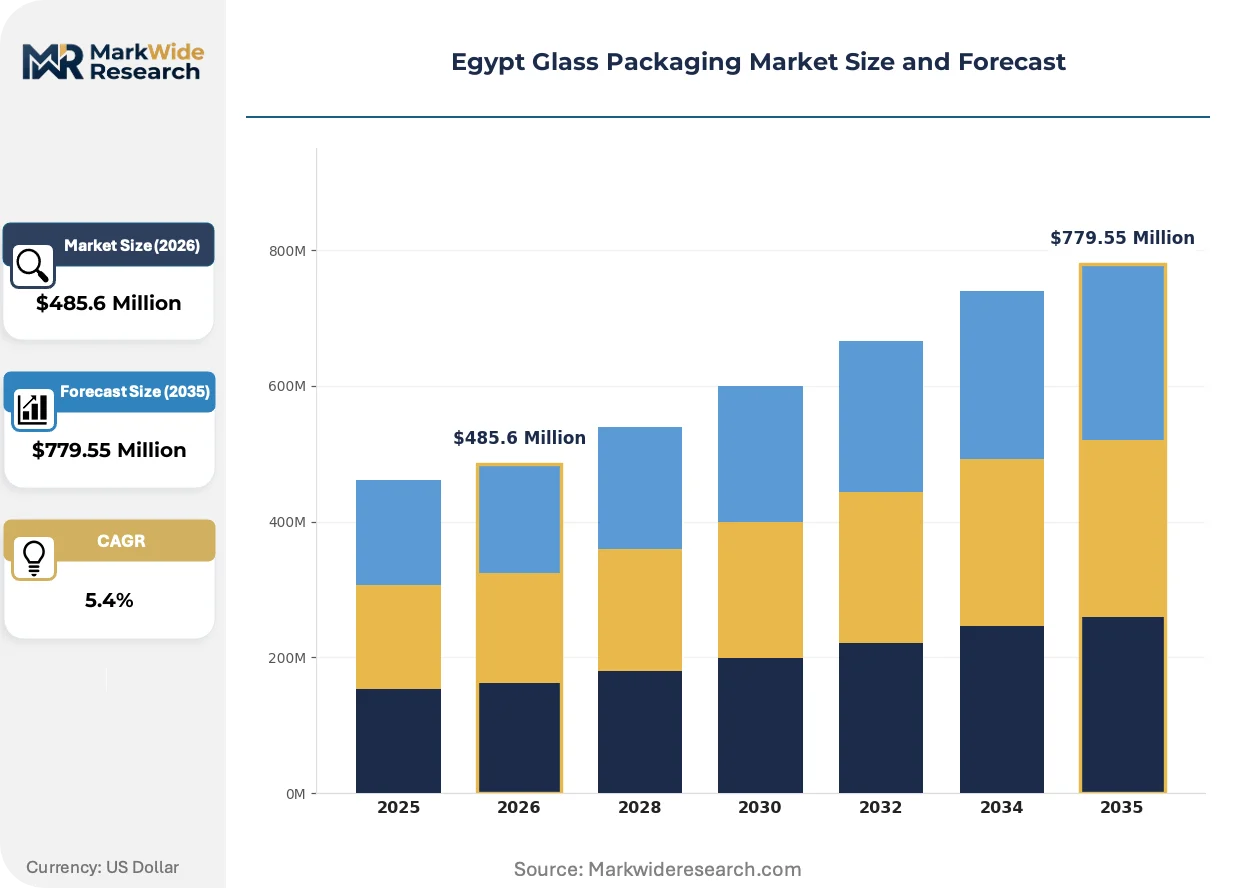
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $779.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Vials End Use Industry: Food, Beverage, Pharmaceuticals, Cosmetics Packaging Type: Rigid, Flexible, Sustainable, Specialty Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Kandil Glass, Schott AG, Middle East Glass Manufacturing Company SAE (MEG), Sphinx Glass, Misr Glass Manufacturing Company SAE (MGM), National Company for Glass and Crystal (SAE), United Glass Company, SGD Pharma Egypt, Arab Pharmaceutical Glass Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Glass Packaging Market Shifts & Advancements
Digital printing and modular mold technologies are fragmenting production economics across Egypt's glass packaging value chain. These shifts enable shorter runs and faster changeovers, reshaping how suppliers compete for brand owner contracts.
Electrostatic powder coating for direct-to-glass decoration is decentralizing label application from centralized converting plants to bottling line integration. Beverage brand owners in 10th of Ramadan City are adopting in-line systems that eliminate wet-glue label inventory. This technology is compressing decoration lead times from weeks to hours while reducing substrate waste.
EOS pharmaceutical container standards are tightening dimensional tolerance requirements for automated filling lines. The Egyptian Organization for Standardization and Quality is aligning with EU MDR traceability provisions, forcing vial manufacturers to invest in laser-etched serialization. Injectable drug finishers in Obour City are consolidating supplier bases to reduce qualification burden.
Modular bottle-and-closure configurations are enabling rapid SKU proliferation without furnace reconfiguration. Brand owners now specify thread standardization across multiple neck finishes, allowing single capping equipment platforms to serve diverse product lines. This flexibility is most visible in New Cairo's contract packaging sector, where co-manufacturers service multiple FMCG clients from shared filling assets.
Egypt Glass Packaging Market Segmentation
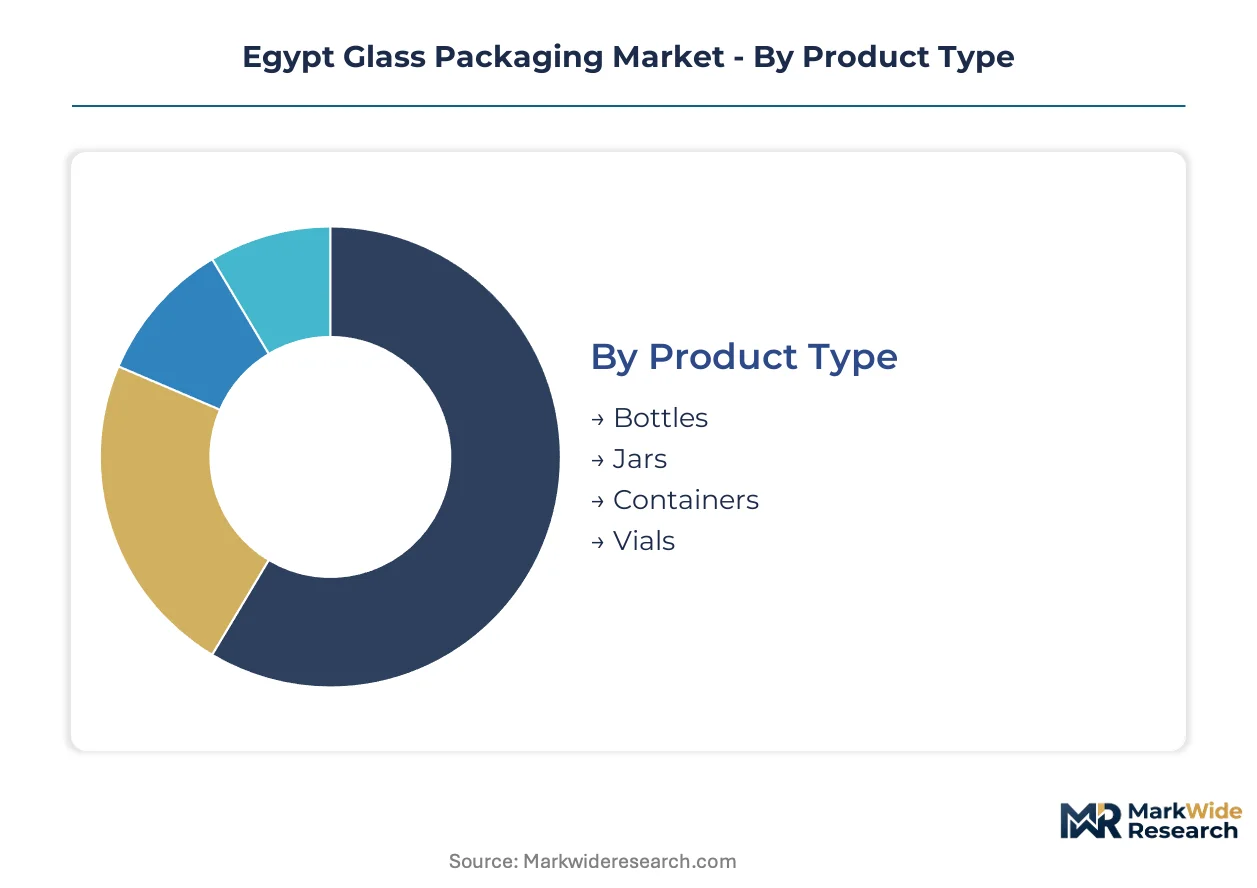
Egypt's glass packaging segmentation reflects furnace-scale economics and regulatory compliance tiers. Product formats, end-use specifications, and distribution channels each carry distinct margin profiles and capital requirements that shape supplier positioning across Greater Cairo's industrial corridor.
Product Type:
Standardization dominates commodity formats while specialty containers command customization premiums tied to thermal performance and chemical stability requirements.
- Bottles:Silica-soda-lime formulations with 40–200 degrees Celsius thermal shock resistance serve carbonated soft drink and bottled water producers clustered in 6th of October City. Furnace operators prioritize neck finish standardization to enable rapid SKU changeovers without mold reconfiguration.
- Vials:Type I borosilicate glass withstands autoclave sterilization and meets CAPA pharmaceutical serialization mandates for injectable drug manufacturers. Egyptian suppliers are qualifying for North African and Levantine export corridors as secondary sourcing alternatives.
- Jars:Wide-mouth configurations preserve viscosity-sensitive food products; cosmetic applications in New Cairo drive small-batch decoration demand.
- Containers:Multi-use formats with enhanced wall thickness serve industrial chemical and bulk food applications requiring repeated thermal cycling.
Leading the category by volume: Bottles. Expanding most quickly: Vials.
End Use Industry:
Regulatory intensity varies sharply across sectors, with pharmaceutical contact materials demanding 18–24 month qualification cycles versus beverage commodity procurement.
- Beverage:Carbonated soft drink and bottled water producers generate highest throughput volumes; aluminum can substitution threats concentrate in single-serve formats.
- Pharmaceuticals:Injectable drug finishers in Obour City consolidate supplier bases to reduce ISO 15378 certification burden; laser-etched serialization compliance drives vial specification tightening.
- Food:Hot-fill and cold-chain applications leverage thermal shock-resistant formulations; pasteurized product lines dominate procurement.
- Cosmetics:Premium skincare brands in New Cairo contract small-batch finishing with specialty decoration; margin pools exceed commodity beverage segments.
Pharmaceuticals leads margin capture. Cosmetics climbs fastest on premium positioning.
Packaging Type:
Material performance tiers separate commodity rigid formats from value-added sustainable and specialty categories with distinct furnace feedstock and decoration requirements.
- Rigid:Standard glass containers dominate Egyptian production; Ministry of Environment recycled content mandates are forcing cullet quality upgrades.
- Sustainable:Higher recycled glass thresholds under extended producer responsibility rules will formalize reverse logistics infrastructure.
- Flexible:Hybrid glass-polymer laminates serve niche pharmaceutical blister applications requiring moisture barrier properties.
- Specialty:Amber and cobalt-tinted formulations protect light-sensitive pharmaceuticals and premium cosmetics; smaller batch sizes require modular furnace operations.
Rigid commands volume dominance. Sustainable faces steepest regulatory-driven trajectory.
Distribution Channel:
Channel economics reflect order consolidation patterns and inventory velocity requirements across Egypt's fragmented retail and industrial procurement landscape.
- Wholesale:Beverage bottlers and pharmaceutical finishers in Greater Cairo procure direct from furnace operators to minimize handling costs.
- Direct Sales:Multinational FMCG brands negotiate long-term furnace capacity allocations; Misr Glass Manufacturing anchors this channel.
- Retail:Smaller food processors and cosmetic brands source through distributor networks with higher per-unit logistics premiums.
- Online:Emerging procurement channel for specialty cosmetic jars and small-batch pharmaceutical containers; limited current penetration.
Wholesale leads by tonnage. Online gains share fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Triangle Economic Zone drives industrial concentration across Egypt's glass packaging sector, with tax incentives attracting furnace operators to the Suez Canal corridor. Greater Cairo anchors domestic demand through beverage bottler and pharmaceutical finisher clusters.
Greater Cairo
Carbonated soft drink producers and injectable drug manufacturers cluster along the industrial corridor between 6th of October City and Obour City. The Central Administration of Pharmaceutical Affairs enforces serialization mandates that shape vial procurement specifications. Furnace operators in 10th of Ramadan City are expanding borosilicate capacity to serve pharmaceutical export qualification requirements.
Alexandria and the Northern Coast
Port access enables imported cullet supply chains for manufacturers facing domestic recycled glass quality shortfalls. The Ministry of Environment's extended producer responsibility rules are pressuring collection network formalization in Alexandria Governorate. Glass container plants near Dekheila Port are positioning for Mediterranean export routes to North African drug manufacturers.
Suez Canal Economic Zone
Natural gas supply contracts through EGAS attract energy-intensive furnace investments to the Ismailia corridor. Special economic zone status offers customs exemptions for silica sand and soda ash raw material imports. New glass melting installations near Ain Sokhna are targeting Red Sea logistics access for Levantine and Gulf pharmaceutical markets.
Upper Egypt
Silica sand deposits in Minya and Assiut Governorates support backward integration strategies for raw material security. The Egyptian Organization for Standardization and Quality is harmonizing regional quality benchmarks with EU pharmaceutical container standards. Small-scale container plants in Beni Suef serve local food processors with limited furnace modernization capital.
Egypt Glass Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Egypt's glass packaging sector. The market structure shows moderate concentration, with furnace-scale operations commanding volume share while mid-tier decorators serve niche cosmetic and specialty pharmaceutical segments. Three archetypes dominate: integrated raw material-to-container producers, pharmaceutical-grade specialists with certification depth, and regional distributors with decoration finishing capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, as producers seek to secure cullet supply chains and qualify for export corridor access.
Within the integrated producer tier, Misr Glass Manufacturing Company SAE and Kandil Glass exemplify furnace-scale operations with captive raw material sourcing. SGD Pharma Egypt occupies a position among pharmaceutical-grade specialists, representing the certification-intensive segment serving CAPA-regulated drug manufacturers. Middle East Glass Manufacturing Company SAE anchors the mid-cap regional fabricator category, sitting between commodity beverage volumes and premium cosmetic jar finishing.
| Leading Market Players |
|---|
| Kandil Glass |
| Schott AG |
| Middle East Glass Manufacturing Company SAE (MEG) |
| Sphinx Glass |
| Misr Glass Manufacturing Company SAE (MGM) |
| National Company for Glass and Crystal (SAE) |
| United Glass Company |
| SGD Pharma Egypt |
| Arab Pharmaceutical Glass Co. |
| Others |
Supply & Pricing Matrix
Electrostatic powder coating adoption across Greater Cairo bottling lines is compressing decoration economics while concentrating procurement leverage among furnace-scale operators. This technology shift simultaneously reduces per-unit finishing costs and reinforces volume-tier pricing power for integrated producers serving multinational beverage contracts.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with pharmaceutical finishers paying 15-25% above spot rates for ISO 15378-certified vial deliveries under 8-week windows. Three-tier pricing structure across premium, standard, and economy levels separates CAPA-validated Type I borosilicate from commodity soda-lime beverage formats. Price differentiation hinges on certification grade and furnace scale, with natural gas subsidy volatility compressing margins across energy-intensive melting operations. Beverage bottlers in 6th of October City exhibit highest price sensitivity due to aluminum can substitution threats, while injectable drug manufacturers absorb premium pricing to maintain qualification continuity.
Supply Chain Analysis
Egypt's Ministry of Environment recycled content mandates are reshaping sourcing patterns, forcing furnace operators to formalize domestic cullet collection networks despite quality inconsistency. Raw material dependencies rest on Egyptian Natural Gas Holding Company supply contracts, silica sand deposits in Minya Governorate, and imported soda ash through Alexandria Port. Single-source vulnerability concentrates in EGAS pipeline infrastructure, where tariff exposure and subsidy reform pressures threaten input cost stability. Distribution runs through direct sales channels for multinational FMCG accounts and wholesale procurement for mid-tier pharmaceutical finishers clustered in Obour City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace rebuild capex intensity creates structural supply constraints, with $50-80 million per installation propping pricing power for existing capacity holders across the projection horizon.
For Market Incumbents: Lock in captive cullet supply through formalized collection partnerships ahead of extended producer responsibility enforcement. Secure long-term EGAS contracts indexed to subsidy reform timelines. Aluminum can substitution in carbonated soft drink segments demands rapid neck-finish standardization investments to preserve volume share against metal alternatives. For New Entrants and Emerging Players: Digital printing capabilities for cosmetic jar decoration offer the most penetrable white-space target, with New Cairo skincare brands seeking small-batch flexibility absent from furnace-scale operators. Modular mold technologies enable rapid SKU proliferation without melting asset ownership. A technology-first go-to-market angle targets contract packaging co-manufacturers servicing multiple FMCG clients from shared filling assets. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade specialists with CAPA certification depth and North African export corridor access. Long-term viability favors integrated producers with backward control over silica sand deposits and soda ash import logistics. The signal to watch is Ministry of Environment enforcement timelines for recycled content thresholds, which will determine cullet supply chain economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand | Captive Minya Governorate deposits reduce raw material cost volatility for furnace operators. |
| Type I Borosilicate Capacity Expansion | CAPA serialization mandates lift demand for autoclave-stable vial formats in Obour City. |
| Extended Producer Responsibility Compliance | Ministry of Environment rules formalize reverse logistics infrastructure for cullet cost advantages. |
| Digital Printing Line Integration | In-line electrostatic coating compresses decoration lead times from weeks to hours for beverage clients. |
| North African Export Qualification | Levantine and Maghreb pharmaceutical manufacturers seek secondary sourcing alternatives to European glasshouses. |
Research Methodology
Multi-period observation of furnace capacity utilization, natural gas contract pricing, and CAPA certification timelines anchored the trend analysis, supplemented by interviews with plant managers at Greater Cairo melting facilities, procurement leads at pharmaceutical finishers, distribution channel partners in Alexandria, and technical R&D directors at decoration specialists. Secondary validation drew from Egyptian Organization for Standardization and Quality publications, Ministry of Environment regulatory filings, EGAS supply disclosures, and customs records for soda ash and cullet imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, end-use industry, and distribution channel dimensions shaped volume and value outputs throughout the forecast period. CAGRs were derived from trend extrapolation of furnace investment cycles, pharmaceutical serialization adoption curves, and beverage bottler concentration patterns. Industry-specific forecast inputs included natural gas subsidy reform scenarios and recycled cullet supply chain maturation trajectories.
Several conditions sit outside the modeled scope, including abrupt subsidy elimination, geopolitical disruption to Red Sea logistics, and technological breakthroughs in aluminum can barrier coatings. Forecasts reflect documented assumptions about regulatory enforcement pacing and raw material import continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Glass Veil Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Oman Container Glass Market