
 Egypt Container Glass Market | 2026-2036
Egypt Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Container Glass Market Insights
Egypt's updated environmental compliance standards for industrial emissions is decoupling small-scale furnace operators from viable participation. Misr Glass Manufacturing Company leverages captive raw-material sourcing near Suez to sustain cost leadership across pharmaceutical vial production. Middle East Glass Manufacturing Company S.A.E. anchors its position through dedicated borosilicate capacity for laboratory and cosmetic applications. United Glass Company competes on beverage bottle scale, operating multiple large-capacity furnaces serving Coca-Cola and local spirits distributors.
Container glass denotes soda-lime-silica formed products manufactured through blow molding or pressing, typically containing 70-74% silica, 12-16% soda ash, and 10-15% lime, engineered for chemical inertness and thermal stability in liquid and solid storage. The material serves as the primary barrier packaging for oxygen-sensitive consumables where plastic permeation risks product degradation. Bottles command the dominant revenue share within product type segmentation, reflecting entrenched beverage industry procurement patterns and returnable deposit systems. Pharmaceutical end-use represents the fastest-expanding demand pool, driven by ampoule and syrup bottle requirements from Egypt's generics manufacturing base. Blow molding dominates manufacturing process selection for hollow ware above 50ml capacity, while pressing retains cost advantage on wide-mouth jar geometries.
Egypt's Environmental Affairs Agency enforces air quality thresholds on furnace emissions, compelling operators to install regenerative thermal oxidizers or face production curtailment. The Egyptian General Authority for Standards and Quality mandates BIS-equivalent glass migration limits for food contact, directly conditioning export eligibility to Gulf Cooperation Council markets. SGD Pharma Egypt and National Company for Glass Industries navigate these dual compliance layers through dedicated quality laboratories and third-party certification maintenance. Stakeholders must weigh furnace rebuild cycles against pending carbon-border adjustments affecting European-bound pharmaceutical exports.
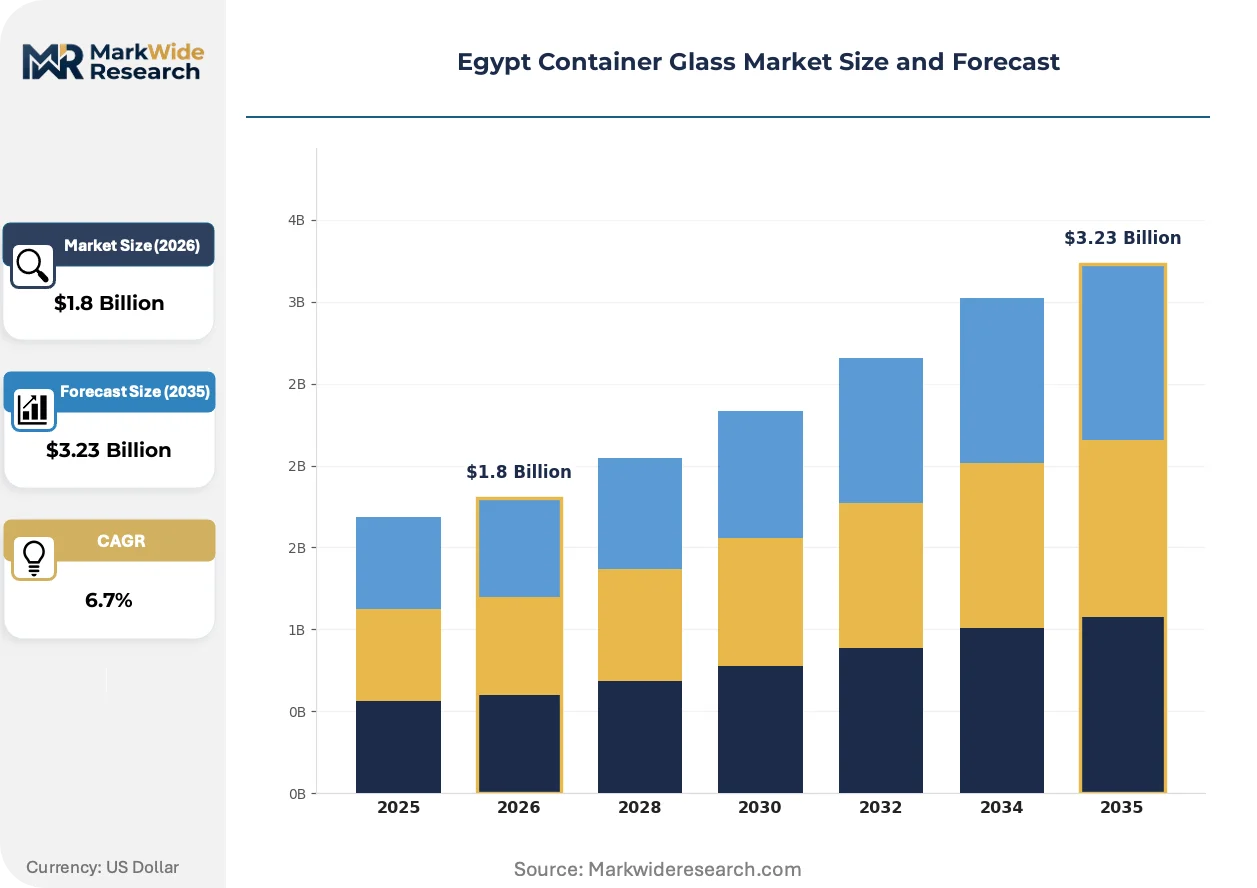
Market Dynamics
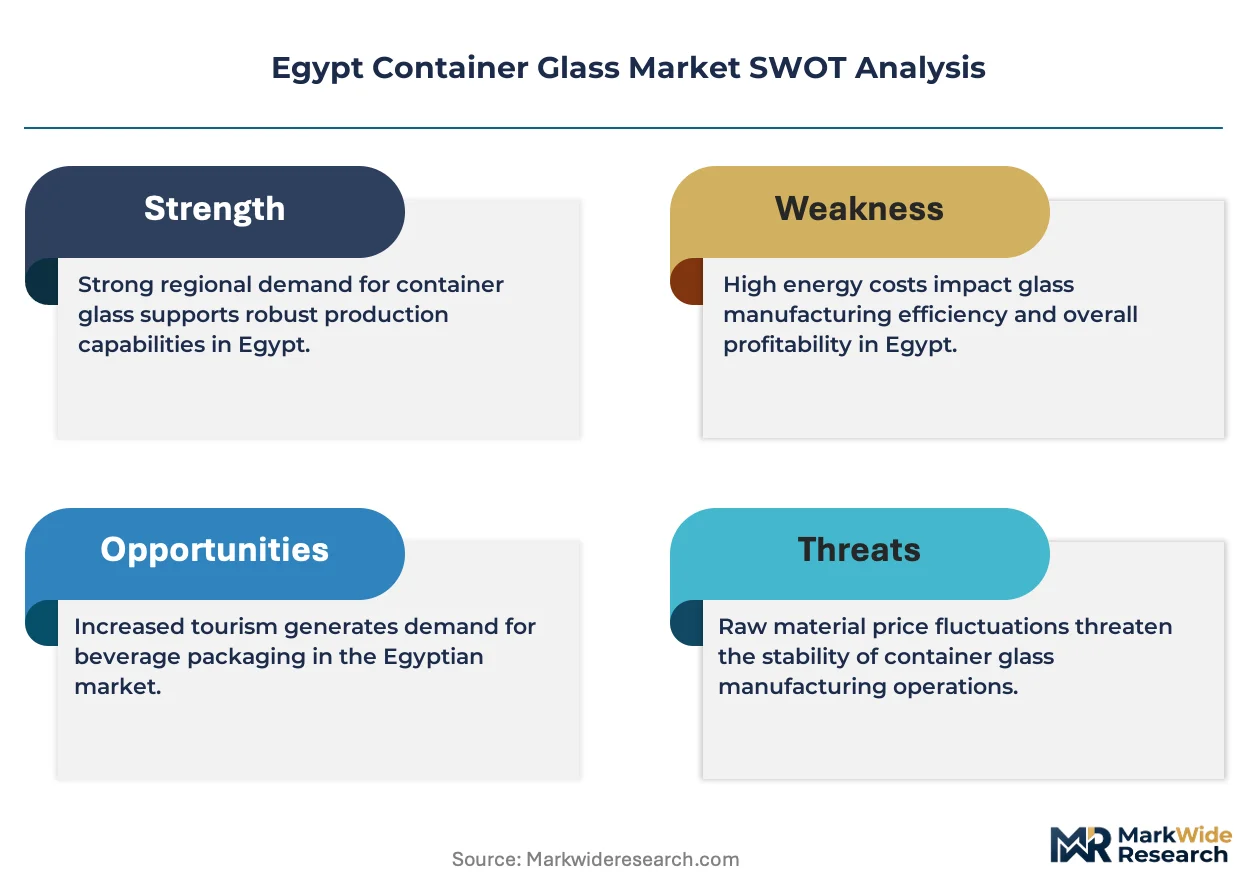
Egypt's Environmental Affairs Agency emission mandates are forcing furnace operators into costly regenerative thermal oxidizer installations, decoupling small-scale producers from viable participation while consolidating output among capital-rich incumbents with captive raw-material positions.
Growth Catalysts
- PLI Manufacturing Incentives:Egypt's production-linked incentive scheme for local manufacturing is redirecting foreign direct investment toward domestic furnace capacity, with automotive and pharmaceutical packaging lines qualifying for tiered subsidy structures.
- Pharmaceutical Export Expansion:Generic drug manufacturers in Cairo and Alexandria are scaling ampoule and syrup bottle procurement to serve Gulf Cooperation Council markets, creating sustained pull for borosilicate and soda-lime container specifications.
- Returnable Deposit Systems:Beverage distributors operating across Greater Cairo have institutionalized bottle-return logistics, locking in circular procurement patterns that favor domestic glass over single-use plastic alternatives.
Market Restraints
- Natural Gas Price Volatility:Furnace operators face input cost pressure from Egypt's phased subsidy rationalization, with energy comprising 35-40% of production economics for continuous-melt operations.
- Import Dependency for Boron:Specialty container production relies on Turkish and German boron trioxide supply, exposing pharmaceutical vial manufacturers to foreign exchange and shipping cost fluctuations.
- Aluminum Can Substitution:Carbonated soft drink bottlers are piloting lightweight aluminum formats for export-bound premium SKUs, threatening glass share in temperature-sensitive logistics chains.
Strategic Opportunities
- Upper Egypt Greenfield Sites:Industrial zones near Sohag and Qena offer untapped land banks with proximity to limestone quarries, enabling integrated raw-material sourcing for new market entrants.
- Cosmetic Ampoule Demand:Egyptian skincare exporters are requesting small-format borosilicate containers with silk-screen decoration, opening margin-rich segments beyond traditional pharmaceutical applications.
- Egyptian General Authority for Standards and Quality Harmonization:BIS-equivalent certification alignment is unlocking Gulf Cooperation Council market access, creating regulatory tailwind for compliant domestic producers.
Industry Challenges
- Specialized Furnace Engineering Talent:Regenerative burner design and combustion optimization expertise remains concentrated among a handful of retiring European consultants, constraining rebuild timelines.
- Multi-Year Certification Cycles:Pharmaceutical container qualification with Egypt's national drug regulator requires 18-24 month stability testing protocols, delaying revenue realization for new product lines.
- Legacy Batch Plant Integration:Automated cullet handling and raw-material dosing systems face interoperability friction with 1980s-vintage furnace infrastructure, complicating digital transformation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Container Glass Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Containers End User: Food & Beverage, Pharmaceuticals, Personal Care, Chemicals Manufacturing Process: Blow Molding, Pressing, Tempering, Coating Capacity: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | United Glass Company, Misr Glass Manufacturing Company, Middle East Glass Manufacturing Company S.A.E., Schott A, Arab Pharmaceutical Glass Co, National Company for Glass and Crystal S.A.E., SGD Pharma Egypt, National Company for Glass Industries, Kandil Glass S.A.E., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Container Glass Market Trends and Innovations
Oxy-fuel combustion and lightweighting technologies are converging to reshape furnace economics and product specifications across Egyptian container glass manufacturing.
Advanced oxy-fuel burner systems are unifying emission reduction with thermal efficiency gains in Egyptian furnace rebuilds. Pharmaceutical and beverage producers are specifying these retrofits to preempt Environmental Affairs Agency enforcement actions. The technology is unifying compliance investment with operational cost control, compressing payback periods for capital-intensive upgrades.
Egypt's Environmental Affairs Agency air quality thresholds are compelling regenerative thermal oxidizer installation across all continuous-melt operations. Non-compliant facilities face production curtailment notices with 90-day remediation windows. Pharmaceutical exporters to European markets are additionally navigating pending carbon-border adjustment mechanisms, layering dual compliance burdens on furnace operators.
Beverage distributors are consolidating procurement under long-term supply agreements with dedicated furnace allocations, displacing spot-market purchasing. Coca-Cola bottlers and local spirits distributors are negotiating five-year contracts with volume commitments and price collars. This pattern concentrates most visibly in Alexandria's industrial corridor, where logistics proximity to Port Said enables export-bound production scheduling.
Egypt Container Glass Market Segmentation
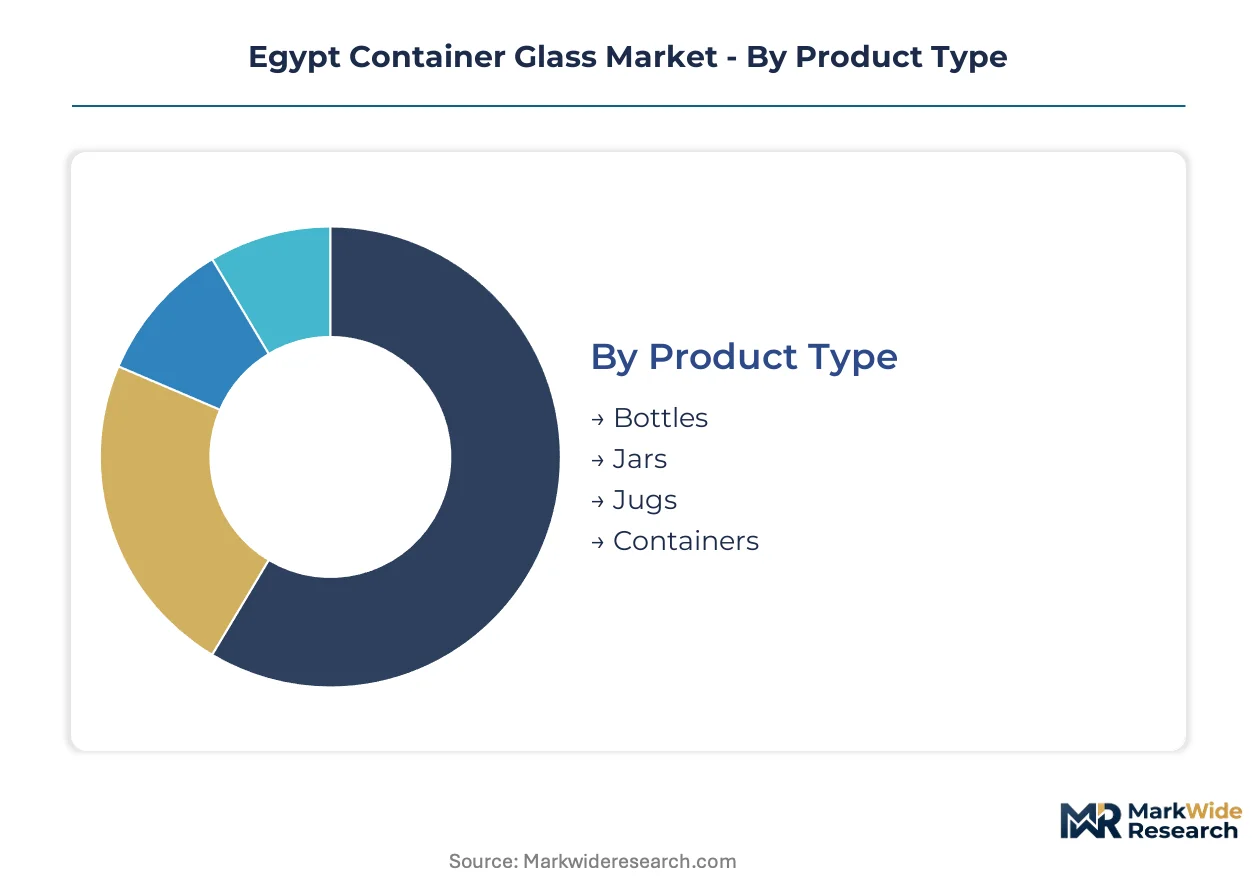
Container glass segmentation in Egypt reflects divergent technical requirements across beverage packaging, pharmaceutical containment, and industrial chemical storage. Each dimension—product geometry, end-use chemistry, forming method, and furnace scale—carries distinct margin profiles and regulatory exposure.
Product Type:
Standalone packaging formats dominate procurement volumes, while embedded or nested container systems serve specialized logistics chains.
- Bottles:Hollow soda-lime-silica vessels formed through blow molding, engineered with 70-74% silica content for oxygen barrier performance. Procurement concentrates among Coca-Cola bottlers and local spirits distributors in Alexandria's industrial corridor, where returnable deposit systems lock in circular procurement patterns.
- Jars:Wide-mouth pressed or blow-molded containers with enhanced thermal shock resistance for pasteurized food storage. Demand clusters in Greater Cairo food processors upgrading to premium packaging for Gulf Cooperation Council export eligibility under Egyptian General Authority for Standards and Quality mandates.
- Jugs:Large-format vessels typically 1-5 liter capacity for edible oils and industrial chemicals. Egyptian chemical distributors specify these for solvent storage where plastic permeation risks contamination.
- Containers:General-purpose rectangular or cylindrical formats for bulk pharmaceutical and cosmetic applications. Misr Glass Manufacturing Company allocates dedicated furnace capacity to this segment for captive pharmaceutical vial production.
Bottles lead volumes today; jars are gaining share fastest through food export packaging upgrades.
End User:
Cost tier stratification separates commodity beverage procurement from certified pharmaceutical containment requiring 18-24 month stability protocols.
- Food & Beverage:Dominant demand pool spanning carbonated soft drinks, edible oils, and processed foods. United Glass Company operates multiple large-capacity furnaces serving this segment with dedicated allocations under five-year supply agreements.
- Pharmaceuticals:Ampoule, vial, and syrup bottle specifications demanding borosilicate or high-grade soda-lime compliance with Egypt's national drug regulator. Generic drug manufacturers in Cairo and Alexandria are scaling procurement to serve Gulf Cooperation Council markets, climbing the fastest among end-use categories.
- Personal Care:Cosmetic ampoules and silk-screen decorated containers for skincare exporters. Middle East Glass Manufacturing Company S.A.E. anchors its position through dedicated borosilicate capacity for this segment.
- Chemicals:Solvent and reagent containment requiring chemical inertness and thermal stability. Laboratory applications favor borosilicate specifications from specialty furnace operators.
Food and beverage commands procurement scale today; pharmaceuticals shows the steepest expansion trajectory.
Manufacturing Process:
Application requirements dictate process selection, with hollow ware above 50ml favoring blow molding and wide-mouth geometries retaining pressing economics.
- Blow Molding:Dominant forming method for beverage bottles and pharmaceutical vials, utilizing compressed air to expand molten glass parisons. Egyptian furnace operators are retrofitting oxy-fuel combustion systems to this process to preempt Environmental Affairs Agency enforcement.
- Pressing:Mechanical forming for wide-mouth jars and containers with complex shoulder geometries, retaining cost advantage on thick-walled products. Legacy batch plants face interoperability friction when integrating automated cullet handling with 1980s-vintage pressing lines.
- Tempering:Controlled thermal treatment to enhance mechanical strength and thermal shock resistance. Food processors specify tempered glass for hot-fill applications and microwaveable packaging.
- Coating:Surface treatment applications including organic spray coatings for abrasion resistance and UV protection. Cosmetic exporters are requesting coated borosilicate containers for premium skincare positioning.
Blow molding leads volumes today; coating is gaining share fastest through cosmetic premiumization.
Capacity:
Supply concentration favors large-scale furnace operations with regenerative thermal oxidizer compliance, while custom capacity serves qualification-intensive pharmaceutical lines.
- Large Scale:Continuous-melt furnaces exceeding 300 tons daily output, serving beverage bottlers with volume commitments and price collars. Energy comprises 35-40% of production economics, exposing operators to Egypt's phased natural gas subsidy rationalization.
- Medium Scale:Mid-capacity furnaces serving regional food processors and chemical distributors. These facilities navigate dual compliance burdens from Environmental Affairs Agency thresholds and pending European carbon-border adjustments.
- Small Scale:Batch furnaces and specialty lines for custom pharmaceutical and cosmetic runs. Emission mandates are decoupling small-scale producers from viable participation, consolidating output among capital-rich incumbents.
- Custom:Dedicated furnace allocations for long-term supply agreements with pharmaceutical exporters. SGD Pharma Egypt maintains custom capacity with dedicated quality laboratories for third-party certification maintenance.
Large scale leads volumes today; custom capacity is expanding most quickly through pharmaceutical qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized furnace engineering talent concentrates in Greater Cairo and Alexandria, anchoring Egypt's container glass production base and shaping sub-regional investment flows across the Nile corridor.
Greater Cairo
Generic drug manufacturers and beverage bottlers drive ampoule and syrup bottle procurement throughout Cairo and Giza. Egypt's Environmental Affairs Agency enforces air quality thresholds that compel regenerative thermal oxidizer installations among furnace operators. The 6th of October City industrial zone hosts multiple large-capacity furnaces serving Coca-Cola bottlers with dedicated allocations under long-term supply agreements.
Alexandria
Port proximity enables export-bound production scheduling for European and Gulf Cooperation Council pharmaceutical markets. The Egyptian General Authority for Standards and Quality mandates BIS-equivalent glass migration limits that condition export eligibility. El-Amreya and Borg El-Arab industrial corridors concentrate borosilicate capacity for laboratory and cosmetic applications.
Suez Canal Zone
Limestone quarries and captive raw-material sourcing sustain cost leadership for pharmaceutical vial production near Suez and Ismailia. Egypt's PLI scheme for local manufacturing redirects foreign direct investment toward domestic furnace capacity with tiered subsidy structures. The Ain Sokhna industrial cluster attracts automotive and pharmaceutical packaging lines qualifying for production-linked incentives.
Delta Region
Edible oil processors and food manufacturers generate demand for wide-mouth jars and large-format jugs across Damietta and Mansoura. Returnable deposit systems institutionalized by beverage distributors lock in circular procurement patterns favoring domestic glass. Kafr El-Sheikh and Dakahlia governorates host medium-scale furnaces serving regional food processors with hot-fill and pasteurization-compatible packaging.
Upper Egypt
Untapped land banks near Sohag and Qena offer integrated raw-material sourcing opportunities for new market entrants. Limestone quarry proximity enables backward integration into captive supply chains for soda-lime-silica batch production. Beni Suef and Minya industrial zones attract greenfield investment targeting cosmetic ampoule demand from Egyptian skincare exporters.
Egypt Container Glass Market Competitive Landscape
The competitive structure tilts toward capital-rich incumbents with captive raw-material positions and regenerative thermal oxidizer compliance. Small-scale furnace operators face decoupling from viable participation as emission mandates escalate compliance burdens. Three archetypes dominate: integrated quarry-to-furnace operators, specialty borosilicate producers, and contract manufacturers serving multinational beverage bottlers. Capacity expansion and long-term supply agreements with volume commitments represent the dominant competitive moves, compressing spot-market participation.
Among Egyptian-based manufacturers, Misr Glass Manufacturing Company and Middle East Glass Manufacturing Company S.A.E. exemplify the integrated and specialty archetypes respectively, while United Glass Company occupies a position representing scale-driven beverage supply. SGD Pharma Egypt anchors the pharmaceutical qualification-intensive tier with dedicated quality laboratory infrastructure. These named entities represent the structural concentration of furnace capacity among operators capable of navigating Egypt's dual compliance layers from Environmental Affairs Agency thresholds and pending European carbon-border adjustments.
| Leading Market Players |
|---|
| United Glass Company |
| Misr Glass Manufacturing Company |
| Middle East Glass Manufacturing Company S.A.E. |
| Schott A |
| Arab Pharmaceutical Glass Co |
| National Company for Glass and Crystal S.A.E. |
| SGD Pharma Egypt |
| National Company for Glass Industries |
| Kandil Glass S.A.E. |
| Others |
Pricing and Supply Chain Analysis
Beverage bottlers operating under five-year supply agreements with dedicated furnace allocations anchor pricing power among Egyptian container glass producers. This buyer concentration locks in contract-based long-term offtake structures that compress spot-market participation and stabilize volume commitments.
Pricing Analysis
Service bundling separates furnace capacity reservations from standalone container procurement, with pharmaceutical exporters paying premium rates for dedicated quality laboratory access and third-party certification maintenance. Price differentiation hinges on certification grade alignment with Egyptian General Authority for Standards and Quality mandates and volume scale under multi-year agreements. Cost compression in commodity beverage tiers is intensifying because natural gas subsidy rationalization feeds directly into energy-intensive furnace economics. Generic drug manufacturers demonstrate highest price sensitivity due to Gulf Cooperation Council export margin constraints, while cosmetic ampoule buyers show lowest sensitivity given silk-screen decoration premiums.
Supply Chain Analysis
Single-source vulnerability sits with Turkish and German boron trioxide supply for specialty pharmaceutical vial production. Raw material sourcing draws from domestic limestone quarries near Suez, imported Turkish soda ash, and German boron trioxide for borosilicate specifications. Supply chain risk centers on foreign exchange exposure for boron-dependent pharmaceutical lines. Distribution runs through Alexandria's industrial corridor for export-bound scheduling and Greater Cairo logistics hubs serving domestic beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's container glass market has entered a late-cycle quality phase where pharmaceutical ampoule specifications and borosilicate certification tiers command sustained premium positioning. Generic drug manufacturers scaling Gulf Cooperation Council exports are pulling demand toward higher-grade containment standards.
For Market Incumbents: Cement cost leadership through captive limestone quarry positions near Suez and regenerative thermal oxidizer compliance ahead of Environmental Affairs Agency enforcement windows. Prioritize furnace rebuild cycles synchronized with pending European carbon-border adjustment timelines. Defend against aluminum can substitution in carbonated soft drink export channels by locking spirits distributors into returnable deposit system expansions. For New Entrants and Emerging Players: Contract manufacturers serving multinational beverage brands represent the most accessible channel entry point for greenfield furnace operators. Target Upper Egypt industrial zones near Sohag for integrated raw-material sourcing and lower land costs. Pursue cosmetic ampoule demand from Egyptian skincare exporters as the most penetrable premium segment, leveraging silk-screen decoration capabilities as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Pharmaceutical packaging specialists are the most active acquirer category in this space, driven by qualification-intensive regulatory barriers. Long-term viability rests on furnace operators capable of navigating dual compliance layers from Egyptian Environmental Affairs Agency thresholds and European carbon-border mechanisms. Monitor borosilicate capacity utilization rates as the critical inflection signal for specialty tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | Suez-based captive sourcing sustains cost leadership against gas price volatility. |
| Oxy-Fuel Furnace Retrofit Program | Environmental Affairs Agency compliance unifies emission reduction with thermal efficiency gains. |
| Pharmaceutical Certification Investment | Egyptian General Authority for Standards and Quality alignment unlocks Gulf Cooperation Council export eligibility. |
| Cosmetic Ampoule Capacity Addition | Silk-screen decoration capabilities capture margin-rich skincare exporter demand. |
| Long-Term Supply Agreement Expansion | Five-year contracts with Coca-Cola bottlers and spirits distributors displace spot-market participation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged furnace operations managers at Egyptian glass manufacturers, procurement leads at generic drug exporters, beverage bottler supply chain directors, and Environmental Affairs Agency compliance officers. Secondary validation drew from Egyptian General Authority for Standards and Quality filings, customs trade data on boron trioxide imports, and production disclosures from Suez Canal Zone industrial clusters. Bottom-up capacity modeling and top-down demand aggregation were triangulated against PLI scheme incentive allocations.
Segment-weighting distributed value and volume across product geometry, end-use chemistry, forming method, and furnace scale dimensions. The analytical framework modeled interactions between pharmaceutical export expansion, beverage returnable deposit system penetration, and emission compliance investment cycles throughout the projection horizon. CAGRs were derived from cohort-based growth rate analysis applied to each segment's demand drivers. Forecast inputs incorporated natural gas subsidy rationalization trajectories and European carbon-border adjustment implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to boron supply disruption, aluminum can substitution acceleration, and regulatory enforcement intensity shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Decanters Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market