
 Boston Round Glass Bottle Market | 2026-2036
Boston Round Glass Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Boston Round Glass Bottle Market Intelligence
Capital-intensity divergence between automated borosilicate forming lines and conventional soda-lime operations is rotating competitive advantage toward integrated manufacturers. Gerresheimer AG leverages captive glass tubing production to sustain margin control across pharmaceutical-grade amber bottle output. Owens-Illinois Inc. anchors North American volume through furnace-scale efficiency in clear glass configurations. Shandong Pharmaceutical Glass Co Ltd competes on cost-optimized cobalt blue capacity serving domestic cosmetic and aromatherapy demand.
A Boston Round Glass Bottle denotes a cylindrical container with rounded shoulders, narrow neck, and uniform wall thickness, typically formed from Type III soda-lime or Type I borosilicate glass through IS machine or press-and-blow processes, designed for chemical stability and light protection in liquid storage. Amber glass bottles dominate pharmaceutical applications where UV-blocking properties meet USP <660> compliance requirements. Clear glass bottles lead cosmetic and essential oil segments where visual product presentation drives shelf appeal. Child-resistant closure types command premium positioning as regulatory mandates tighten across pediatric safety frameworks.
FDA container closure integrity standards, EPA glass manufacturing emissions protocols, and EU REACH chemical migration limits collectively elevate barrier performance requirements and supplier qualification burdens. These frameworks push pharmaceutical firms toward documented batch consistency and extractables testing from amber and cobalt blue variants. Stakeholders must monitor evolving state-level extended producer responsibility laws and pharmaceutical serialization mandates to anticipate capital deployment timing for compliant capacity.
Market Dynamics
FDA's updated container closure integrity guidelines are forcing pharmaceutical manufacturers to requalify existing bottle inventories and source amber glass with documented extractables profiles, compressing supplier approval timelines and concentrating procurement among qualified vendors.
Growth Catalysts
- Biologics expansion:Compounding pharmacies and cell therapy manufacturers require Type I borosilicate bottles with thermal shock resistance for parenteral formulations, pulling demand toward pharmaceutical-grade capacity.
- EU MDR serialization mandates:European medical device regulations now require unique device identifiers on primary packaging, driving integrated bottle-and-closure sourcing from qualified molders.
- Essential oil aromatherapy:Cobalt blue and amber variants with UV-blocking properties capture shelf space in wellness retail channels across Germany and United States specialty stores.
Market Restraints
- Natural gas cost volatility:Soda-lime and borosilicate furnace operations depend on natural gas feedstock, exposing margin structures to European and North American energy price swings.
- Borosilicate tubing concentration:Type I glass pharmaceutical bottles rely on captive tubing supply from Schott and Corning facilities in Germany and United States, creating single-source vulnerability.
- Plastic polymer substitution:High-density polyethylene and cyclic olefin copolymer vials compete in parenteral applications where break resistance outweighs glass barrier performance.
Strategic Opportunities
- India contract packaging:CDSCO's accelerated approval pathways for generic injectables position Indian CMOs to absorb amber bottle demand from cost-sensitive formulation sponsors.
- Connected packaging convergence:Near-field communication tags and printed electronics integration with glass surfaces enable cold-chain verification for temperature-sensitive biologics.
- State EPR legislation:California and Maine extended producer responsibility laws create first-mover advantage for bottle manufacturers with post-consumer recycled content certification.
Industry Challenges
- Container closure integrity validation:FDA's 2023 guidance requires probabilistic leak detection methods, extending qualification timelines for new bottle-closure combinations by 12-18 months.
- IS machine technician scarcity:Automated glass forming lines require specialized mechanical and thermal process expertise that aging workforce demographics in United States and Germany cannot replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boston Round Glass Bottle Market |
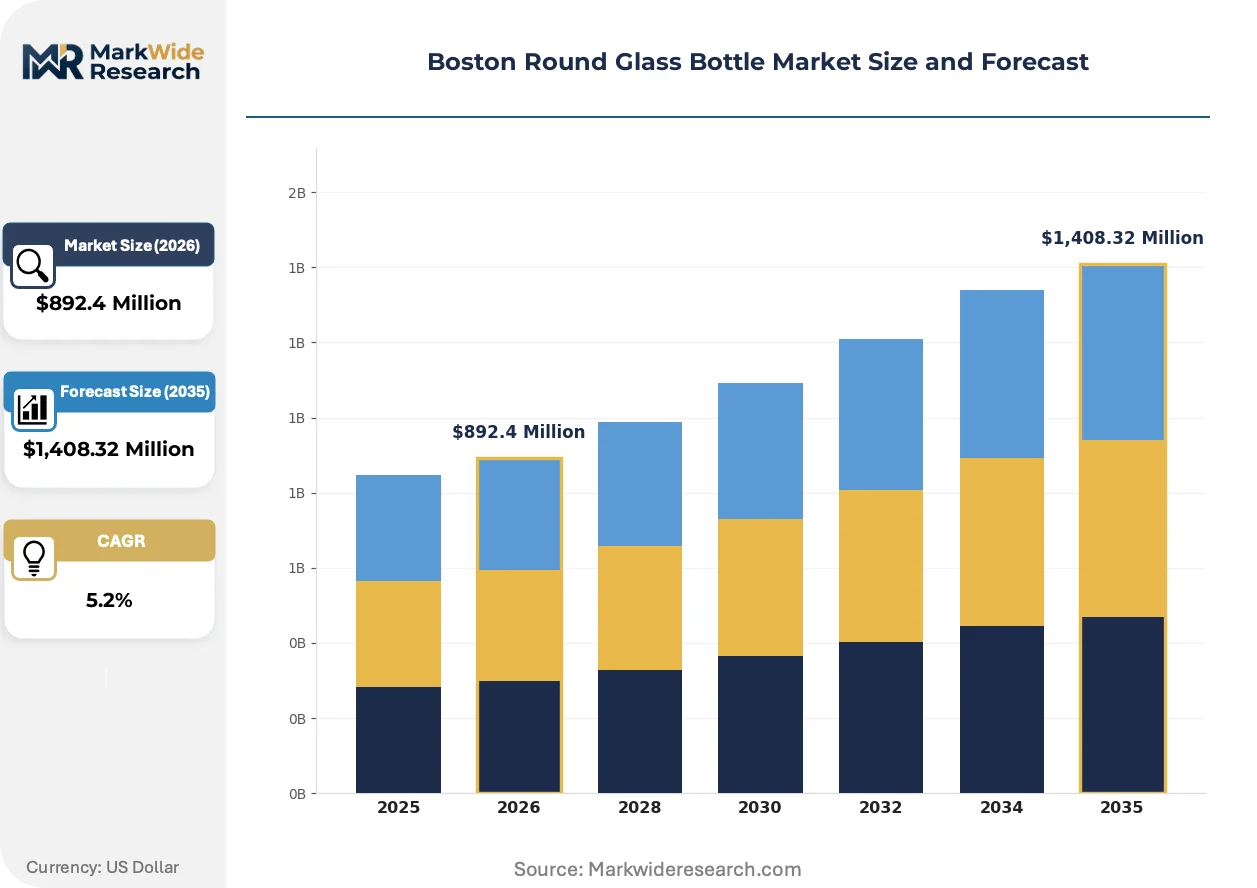
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,408.32 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amber Glass Bottles, Clear Glass Bottles, Cobalt Blue Glass Bottles, Frosted Glass Bottles Application: Essential Oils, Pharmaceuticals, Cosmetics, Food Flavorings, Aromatherapy Closure Type: Dropper Caps, Screw Caps, Child-Resistant Caps, Spray Pumps, Plastic Caps End User: Cosmetic Manufacturers, Pharmaceutical Firms, Food Service Providers, Aromatherapy Producers |
| Companies Covered | Gerresheimer AG, O.Berk Company LLC, E.D. Luce Packaging, MJS Packaging, BASCO Inc., Shandong Pharmaceutical Glass Co Ltd, The Cary Company, The Boston Round Company, Owens-Illinois Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boston Round Glass Bottle Market Strategic Shifts & Innovations
Formulation sponsors are demanding documented batch consistency and extractables testing, compressing the qualified supplier base while opening white space for integrated manufacturers with in-house analytical capabilities.
Siliconization of borosilicate interior surfaces is fragmenting the parenteral packaging landscape. This plasma-deposited barrier coating reduces protein adsorption in biologic formulations. Large-molecule drug manufacturers are adopting siliconized vials for high-value monoclonal antibodies. The technology is fragmenting procurement patterns by creating a premium tier above standard Type I glass, compressing margin for undifferentiated commodity bottle suppliers.
REACH chemical migration limits are tightening extractables thresholds for pharmaceutical glass across European manufacturing sites. ECHA's updated substance restrictions now cover heavy metal leachates from cobalt colorants in cosmetic applications. Amber bottle exporters to Germany and France must demonstrate compliance through third-party analytical certification, shifting competitive advantage toward manufacturers with captive testing laboratories.
Direct-to-consumer essential oil brands are consolidating bottle procurement through vertical e-commerce platforms, bypassing traditional distribution intermediaries. Young Living and doTerra-scale operators now specify custom cobalt blue configurations with child-resistant droppers through dedicated supplier portals. This channel compression is most visible in United States wellness markets, where subscription-based replenishment models lock in multi-year bottle supply agreements.
Boston Round Glass Bottle Market Segmentation
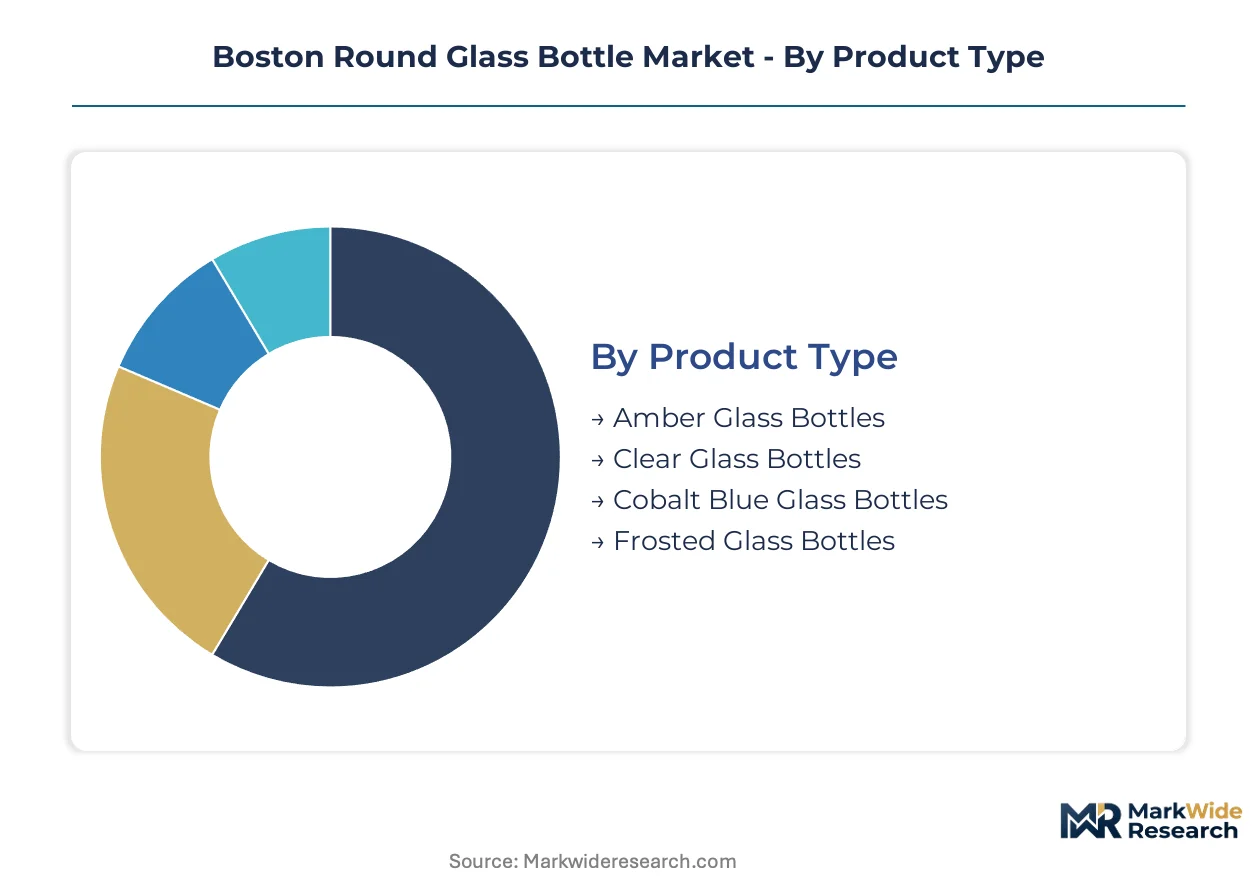
Segmentation in the Boston Round Glass Bottle Market reveals how formulation requirements, regulatory compliance, and channel economics fragment procurement patterns across pharmaceutical, cosmetic, and wellness verticals. Understanding these divides exposes where integrated manufacturers can capture premium positioning versus commodity volume plays.
Product Type:
Amber glass dominates pharmaceutical and wellness channels where light protection commands specification premiums, while clear and cobalt variants flow through cosmetic retail and direct-to-consumer aromatherapy platforms.
- Amber Glass Bottles:Formulated with iron-sulfur amber colorants achieving UV transmission below 10% at 290-450nm wavelengths. Pharmaceutical compounders in the United States and Germany specify these for USP <660> compliant parenteral storage, with FDA container closure integrity mandates compressing supplier qualification to documented extractables profiles.
- Clear Glass Bottles:Soda-lime or borosilicate compositions with no color additives, prioritizing visual product presentation. Cosmetic manufacturers in Germany and essential oil brands across United States specialty retail channels drive volume, where shelf transparency outweighs photostability requirements.
- Cobalt Blue Glass Bottles:Cobalt oxide colorants provide UV-blocking with distinctive aesthetic differentiation. Aromatherapy producers and wellness brands specify these for premium positioning in subscription-based replenishment models.
- Frosted Glass Bottles:Acid-etched or sandblasted surface treatments creating matte diffusion. Cosmetic serums and high-end essential oil applications favor this finish for tactile differentiation in direct-to-consumer channels.
By volume, clear glass leads. By growth pace, amber pharmaceutical grades are climbing the fastest.
Application:
Application segmentation tracks how end-use chemistry dictates glass type, closure integration, and regulatory burden across formulation categories.
- Essential Oils:Volatile organic compounds demand Type III soda-lime or Type I borosilicate with documented chemical resistance. Cobalt blue and amber variants capture United States wellness retail through Young Living-scale vertical e-commerce platforms.
- Pharmaceuticals:Parenteral formulations, oral solutions, and compounding pharmacy stocks require Type I borosilicate thermal shock resistance. CDSCO accelerated approval pathways for Indian generic injectables are pulling amber bottle demand toward contract packaging hubs.
- Cosmetics:Serums, toners, and facial oils prioritize visual presentation. Clear and frosted configurations dominate, with child-resistant droppers specified for regulatory compliance in pediatric safety frameworks.
- Food Flavorings:Extracts, concentrates, and culinary oils require FDA food-contact compliance. Smaller volume formats with phenolic or metal closures prevail in food service distribution.
- Aromatherapy:Diffuser blends and therapeutic oils combine UV protection with aesthetic differentiation. German and United States specialty retailers drive specification toward cobalt blue with integrated dropper assemblies.
Pharmaceutical applications command the highest per-unit margins. Essential oils represent the steepest expansion trajectory through direct-to-consumer channel compression.
Closure Type:
Closure segmentation determines child-resistance compliance, dosing precision, and supply chain integration complexity across end-use categories.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms meeting US 16 CFR 1700 and ISO 8317 standards. Pharmaceutical firms and aromatherapy brands targeting pediatric safety mandates absorb 15-25% premiums over standard closures.
- Dropper Caps:Glass or plastic pipette assemblies with bulb or button actuation. Essential oil and cosmetic serum applications specify these for precise volumetric dosing.
- Screw Caps:Continuous thread aluminum or phenolic constructions. Food flavorings and bulk pharmaceutical intermediates favor this cost-optimized configuration.
- Spray Pumps:Fine mist or stream actuation for topical and room applications. Aromatherapy producers integrate these for diffuser refill formats.
- Plastic Caps:Polypropylene or polyethylene constructions for non-critical containment. Cosmetic manufacturers specify these for economy-tier positioning.
Child-resistant closures generate the highest margin contribution. Dropper assemblies are gaining share fastest through wellness and cosmetic serum proliferation.
End User:
End user segmentation exposes how procurement scale, technical specification depth, and supplier qualification requirements stratify the customer base.
- Pharmaceutical Firms:Large-molecule biologics manufacturers and generic injectables sponsors demand documented batch consistency, extractables testing, and Type I borosilicate thermal shock resistance. FDA container closure integrity guidelines force requalification of existing inventories.
- Cosmetic Manufacturers:Formulation houses and contract packagers prioritize visual differentiation, shelf appeal, and flexible minimum order quantities. Clear and frosted configurations dominate with integrated dropper or pump closures.
- Aromatherapy Producers:Young Living-scale operators and mid-tier wellness brands consolidate procurement through vertical e-commerce platforms. Cobalt blue and amber variants with child-resistant droppers lock in multi-year supply agreements.
- Food Service Providers:Flavoring houses and culinary oil packagers require FDA food-contact compliance with cost-optimized phenolic closures. Lower specification burden enables broader supplier qualification.
Pharmaceutical firms anchor value concentration. Aromatherapy producers are expanding procurement volume most rapidly through subscription model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for Boston round glass bottles diverges sharply across geographies, with pharmaceutical buyers in Germany and the United States absorbing specification premiums while Indian contract manufacturers and Chinese wellness brands drive volume through cost-optimized sourcing.
United States
Compounding pharmacies and biologics manufacturers anchor pharmaceutical-grade amber bottle procurement, with FDA container closure integrity guidelines compressing supplier qualification timelines. Young Living-scale aromatherapy operators consolidate cobalt blue and amber procurement through vertical e-commerce platforms, locking multi-year supply agreements for subscription-based replenishment models in Utah and California wellness clusters.
Germany
Gerresheimer AG leverages captive borosilicate tubing production to sustain margin control across pharmaceutical-grade amber output, serving EMA-regulated parenteral formulation sponsors. REACH chemical migration limits and ECHA heavy metal restrictions on cobalt colorants now require third-party analytical certification for cosmetic bottle exports, shifting advantage toward manufacturers with in-house testing laboratories in Baden-Württemberg glassmaking centers.
China
Shandong Pharmaceutical Glass Co Ltd competes on cost-optimized cobalt blue capacity serving domestic cosmetic and aromatherapy demand, with NMPA serialization mandates for pharmaceutical packaging driving integrated bottle-and-closure sourcing. Yangtze River Delta contract packaging hubs absorb export-oriented amber bottle production for essential oil brands targeting United States and German wellness retail channels.
India
CDSCO accelerated approval pathways for generic injectables position Indian CMOs to absorb amber bottle demand from cost-sensitive formulation sponsors, with Maharashtra and Gujarat pharmaceutical clusters expanding Type III soda-lime forming capacity. Domestic essential oil producers specify cobalt blue variants with child-resistant droppers for Ayurvedic and aromatherapy exports to Middle Eastern and Southeast Asian markets.
Boston Round Glass Bottle Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Boston round glass bottle market. Integrated manufacturers with captive borosilicate tubing supply and in-house analytical capabilities capture pharmaceutical-grade premiums, while regional soda-lime specialists compete on volume through furnace-scale efficiency. The competitive terrain stratifies into three archetypes: upstream-integrated pharmaceutical-grade suppliers, scale-driven North American volume producers, and cost-optimized Asian commodity manufacturers. Dominant competitive moves include backward integration into glass tubing production and geographic expansion into Indian contract packaging hubs.
Among Germany-based pharmaceutical packaging specialists, Gerresheimer AG exemplifies the upstream-integrated archetype through captive borosilicate forming operations. Owens-Illinois Inc. anchors North American volume positioning through furnace-scale efficiency in clear glass configurations. Shandong Pharmaceutical Glass Co Ltd occupies the cost-optimization tier, serving domestic and export markets with cobalt blue and amber variants for cosmetic and wellness applications.
| Leading Market Players |
|---|
| Gerresheimer AG |
| O.Berk Company LLC |
| E.D. Luce Packaging |
| MJS Packaging |
| BASCO Inc. |
| Shandong Pharmaceutical Glass Co Ltd |
| The Cary Company |
| The Boston Round Company |
| Owens-Illinois Inc. |
| Others |
Cost & Logistics Intelligence
Plastic polymer substitution in parenteral packaging is fragmenting procurement patterns and compressing glass bottle pricing power in break-sensitive applications, while simultaneously concentrating premium-grade borosilicate supply among captive tubing producers in Germany and the United States.
Pricing Analysis
After-sales service contracts for extractables testing and batch certification now generate lifetime value exceeding per-unit bottle margins. Three-tier pricing structure across pharmaceutical-grade amber, cosmetic clear glass, and commodity soda-lime economy tiers stratifies the market, with FDA container closure integrity mandates widening spreads between documented and undifferentiated supply. Cost compression in standard soda-lime configurations is intensifying because Indian contract manufacturers absorb volume from cost-sensitive generic sponsors. Pharmaceutical firms demonstrate lowest price sensitivity due to regulatory qualification burdens, while wellness brands and cosmetic manufacturers exhibit highest elasticity.
Supply Chain Analysis
Germany and the United States anchor pharmaceutical-grade borosilicate tubing production, with Schott and Corning facilities feeding captive forming operations at Gerresheimer and specialized glass converters. Type I borosilicate tubing, cobalt oxide colorants, and natural gas furnace feedstock constitute critical input dependencies. Single-source vulnerability in borosilicate tubing supply creates structural exposure to production disruptions at German and United States facilities. Distribution runs through direct procurement contracts for pharmaceutical grades, while cosmetic and wellness volumes flow through distributor networks and vertical e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cyclic olefin copolymer and high-density polyethylene vials in parenteral applications, where polymer break resistance is displacing glass barrier performance in cost-sensitive therapeutic categories.
For Market Incumbents: Compound defensive positioning through backward integration into captive borosilicate tubing production and in-house analytical laboratories for extractables certification. FDA container closure integrity mandates compress supplier qualification timelines, creating lock-in effects for qualified vendors with documented batch consistency capabilities. Geographic capacity expansion into Indian contract packaging hubs captures CDSCO-accelerated generic injectables demand. For New Entrants and Emerging Players: Anchor in white-space opportunities at the intersection of connected packaging and cold-chain verification, where near-field communication integration with glass surfaces remains underdeveloped. Indian pharmaceutical contract manufacturing organizations represent the most penetrable customer segment given CDSCO regulatory momentum and cost-sensitive procurement profiles. Direct-to-consumer wellness brands offer go-to-market traction through subscription-based replenishment models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors upstream-integrated manufacturers with captive tubing supply and in-house testing infrastructure. Long-term viability over the next decade hinges on regulatory qualification moats deepening around FDA and EMA compliance documentation. Acquisition targets should demonstrate extractables testing capabilities and pharmaceutical-grade amber output. The signal to watch is state-level extended producer responsibility legislation adoption in California and Maine, which would accelerate recycled content certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Gerresheimer's captive supply model demonstrates margin control against Schott and Corning pricing power. |
| In-House Extractables Testing Laboratories | FDA container closure integrity guidelines elevate analytical certification to competitive differentiator status. |
| Geographic Expansion into Indian CMO Hubs | CDSCO accelerated approval pathways position Maharashtra and Gujarat clusters for amber bottle demand absorption. |
| Connected Packaging Integration | Near-field communication tags enable cold-chain verification for temperature-sensitive biologics shipments. |
| Post-Consumer Recycled Content Certification | California and Maine extended producer responsibility laws create first-mover advantage for compliant manufacturers. |
Research Approach
A standing panel of pharmaceutical packaging procurement managers, glass forming plant engineers, regulatory affairs specialists at FDA and EMA, and contract manufacturing organization supply chain directors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA container closure integrity guidance documents, ECHA REACH substance restriction updates, CDSCO regulatory circulars, and customs trade data for glass pharmaceutical packaging. Bottom-up volume modeling triangulated against top-down market sizing across amber, clear, cobalt blue, and frosted product configurations.
Consistency checks validated volume and value outputs against external benchmarks including pharmaceutical serialization mandate implementation timelines and natural gas cost volatility indices. The analytical framework modeled demand across product type, application category, closure integration complexity, and end-user procurement scale throughout the projection horizon. CAGRs derived from regression analysis of historical shipment data and forward-looking capacity expansion announcements, with specific inputs including biologics pipeline growth rates and essential oil direct-to-consumer channel penetration.
Decision-makers should treat outputs as directional under assumptions of sustained FDA regulatory stringency and stable natural gas feedstock pricing; material deviation in polymer substitution rates or energy cost spikes would warrant model refresh. Recalibration cycles align with material shifts in container closure integrity guidance updates and extended producer responsibility legislation adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Glass Frosting for Packaging Market