
 Nigeria Container Glass Market | 2026-2036
Nigeria Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Container Glass Market Insights
The National Environmental Standards and Regulations Enforcement Agency (NESREA) plastic reduction mandates is restructuring container procurement across Nigerian consumer sectors. Beta Glass Nigeria Plc leverages its backward integration into cullet recycling to sustain cost advantages in bottle production. Ardagh Glass Packaging Nigeria Limited anchors premium pharmaceutical vial supply through dedicated borosilicate lines. Frigoglass Industries (Nigeria) Limited competes in the returnable bottle segment with heat-tempered designs for carbonated drinks.
Container glass comprises soda-lime-silica formulations melted at temperatures exceeding 1500°C, then formed through blow-and-blow or press-and-blow processes into rigid, chemically inert vessels for liquid and solid containment. Bottles dominate Nigerian output, with amber and flint grades commanding premium placement in beer and pharmaceutical packaging respectively. Food & Beverage end users absorb the majority of domestic tonnage, while Cosmetics applications generate higher per-unit margins through decorative finishing and custom molds. The Packaging application segment ties directly to NAFDAC serialization requirements, pushing pharmaceutical buyers toward traceable glass primary containers.
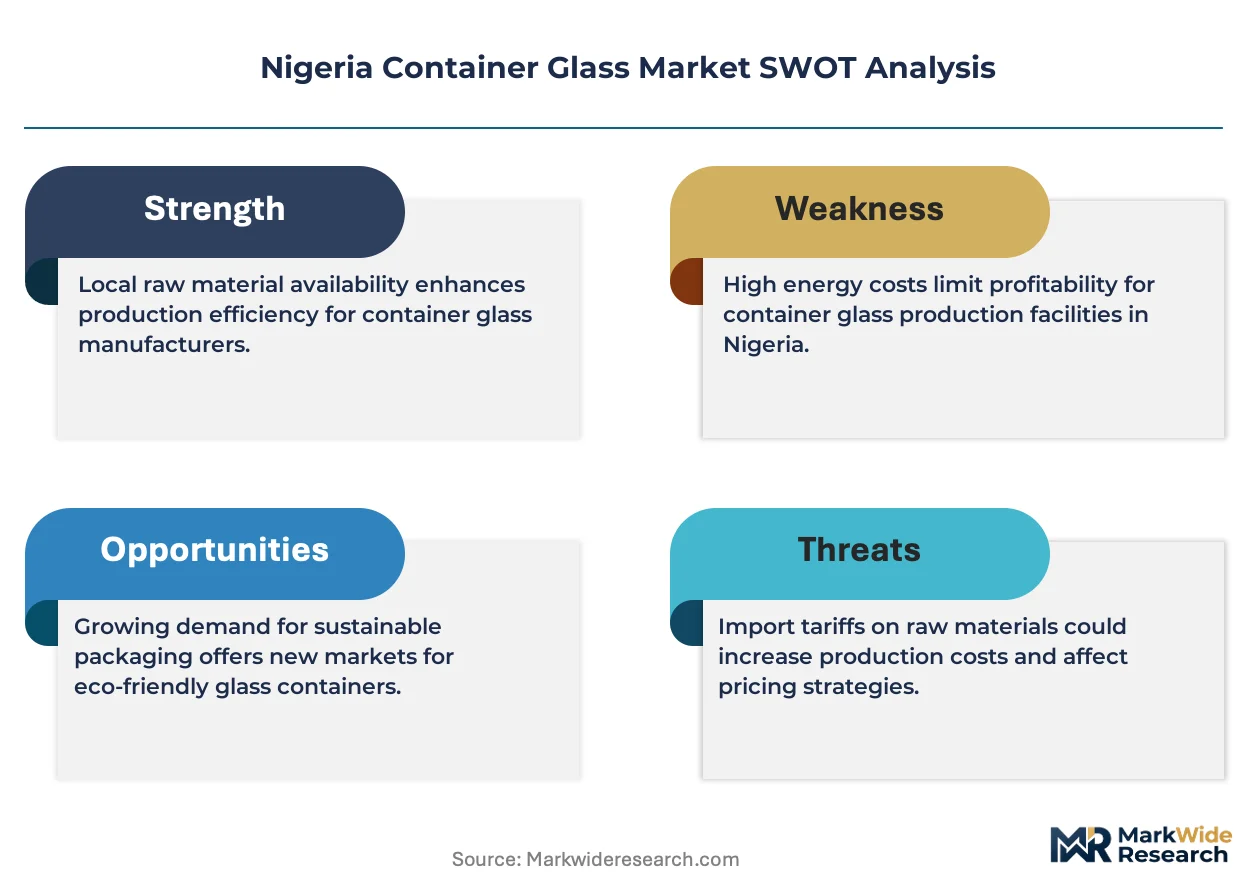
NAFDAC enforces pharmacopeial compliance for drug-contact packaging, while Standards Organisation of Nigeria (SON) certifies dimensional tolerances and thermal shock resistance for commercial glassware. NESREA extended producer responsibility rules now require glass manufacturers to document recycling recovery rates, raising capital requirements for new market entrants. Stakeholders must monitor whether federal import tariff adjustments on cullet and raw silica sand alter the economics of domestic melting versus finished-glass imports.
Market Dynamics
NAFDAC's serialization mandates for pharmaceutical packaging are compressing procurement cycles as drug manufacturers abandon polymer alternatives for traceable glass primary containers. This regulatory pressure is restructuring supplier relationships across Nigerian manufacturing corridors.
Growth Catalysts
- Plastic displacement mandates:NESREA enforcement of extended producer responsibility rules is forcing beverage bottlers to source returnable glass formats at scale.
- Pharmaceutical compliance upgrades:NAFDAC pharmacopeial standards for drug-contact materials are eliminating polymer vials from oncology and parenteral drug lines.
- Lagos industrial clustering:Southwestern manufacturing corridors concentrate melting capacity within 150 kilometers of Nigeria's largest beverage production bases.
Market Restraints
- Energy cost volatility:Natural gas supply interruptions at Nigerian LNG terminals create furnace operating cost spikes that compress margin structures.
- Cullet import dependency:Domestic silica sand beneficiation capacity constraints force manufacturers to source processed cullet through Lagos port channels.
- Polymer substitution resilience:PET bottle cost advantages in still-water and edible-oil segments limit glass penetration in price-sensitive categories.
Strategic Opportunities
- Northern Nigeria expansion:Kano and Kaduna pharmaceutical manufacturing zones remain underserved by borosilicate vial suppliers.
- Cosmetics decorative finishing:Premium skincare brands in Lagos and Abuja are commissioning custom-molded amber and cobalt glass for shelf differentiation.
- Recycling infrastructure incentives:NESREA recovery-rate documentation requirements reward manufacturers with captive cullet collection networks.
Industry Challenges
- Furnace engineering talent scarcity:Nigerian technical institutes produce insufficient refractory specialists and combustion engineers for float and container glass expansion.
- NAFDAC certification timelines:Pharmaceutical packaging approvals stretch 18-24 months, freezing supplier switches until compliance verification completes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Container Glass Market |
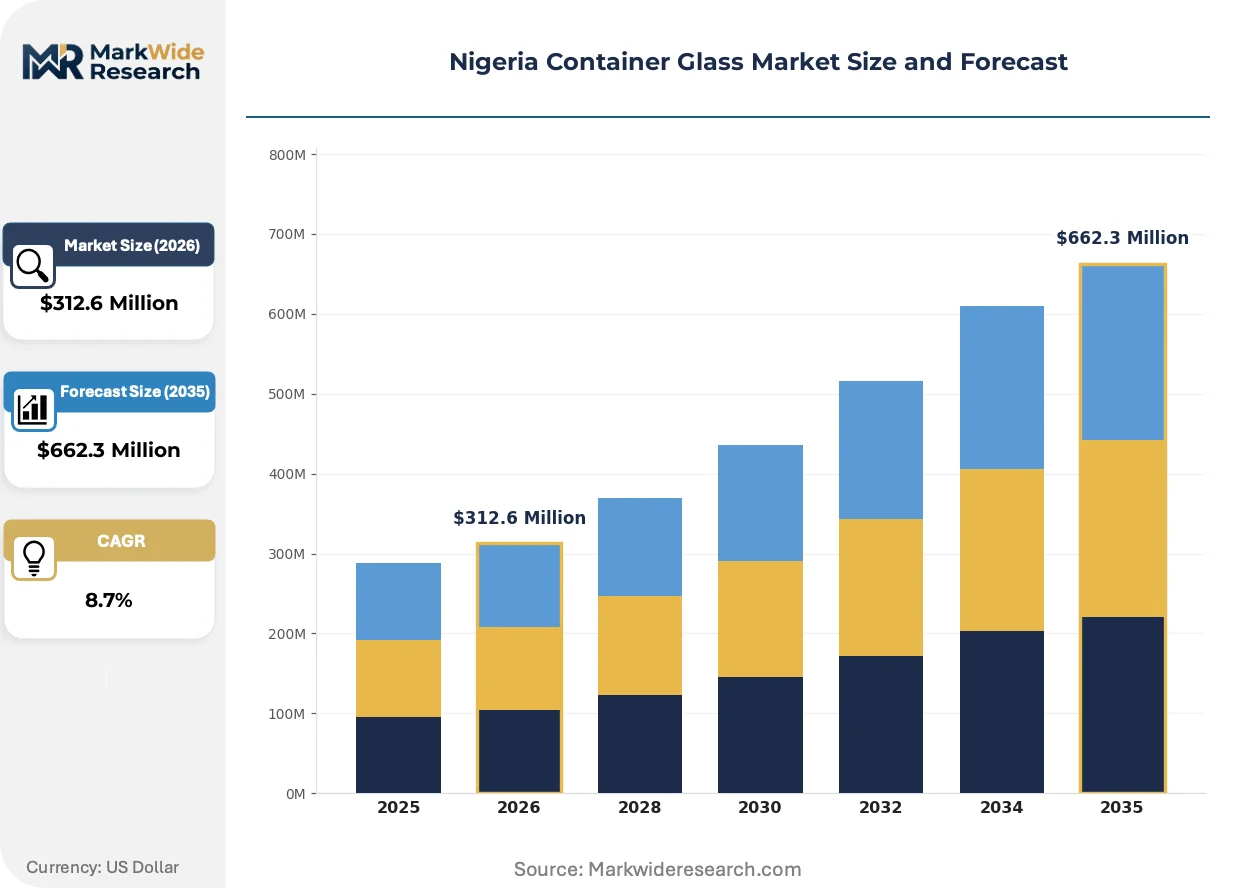
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Containers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Application: Packaging, Storage, Transport, Display Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Technoglass Industries Limited, Nampak Glass, Frigoglass Industries (Nigeria) Limited, Avon Crowncaps & Containers Nigeria Limited, Greif, Ardagh Glass Packaging Nigeria Limited, The Chagoury Group, Twinstar Industries Limited, Beta Glass Nigeria Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Container Glass Market Trends and Innovations
Digital traceability integration and furnace efficiency upgrades are compressing production economics while expanding addressable applications for Nigerian glass manufacturers.
Electromagnetic boosting technology is unifying temperature control precision in regenerative furnaces. Nigerian container glass producers are retrofitting existing float lines to reduce energy intensity per ton of melted soda-lime-silica. This unifying capability is enabling smaller batch runs for pharmaceutical vials without sacrificing thermal uniformity.
NAFDAC's draft guidance on blockchain-enabled serialization for drug packaging is mandating machine-readable codes on primary containers. Pharmaceutical manufacturers must redesign label adhesion and surface treatments to accommodate laser-etched and printed traceability markers. Injectable drug lines in Lagos and Ogun State are piloting these formats ahead of enforcement deadlines.
Direct supplier relationships are displacing distributor intermediaries in beverage procurement. Major Nigerian brewers are negotiating multi-year offtake agreements with glassworks for heat-tempered returnable bottles. This pattern concentrates procurement decision-making in Lagos-based technical teams rather than regional trading houses.
Nigeria Container Glass Market Segmentation
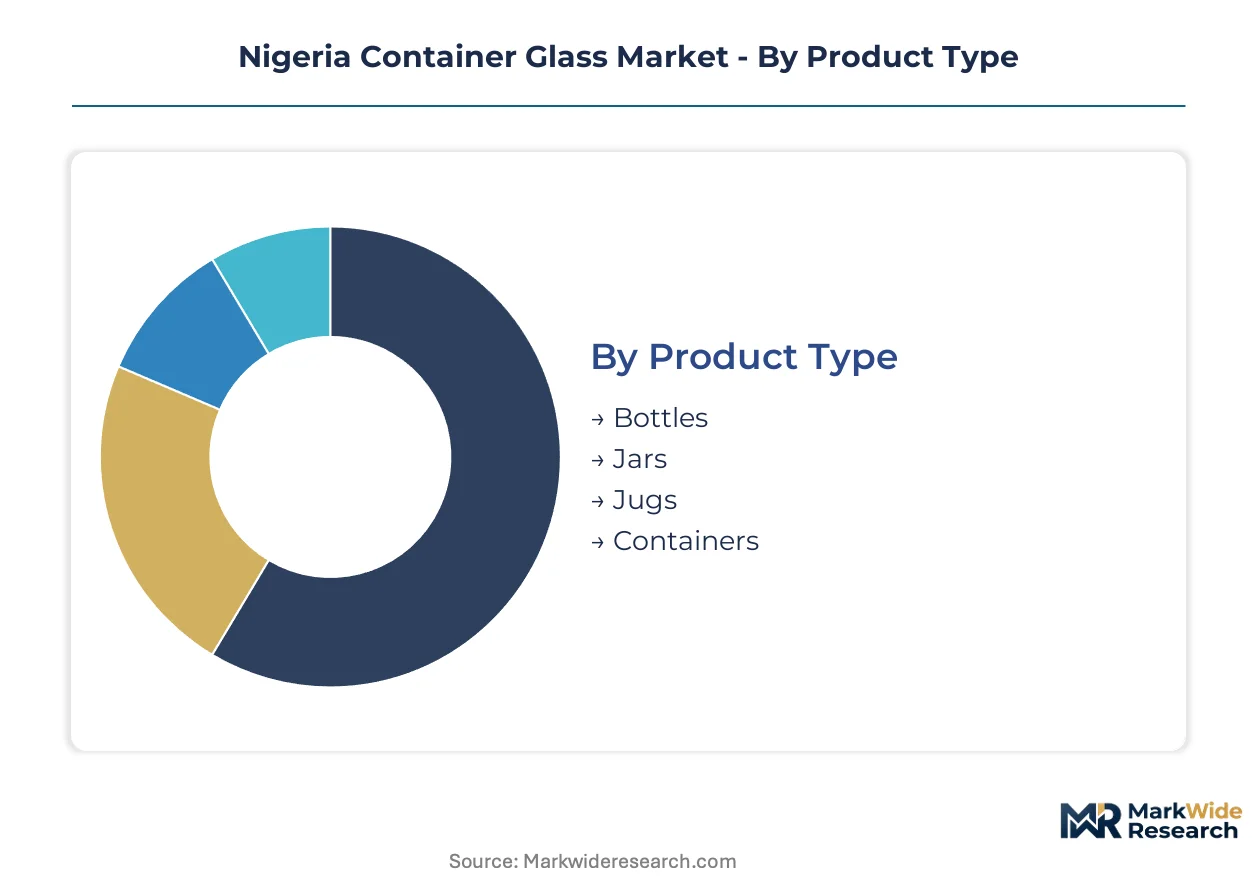
Nigeria's container glass market segments reflect divergent technical requirements across beverage, pharmaceutical, and cosmetic value chains. Procurement patterns vary sharply by end-use compliance burden and furnace batch economics.
Product Type:
Standalone formats dominate volume, while embedded-system designs serve specialized containment needs.
- Bottles:Soda-lime-silica formulations in amber and flint grades withstand internal pressures exceeding 150 psi. Nigerian breweries in Lagos and Ogun State specify heat-tempered returnable designs to survive 50+ wash cycles under NESREA plastic displacement rules.
- Jars:Wide-mouth press-and-blow configurations accommodate viscous food products and cosmetic creams. Food processors in Kano prioritize hermetic sealing performance for tomato paste and spice packaging.
- Jugs:Reinforced shoulder designs support edible oil and chemical transport. Capacity concentrates in 5-liter formats for institutional catering buyers.
- Containers:Rectangular press-molded formats optimize pallet density for pharmaceutical bulk APIs. NAFDAC serialization mandates drive demand for laser-etchable surface finishes.
Volume placements concentrate in Bottles; the faster expansion belongs to Containers.
End User:
Cost tiers separate commodity beverage buyers from premium cosmetic and compliance-heavy pharmaceutical accounts.
- Food & Beverage:Absorbs majority domestic tonnage through returnable beer and soft-drink formats. Nigerian bottlers negotiate multi-year offtake agreements tied to furnace capacity reservations.
- Pharmaceuticals:Borosilicate vials and ampoules command 3-5x per-unit margins versus commodity bottles. NAFDAC pharmacopeial compliance requirements eliminate polymer alternatives for injectable and oncology lines.
- Cosmetics:Decorative finishing and custom cobalt or amber molds generate highest margins per kilogram. Lagos and Abuja skincare brands commission limited-edition surface treatments for shelf differentiation.
- Household Products:Standard flint containers for cleaning chemicals and solvents. Price sensitivity limits specification upgrades despite available technical capabilities.
Food & Beverage anchors absolute volume; Pharmaceuticals climbs the fastest on compliance-driven substitution.
Application:
Functional roles determine surface treatment, dimensional tolerance, and traceability requirements.
- Packaging:Primary containment with direct product contact demands chemical inertness and thermal shock resistance. NAFDAC serialization mandates push pharmaceutical buyers toward machine-readable glass surfaces.
- Storage:Secondary containment for warehouse and retail shelf stability emphasizes stack strength and UV protection. Amber grades dominate light-sensitive pharmaceutical and cosmetic inventory.
- Transport:Bulk logistics formats prioritize pallet efficiency and strap compatibility. Heat-tempering treatments prevent breakage under vibration and impact loads.
- Display:Cosmetic and premium beverage applications balance transparency with decorative embossing. Custom mold investments amortize across shorter production runs.
Packaging captures the largest installed base; Display gains share fastest on premium cosmetic expansion.
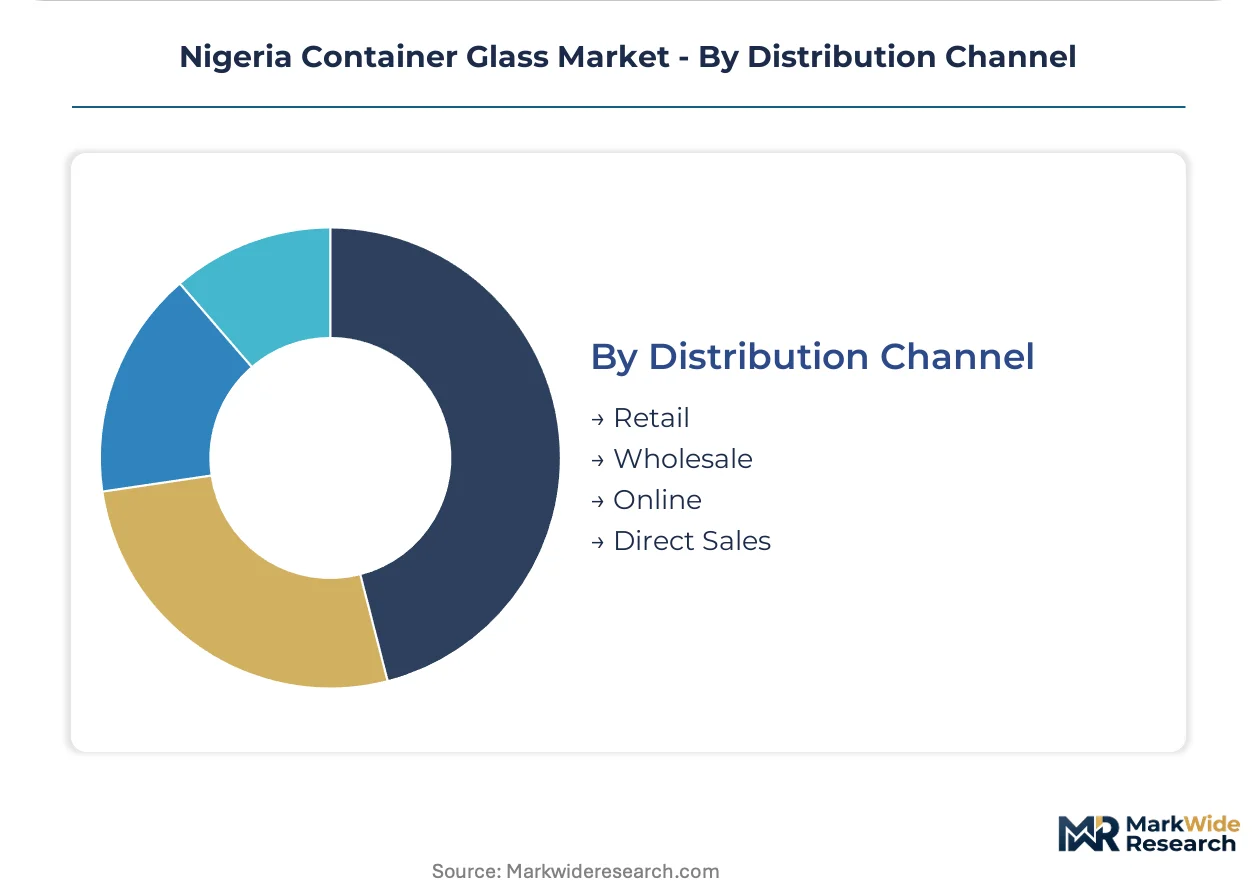
Distribution Channel:
Customer type and order scale determine channel selection and pricing architecture.
- Retail:Small-lot procurement by artisanal food producers and independent pharmacies. Higher per-unit costs reflect broken pallet premiums and logistics fragmentation.
- Wholesale:Regional distributors aggregate demand from secondary beverage bottlers. Inventory pooling reduces working capital requirements for mid-tier buyers.
- Online:Emerging channel for standardized jar and container formats. Limited penetration due to breakage risk in last-mile delivery.
- Direct Sales:Major brewers and pharmaceutical manufacturers negotiate furnace-dedicated production slots. Technical teams at Lagos headquarters manage multi-year supply agreements.
Direct Sales commands the highest volume commitment; Online shows steepest expansion trajectory on logistics platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos and its surrounding southwestern industrial corridors concentrate Nigeria's container glass melting capacity within 150 kilometers of the country's largest beverage production bases.
Southwest Nigeria
Ogun State glassworks supply amber and flint bottles to Lagos-based breweries under multi-year offtake agreements. NAFDAC pharmacopeial standards drive pharmaceutical manufacturers toward traceable glass primary containers. The Sagamu-Ikorodu industrial belt hosts dedicated borosilicate vial lines serving injectable drug producers.
North-Central Nigeria
Kaduna and Kano pharmaceutical manufacturing zones remain underserved by specialized glass suppliers despite rising oncology drug production. The country's national pharmaceutical regulator enforces serialization mandates that eliminate polymer alternatives for parenteral lines. Abuja skincare brands commission custom-molded cobalt glass from southwestern fabricators.
Southeast Nigeria
Anambra and Enugu food processors demand wide-mouth jars for tomato paste and spice packaging under hermetic sealing specifications. Standards Organisation of Nigeria certifies dimensional tolerances for commercial glassware used in regional agro-processing clusters. Onitsha trading hubs aggregate small-lot procurement from independent bottlers.
South-South Nigeria
Port Harcourt and Warri petrochemical corridors generate institutional demand for reinforced jugs in 5-liter formats. The National Environmental Standards and Regulations Enforcement Agency plastic reduction mandates force edible oil repackagers toward returnable glass. Local distributors pool inventory for mid-tier buyers across the Niger Delta.
Nigeria Container Glass Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive cullet recycling networks. Three domestic melting operations control the majority of furnace capacity, while regional distributors fragment downstream channels. Strategic archetypes separate backward-integrated bottle producers from premium pharmaceutical vial specialists and heat-tempered returnable designers. Capacity reservation agreements and dedicated production slots constitute the dominant competitive moves as major brewers lock in supply security.
Among Nigeria-based fabricators, Beta Glass Nigeria Plc and Ardagh Glass Packaging Nigeria Limited exemplify the integrated-production archetype, while Frigoglass Industries (Nigeria) Limited occupies a position within the returnable-bottle specialization tier. These three entities anchor the supplier base as pharmaceutical serialization requirements and beverage plastic displacement mandates restructure procurement patterns across southwestern manufacturing corridors.
| Leading Market Players |
|---|
| Technoglass Industries Limited |
| Nampak Glass |
| Frigoglass Industries (Nigeria) Limited |
| Avon Crowncaps & Containers Nigeria Limited |
| Greif |
| Ardagh Glass Packaging Nigeria Limited |
| The Chagoury Group |
| Twinstar Industries Limited |
| Beta Glass Nigeria Plc |
| Others |
Pricing and Supply Chain Analysis
Refractory specialist shortages across southwestern Nigerian industrial corridors widen labor-cost differentials between furnace engineering tiers, compressing margin structures for technical-grade output while premium pharmaceutical vial production commands sustained pricing power through NAFDAC compliance premiums.
Pricing Analysis
Value-based pricing anchored to furnace throughput guarantees dominates procurement negotiations between Lagos-based brewers and glassworks operators. Three-tier pricing structure across premium pharmaceutical-grade, standard beverage-grade, and economy household-grade levels separates borosilicate vial output from commodity amber bottles. Cost compression in standard beverage grades is intensifying because NESREA-mandated returnable bottle investments raise capital recovery requirements. Food and beverage bottlers exhibit highest price sensitivity due to PET substitution threats, while pharmaceutical manufacturers accept premium positioning to secure NAFDAC serialization compliance.
Supply Chain Analysis
Regional distribution centers in Sagamu and Ikorodu operate hub-and-spoke patterns radiating toward Kano and Port Harcourt secondary markets. Manufacturing capacity draws from Nigerian melting operations, European borosilicate specialist imports, and Asian equipment fabricators. Raw material dependencies center on processed silica sand, soda ash, and imported cullet through Lagos port channels. Single-source vulnerability concentrates in natural gas supply from Nigerian LNG terminals. Distribution runs through direct sales agreements for major beverage accounts and wholesale aggregators for mid-tier pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace capacity scarcity across Nigerian glassworks props pricing power for incumbent operators, with new melting installations requiring 24-36 month commissioning timelines that constrain supply elasticity.
For Market Incumbents: Deploy captive cullet collection networks to defend margin position against imported raw material cost volatility. Secure multi-year offtake agreements with Lagos-based pharmaceutical manufacturers ahead of NAFDAC serialization enforcement deadlines. Backward integration into silica sand beneficiation reduces exposure to Lagos port congestion. For New Entrants and Emerging Players: Capture underserved borosilicate vial demand in Kano and Kaduna pharmaceutical manufacturing zones where oncology drug production expansion outpaces local glass supply. Target cosmetics decorative finishing contracts from Abuja skincare brands seeking cobalt and amber custom molds. Partner with southwestern equipment distributors for furnace technology transfer rather than greenfield engineering. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists given NESREA extended producer responsibility rules rewarding documented recycling recovery rates. Long-term viability favors operators with captive cullet networks and NAFDAC pre-certified production lines. Watch natural gas supply stabilization at Nigerian LNG terminals as inflection indicator for furnace operating cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Recycling | NESREA recovery-rate documentation requirements reward manufacturers with captive collection networks. |
| NAFDAC Pre-Certification Investment | Pharmaceutical packaging approvals stretching 18-24 months freeze supplier switches until verification completes. |
| Multi-Year Offtake Agreements | Lagos-based brewers negotiate furnace-dedicated production slots securing supply against capacity constraints. |
| Electromagnetic Furnace Retrofitting | Energy intensity reduction per ton of melted soda-lime-silica compresses production economics for smaller batches. |
| Northern Nigeria Distribution Expansion | Kano and Kaduna pharmaceutical zones remain underserved by specialized borosilicate vial suppliers. |
Research Methodology
Independent corroboration across plant managers at Nigerian glassworks, procurement leads at Lagos-based beverage bottlers, pharmaceutical regulatory affairs specialists, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from NAFDAC pharmacopeial guidance documents, Standards Organisation of Nigeria certification records, NESREA environmental compliance filings, and customs trade data on cullet and finished glass imports. Bottom-up furnace capacity assessments and top-down end-use demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth into packaging format substitution, regulatory compliance upgrades, and regional manufacturing expansion across the analysis window. Segmentation dimensions modeled include product type, end-user industry, application function, and distribution channel structure. CAGRs derive from regression analysis against macroeconomic indicators and industry-specific inputs including natural gas supply stability and NAFDAC enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to energy cost volatility, import tariff adjustments on raw materials, and polymer substitution resilience in price-sensitive categories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Peru Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom Container Glass Market