
 Container Glass Coatings Market | 2026-2036
Container Glass Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Container Glass Coatings Market Outlook
Food-grade durability specifications is collapsing the gap between commodity glass and performance-coated alternatives. Axalta Coating Systems leverages its automotive-derived resin expertise to anchor high-barrier food packaging contracts. PPG Industries competes through specialized UV-curable formulations that dominate North American pharmaceutical bottle lines. AkzoNobel differentiates via waterborne coating platforms that sustain compliance with tightening volatile organic compound limits.
Container glass coatings comprise thin functional layers applied to glass substrates through sol-gel, vacuum deposition, or spray processes, typically measuring 50-500 nanometers, to impart properties such as thermal insulation, abrasion resistance, or ultraviolet blocking for extended product shelf life. Anti-fog and heat reflective product types lead current volume, while scratch resistant formulations capture expanding margin pools in premium cosmetics jars. Sol-gel technology dominates pharmaceutical bottle applications due to its ambient curing and precise thickness control, whereas vacuum coating occupies the fastest-growing position in high-end beverage containers requiring optical clarity.
FDA food contact substance notifications govern coating chemistry approvals for US food packaging applications, while REACH and the EU Green Deal restrict hazardous substance content and mandate circularity disclosures for European cosmetic and pharmaceutical containers. China's GB standards and NMPA pharmaceutical packaging rules impose additional migration testing protocols that shape export-oriented manufacturer formulations. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in regional formulation certification or consolidate production in jurisdictions with mutual recognition agreements.
Market Dynamics
The EU Green Deal's circularity mandates are compressing formulation timelines as converters race to certify low-VOC sol-gel coatings before 2030 disclosure deadlines. REACH compliance costs are selectively advantaging waterborne platforms over legacy solvent systems.
Growth Catalysts
- REACH chemical restrictions:Hazardous substance limits are forcing beverage packagers in Germany toward compliant barrier coatings for premium carbonated lines.
- Sol-gel ambient curing:Pharmaceutical bottle manufacturers favor this process for precise thickness control without thermal stress on sensitive substrates.
- Cologne-Hamburg innovation cluster:German beverage packaging R&D concentration accelerates coated glass adoption for still water premiumization.
Market Restraints
- Silica precursor cost volatility:Tetraethyl orthosilicate price swings compress margin pools for sol-gel coaters locked into annual supply contracts.
- Optical-grade vacuum equipment concentration:German and Japanese deposition system suppliers create procurement bottlenecks for high-clarity beverage container lines.
- Uncoated glass substitution:Lightweighting advances in commodity borosilicate threaten coated alternatives in mid-tier cosmetics packaging.
Strategic Opportunities
- India pharmaceutical exports:CDSCO packaging rule harmonization with EU standards creates certified-coating demand for export-oriented injectable vial producers.
- UV-curable food contact:FDA notification pathways for acrylate-based barriers open shelf-life extension applications in North American condiment segments.
- Digital printing convergence:Direct-to-glass decoration systems require compatible scratch-resistant base coats, creating bundled specification opportunities.
Industry Challenges
- Sol-gel formulation chemist scarcity:Cross-disciplinary expertise spanning colloid science and food contact compliance commands premium compensation in European coating houses.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and NMPA migration testing extends product launch cycles by 18-24 months for global pharmaceutical accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Glass Coatings Market |
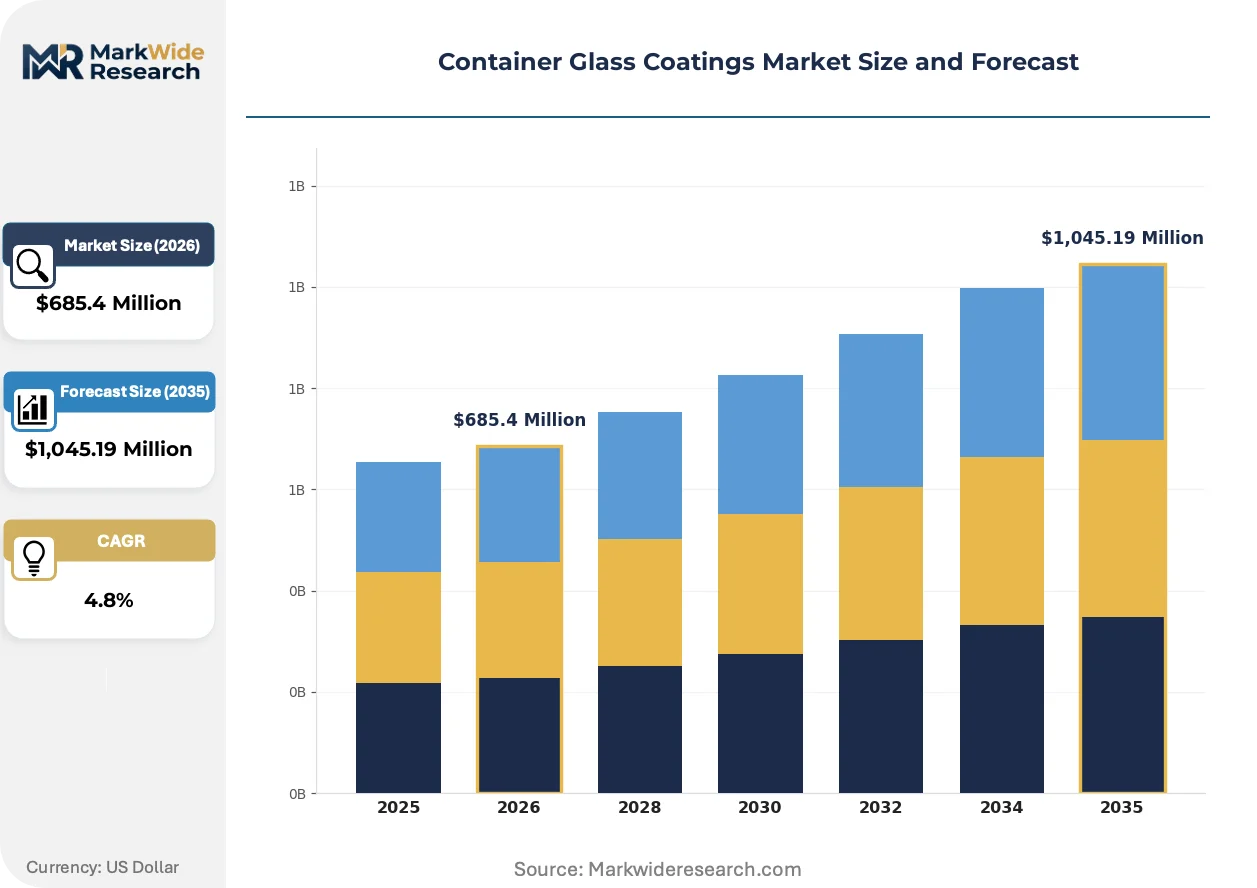
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Fog, UV Resistant, Heat Reflective, Scratch Resistant Application: Food Packaging, Beverage Containers, Pharmaceutical Bottles, Cosmetics Jars End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Cosmetic Brands Technology: Coating Process, Sol-Gel, Vacuum Coating, Spray Coating |
| Companies Covered | Axalta Coating Systems, Jotun, PPG Industries, DuPont, Nippon Paint, AkzoNobel, BASF, 3M, Sherwin-Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Glass Coatings Market Strategic Shifts
Coating functionality is migrating from passive protection to active performance enhancement as beverage and pharmaceutical packagers demand measurable shelf-life extension. Formulation chemistry, regulatory disclosure frameworks, and procurement specifications are evolving in lockstep.
Waterborne polyurethane-silica hybrids are supplanting traditional solvent-borne epoxies in North American pharmaceutical bottle applications. Major contract manufacturers specify these systems to preempt FDA food contact substance review delays. The shift compresses incumbent resin suppliers lacking aqueous platform expertise.
EU Green Deal circularity disclosure rules now mandate coating mass-balance accounting for cosmetic containers entering European distribution. ECHA guidance on article definition forces brand owners to document coating composition through supply chain tiers. Premium skincare jar producers in France and Italy are responding by consolidating supplier panels to auditable single-source coating partnerships.
Buyers are unbundling coating specification from primary glass supply contracts, creating direct procurement relationships with specialized coaters. Large beverage groups now issue separate RFQs for base glass and functional barrier layers, inserting quality audits between previously integrated supply steps. This pattern concentrates in German and Benelux markets where packaging procurement functions have centralized at regional headquarters.
Container Glass Coatings Market Segmentation
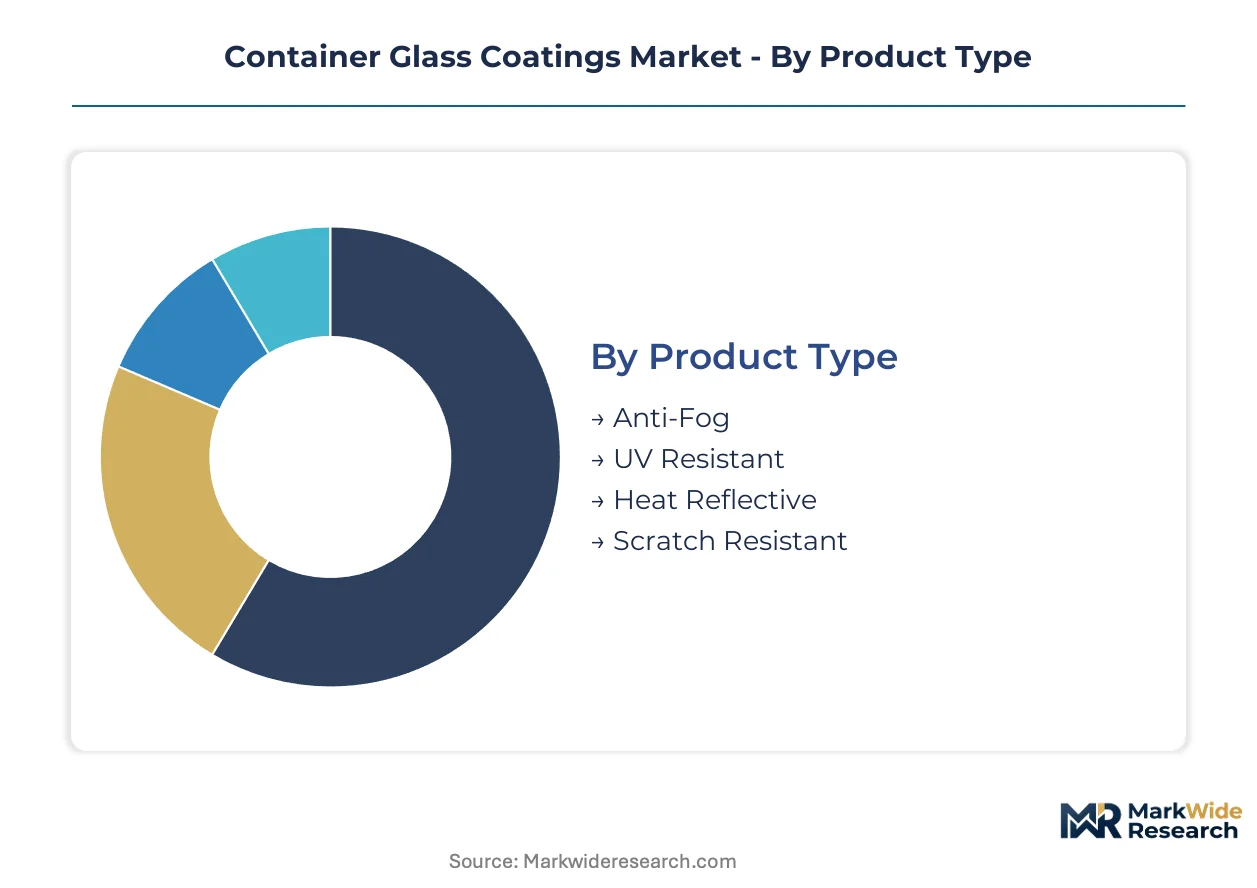
Coating specification unbundling from primary glass supply creates direct procurement relationships between end users and specialized coaters. Segmentation clarity enables buyers to match functional requirements with certified formulation platforms across regulatory jurisdictions.
Product Type:
Premium margin pools concentrate in performance layers that extend measurable shelf life or enable optical differentiation in crowded retail environments.
- Anti-Fog:Hydrophilic surface treatments prevent condensation on chilled beverage containers and refrigerated food jars. German beverage packagers specify these coatings for premium carbonated water lines displayed in open refrigeration cases.
- Scratch Resistant:Silica-doped polyurethane hardcoats protect cosmetic jars through repeated handling and transportation cycles. French and Italian skincare brands mandate these specifications for premium glass packaging destined for duty-free retail channels.
- UV Resistant:Organic UV absorbers integrated into sol-gel matrices block degradation wavelengths for light-sensitive pharmaceutical formulations.
- Heat Reflective:Metal oxide interference layers reduce thermal transfer in hot-fill food applications and microwaveable containers.
The dominant share belongs to Anti-Fog, while Scratch Resistant is closing the gap fastest.
Application:
Volume distribution tracks end-use regulatory stringency, with pharmaceutical and food contact applications commanding formulation premiums over cosmetic counterparts.
- Pharmaceutical Bottles:Sol-gel barrier coatings satisfy FDA food contact substance notifications and EMA migration limits for injectable and oral dosage packaging. Precise thickness control prevents thermal stress on borosilicate vials during ambient curing.
- Beverage Containers:Vacuum-deposited optical clarity layers serve premium carbonated and still water lines. Cologne-Hamburg innovation clusters drive coated glass adoption for German beverage premiumization strategies.
- Food Packaging:Heat-resistant formulations withstand hot-fill processing for sauces and condiments in North American retail distribution.
- Cosmetics Jars:Scratch-resistant base coats enable direct-to-glass digital decoration systems for limited-edition skincare launches.
Pharmaceutical Bottles command the highest specification premiums, though Beverage Containers are expanding most quickly.
End User:
Procurement centralization at beverage group regional headquarters in Germany and Benelux is compressing supplier panels and elevating quality audit frequency.
- Beverage Companies:Separated RFQs for base glass and functional barrier layers now dominate German and Benelux markets. Quality audits insert between previously integrated supply steps, favoring coaters with standalone certification capabilities.
- Pharmaceutical Firms:Parallel FDA, EFSA, and NMPA migration testing extends product launch cycles. Formulation lock-in with certified suppliers reduces regulatory risk for global injectable vial accounts.
- Food Manufacturers:Waterborne polyurethane-silica hybrids preempt FDA review delays for North American condiment shelf-life extension applications.
- Cosmetic Brands:EU Green Deal mass-balance accounting mandates drive consolidation to auditable single-source coating partnerships for French and Italian skincare jar producers.
Beverage Companies generate the largest absolute demand, while Pharmaceutical Firms are deepening supplier integration fastest.
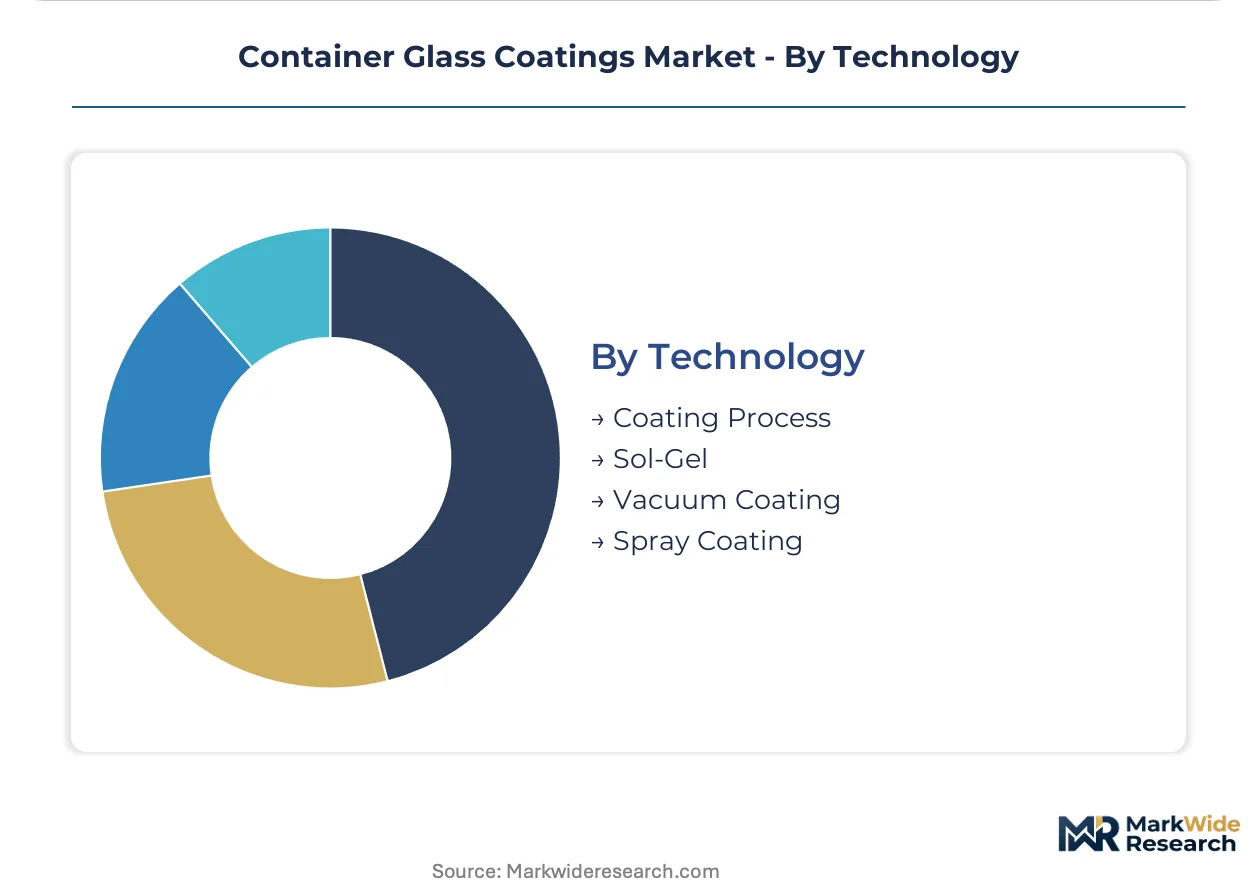
Technology:
Equipment concentration in German and Japanese deposition system suppliers creates procurement bottlenecks for optical-grade beverage container lines.
- Sol-Gel:Ambient curing and precise thickness control suit temperature-sensitive pharmaceutical substrates. Tetraethyl orthosilicate precursor cost volatility compresses margins for coaters locked into annual supply contracts.
- Vacuum Coating:Physical vapor deposition delivers optical clarity for high-end beverage containers requiring premium shelf presentation. Japanese and German equipment suppliers constrain expansion timelines for new market entrants.
- Spray Coating:Conventional atomized application serves commodity cosmetics and food packaging with lower clarity requirements.
- Coating Process:Umbrella category encompassing dip-coating and flow-coating methods for uniform coverage on complex jar geometries.
Sol-Gel retains the largest installed base, though Vacuum Coating is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese equipment suppliers dominate optical-grade vacuum deposition systems, creating procurement bottlenecks for high-clarity beverage container lines. REACH compliance costs and EU Green Deal circularity mandates compress formulation timelines across European coating houses. Tetraethyl orthosilicate precursor volatility constrains margin pools for sol-gel coaters locked into annual supply contracts.
United States
FDA food contact substance notifications govern coating chemistry approvals for pharmaceutical and food packaging applications. Waterborne polyurethane-silica hybrids preempt review delays as contract manufacturers specify aqueous platforms. North American condiment segments drive UV-curable barrier adoption for shelf-life extension in retail distribution.
Germany
REACH hazardous substance limits force beverage packagers toward compliant barrier coatings for premium carbonated lines. ECHA guidance on article definition compels mass-balance accounting through supply chain tiers. Cologne-Hamburg innovation clusters accelerate coated glass adoption for still water premiumization strategies.
China
GB standards and NMPA pharmaceutical packaging rules impose migration testing protocols shaping export-oriented manufacturer formulations. Dual carbon goals pressure converters toward low-emission coating processes. Yangtze River Delta coating houses invest in sol-gel capacity to serve injectable vial export markets.
India
CDSCO packaging rule harmonization with EU standards creates certified-coating demand for export-oriented injectable vial producers. FSSAI food contact regulations extend compliance requirements to domestic condiment and beverage segments. Maharashtra and Gujarat pharmaceutical clusters drive barrier coating specification for international contract manufacturing.
France
EU Green Deal mass-balance disclosure mandates drive consolidation to auditable single-source coating partnerships for skincare jar producers. ANSM pharmaceutical packaging guidance aligns with EMA migration limits for premium cosmetic containers. Paris and Lyon regional headquarters centralize procurement functions for multinational cosmetic brands.
Container Glass Coatings Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized coating houses serving distinct regulatory jurisdictions. The vendor base spans three tiers: automotive-derived resin specialists, waterborne platform innovators, and vacuum deposition equipment-integrated coaters. Strategic moves center on formulation certification lock-in with global pharmaceutical accounts and geographic expansion through regional compliance partnerships.
Among diversified chemical conglomerates, Axalta Coating Systems and PPG Industries exemplify contrasting archetypes. Axalta represents automotive resin expertise translated into high-barrier food packaging contracts. PPG occupies a position in specialized UV-curable formulations for North American pharmaceutical bottle lines. AkzoNobel anchors the waterborne platform tier, sustaining compliance with tightening volatile organic compound limits across European cosmetic and pharmaceutical containers.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Jotun |
| PPG Industries |
| DuPont |
| Nippon Paint |
| AkzoNobel |
| BASF |
| 3M |
| Sherwin-Williams |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese vacuum deposition equipment suppliers shapes price floors across optical-grade beverage container lines, compressing margin pools for coaters locked into annual tetraethyl orthosilicate supply contracts while elevating premiums for sol-gel formulation chemists with cross-disciplinary expertise.
Pricing Analysis
REACH hazardous substance limits dictate the pricing tier structure across European container glass coating markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pharmaceutical barrier coatings from REACH-compliant cosmetic formulations and commodity food-contact spray applications. Cost compression in standard-tier sol-gel formulations is intensifying because tetraethyl orthosilicate precursor volatility feeds through annual supply contracts. Beverage companies in Germany and Benelux exhibit the lowest price sensitivity due to procurement centralization, while commodity cosmetics packagers in Southern Europe face acute margin pressure from uncoated glass lightweighting substitutes.
Supply Chain Analysis
Baltic Sea port congestion and Rhine water level variability periodically choke tetraethyl orthosilicate feedstock deliveries to Cologne-Hamburg coating clusters. Manufacturing concentration centers on Germany, Japan, and China, with Yangtze River Delta sol-gel capacity expanding fastest for pharmaceutical export markets. Raw material dependencies rest on silica precursors from petrochemical crackers, metal oxide sputtering targets from specialty refiners, and UV-curable acrylate resins from polymer producers. Single-source vulnerability pervades German and Japanese vacuum deposition equipment supply. Distribution runs through integrated glass-coater partnerships and direct procurement relationships with beverage group regional headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists commanding simultaneous expertise in colloid science and multi-jurisdiction food contact compliance represent the scarcest capability layer, constraining expansion timelines for coating houses pursuing global pharmaceutical accounts.
For Market Incumbents: Compound certification lock-in with global injectable vial manufacturers by accelerating parallel FDA-EMA-NMPA migration testing capabilities before disclosure deadlines tighten. Defend margin position through backward integration into tetraethyl orthosilicate precursor supply, neutralizing cost volatility that threatens sol-gel coaters on annual contracts. Capacity expansion in Yangtze River Delta coating houses addresses Chinese pharmaceutical export demand while circumventing European energy cost premiums. For New Entrants and Emerging Players: Regulatory compliance services for EU Green Deal mass-balance accounting represent an under-served layer where incumbent coaters lack dedicated advisory capacity. Target Indian pharmaceutical export clusters in Maharashtra and Gujarat where CDSCO-EU harmonization creates certified-coating demand without entrenched supplier relationships. Pursue white-space in UV-curable food contact barriers for North American condiment segments through direct relationships with contract manufacturers seeking FDA notification pathway acceleration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating houses with standalone certification capabilities and direct procurement relationships with beverage group regional headquarters. Long-term viability over the next decade hinges on aqueous platform expertise as REACH compliance costs displace legacy solvent systems. Acquisition targets should demonstrate established ECHA guidance compliance infrastructure and auditable single-source partnerships with French or Italian skincare brands. Monitor FDA food contact substance notification backlogs as an inflection indicator for contract manufacturer specification shifts toward pre-cleared aqueous formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursor Supply | Tetraethyl orthosilicate cost volatility compression secures sol-gel margin pools for European coaters. |
| Parallel Multi-Jurisdiction Certification Investment | Simultaneous FDA-EMA-NMPA migration testing reduces pharmaceutical account launch cycles by 18-24 months. |
| Waterborne Platform R&D Expansion | Polyurethane-silica hybrid development preempts REACH compliance cost escalation across cosmetic containers. |
| Regional Compliance Partnership Formation | CDSCO-certified coating capacity in Maharashtra addresses Indian pharmaceutical export growth without EU energy premiums. |
| Digital Printing Compatibility Development | Scratch-resistant base coat formulations capture bundled specification opportunities with direct-to-glass decoration systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA food contact substance notifications, ECHA REACH registration databases, SEC 10-K filings from diversified chemical conglomerates, and trade flow data from European and Asian customs authorities. Primary interviews engaged coating formulation chemists, pharmaceutical packaging procurement managers at global injectable vial manufacturers, beverage group regional headquarters sourcing directors, and vacuum deposition equipment suppliers in Germany and Japan. Bottom-up volume modeling from installed coating line capacity and top-down value triangulation from disclosed segment revenues were cross-validated.
Segmentation dimensions modeled encompass coating technology platform, end-use application regulatory stringency, product type functional performance, and geographic regulatory cluster across the analysis window. CAGRs were derived from regression analysis of historical volume trends against disclosed capacity expansion announcements and regulatory timeline milestones. Forecast inputs incorporated EU Green Deal circularity disclosure deadline impacts on formulation substitution rates and tetraethyl orthosilicate precursor contract pricing volatility assumptions.
Forecasts assume regulatory continuity in FDA food contact substance review pathways, REACH hazardous substance restriction trajectories, and NMPA pharmaceutical packaging rule harmonization with EU standards; material policy shifts would require re-modeling. Specific risk factors include unilateral tariff imposition on Chinese coating equipment, accelerated EU Green Deal mass-balance accounting enforcement, and breakthrough lightweighting in uncoated borosilicate glass. Practitioners should keep alternative scenarios live as CDSCO packaging rule implementation and FDA notification backlog durations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Spain Packaging Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Portugal Container Glass Market