
 Stationary Air Compressor Market | 2026-2036
Stationary Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Air Compressor Market Analysis
A widening capability gap between integrated manufacturers and component assemblers is reorganizing competitive tiers in the stationary air compressor space. Atlas Copco AB leverages captive production of airends and precision rotors to sustain margin structures that smaller rivals cannot match. Kaeser Compressors anchors its position through dense German service networks and long-term lifecycle contracts. Ingersoll Rand competes by extending a broad rotary and centrifugal portfolio across North American energy and chemical installations.
A stationary air compressor is a fixed-installation machine that converts mechanical power into pressurized air, typically achieving discharge pressures from 100 to 175 psi through positive-displacement or dynamic compression principles, and serves as the central pneumatic utility in factories, refineries, and processing plants. Screw compressors dominate installed base value due to continuous-duty reliability and superior energy efficiency at medium-to-large duty cycles, while piston compressors retain relevance in intermittent, small-scale shop environments where capital constraints outweigh operating cost concerns. The manufacturing end-user segment concentrates demand for large-capacity oil-free systems where contamination risks invalidate lubricated alternatives, and automotive painting lines represent a high-specification sub-pocket where scroll and diaphragm technologies are displacing older reciprocating units.
EPA energy conservation standards and DOE test procedures shape product design by mandating minimum full-load and part-load efficiency metrics, while OSHA workplace noise regulations limit maximum decibel thresholds for indoor installations and compress enclosure engineering costs. ISO 8573 air purity classes govern oil-free compressor certification requirements in food, pharmaceutical, and electronics applications, creating a compliance barrier that filters out uncertified suppliers. Stakeholders must monitor how tightening efficiency thresholds and carbon accounting rules reshape capital allocation between retrofit upgrades and full system replacements.
Market Dynamics
Variable-speed drive technology is compressing the installed base toward permanent-magnet synchronous motors and integrated inverter packages, while EPA efficiency mandates accelerate obsolescence of fixed-speed reciprocating systems across North American manufacturing facilities.
Growth Catalysts
- OSHA Noise Regulations:Workplace decibel limits in the United States are forcing enclosure upgrades and low-noise screw compressor installations in indoor fabrication plants.
- Automotive Electrification:Battery gigafactories in Germany's industrial belt require oil-free compressed air for electrode coating lines, pulling demand for Class 0 certified systems.
- Compressed Air as Utility:Food processing clusters in the Netherlands treat pneumatic infrastructure as critical utility, mandating ISO 8573-1 Class 2.4.2 purity for packaging automation.
Market Restraints
- Copper and Rare-Earth Magnet Costs:Permanent-magnet rotor assemblies face input price volatility from concentrated Chinese rare-earth processing.
- Technical Limitation of Scroll Compressors:Limited discharge pressure above 150 psi restricts scroll technology to light-duty applications, excluding heavy manufacturing.
- REACH Substance Restrictions:European chemical regulations on fluorinated lubricants complicate oil-free compressor maintenance protocols and spare parts logistics.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for domestic manufacturing are attracting compressor assembly investments to serve Southeast Asian automotive supply chains.
- Carbon Accounting Integration:EU CSRD disclosure requirements position compressor efficiency data as a procurement differentiator for Scope 3 reporting multinationals.
- Digital Twin Convergence:IoT sensor networks combined with predictive analytics enable remote airend monitoring, opening subscription revenue streams for service providers.
Industry Challenges
- Rotor Grinding Specialist Shortage:Precision machining of screw compressor airends requires skilled technicians with diminishing vocational pipeline supply.
- ISO 8573-1 Certification Timelines:Third-party validation for oil-free compressor claims extends 12-18 months, delaying product launches in pharmaceutical and electronics verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Air Compressor Market |
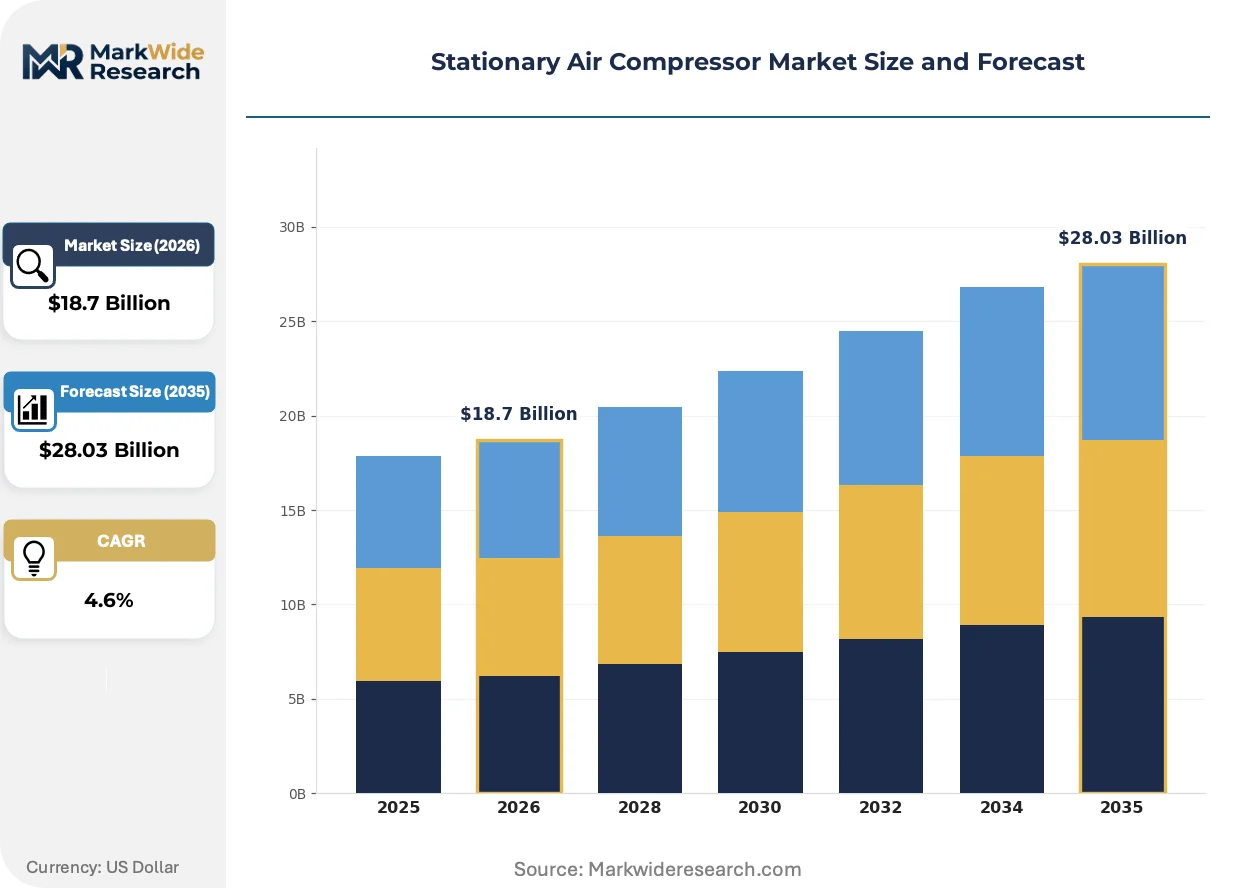
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Compressors, Screw Compressors, Scroll Compressors, Diaphragm Compressors End User: Manufacturing, Automotive, Aerospace, Construction Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Distributors Capacity: Small Capacity, Medium Capacity, Large Capacity, High Capacity |
| Companies Covered | Gardner Denver, Elgi Equipments, Atlas Copco AB, Chicago Pneumatic, Quincy Compressor, Ingersoll Rand, Sullair, Bauer Compressor, Kaeser Compressors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Air Compressor Market Emerging Trajectories
Permanent-magnet synchronous motor technology is mainstreaming across medium-duty screw compressors, while digital service platforms reconfigure aftermarket revenue models away from transactional parts sales toward continuous monitoring contracts.
Magnetic bearing centrifugal compressors are displacing traditional geared turbocompressors in petrochemical and refining applications where oil contamination risks and maintenance downtime costs outweigh premium capital expenditure. Major ethylene producers in the US Gulf Coast and Rotterdam harbor clusters have specified oil-free magnetic bearing units for continuous process air, compressing demand for lubricated centrifugal alternatives in large-scale installations above 500 kW.
EPA energy conservation standards for stationary air compressors tighten minimum full-load and part-load efficiency metrics through 2027, forcing redesign of fixed-speed piston and small rotary units. Manufacturers serving the North American market are consolidating product lines around variable-speed screw platforms and discontinuing non-compliant reciprocating models below 50 horsepower, with compliance costs concentrating on small-shop and intermittent-use segments.
Compressed air service contracts are unbundling from equipment sales, with industrial buyers in Germany and the Netherlands negotiating availability-based agreements that transfer operational risk to OEM service networks. These arrangements replace traditional time-and-materials maintenance with guaranteed uptime commitments, compressing margins for independent distributors while rewarding manufacturers with captive service infrastructure and remote monitoring capabilities.
Stationary Air Compressor Market Segmentation
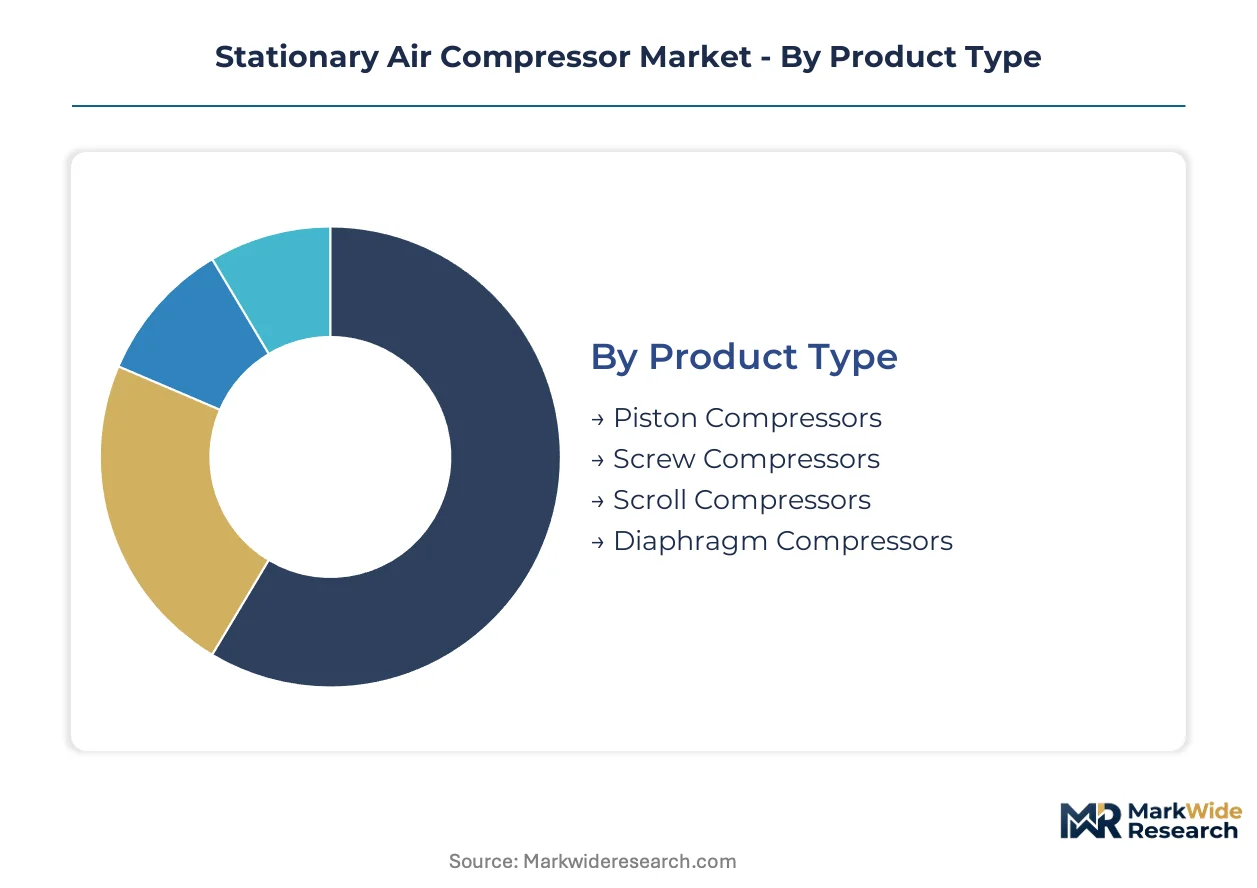
Segmentation in the stationary air compressor market reveals how technology choices, end-use requirements, and procurement channels create distinct competitive battlegrounds. Each dimension carries unique substitution pressures and margin structures that reshape supplier positioning.
Product Type:
Scroll compressors face the most acute substitution threat as magnetic bearing centrifugal technology penetrates light-duty applications below 75 kW.
- Screw Compressors:Positive-displacement machines with intermeshing helical rotors deliver continuous-duty reliability at 100-175 psi discharge pressures. Battery gigafactories in Germany specify oil-free screw banks for electrode coating lines where ISO 8573-1 Class 0 purity eliminates contamination risks.
- Piston Compressors:Reciprocating units with crankshaft-driven pistons achieve intermittent compression cycles at lower capital cost. Small machine shops in the United States retain piston installations where low duty cycles make screw compressor energy savings economically unrecoverable.
- Scroll Compressors:Orbiting spiral mechanisms provide pulsation-free air delivery limited to 150 psi maximum discharge pressure.
- Diaphragm Compressors:Membrane-driven positive-displacement systems achieve ultra-high purity compression for pharmaceutical and laboratory applications.
Screw compressors anchor the volume base while scroll compressors gain share at the steepest rate in food packaging and medical device manufacturing.
End User:
Cost tier stratification separates capital-intensive continuous process industries from intermittent-use fabrication segments with compressed payback horizons.
- Manufacturing:Discrete and process industries consume large-capacity oil-free systems for pneumatic automation, material handling, and precision assembly. EPA efficiency mandates accelerate fixed-speed reciprocating obsolescence across North American fabrication plants.
- Automotive:OEM assembly lines and tier suppliers require Class 0 certified compressed air for painting, welding, and powertrain testing. Electrification shifts battery cell production toward ultra-dry air specifications that exclude lubricated compressor technologies.
- Aerospace:Precision machining and composite curing operations demand stable pressure dew points and minimal oil carryover.
- Construction:Stationary installations support precast concrete production and metal fabrication with intermittent duty cycles favoring lower capital expenditure.
Manufacturing commands the installed base value while automotive expands most quickly on electrification-driven battery factory construction.
Distribution Channel:
Volume concentration in direct procurement reshapes channel economics as lifecycle contracts displace transactional equipment sales.
- Direct Sales:OEM field organizations negotiate availability-based service agreements with guaranteed uptime commitments. German industrial buyers compress independent distributor margins by transferring operational risk to manufacturer service networks.
- Distributors:Regional stocking distributors serve small and mid-cap fabricators with shorter replacement cycles and standard product configurations.
- Online Sales:E-commerce platforms capture replacement parts and accessory procurement for maintenance departments.
- Retail Outlets:Big-box and industrial supply stores address hobbyist and light commercial segments with portable and small stationary units.
Direct sales dominate large-capacity project value while online channels climb fastest in aftermarket parts procurement.
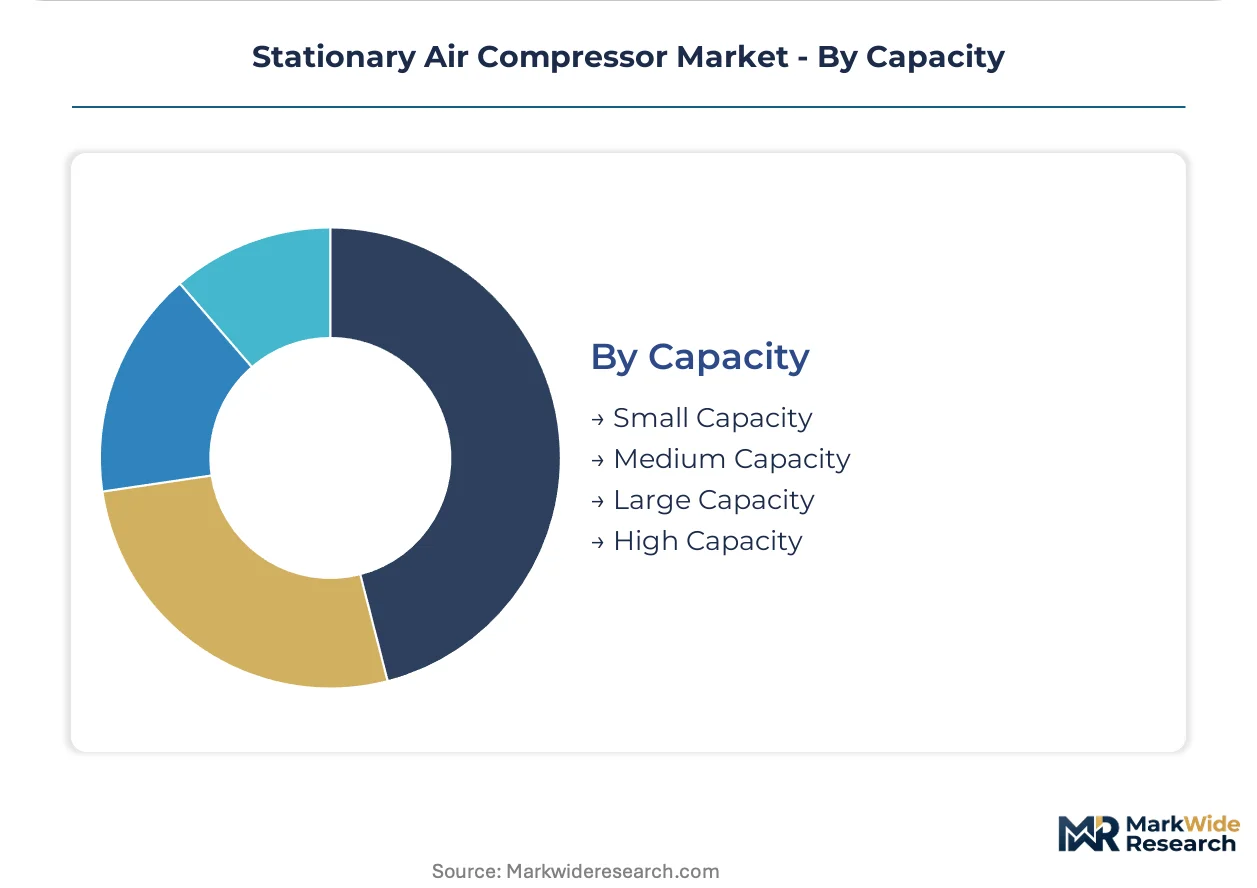
Capacity:
Supply concentration in large-capacity airend manufacturing creates margin pressure on mid-range segments where component sourcing overlaps.
- Large Capacity:Systems above 200 kW serve continuous process industries with redundant compressor banks and centralized dryer arrays. US Gulf Coast ethylene producers specify magnetic bearing centrifugal units above 500 kW to eliminate oil contamination risks.
- Medium Capacity:50-200 kW screw platforms balance efficiency gains against capital constraints in regional manufacturing plants.
- Small Capacity:Units below 50 kW face EPA efficiency mandate consolidation as manufacturers discontinue non-compliant fixed-speed models.
- High Capacity:Specialized turbocompressor installations exceed 1 MW for air separation and steel mill oxygen enrichment.
Large capacity systems anchor revenue concentration while medium capacity segments show the steepest technology transition toward permanent-magnet variable-speed drives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers deploy oil-free compressor banks for battery electrode coating, while US manufacturing plants retrofit for EPA efficiency compliance, and India's PLI scheme attracts assembly investments for Southeast Asian supply chains.
United States
OSHA noise regulations force enclosure upgrades and low-noise screw installations across indoor fabrication plants. EPA energy conservation standards tighten through 2027, mandating minimum part-load efficiency metrics. Gulf Coast ethylene producers specify magnetic bearing centrifugal units above 500 kW to eliminate oil contamination risks in continuous process air applications.
Germany
Automotive electrification pulls demand for Class 0 certified oil-free systems in battery gigafactories. REACH substance restrictions on fluorinated lubricants complicate maintenance protocols for oil-free compressor fleets. The industrial belt around Stuttgart and Munich sees tier suppliers retrofitting assembly lines with centralized compressor banks.
China
Rare-earth magnet cost volatility concentrates permanent-magnet rotor assembly supply chains. MIIT efficiency standards and dual carbon goals accelerate fixed-speed obsolescence in coastal manufacturing zones. Yangtze River Delta electronics clusters mandate ISO 8573-1 Class 2.4.2 purity for semiconductor packaging automation.
India
Production-linked incentive schemes attract compressor assembly investments targeting Southeast Asian automotive supply chains. BIS certification requirements shape product specifications for domestic market entry. Gujarat and Maharashtra industrial corridors expand compressed air infrastructure to support automation upgrades in textile and automotive component plants.
Netherlands
Food processing clusters treat pneumatic infrastructure as critical utility with mandated ISO 8573-1 Class 2.4.2 purity for packaging lines. EU CSRD disclosure requirements position compressor efficiency data as a procurement differentiator for Scope 3 reporting. Rotterdam harbor petrochemical installations specify oil-free magnetic bearing units for continuous process reliability.
Stationary Air Compressor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive airend production separating margin-sustainable OEMs from component assemblers. The upper tier commands lifecycle service contracts and remote monitoring capabilities. Three archetypes dominate: vertically integrated precision manufacturers, dense service-network operators, and broad-portfolio industrial conglomerates. Competitive moves concentrate on M&A for regional service density and technology licensing for permanent-magnet drive integration.
Within the integrated-manufacturer archetype, Atlas Copco AB and Kaeser Compressors exemplify divergent geographic anchoring strategies. Among North American industrial conglomerates, Ingersoll Rand occupies a position spanning rotary and centrifugal portfolio breadth. Elgi Equipments represents the emerging-market assembly specialist tier, with Indian manufacturing origin positioning for PLI-scheme regional supply.
| Leading Market Players |
|---|
| Gardner Denver |
| Elgi Equipments |
| Atlas Copco AB |
| Chicago Pneumatic |
| Quincy Compressor |
| Ingersoll Rand |
| Sullair |
| Bauer Compressor |
| Kaeser Compressors |
| Others |
Supply Flow & Price Mechanics
ISO 8573-1 certification requirements gate both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified oil-free systems command sustained premiums while uncertified alternatives face margin compression from regulatory exclusion.
Pricing Analysis
Long-term availability-based service contracts dominate large-capacity procurement, transferring operational risk from industrial buyers to OEM service networks. Price differentiation hinges on ISO 8573-1 Class 0 certification grade and bundled lifecycle service intensity. Cost compression in small-capacity fixed-speed segments intensifies because EPA efficiency mandates force product line consolidation. Small machine shops exhibit highest price sensitivity, while battery gigafactories prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for permanent-magnet rotor assemblies and precision-ground airends. Manufacturing concentrates in China, Germany, and the United States for screw compressor airends, with rare-earth magnet processing anchored in Chinese supply chains. Raw material dependencies include neodymium-iron-boron magnets, high-grade aluminum castings, and specialized rotor steels. Single-source vulnerability in rare-earth magnet supply creates structural risk. Distribution runs through direct OEM field organizations for large projects and regional distributors for standard configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments demand across battery gigafactories, electrode coating specialists, and tier suppliers, creating service and certification niches that favor focused entrants over generalist incumbents.
For Market Incumbents: Consolidate service network density in Germany's industrial belt and the US Gulf Coast to defend against independent distributors losing availability-based contract share. Deepen backward integration into permanent-magnet rotor production to offset Chinese rare-earth price volatility. Prioritize ISO 8573-1 Class 0 certification breadth across oil-free product lines.
For New Entrants and Emerging Players: Remote airend monitoring and predictive maintenance subscriptions represent a service-layer gap where incumbents under-serve mid-cap fabricators with limited captive digital infrastructure. Target India's PLI-scheme manufacturing corridors with assembly investments serving Southeast Asian automotive supply chains. Pursue carbon accounting integration as a procurement differentiator for EU CSRD-reporting multinationals.
For Investors and Strategic Acquirers: EPA efficiency mandate implementation through 2027 reshapes the acquisition landscape toward variable-speed screw specialists with compliant product platforms. Five-to-ten year viability favors vertically integrated manufacturers with captive airend production and dense regional service infrastructure. Monitor magnetic bearing centrifugal technology adoption rates in ethylene and petrochemical installations as an inflection indicator for oil-free technology displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Airend Manufacturing | Captive rotor grinding capabilities insulate Atlas Copco and Kaeser from specialist technician shortages. |
| ISO 8573-1 Class 0 Certification Expansion | Battery gigafactories in Stuttgart and Munich mandate oil-free purity for electrode coating lines. |
| Digital Twin Service Platform Launch | IoT-enabled predictive maintenance reconfigures aftermarket revenue toward subscription contracts. |
| Permanent-Magnet Motor Technology Licensing | Variable-speed drive integration addresses EPA part-load efficiency mandates for North American facilities. |
| Regional Assembly Investment under PLI Schemes | Gujarat and Maharashtra corridors attract capacity to serve Southeast Asian automotive supply chains. |
Methodological Framework
A spread of perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with compressor fleet operators and technical directors at automotive and petrochemical installations. Secondary validation drew from EPA efficiency standard filings, DOE test procedure documentation, ISO certification registries, and customs trade data for compressor component flows. Bottom-up unit economics and top-down industry revenue estimates were triangulated to anchor segmentation splits.
Segmentation dimensions modeled include product type, end-user industry, capacity tier, and distribution channel across the projection horizon. Screw, piston, scroll, and centrifugal technologies were tracked separately with purity class and drive type as cross-cutting variables. CAGRs were derived from installed base turnover rates and replacement demand elasticities. Forecast inputs incorporated EPA mandate compliance timelines, battery factory construction pipelines, and rare-earth magnet price trajectory assumptions.
Forecasts assume regulatory continuity in EPA efficiency standards and REACH substance restrictions; material policy shifts would require re-modeling. Rare-earth supply disruptions, accelerated electrification timelines, or magnetic bearing technology cost breakthroughs represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
LNG Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Gas Compressors Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Bus Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Oil Filled Air Compressor Market
Compressors
Compressor Rental Market
Compressors
Regenerative Blowers Market
Compressors
North America Hydrogen Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Portable Compressor Market
Compressors
Process Gas Compressors Market