
 Rental Air Compressors Market | 2026-2036
Rental Air Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Rental Air Compressors Market Analytics
Buyer concentration in the North American construction sector is recalibrating as mid-sized contractors shift from ownership to rental models for compressed air assets. Atlas Copco leverages its global service network to dominate premium portable fleet deployments. United Rentals, Inc. sustains the largest rental yard footprint across the United States, capturing volume-driven construction demand. Ingersoll Rand specializes in integrated air solutions that bundle compressors with downstream treatment equipment.
Rental air compressors are mechanical devices that convert power into potential energy stored in pressurized air, typically delivering output from 70 to 250 psi through reciprocating, rotary screw, or centrifugal mechanisms for industrial and commercial applications. The equipment serves construction sites, manufacturing floors, and energy infrastructure where permanent installation proves uneconomical or operationally inflexible. Portable compressors lead equipment mix due to cross-site mobility requirements in construction and oilfield services. Electric compressors represent the fastest-expanding product category as site operators respond to emissions mandates and indoor air quality rules. Direct rental channels capture the dominant margin pool by eliminating intermediary markups and enabling long-term fleet management contracts.
The EPA enforces Tier IV final emissions standards for non-road diesel engines, compelling rental fleets to retire older compressors or absorb costly after-treatment retrofits. The EU F-Gas Regulation and REACH framework restrict refrigerants and lubricants used in compressed air systems, shaping product design and cross-border equipment transfers. OSHA mandates govern workplace noise exposure and compressed air safety protocols, influencing equipment specification at manufacturing and construction sites. Stakeholders must monitor the pace of electrification infrastructure buildout and the evolving compliance cost gap between diesel and electric fleet economics.
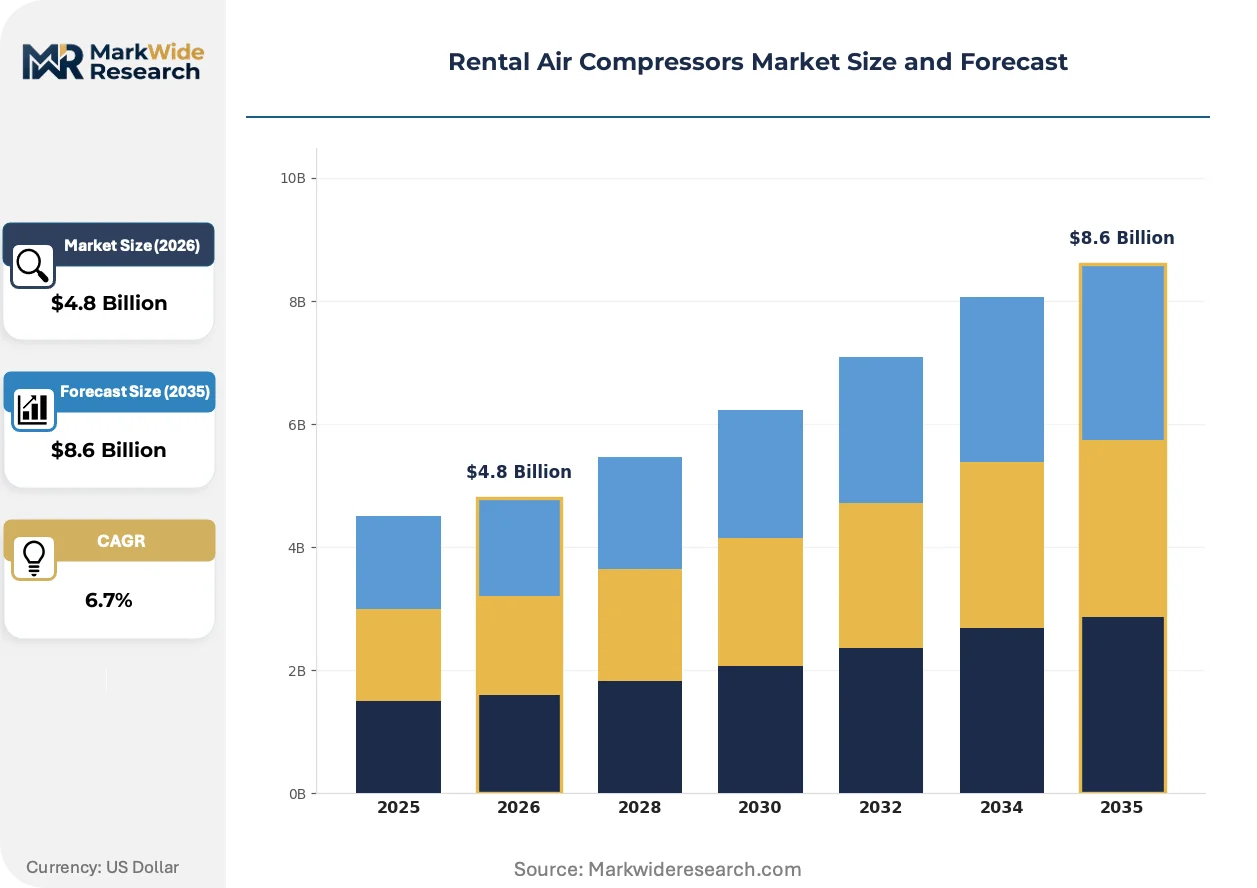
Market Dynamics
Compressed project timelines and emissions mandates are forcing fleet operators to accelerate replacement cycles and reconfigure equipment mix toward portable electric units.
Growth Catalysts
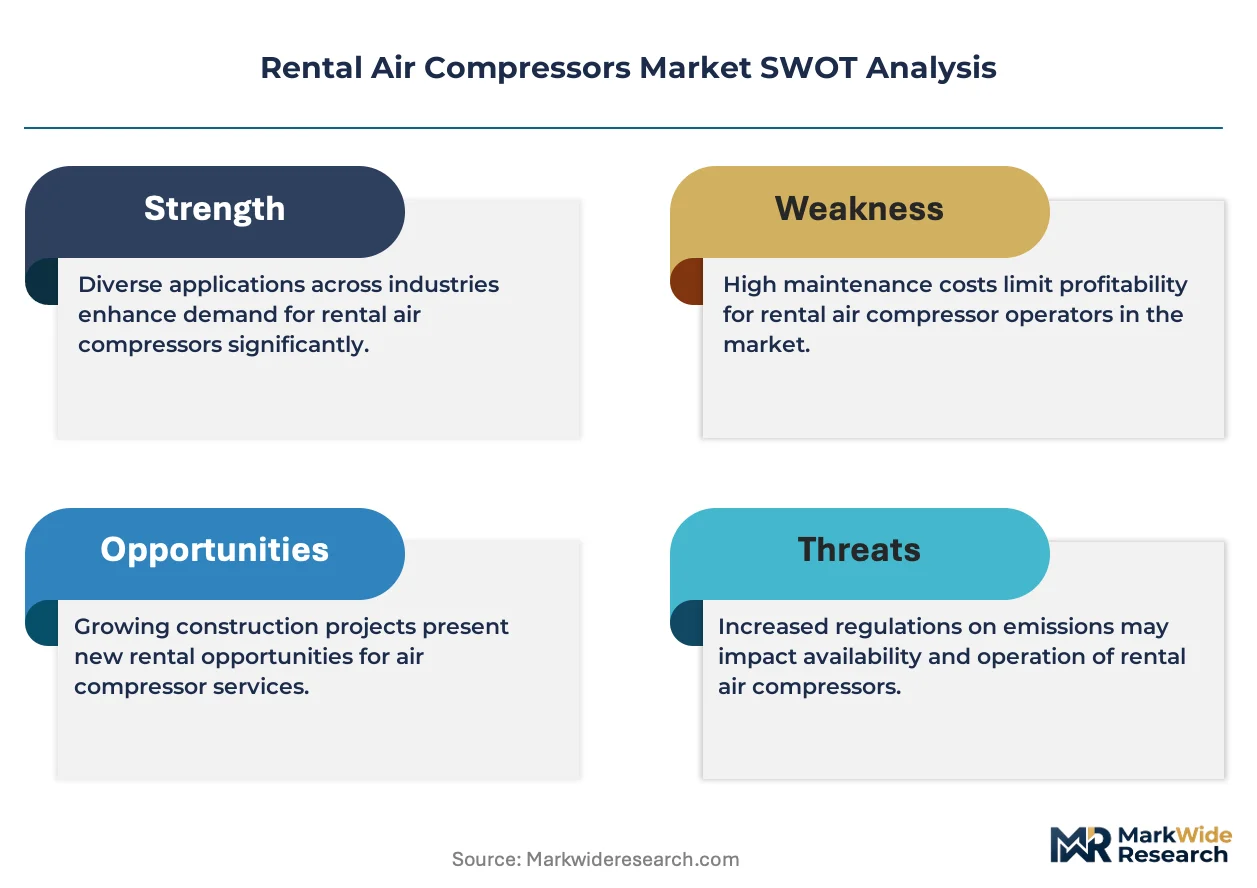
- EPA Tier IV Final Standards:Non-road diesel engine rules compel rental yards to refresh aging portable fleets, creating replacement demand for compliant compressors across construction and energy corridors.
- Modular Construction Methods:Offsite manufacturing facilities require flexible compressed air supply that permanent installations cannot match, pulling mobile electric units into factory settings.
- Gulf Coast Energy Corridor:Petrochemical turnaround schedules and LNG export facility construction concentrate short-term rental demand for high-pressure portable systems in Texas and Louisiana.
Market Restraints
- Copper and Rare Earth Input Costs:Electric motor windings and permanent magnet materials expose fleet capex to commodity volatility that diesel engine suppliers partially hedge.
- Charging Infrastructure Gaps:Rural construction sites and remote oilfield locations lack grid capacity for electric compressor deployment, constraining geographic addressable market.
- EU F-Gas Refrigerant Restrictions:Aftercooler and dryer systems face lubricant reformulation costs that compress margin on mid-range rental units crossing European borders.
Strategic Opportunities
- India Industrial Clusters:Automotive and textile manufacturing zones near Pune and Chennai show nascent rental penetration with limited local fleet supply.
- Battery-Electric Convergence:Integration of onboard energy storage with variable-speed drive compressors enables off-grid operation at sites with intermittent power.
- OSHA Silica Rule Enforcement:Strict dust suppression mandates on construction sites accelerate specification of integrated compressor-blower packages for wet cutting applications.
Industry Challenges
- Certified Compressor Technician Shortage:Tier IV after-treatment systems and electric drive diagnostics require specialized training that vocational programs have not scaled to match fleet growth.
- Cross-Border Equipment Harmonization:Divergent Stage V and EPA certification requirements complicate fleet fungibility between European and North American rental pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rental Air Compressors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Compressors, Stationary Compressors, Electric Compressors, Diesel Compressors End User: Construction, Oil & Gas, Manufacturing, Automotive Distribution Channel: Direct Rental, Online Rental, Retail Rental, Third-Party Rental Application: Pneumatic Tools, Spray Painting, Sandblasting, Air Cleaning |
| Companies Covered | Atlas Copco, United Rentals, Inc., Ingersoll Rand, Caterpillar Inc., Ashtead Group Plc, Loxam Group, Kaeser Kompressoren, H&E Equipment Services, Doosan Portable Power, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rental Air Compressors Market Evolving Landscape
Electrification architectures and predictive maintenance platforms are compressing equipment lifecycles and rewriting how rental operators monetize uptime versus asset ownership.
Variable-speed permanent magnet motors paired with advanced drive controls are rewriting efficiency benchmarks for portable compressed air. Large general contractors in urban high-rise construction specify these units to meet indoor emissions rules while reducing fuel logistics overhead. The technology is rewriting lease rate structures toward kilowatt-hour consumption models rather than flat daily fees.
The EU F-Gas Regulation phase-down schedule tightens refrigerant choices for compressed air dryers and aftercoolers. Equipment manufacturers reformulate thermal management systems to accommodate lower-global-warming-potential alternatives. German industrial rental yards face the steepest compliance curve as REACH chemical restrictions overlap with F-Gas timelines.
Performance-based rental agreements now tie contractor payments to verified air delivery and energy consumption rather than equipment availability alone. Energy-intensive manufacturing verticals in the US Midwest pilot these arrangements to transfer operational risk to fleet owners. The shift is most pronounced among automotive stamping plants seeking to cap compressed air costs per unit produced.
Rental Air Compressors Market Segmentation
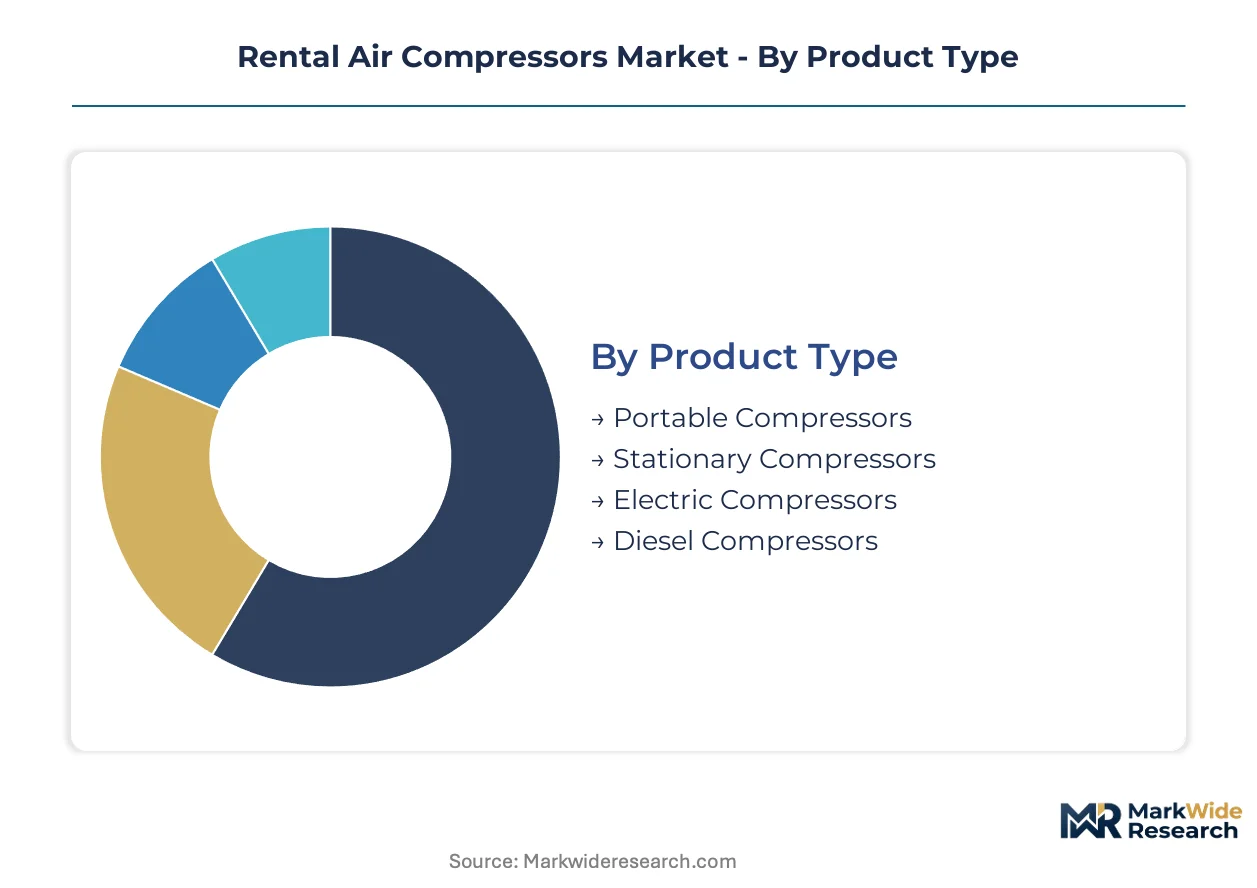
Rental air compressor procurement decisions pivot on mobility requirements, site power availability, and project duration. Fleet operators structure equipment mix around cross-site utilization rates and emissions compliance deadlines rather than upfront capital cost alone.
Product Type:
Buyers prioritize portability and fuel flexibility when specifying rental compressors for multi-location deployment.
- Portable Compressors:Mobile units mounted on skids or trailers deliver 70-250 psi output across construction phases and turnaround schedules. Demand concentrates in the United States Gulf Coast energy corridor where petrochemical contractors rotate equipment between Texas and Louisiana facilities on compressed timelines.
- Electric Compressors:Variable-speed permanent magnet drives eliminate diesel logistics and satisfy indoor air quality mandates. German automotive stamping plants and US Midwest manufacturing floors specify these units to cap energy costs per unit produced under performance-based rental agreements.
- Stationary Compressors:Fixed installations serve modular construction factories with continuous air demand.
- Diesel Compressors:Off-grid reliability sustains remote oilfield and rural construction sites lacking grid infrastructure.
Portable compressors lead on scale; electric compressors lead on momentum.
End User:
Application intensity and regulatory exposure determine rental-versus-ownership economics across verticals.
- Construction:General contractors face OSHA silica suppression mandates and compressed project schedules. Wet cutting applications pull integrated compressor-blower packages into urban high-rise sites where emissions rules prohibit diesel operation indoors.
- Manufacturing:Offsite modular construction facilities require flexible compressed air supply that permanent installations cannot match. Automotive and textile zones near Pune and Chennai show nascent rental penetration with limited local fleet supply.
- Oil & Gas:LNG export facility construction and turnaround maintenance concentrate short-term demand for high-pressure portable systems.
- Automotive:Stamping plants pilot energy consumption-based rental structures to transfer operational risk.
Construction dominates volume; manufacturing shows the steepest expansion trajectory.
Distribution Channel:
Channel selection hinges on contract duration, fleet management requirements, and margin capture objectives.
- Direct Rental:Fleet owners eliminate intermediary markups and enable long-term asset management contracts. Large general contractors negotiate kilowatt-hour consumption models rather than flat daily fees for electric unit deployments.
- Third-Party Rental:Regional brokers aggregate fragmented demand in secondary markets where national fleets lack yard density.
- Online Rental:Digital platforms match spot demand with available inventory in urban construction corridors.
- Retail Rental:Hardware-focused channels serve small contractors and DIY segments with limited specification requirements.
Direct rental captures the dominant margin pool; online channels are gaining share fastest.
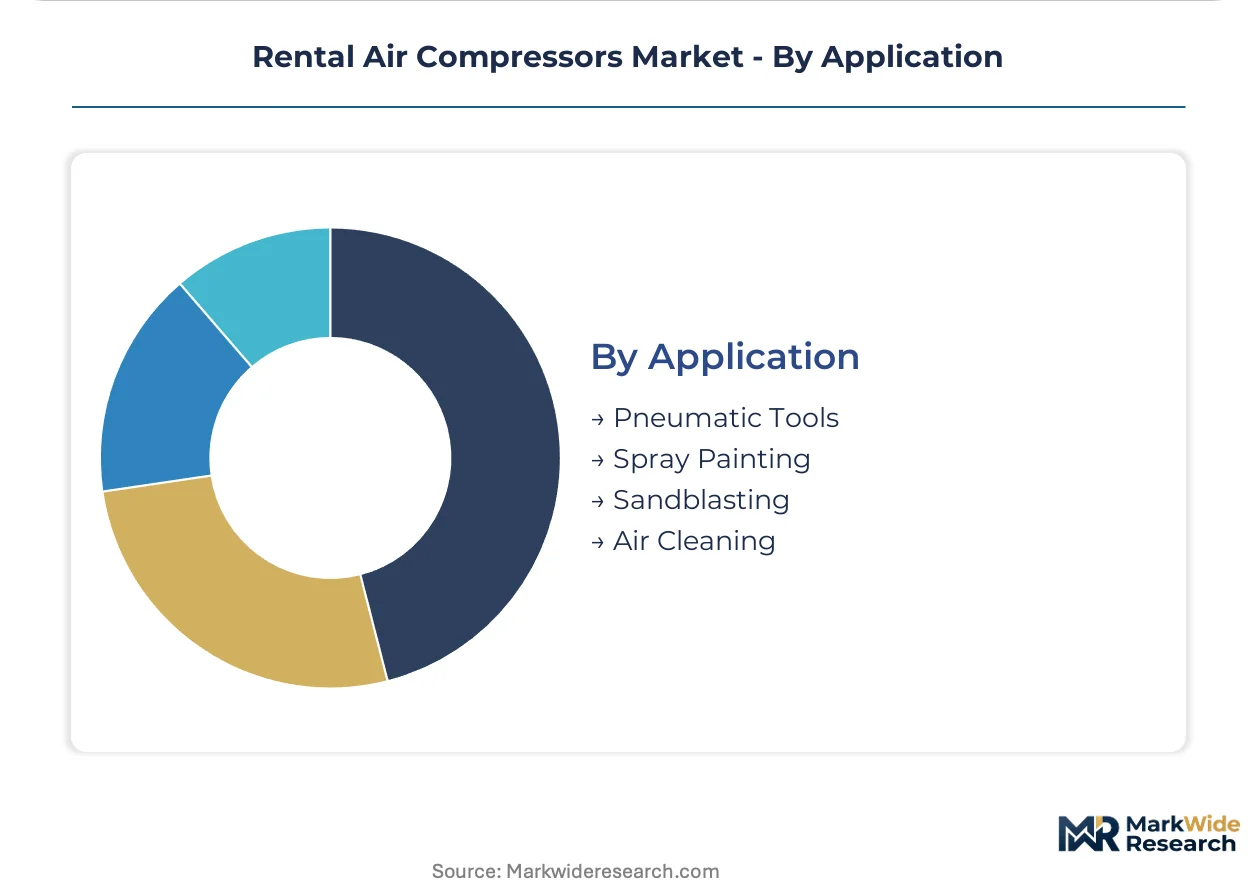
Application:
Air quality requirements and duty cycles differentiate equipment specification across use cases.
- Pneumatic Tools:Jackhammers, impact wrenches, and nail guns drive continuous demand for 90-120 psi portable units across construction phases. German industrial clusters specify Stage V-compliant compressors for infrastructure projects facing EU emissions deadlines.
- Sandblasting:High-volume air consumption requires large rotary screw units with integrated aftercoolers. REACH chemical restrictions and F-Gas refrigerant phase-downs force lubricant reformulation for dryer systems crossing European borders.
- Spray Painting:Moisture control specifications pull refrigerated dryer bundles into automotive refinishing applications.
- Air Cleaning:Blow-off and debris removal applications tolerate lower pressure precision with higher flow tolerance.
Pneumatic tools anchor volume; sandblasting commands premium rate structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified compressor technicians cluster around the United States Gulf Coast, German industrial corridors, and Chinese manufacturing zones, anchoring regional fleet deployment capacity and service response times.
United States
Petrochemical turnaround schedules and LNG export facility construction concentrate short-term rental demand for high-pressure portable systems across Texas and Louisiana. The EPA enforces Tier IV final emissions standards for non-road diesel engines, compelling rental yards to refresh aging portable fleets. The Gulf Coast energy corridor rotates equipment between facilities on compressed timelines, pulling mobile electric units into factory settings.
Germany
Automotive stamping plants and industrial manufacturing floors specify electric compressors to cap energy costs per unit produced under performance-based rental agreements. The EU F-Gas Regulation and REACH framework restrict refrigerants and lubricants used in compressed air systems, shaping product design and cross-border equipment transfers. German industrial rental yards face the steepest compliance curve as chemical restrictions overlap with emissions deadlines.
China
Automotive and textile manufacturing zones near Shanghai and Guangzhou show accelerating rental penetration as project timelines compress and ownership economics shift. The country's national environmental regulator enforces dual carbon goals that push fleet operators toward electric and Stage V-compliant compressors. Yangtze River Delta industrial clusters concentrate demand for flexible compressed air supply that permanent installations cannot match.
India
Automotive and textile manufacturing zones near Pune and Chennai demonstrate nascent rental penetration with limited local fleet supply, creating white-space opportunities for organized rental operators. The Bureau of Indian Standards and central environmental authority shape equipment certification and emissions compliance timelines. Western and Southern industrial corridors concentrate project demand where permanent compressed air infrastructure remains underdeveloped.
United Arab Emirates
Construction megaprojects and oilfield services sustain demand for portable diesel units in remote locations lacking grid infrastructure for electric deployment. The national environmental regulator enforces emissions standards that gradually tighten non-road engine specifications. Dubai and Abu Dhabi construction corridors concentrate short-term rental demand for high-pressure systems on compressed project schedules.
Rental Air Compressors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where scale advantages in fleet density clash with agility in customer-specific configurations. The vendor base organizes around three strategic archetypes: global equipment manufacturers with captive rental divisions, independent national rental networks with yard-density advantages, and regional brokers aggregating fragmented secondary-market demand. Consolidation pressure operates through acquisition of local fleet operators and strategic partnerships for electrification technology access.
Among global equipment manufacturers with integrated rental capabilities, Atlas Copco, United Rentals, Inc., and Ingersoll Rand exemplify contrasting strategic positions. The Swedish conglomerate anchors premium portable fleet deployments through global service network reach. The American rental pure-play occupies the largest yard footprint position across domestic construction corridors. The Irish-American industrial specialist represents integrated air solution bundling that combines compressors with downstream treatment equipment.
| Leading Market Players |
|---|
| Atlas Copco |
| United Rentals, Inc. |
| Ingersoll Rand |
| Caterpillar Inc. |
| Ashtead Group Plc |
| Loxam Group |
| Kaeser Kompressoren |
| H&E Equipment Services |
| Doosan Portable Power, Inc. |
| Others |
Value Network & Pricing Analysis
Copper winding costs and rare earth magnet prices cascade from motor suppliers through electric compressor OEMs to rental fleet operators, compressing margins on premium portable units while diesel engine hedging partially insulates legacy tiers. Tier IV after-treatment retrofit expenses and F-Gas refrigerant reformulation costs concentrate pricing pressure on mid-range equipment crossing regulatory boundaries.
Pricing Analysis
The bundled-versus-unbundled service split separates fleet operators capturing long-term asset management contracts from spot rental brokers aggregating fragmented demand. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier IV certification status, after-sales service bundling, and geographic delivery density. Cost compression in the electric compressor tier is intensifying because copper and permanent magnet commodity exposure remains unhedged. Small regional contractors exhibit the highest price sensitivity, while petrochemical turnaround contractors prioritize uptime guarantees over daily rate differentials.
Supply Chain Analysis
Certified compressor technician scarcity in the United States Gulf Coast, German industrial corridors, and Chinese manufacturing zones constrains fleet deployment velocity and extends service response intervals. Motor winding fabrication draws from Chinese rare earth processing and German precision manufacturing, while diesel engine supply rests on established North American and European foundry networks. Single-source vulnerability in permanent magnet sourcing exposes electric fleet expansion timelines to export restriction risk. Distribution runs through captive rental yards for national fleet operators and regional broker networks for secondary market coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through electrification-driven premium tier migration and performance-based contract structures that transfer operational risk to fleet owners.
For Market Incumbents: Acquire specialized electric drive service capabilities to offset certified technician scarcity threatening fleet utilization rates. Consolidate regional broker networks in the United States Gulf Coast and German industrial corridors to capture density economies. Battery-electric compressor integration represents the critical R&D lever against emerging pure-play electric entrants. For New Entrants and Emerging Players: Digital platform aggregation of spot demand in Indian automotive and textile manufacturing zones near Pune and Chennai bypasses incumbent yard density advantages. Target wet cutting application bundles for OSHA silica rule compliance as the most penetrable construction segment. White-label electric compressor deployment with integrated IoT monitoring enables rapid fleet scaling without captive manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fleet operators lack capital to refresh toward Tier IV and Stage V compliance deadlines. Long-term viability favors vertically integrated specialists with captive service networks over pure equipment lessors. Monitor electrification infrastructure buildout pace in rural construction corridors as the inflection signal for diesel residual value risk.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | EPA Tier IV and EU Stage V deadlines force diesel retirement timelines across rental yards. |
| Performance-Based Contracting | Automotive stamping plants in the US Midwest pilot kilowatt-hour consumption models. |
| Service Network Expansion | Gulf Coast petrochemical corridors require compressed turnaround response intervals. |
| Digital Platform Integration | Online channels match spot demand with available inventory in urban construction zones. |
| Technician Certification Programs | Vocational training gaps threaten Tier IV after-treatment and electric drive diagnostics capacity. |
Research Methodology
Bottom-up construction and manufacturing demand modeling reconciled against top-down rental fleet capacity tracking forms the analytical core of this study. Primary interviews with fleet operations directors, plant maintenance engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation filings, customs trade records, and equipment registration data. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of replacement cycle patterns and emissions compliance deadlines informed the projection framework across the analysis window. Segmentation dimensions modeled include product mobility tier, power source architecture, end-use vertical, distribution channel structure, and regional regulatory cluster. CAGRs derive from equipment deployment velocity, fleet refresh timelines, and contract structure evolution. Electrification infrastructure buildout assumptions and commodity price trajectory scenarios shape electric compressor adoption curves.
The model assumes a particular technology adoption path; alternative pathways for battery-electric convergence with onboard energy storage would alter the outlook. Forecasts reflect underlying assumptions about emissions enforcement consistency, rare earth supply continuity, and charging infrastructure deployment. Material deviation in EPA Tier IV enforcement intensity, EU F-Gas phase-down pacing, or copper price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Reciprocating Compressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Air and Gas Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Root Blower Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Automotive Compressors Market
Compressors
Air Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Bus Compressor Market
Compressors
North America Air Compressor Market
Compressors
Stationary Air Compressor Market