
 Solar Panel Mounting Structure Market | 2026-2036
Solar Panel Mounting Structure Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Mounting Structure Market Analysis
The capital-intensity divergence between automated tracker manufacturers and fixed-tilt fabricators is redrawing competitive boundaries across the supply base. Nextracker Inc. leverages its vertically integrated steel sourcing and software-driven tracking algorithms to sustain margin capture in utility-scale deployments. Array Technologies Inc. anchors its position through domestic U.S. manufacturing footprints that navigate tariff exposure on imported structural steel. Clenergy specializes in distributed roof-mounted systems, competing on lightweight aluminum extrusion designs that reduce ballast requirements for commercial flat-roof installations.
A solar panel mounting structure is a mechanical assembly of rails, clamps, brackets, and foundation anchors that positions photovoltaic modules at optimal orientation angles while withstanding wind loads, snow loads, and seismic forces per IEC 62817 and ASCE 7 design standards. Its primary commercial purpose is to maximize energy yield per installed kilowatt while ensuring structural integrity across twenty-five-year asset lifetimes. Ground-mounted tracker systems command premium pricing due to dual-axis motorization and control electronics integration, whereas roof-mounted fixed-tilt configurations represent the volume base driven by residential and commercial retrofit activity. Steel dominates material selection for utility-scale pylons and torque tubes, while aluminum extrusions lead in distributed applications where corrosion resistance and weight reduction offset higher raw material costs.
The U.S. Department of Commerce anti-dumping duties on Chinese steel and aluminum shape sourcing strategies for domestic mounting structure fabricators, while India's BIS certification mandates for structural steel and the PLI scheme's domestic content requirements redirect procurement toward local mills and roll-formers. The EU's F-Gas Regulation and CSRD disclosure rules indirectly pressure mounting system suppliers to document embodied carbon in aluminum and steel supply chains for EPC contractor compliance. Stakeholders must monitor evolving local content thresholds and carbon border adjustment mechanisms to calibrate manufacturing footprints and supplier qualification programs.
Market Dynamics
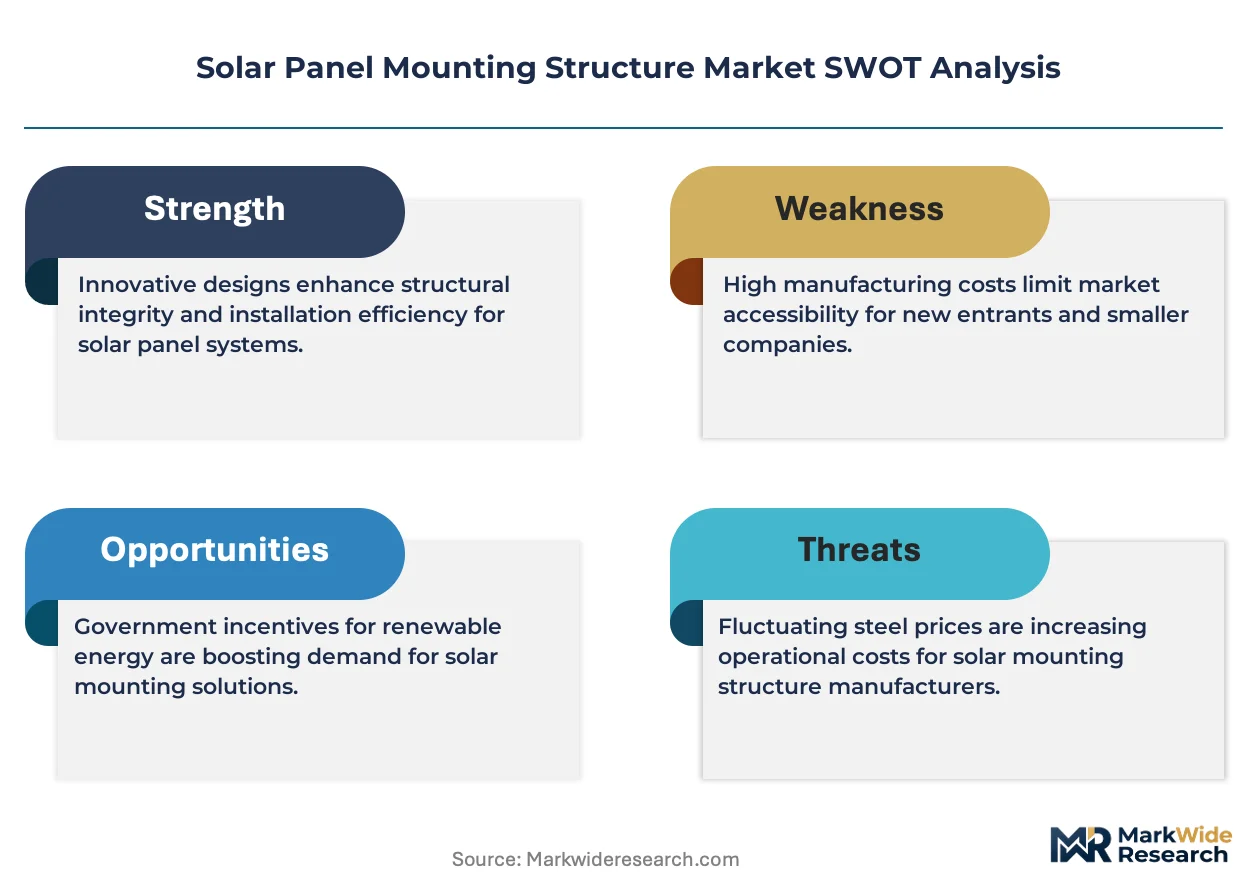
Steel tariff cascades and domestic content mandates are fragmenting procurement strategies across the mounting structure supply base. Fabricators must now qualify multiple regional mill sources while tracker manufacturers absorb motor and control electronics cost volatility.
Growth Catalysts
- India PLI Scheme:Domestic content requirements for solar modules are cascading downstream into localized racking and structural component sourcing, creating captive demand for local roll-formers.
- Tracker-enabled systems:Dual-axis motorization with embedded control electronics is capturing procurement preference from utility-scale developers seeking yield optimization.
- IEC 62817 certification:Standardized design validation for wind and seismic loads is reducing EPC contractor qualification friction across emerging solar markets.
Market Restraints
- Structural steel volatility:Hot-rolled coil price swings and Section 232 tariff exposure compress fabrication margins for ground-mounted pylons and torque tubes.
- Aluminum extrusion concentration:Chinese smelter dominance in primary aluminum creates supply risk for distributed roof-mounted system manufacturers.
- Foundation anchoring complexity:Geotechnical variability across clay, sand, and rocky substrates limits standardization of driven-pile foundations.
Strategic Opportunities
- Agrivoltaics integration:Elevated tracker configurations enabling simultaneous crop cultivation and energy generation are opening farmland-adjacent deployment channels.
- Floating solar anchoring:Pontoon-based and tension-mooring systems for reservoirs and quarry lakes represent underpenetrated application white space.
- EU Carbon Border Adjustment Mechanism:Embodied carbon documentation requirements create first-mover advantage for mills with verified low-carbon steel production.
Industry Challenges
- Structural engineering talent scarcity:Finite pool of licensed engineers proficient in ASCE 7 wind load calculations and IEC seismic validation bottlenecks project execution timelines.
- Multi-jurisdiction certification backlog:BIS approval queues for India-market steel grades and UL 2703 testing for U.S. grounding continuity delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Mounting Structure Market |
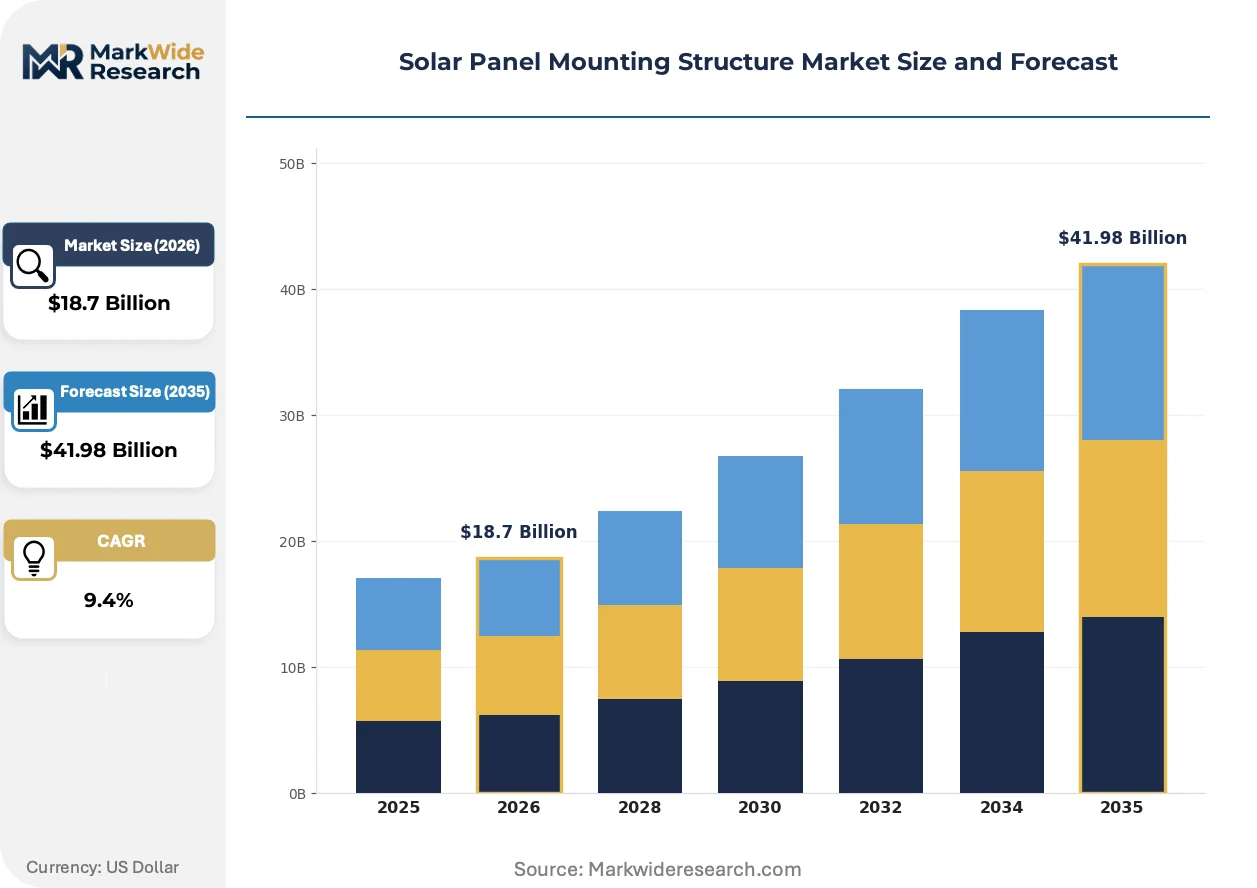
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-mounted, Roof-mounted, Building-integrated, Solar tracker Installation Type: Residential, Commercial, Industrial, Utility-scale Material: Aluminum, Steel, Plastic, Composite Design: Fixed tilt, Adjustable tilt, Ballasted, Hybrid |
| Companies Covered | Nextracker Inc., Array Technologies Inc., Arctech Solar Holding Co., Ltd., Soltec Power Holdings, PVHardware, Schletter Group, Unirac, Clenergy, GameChange Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Mounting Structure Market Emerging Trajectories
Control electronics and structural hardware are converging into integrated electromechanical systems. This fusion is compressing supplier tiers and rewriting qualification protocols for utility-scale procurement.
Artificial intelligence-driven tracking algorithms are miniaturizing into edge-computing modules mounted directly on torque tube assemblies. These embedded controllers process local irradiance and weather data to optimize panel orientation without centralized SCADA dependency. Array Technologies and Nextracker are embedding these modules in new utility deployments, compressing commissioning timelines and reducing cabling infrastructure.
The EU F-Gas Regulation and CSRD disclosure rules are mandating embodied carbon documentation across aluminum and steel supply chains. EPC contractors now require mill-specific emissions certificates to satisfy project finance due diligence. Mounting structure suppliers serving European utility-scale tenders are requalifying toward electric-arc-furnace steel sources and low-carbon primary aluminum.
Engineering-procurement-construction firms are consolidating vendor panels and demanding outcome-based performance guarantees. Tier-one developers now specify energy yield per installed kilowatt rather than component-level pricing, forcing mounting structure suppliers to assume production risk. This shift is most visible in U.S. utility-scale procurement, where Nextracker and Array Technologies compete on guaranteed performance algorithms rather than hardware cost alone.
Solar Panel Mounting Structure Market Segmentation
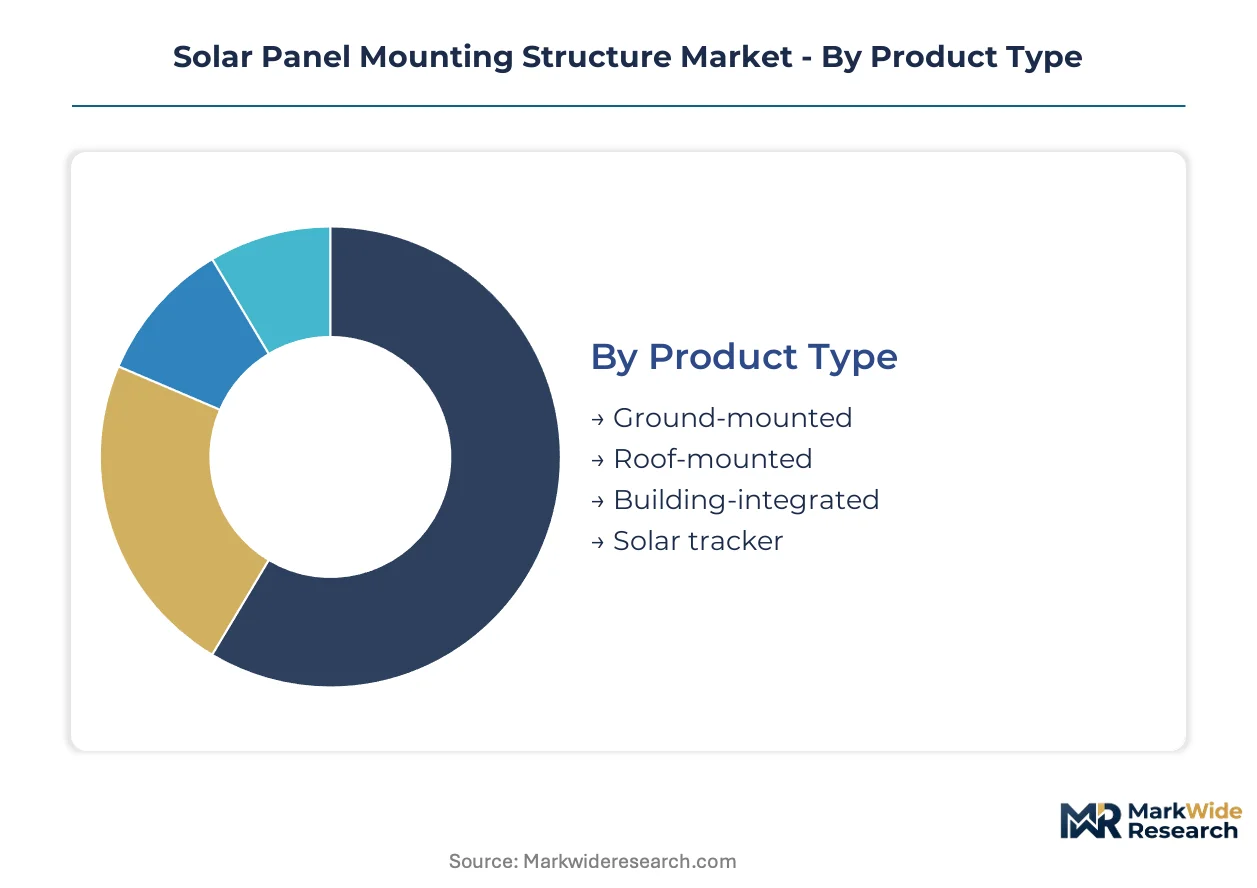
Mounting structure procurement diverges sharply across deployment contexts, with utility-scale developers prioritizing yield optimization through motorized tracking while residential contractors minimize labor hours through lightweight prefabrication. Material selection and design configuration directly determine foundation requirements, shipping costs, and installation crew sizing.
Product Type:
Ground-mounted pylons face substitution pressure from elevated agrivoltaic configurations and floating solar pontoon systems that unlock previously inaccessible land and water surfaces.
- Ground-mounted:Steel pylon and torque tube assemblies anchored by driven piles or concrete ballast dominate utility-scale procurement. Demand concentrates in India and the southwestern United States where flat terrain and high irradiance justify extensive civil preparation.
- Roof-mounted:Aluminum rail and clamp systems reduce structural loading on commercial flat roofs while minimizing penetration. Installers in Germany and Japan favor these configurations for dense urban retrofit markets with limited ground availability.
- Building-integrated:Structural glazing and facade-embedded frames merge photovoltaic generation with architectural envelope functions. These systems command design premiums in commercial construction across France and Italy where aesthetic integration mandates apply.
- Solar tracker:Dual-axis and single-axis motorized assemblies with embedded control electronics optimize panel orientation throughout diurnal and seasonal cycles. Procurement is accelerating in Saudi Arabia and Australia where desert conditions amplify yield gains from tracking precision.
Ground-mounted configurations retain volume leadership; solar tracker holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates high-volume residential retrofit kits from engineered utility-scale systems requiring geotechnical survey and custom foundation design.
- Residential:Standardized rail kits with pre-assembled clamps reduce crew time for rooftop retrofits. Demand clusters in suburban California and Texas where net metering policies and installer competition compress customer acquisition costs.
- Commercial:Ballasted flat-roof systems eliminate membrane penetration while accommodating HVAC equipment clearance. Property owners in Illinois and New York specify these for warehouse and big-box retail portfolios facing roof warranty constraints.
- Industrial:Heavy-duty steel structures support larger module formats and higher wind loads for manufacturing facility carports and canopies. Mexican maquiladora zones and Vietnamese export processing parks drive procurement for on-site generation mandates.
- Utility-scale:Centralized procurement of tracker-enabled or fixed-tilt arrays exceeding 100 MW requires integrated steel sourcing and installation logistics. Developers in Rajasthan and Gujarat anchor volume through India's renewable energy auction mechanisms.
Utility-scale commands the highest revenue per installation; residential delivers the steepest expansion trajectory.
Material:
Supply concentration in Chinese primary aluminum and tariff-exposed steel grades is fragmenting procurement toward regional mill qualification and recycled content verification.
- Aluminum:Extruded 6000-series alloys deliver corrosion resistance and weight reduction for roof-mounted distributed applications. European EPC contractors now require electric-arc-furnace sourcing to satisfy CSRD embodied carbon disclosure rules.
- Steel:Hot-rolled coil and galvanized structural sections form torque tubes, pylons, and ground screws for utility-scale deployments. Section 232 tariff exposure and BIS certification requirements in India are redirecting procurement toward domestic U.S. and Indian mills.
- Plastic:Glass-reinforced polymer and high-density polyethylene components reduce shipping weight for remote island and alpine installations. These materials expand most quickly in Caribbean microgrid projects where corrosion and logistics constraints exclude metallic alternatives.
- Composite:Fiber-reinforced polymer hybrids combine tensile strength with electromagnetic transparency for radar-adjacent and airport perimeter deployments. Military and aviation authorities in the United Kingdom and Japan specify these for critical infrastructure security zones.
Steel retains volume leadership; composite materials gain share fastest in specialized applications.
Design:
Maturity differentiation separates decades-proven fixed-tilt engineering from emerging hybrid configurations that adapt to terrain constraints without full motorization.
- Fixed tilt:Rigid angle settings optimized for latitude-season yield profiles minimize moving parts and maintenance exposure. These designs dominate residential and commercial retrofits in Spain and Australia where simplicity and durability outweigh incremental yield capture.
- Adjustable tilt:Seasonal manual or semi-automated angle modification accommodates summer-winter sun path variation. Agricultural cooperatives in Italy and Greece deploy these for elevated agrivoltaic arrays where crop rotation cycles dictate panel repositioning.
- Ballasted:Concrete block or paver-based anchoring eliminates ground penetration for landfill caps, brownfields, and membrane-protected commercial roofs. Environmental regulators in Massachusetts and New Jersey mandate these for contaminated site reuse projects.
- Hybrid:Combined structural approaches integrate driven piles with ballast backup or fixed-tilt frames with limited seasonal adjustability. These configurations are climbing the fastest in Southeast Asian markets where monsoon flooding and variable substrate conditions defy pure design categorization.
Fixed tilt retains volume leadership; hybrid designs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in India absorb steel price volatility most readily, while residential installers in Germany and Japan optimize for lightweight aluminum systems where labor costs dominate project economics. This elasticity divergence fragments procurement strategies across geographies.
United States
Utility-scale solar auctions in Texas and California drive concentrated demand for tracker-enabled steel structures. Section 232 tariffs on imported hot-rolled coil redirect procurement toward domestic mills in Indiana and Ohio. Nextracker and Array Technologies anchor manufacturing footprints in Arizona and New Mexico to navigate tariff exposure.
India
PLI scheme domestic content requirements cascade from module manufacturing into localized racking and structural component sourcing. BIS certification mandates for structural steel redirect procurement toward domestic roll-formers in Gujarat and Rajasthan. Developers in these states anchor volume through centralized renewable energy auction mechanisms.
Germany
Commercial flat-roof retrofits in the Ruhr and Bavaria prioritize aluminum rail systems that minimize structural loading. CSRD disclosure rules and EU F-Gas Regulation pressure EPC contractors to document embodied carbon in steel and aluminum supply chains. Electric-arc-furnace mills in North Rhine-Westphalia gain qualification preference for low-carbon verification.
Australia
Desert utility-scale deployments in Queensland and South Australia amplify yield gains from dual-axis tracking precision. IEC 62817 certification reduces qualification friction for wind and seismic load validation. Local fabricators in Adelaide and Brisbane specialize in hybrid foundation designs accommodating variable geotechnical substrates.
Saudi Arabia
Neom and Red Sea gigaproject developments procure elevated agrivoltaic configurations enabling simultaneous crop cultivation. The kingdom's renewable energy procurement office mandates localized content thresholds for structural steel. Domestic roll-formers in Jubail Industrial City scale capacity to serve concentrated utility-scale pipeline.
Solar Panel Mounting Structure Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in tracker motorization and software integration. The middle tier fragments across regional roll-formers serving fixed-tilt utility projects and lightweight fabricators targeting distributed roof markets. Two strategic archetypes dominate: vertically integrated tracker manufacturers with captive steel sourcing, and aluminum extrusion specialists competing on corrosion resistance and weight reduction. Competitive moves concentrate on domestic manufacturing footprint expansion and outcome-based performance guarantee structures.
Within the integrated tracker tier, Nextracker Inc. and Array Technologies Inc. occupy positions exemplifying scale-driven electromechanical convergence. Nextracker represents the archetype of software-driven yield optimization with embedded control algorithms, while Array Technologies anchors the domestic U.S. manufacturing footprint strategy. Clenergy sits within the distributed-application specialist tier, exemplifying lightweight aluminum design competition for commercial flat-roof installations where ballast reduction determines procurement preference.
| Leading Market Players |
|---|
| Nextracker Inc. |
| Array Technologies Inc. |
| Arctech Solar Holding Co., Ltd. |
| Soltec Power Holdings |
| PVHardware |
| Schletter Group |
| Unirac |
| Clenergy |
| GameChange Solar |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with domestic steel mills lock in both supply access and price visibility for utility-scale tracker manufacturers navigating Section 232 tariff exposure in the United States and BIS certification mandates in India. These arrangements insulate procurement teams from hot-rolled coil volatility while satisfying EPC contractor requirements for domestic content documentation.
Pricing Analysis
After-sales service contracts spanning control electronics calibration, torque tube inspection, and tracker motor replacement drive lifetime value capture for integrated system suppliers. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed performance algorithms with embedded AI optimization from fixed-tilt commodity hardware. Cost compression in standard-tier fixed-tilt pylons is intensifying because Indian roll-formers scale capacity under PLI scheme downstream pressure. Residential retrofit contractors exhibit highest price sensitivity due to customer acquisition cost constraints, while utility-scale developers prioritize yield guarantees over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as fabricators buffer against hot-rolled coil price swings and aluminum extrusion lead time variability. Primary supply concentration centers on China for primary aluminum smelting, India for galvanized structural steel under BIS certification, and the United States for electric-arc-furnace steel serving EU-bound exports. Component dependencies include torque tube steel grades, tracker motor assemblies, and edge-computing control modules. Single-source vulnerability in Chinese primary aluminum creates supply risk for distributed roof-mounted system manufacturers. Distribution runs through EPC contractor vendor panels and qualified supplier lists at tier-one developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel mounting structure market sits in early-cycle expansion as agrivoltaic configurations and floating solar anchoring systems unlock previously inaccessible deployment surfaces. Tracker-enabled yield optimization is accelerating procurement preference among utility-scale developers seeking production guarantees.
For Market Incumbents: Fortify domestic manufacturing footprints in Arizona and New Mexico to navigate tariff exposure on imported structural steel. Deepen captive supply of hot-rolled coil through mill partnerships in Indiana and Ohio. Invest in IEC 62817 certification capacity to reduce EPC contractor qualification friction as project pipelines concentrate in Rajasthan and Gujarat.
For New Entrants and Emerging Players: Anchor in floating solar pontoon systems for Southeast Asian reservoir deployments where geotechnical constraints exclude driven-pile foundations. Target elevated agrivoltaic configurations in Saudi Arabia's Neom development and Italian agricultural cooperatives. Pursue outcome-based performance guarantee structures that shift revenue toward energy yield per installed kilowatt rather than hardware unit sales.
For Investors and Strategic Acquirers: Regional roll-formers with BIS-certified steel capacity and established EPC contractor relationships represent the most compelling acquisition target archetype. Long-term viability hinges on localization depth under tightening domestic content mandates across India, the United States, and Saudi Arabia. Watch for steel tariff cascade announcements as the primary inflection indicator for margin compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Steel Mill Partnership | BIS certification and PLI compliance in India redirect procurement toward Gujarat and Rajasthan roll-formers. |
| Tracker Control Electronics Integration | Embedded AI modules on torque tube assemblies compress commissioning timelines for Saudi Arabian desert deployments. |
| Agrivoltaic Configuration Development | Elevated tracker designs enable simultaneous crop cultivation in Italian cooperatives and Saudi gigaprojects. |
| Floating Solar Anchoring System Launch | Pontoon-based and tension-mooring systems unlock reservoir deployments across Southeast Asian markets. |
| Low-Carbon Steel Sourcing Program | Electric-arc-furnace qualification satisfies EU CSRD disclosure rules and Carbon Border Adjustment Mechanism compliance. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility-scale developers in Texas and California, EPC contractor procurement leads, tracker manufacturer supply chain directors, Indian roll-former operations managers, and commercial rooftop installation contractors in Germany and Japan. Secondary validation drew from EIA project development databases, IEA renewable energy deployment reports, SEC filings of publicly listed tracker manufacturers, BIS certification registries, and EU CSRD disclosure filings. Bottom-up volume estimates from project-level procurement data were triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework modeled demand by product type, installation scale tier, material specification, and design configuration while tracking regulatory framework variations across national jurisdictions. CAGRs were derived from segment-level growth trajectory analysis incorporating steel price elasticity coefficients, tracker penetration curves in high-irradiance markets, and domestic content threshold compliance timelines. Industry-specific inputs included hot-rolled coil price indices, IEC 62817 certification adoption rates, and PLI scheme disbursement velocity in India.
Decision-makers should treat outputs as directional under base assumptions of sustained steel tariff structures and stable renewable energy auction mechanisms; material deviation would warrant model refresh. Specific risk factors include sudden suspension of India's PLI scheme, elimination of Section 232 steel tariffs, or breakthrough cost reduction in perovskite tandem cells displacing silicon module formats. Revision becomes warranted when aluminum smelter concentration in China crosses critical supply disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Marine Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Solar EPC Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Norway Renewable Energy Market