
 Electric Vehicle Charging Facilities Market | 2026-2036
Electric Vehicle Charging Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Facilities Market Insights
Aftermarket service revenue is tilting from pure hardware sales toward software-managed charging subscriptions and grid-integration services. ABB leverages its power-electronics heritage to sustain leadership in high-voltage DC fast charging systems. Tesla anchors its competitive position through proprietary Supercharger network control and energy management software. Star Charge dominates China's domestic installation base with extensive operational scale across tier-one cities.
Electric vehicle charging facilities encompass the physical infrastructure, power distribution equipment, and communication systems enabling battery electric vehicles to replenish energy stores, typically operating across voltage ranges from 120V alternating current to 800V direct current with power outputs spanning 1.4 kW to 350 kW. These installations serve commercial, residential, and public environments to reduce vehicle downtime and enable fleet utilization. DC Fast Chargers command the dominant share of capital deployment as fleet operators and highway corridor developers prioritize rapid turnaround times. Wireless Chargers represent an emerging structural segment where technology leadership in inductive power transfer standards will determine early margin pools. Residential Installations maintain steady baseline demand but face margin compression from commoditized Level 2 hardware.
The US Federal Energy Regulatory Commission and the Environmental Protection Agency shape grid interconnection standards and clean energy procurement requirements that directly influence charging facility economics. China's Ministry of Industry and Information Technology governs GB/T charging standards and dual carbon implementation timelines that mandate infrastructure buildout. The European Union's F-Gas Regulation and Alternative Fuels Infrastructure Regulation establish binding deployment targets and technical specifications across member states. Stakeholders must monitor evolving interoperability mandates and grid capacity allocation mechanisms as decisive variables for capital allocation.
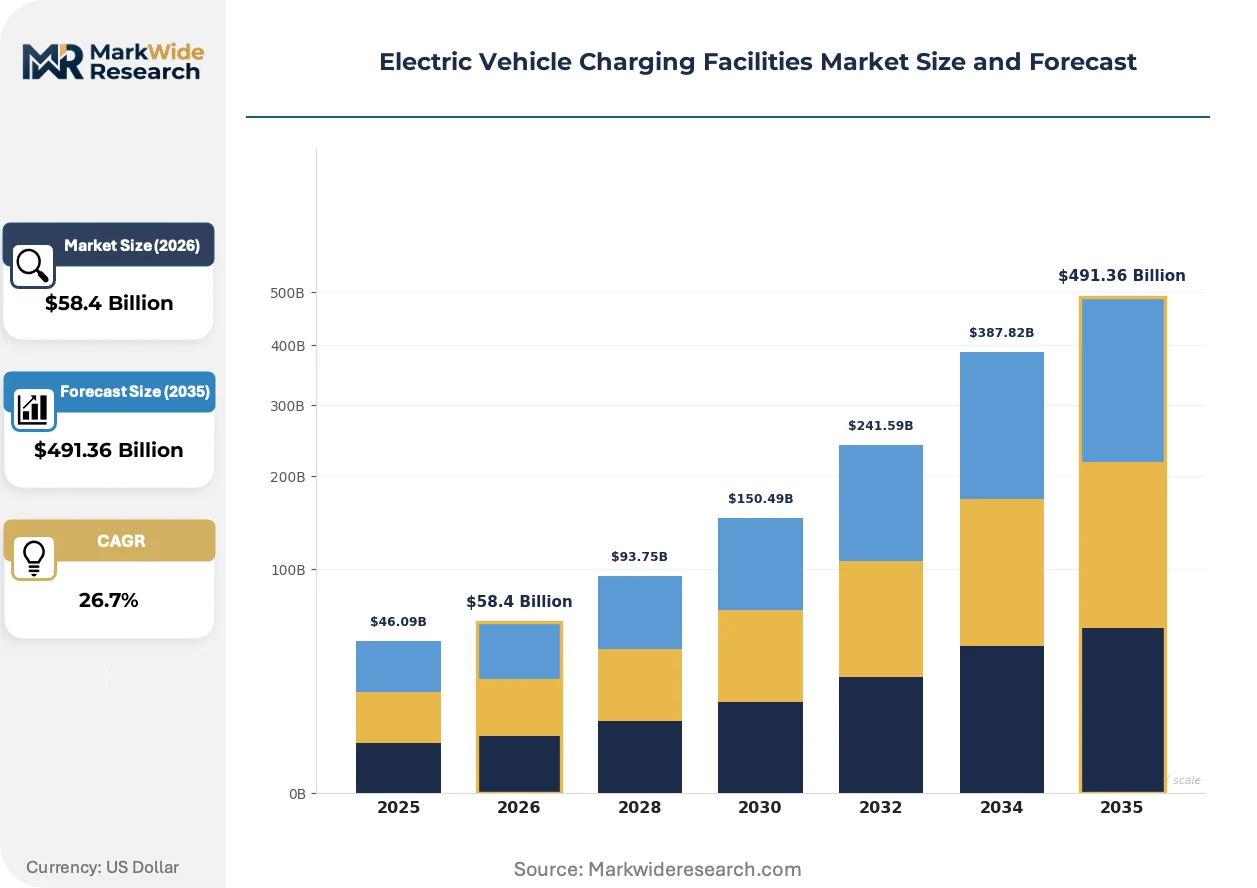
Market Dynamics
Fleet electrification timelines are compressing installation windows while grid interconnection queues stretch beyond twenty-four months in major metropolitan clusters, forcing developers to pre-position substations ahead of committed vehicle deployments.
Growth Catalysts
- US Inflation Reduction Act:Federal tax credits covering thirty percent of charging hardware and installation costs are accelerating deployment commitments from logistics operators and highway corridor developers.
- China's dual carbon mandate:Binding provincial targets under MIIT supervision are requiring state-owned fleet operators to electrify vehicle bases and install supporting infrastructure across eastern coastal manufacturing belts.
- 800V battery architectures:Premium passenger and commercial vehicle platforms are demanding 350kW DC fast charging capability, driving capital allocation toward high-voltage power electronics and thermal management systems.
Market Restraints
- Transformer lead times:Distribution-grade electrical equipment from domestic suppliers now extends beyond fifty-two weeks, creating critical-path delays for site energization.
- Silicon carbide supply concentration:Power semiconductor fabrication for high-efficiency inverters concentrates among East Asian foundries, exposing charger manufacturers to single-source vulnerability.
- Grid capacity allocation:Utility interconnection studies in dense urban districts are rejecting or deferring commercial charging projects due to localized distribution constraints.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are creating downstream demand for charging infrastructure across Maharashtra and Gujarat industrial corridors.
- Bidirectional charging integration:Vehicle-to-grid capability convergence with distributed energy resource management systems is opening recurring revenue streams for fleet operators and utilities.
- Apartment and condominium retrofits:Multi-unit dwelling parking structures represent an underserved installation category requiring load-sharing hardware and submetering solutions.
Industry Challenges
- Licensed electrician scarcity:Journeyman certification programs are failing to match installation workforce demand in California, Texas, and Germany's industrial regions.
- Interoperability certification delays:Multi-vendor testing protocols for ISO 15118-2 communication stacks are extending product launch timelines by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Facilities Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $491.36 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Home Charging Stations Installation Type: Commercial Installations, Residential Installations, Public Installations, Fleet Installations End User: Individual Consumers, Businesses, Government Agencies, Fleet Operators Charging Station Type: Level 1 Stations, Level 2 Stations, Superchargers, Fast Charge Stations |
| Companies Covered | ChargePoint, ABB, EVBox, Tesla, Eaton, Star Charge, TELD New Energy, Delta Electronics, Wallbox Chargers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Facilities Market Trends and Innovations
Software-defined charging management is displacing hardware-centric business models while regulatory mandates force faster standardization across communication protocols and grid integration requirements.
Cloud-native charging management platforms are virtualizing network operations previously requiring on-premise server infrastructure. Large fleet operators and charge point operators are adopting these architectures to centralize pricing optimization, predictive maintenance scheduling, and dynamic load balancing across dispersed asset bases. This virtualization is compressing capital requirements for network scaling while enabling real-time grid services participation.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon use in cooling systems for high-power charging equipment. Equipment manufacturers are redesigning thermal management architectures around CO2-based refrigeration cycles and liquid cooling loops to maintain power density compliance. German and French charging hardware suppliers are most affected, with product redesign cycles accelerating to meet 2027 prohibitions.
Fleet procurement departments are consolidating vendor relationships around integrated hardware-software-service bundles rather than transactional equipment purchases. Logistics operators and municipal transit agencies are favoring providers offering guaranteed uptime commitments and energy cost management. This concentration is most visible across the US West Coast corridor where megafleet electrification timelines demand single-accountability contracting structures.
Electric Vehicle Charging Facilities Market Segmentation
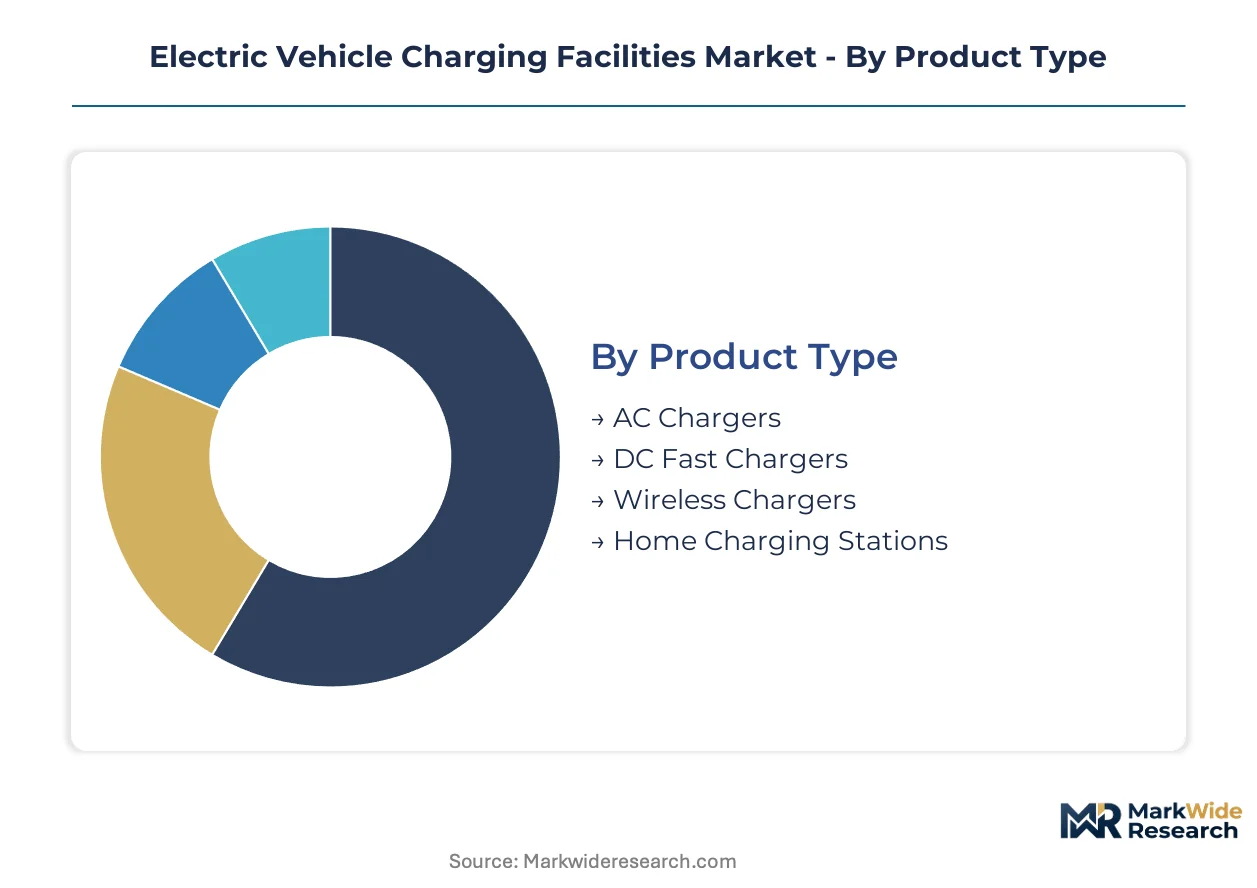
Charging facility economics diverge sharply across deployment contexts, with power output requirements and utilization patterns dictating capital recovery timelines. Segmentation reveals where hardware commoditization pressures concentrate versus where software and service layers capture durable margin.
Product Type:
Use cases span overnight residential replenishment to highway corridor fleet turnaround, with power electronics sophistication determining competitive differentiation.
- AC Chargers:These units deliver alternating current at 1.4 kW to 19.2 kW through onboard vehicle rectifiers. Demand clusters in workplace parking structures and multi-unit dwellings across Germany's industrial regions where extended dwell times accommodate slower replenishment cycles.
- DC Fast Chargers:Direct current systems bypass onboard conversion to deliver 50 kW to 350 kW through high-voltage power electronics and liquid-cooled cables. China's eastern coastal provinces and the US West Coast corridor dominate deployment as logistics operators prioritize sub-thirty-minute turnaround times for commercial vehicle fleets.
- Wireless Chargers:Inductive power transfer systems eliminate connector wear through aligned charging pads embedded in parking surfaces.
- Home Charging Stations:Dedicated residential units integrate with home energy management systems and time-of-use utility rate structures.
Established volume favors DC Fast Chargers; emerging adoption favors Wireless Chargers.
Installation Type:
Site ownership models and grid interconnection complexity create four distinct deployment archetypes with diverging procurement behaviors.
- Commercial Installations:Retail, hospitality, and workplace sites host these assets to attract customer dwell time and employee retention. California and Texas lead deployment volumes where commercial electricity rates and building code mandates accelerate landlord investment decisions.
- Residential Installations:Single-family home deployments dominate this category with Level 2 hardware standardizing around 240V, 40A configurations. Margin compression from hardware commoditization is most severe here as big-box retail channels displace electrical contractor sales.
- Public Installations:Municipal and highway corridor sites serve transient users with high reliability requirements and 24/7 accessibility mandates.
- Fleet Installations:Dedicated depot charging for logistics, transit, and municipal vehicle bases operates at highest utilization rates with predictable load profiles.
Procurement concentration is shifting toward Fleet Installations as electrification timelines compress; Residential Installations face channel margin erosion.
End User:
Customer sophistication and energy cost exposure create tiered service requirements from basic hardware to integrated energy management.
- Individual Consumers:Homeowners and renters prioritize installation simplicity and smartphone-controlled scheduling. China's tier-one cities show highest penetration where apartment dwellers access shared residential infrastructure through property management platforms.
- Businesses:Corporate facility managers seek workplace charging as employee benefit infrastructure with load management across multiple ports. Germany's automotive supplier corridors demonstrate densest deployment where employer-provided charging substitutes for scarce public alternatives.
- Government Agencies:Municipal procurement favors domestic manufacturing content and open-network interoperability standards.
- Fleet Operators:Logistics and transit entities demand guaranteed uptime commitments and total cost of ownership optimization through energy procurement and vehicle-to-grid integration.
Contract value concentrates with Fleet Operators; transaction volume concentrates with Individual Consumers.
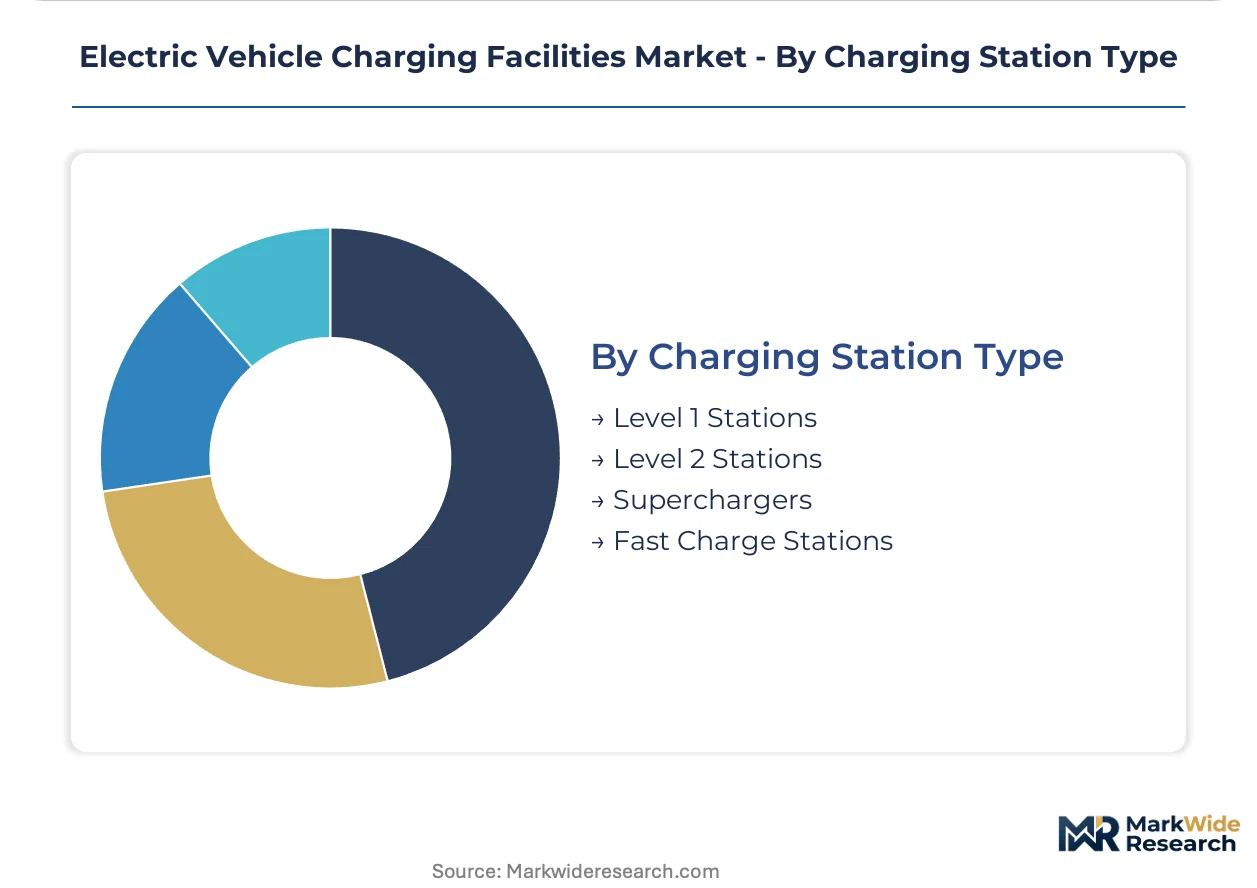
Charging Station Type:
Voltage and amperage specifications map directly to dwell time economics and vehicle platform compatibility requirements.
- Level 1 Stations:Standard 120V residential outlets deliver 1.4 kW to 1.9 kW through conventional three-prong connections. These persist in legacy parking infrastructure and emergency backup contexts where electrical service upgrades prove cost-prohibitive.
- Level 2 Stations:240V alternating current systems at 3.3 kW to 19.2 kW represent the commercial and residential workhorse standard. India's Maharashtra and Gujarat industrial corridors are scaling deployment fastest where PLI scheme incentives for cell manufacturing create downstream infrastructure demand.
- Superchargers:Proprietary high-power networks operate at 250 kW to 350 kW with integrated vehicle communication and billing ecosystems.
- Fast Charge Stations:Open-standard DC systems at 50 kW to 150 kW serve highway corridors and urban fast-turnaround applications.
Hardware margin pools concentrate in Superchargers; standardization pressure concentrates in Level 2 Stations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics fabrication clusters in East Asia and high-voltage equipment manufacturing in Central Europe concentrate supply-side capacity. Demand deployment follows fleet electrification corridors and subsidy-activated infrastructure programs across three continents. Regulatory fragmentation around grid interconnection standards is creating divergent procurement specifications by jurisdiction.
United States
Logistics operators and highway corridor developers are accelerating DC fast charging deployment along the West Coast and Texas interstates. The Inflation Reduction Act's thirty percent tax credit for charging hardware and installation costs compresses capital recovery timelines for commercial projects. California's building code mandates and Texas's deregulated utility market are driving divergent deployment models across metropolitan clusters.
China
State-owned fleet operators are electrifying vehicle bases across eastern coastal manufacturing belts under MIIT-supervised dual carbon mandates. Provincial binding targets require supporting infrastructure buildout in Jiangsu, Zhejiang, and Guangdong provinces. Star Charge and TELD New Energy dominate installation scale across Shanghai, Shenzhen, and Beijing tier-one city networks.
Germany
Automotive supplier corridors in Baden-Württemberg and Bavaria demonstrate densest workplace charging deployment where employer-provided infrastructure substitutes for scarce public alternatives. The EU F-Gas Regulation's 2027 hydrofluorocarbon prohibitions are forcing thermal management redesigns in high-power charging equipment. Berlin-Brandenburg and North Rhine-Westphalia industrial zones concentrate fleet depot electrification timelines.
India
Production-linked incentives for advanced chemistry cell manufacturing across Maharashtra and Gujarat industrial corridors are creating downstream charging infrastructure demand. State-level electric vehicle policies in Karnataka and Tamil Nadu mandate public charging density targets for urban agglomerations. The Bureau of Indian Standards is finalizing charging protocol harmonization to reduce multi-vendor interoperability friction.
Electric Vehicle Charging Facilities Market Competitive Landscape
Integrated hardware-software-service providers and pure-play equipment manufacturers split the market along value-capture depth. Incumbents with power-electronics heritage leverage high-voltage DC competency against cloud-native charge point operators scaling through network effects. Strategic moves concentrate on vertical integration into power semiconductor sourcing and geographic licensing partnerships for grid-interconnection expertise. M&A activity targets software-defined charging management platforms and thermal management specialists.
Within the integrated-systems tier, ABB and Tesla exemplify divergent strategic positioning around proprietary network control versus open-standard industrial equipment. ChargePoint occupies a position between these archetypes with cloud-native network operations spanning residential through commercial deployment contexts. Delta Electronics and EVBox represent regional-specialist configurations with concentrated European and Asian market presence respectively. Eaton anchors the electrical infrastructure incumbent archetype with distribution equipment integration capabilities.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| EVBox |
| Tesla |
| Eaton |
| Star Charge |
| TELD New Energy |
| Delta Electronics |
| Wallbox Chargers |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in silicon carbide wafer fabrication across East Asian foundries is forcing charger manufacturers into long-term offtake commitments, compressing procurement flexibility while elevating power electronics pricing premiums for DC fast charging systems. This utilization squeeze cascades through transformer procurement queues and licensed electrician labor markets, reshaping how developers structure project economics and supplier relationships.
Pricing Analysis
Software-managed charging subscriptions and grid-integration service contracts now capture the dominant share of lifetime value, displacing transactional hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates fleet operators demanding guaranteed uptime commitments from residential consumers prioritizing installation simplicity. Cost compression in Level 2 residential hardware is intensifying because big-box retail channels displace electrical contractor sales. Individual consumers exhibit highest price sensitivity, while fleet operators accept premium positioning for integrated energy management and vehicle-to-grid capability.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities are becoming standard for power semiconductor procurement as charger manufacturers manage working capital through fabrication bottlenecks. Power electronics fabrication concentrates in Taiwan, South Korea, and China, while high-voltage transformer manufacturing anchors in Germany and the United States. Silicon carbide wafers, liquid-cooled cable assemblies, and grid-interconnection switchgear constitute critical input dependencies. Single-source vulnerability in East Asian foundry capacity exposes the supply chain to geopolitical disruption and allocation rationing. Distribution runs through direct OEM relationships for fleet deployments and electrical contractor networks for residential installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
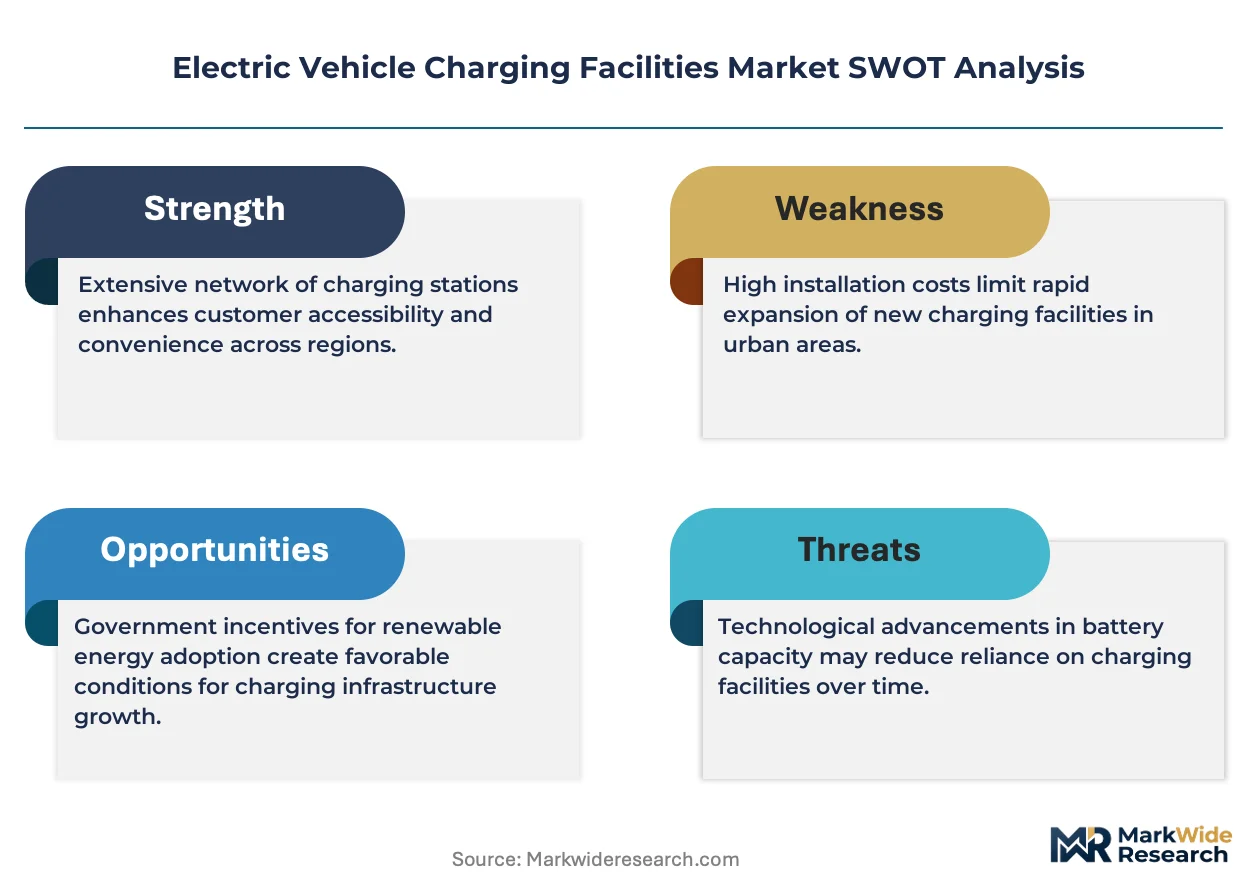
Incumbent charging infrastructure providers face substitution pressure from cloud-native charge point operators leveraging network effects to displace hardware-centric business models. Hydrogen fuel cell corridor development and battery swapping networks for commercial fleets represent credible alternative energy replenishment architectures demanding defensive positioning.
For Market Incumbents: Harden proprietary network control through backward integration into power semiconductor sourcing and captive silicon carbide supply agreements. Secure journeyman electrician training pipelines in California, Texas, and Germany's industrial regions to defend installation capacity against workforce scarcity. Deepen software-defined charging management platforms to create switching costs against cloud-native entrants.
For New Entrants and Emerging Players: Build out apartment and condominium retrofit infrastructure requiring load-sharing hardware and submetering solutions, the most penetrable installation category underserved by incumbent scale. Target India's Maharashtra and Gujarat industrial corridors where PLI scheme incentives for advanced chemistry cell manufacturing create downstream charging demand without entrenched competitor presence. Pursue guaranteed uptime contracting structures with municipal transit agencies favoring single-accountability vendors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across DC fast charging deployments as 350kW capability requirements elevate power electronics and thermal management investment thresholds. Viable acquisition targets include software-defined charging management platforms and thermal management specialists redesigning around CO2-based refrigeration cycles. Monitor silicon carbide supply allocation announcements from East Asian foundries as inflection indicators for charger manufacturer margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive silicon carbide supply secures allocation priority amid East Asian foundry undercapacity. |
| Cloud-Native Charging Management Platform Development | Virtualized network operations compress capital requirements for scaling across dispersed asset bases. |
| Workforce Pipeline Investment in Licensed Electrician Training | Journeyman certification programs in California and Texas address critical-path installation delays. |
| Vehicle-to-Grid Integration Capability Buildout | Bidirectional charging convergence with distributed energy resource management opens recurring utility revenue streams. |
| CO2-Based Thermal Management System Redesign | Compliance with EU F-Gas Regulation 2027 prohibitions maintains power density in high-power equipment. |
Research Methodology
A standing panel of charge point operators, fleet procurement directors, utility interconnection planners, and power electronics procurement managers provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FERC filings, EIA infrastructure deployment data, MIIT policy circulars, and EU Alternative Fuels Infrastructure Regulation implementation reports. Bottom-up installation database construction triangulated against top-down subsidy allocation tracking across the US Inflation Reduction Act, China's dual carbon mandate provincial targets, and India's PLI scheme disbursements.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated fleet electrification pathways without specifying discrete year markers. Segmentation dimensions modeled span charging power tier, installation ownership archetype, end-user sophistication level, and regional regulatory framework cluster. CAGRs derived from compound growth trajectory analysis applied to hardware unit shipments and service revenue streams. Forecast inputs incorporated grid interconnection queue duration assumptions, transformer lead time trajectories, and silicon carbide supply expansion announcements.
Stress conditions across utility capacity allocation rejection rates, power semiconductor supply rationing severity, and licensed electrician workforce growth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy program continuity, interoperability standard adoption timelines, and battery electric vehicle platform voltage architecture evolution. Macroeconomic contraction, regulatory rollback, or breakthrough wireless charging commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market