
 Liquid Ring Compressors Market | 2026-2036
Liquid Ring Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Ring Compressors Market Foresight
EPA emissions standards for industrial process equipment is shifting the cost-of-entry calculus for compressor OEMs serving North American chemical plants. Flowserve Corporation leverages its aftermarket service network to sustain recurring revenue from installed base upgrades. DEKKER Vacuum Technologies anchors its position through specialized engineering for corrosive gas handling applications. Busch Vacuum Solutions competes on energy efficiency ratings across its liquid ring portfolio.
Liquid ring compressors are positive displacement machines that use a rotating impeller and a ring of service liquid—typically water or oil—to form compression chambers; operating vacuum levels commonly range from 33 to 1013 mbar absolute. These systems handle wet, saturated, or particulate-laden gas streams where dry compressors would fail, making them essential for chemical processing and wastewater treatment operations. Single acting configurations dominate unit shipments due to lower capital outlay, while double acting designs command premium positioning in continuous-duty petrochemical applications. Vacuum technology applications in pharmaceutical freeze-drying are expanding fastest, though from a smaller installed base.
The EPA enforces emissions thresholds that shape compressor sealing requirements and liquid sealant specifications in U.S. process industries. EMA and REACH frameworks in Europe impose material compliance obligations on manufacturers exporting into EU pharmaceutical and chemical markets. Stakeholders must monitor regulatory divergence between jurisdictions to determine where certification investments yield preferred supplier status.
Market Dynamics
Stricter EPA emissions standards are compressing allowable tolerance bands for industrial vacuum systems, forcing chemical processors to retire legacy equipment ahead of depreciation schedules. This regulatory pressure is redirecting capital toward sealed-system liquid ring compressors that eliminate fugitive emissions at the sealing interface.
Growth Catalysts
- Chemical Processing Expansion:Rising adoption in chemical processing facilities is strengthening order pipelines for corrosion-resistant liquid ring systems. Petrochemical clusters in the US Gulf Coast and Germany's Ruhr region are replacing dry compressors with liquid ring technology for wet gas handling.
- REACH Material Compliance:EMA and REACH frameworks in Europe impose material compliance obligations on manufacturers exporting into EU pharmaceutical markets. Compliance investments yield preferred supplier status for compressor OEMs serving freeze-drying applications.
- Wastewater Treatment Mandates:Municipal wastewater treatment operations are deploying liquid ring compressors for biogas recovery and vacuum filtration. These systems tolerate saturated gas streams where dry alternatives would fail.
Market Restraints
- Service Liquid Consumption:Continuous water or oil consumption elevates operating costs versus dry screw or centrifugal alternatives. Water-scarce regions impose additional treatment and disposal burdens on operators.
- Energy Efficiency Gap:Liquid ring compressors exhibit lower isentropic efficiency than dry technologies at equivalent pressure ratios. Energy-intensive continuous-duty applications face total-cost-of-ownership disadvantages.
- Speed Limitations:Rotor tip speed constraints restrict maximum capacity per unit frame size. Large-scale applications require multiple machines or alternative technologies.
Strategic Opportunities
- Pharmaceutical Freeze-Drying:Vacuum technology applications in pharmaceutical freeze-drying are expanding fastest from a smaller installed base. Specialized engineering for sterile process environments commands premium positioning.
- Aftermarket Service Networks:Process engineering clusters in Germany anchor aftermarket service revenue through predictive maintenance contracts. Remote monitoring integration creates recurring revenue streams from installed base upgrades.
- Corrosive Gas Specialization:Hydrogen sulfide and chlorine handling in chemical processing requires metallurgical expertise that generalist compressor manufacturers lack. Specialized engineering capabilities create defendable market positions.
Industry Challenges
- Sealing System Expertise:Tighter EPA tolerance bands demand precision machining and assembly capabilities that exceed traditional pump manufacturing skill bases. Workforce development lags regulatory escalation.
- Legacy System Integration:Retrofit installations must interface with existing distributed control systems and process safety architectures. Custom engineering extends delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Ring Compressors Market |
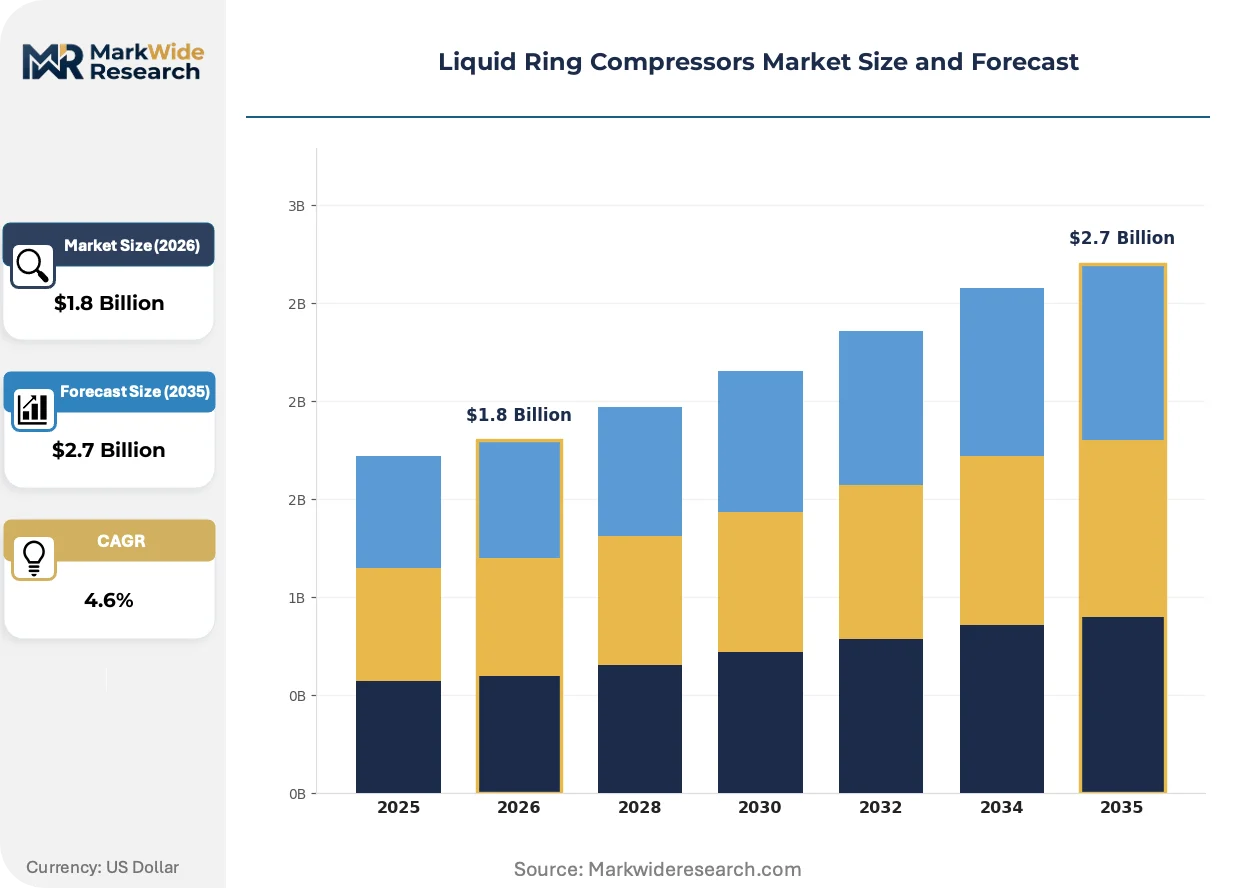
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Positive Displacement, Vacuum Application: Chemical Processing, Wastewater Treatment, Oil & Gas, Food & Beverage End User: Manufacturing, Energy, HVAC, Pharmaceuticals Technology: Electric, Gas, Hybrid, Steam |
| Companies Covered | Flowserve Corporation, DEKKER Vacuum Technologies, Busch Vacuum Solutions, Sulzer, Graham Corporation, Atlas Copco, Gardner Denver, OMEL, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Ring Compressors Market Shifts & Advancements
Digital instrumentation and predictive analytics are penetrating liquid ring compressor installations, converting mechanical assets into data-generating nodes. Equipment suppliers are repositioning around uptime guarantees rather than unit sales.
Magnetic bearing technology is integrating into high-speed liquid ring compressor drives, eliminating mechanical seal wear and extending maintenance intervals. Pharmaceutical manufacturers in Switzerland and Germany are adopting these systems for continuous-duty freeze-drying operations. The technology is integrating sealed-system reliability with dry compressor energy efficiency, compressing the historical trade-off between the two architectures.
EPA enforcement of emissions thresholds is reshaping compressor sealing requirements and liquid sealant specifications in US process industries. Chemical plants in Louisiana and Texas are upgrading to closed-loop sealant systems ahead of inspection cycles. Petrochemical applications face the steepest compliance costs, driving consolidation toward suppliers with pre-certified platform designs.
Service contract unbundling is fragmenting traditional procurement relationships in the chemical processing sector. End-users are separating equipment purchase from maintenance obligations, forcing OEMs to compete on lifecycle cost transparency. This pattern is most visible in Germany, where process engineering clusters have cultivated independent service providers with specialized metallurgical repair capabilities.
Liquid Ring Compressors Market Segmentation
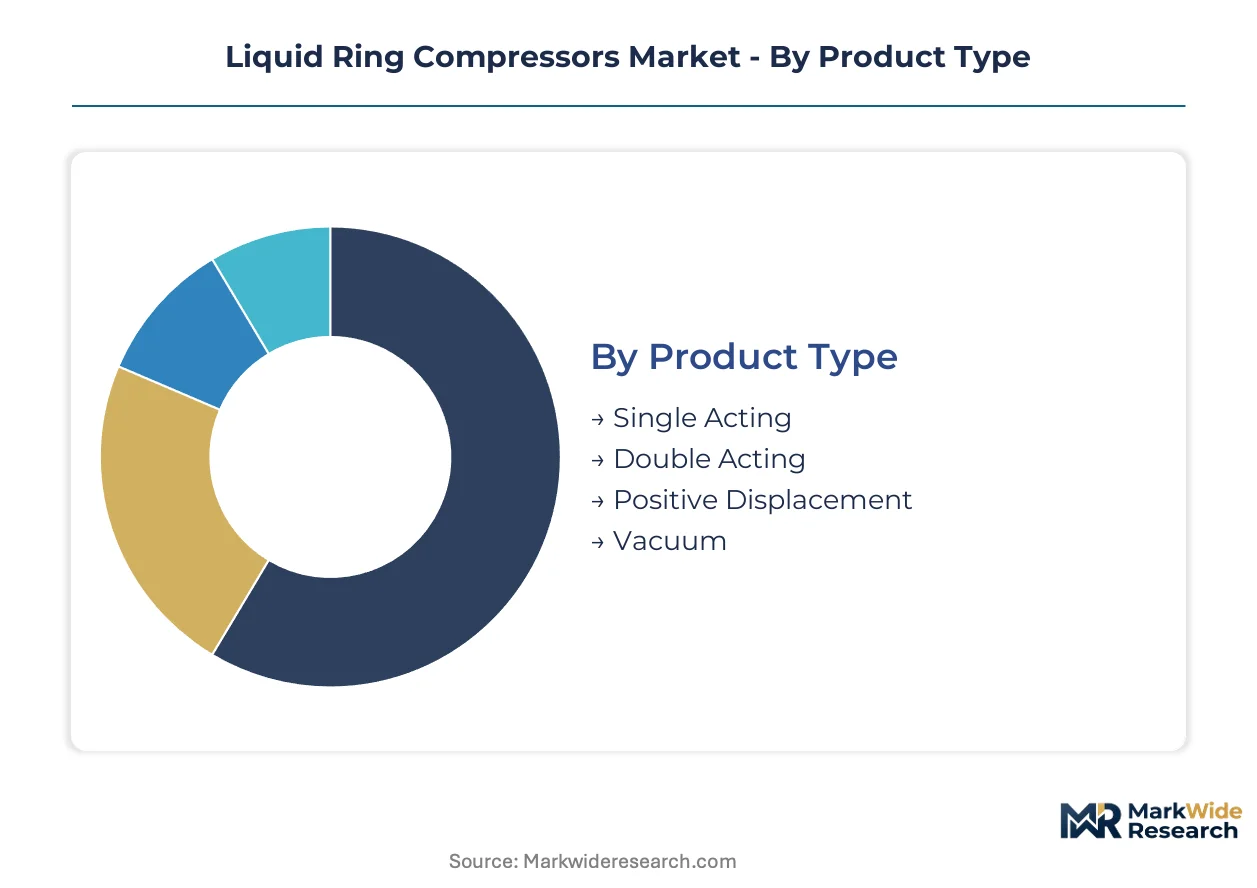
Liquid ring compressor procurement varies sharply by operational intensity and regulatory exposure. Buyers in chemical processing prioritize corrosion-resistant configurations, while pharmaceutical end-users demand sterile-system compliance. Understanding segment boundaries clarifies where engineering customization commands premium pricing versus standardized unit sales.
Product Type:
Standardized single-acting units dominate high-volume shipments, yet double-acting designs anchor project engineering margins through customization intensity.
- Single Acting:One compression cycle per impeller revolution using a single set of ports. Chemical processors in Germany's Ruhr region specify these for intermittent vacuum duty where capital constraints outweigh efficiency concerns.
- Double Acting:Compression occurs on both sides of the impeller hub, nearly doubling displacement per revolution. Continuous-duty petrochemical applications in the US Gulf Coast favor these despite higher upfront costs, driven by EPA emissions tolerance bands that penalize unplanned downtime.
- Positive Displacement:Sealed-chamber geometry ensures consistent volumetric efficiency across pressure ranges.
- Vacuum:Specialized porting achieves deep vacuum levels for freeze-drying and degassing operations.
Leading the category by volume: Single Acting. Expanding most quickly: Double Acting.
Application:
Process severity and gas stream composition determine specification intensity across end-use environments.
- Chemical Processing:Wet, saturated, and particulate-laden gas streams demand liquid ring tolerance where dry compressors fail. Hydrogen sulfide handling in Louisiana refineries requires metallurgical upgrades that generalist suppliers cannot deliver.
- Wastewater Treatment:Biogas recovery and vacuum filtration operations deploy these systems for saturated stream compatibility. Municipal operators in water-scarce regions face elevated sealant treatment costs that compress total-cost-of-ownership advantages.
- Oil & Gas:Upstream and midstream vapor recovery applications favor robust sealing systems.
- Food & Beverage:Aseptic processing requirements drive stainless steel construction and FDA-compliant sealant specifications.
Highest specification intensity: Chemical Processing. Steepest expansion trajectory: Wastewater Treatment.
End User:
Capital deployment cycles and maintenance sophistication fragment procurement behavior across buyer categories.
- Manufacturing:General industrial vacuum applications span packaging, degassing, and materials handling. Process engineering clusters in Germany anchor aftermarket service revenue through predictive maintenance contracts and remote monitoring integration.
- Energy:Power generation and renewable fuel processing require continuous-duty reliability.
- HVAC:Building systems prioritize acoustic performance and compact footprint over process tolerance.
- Pharmaceuticals:Sterile process environments in Swiss and German freeze-drying facilities command premium positioning for sealed-system designs with magnetic bearing integration.
Deepest installed base: Manufacturing. Gaining share fastest: Pharmaceuticals.
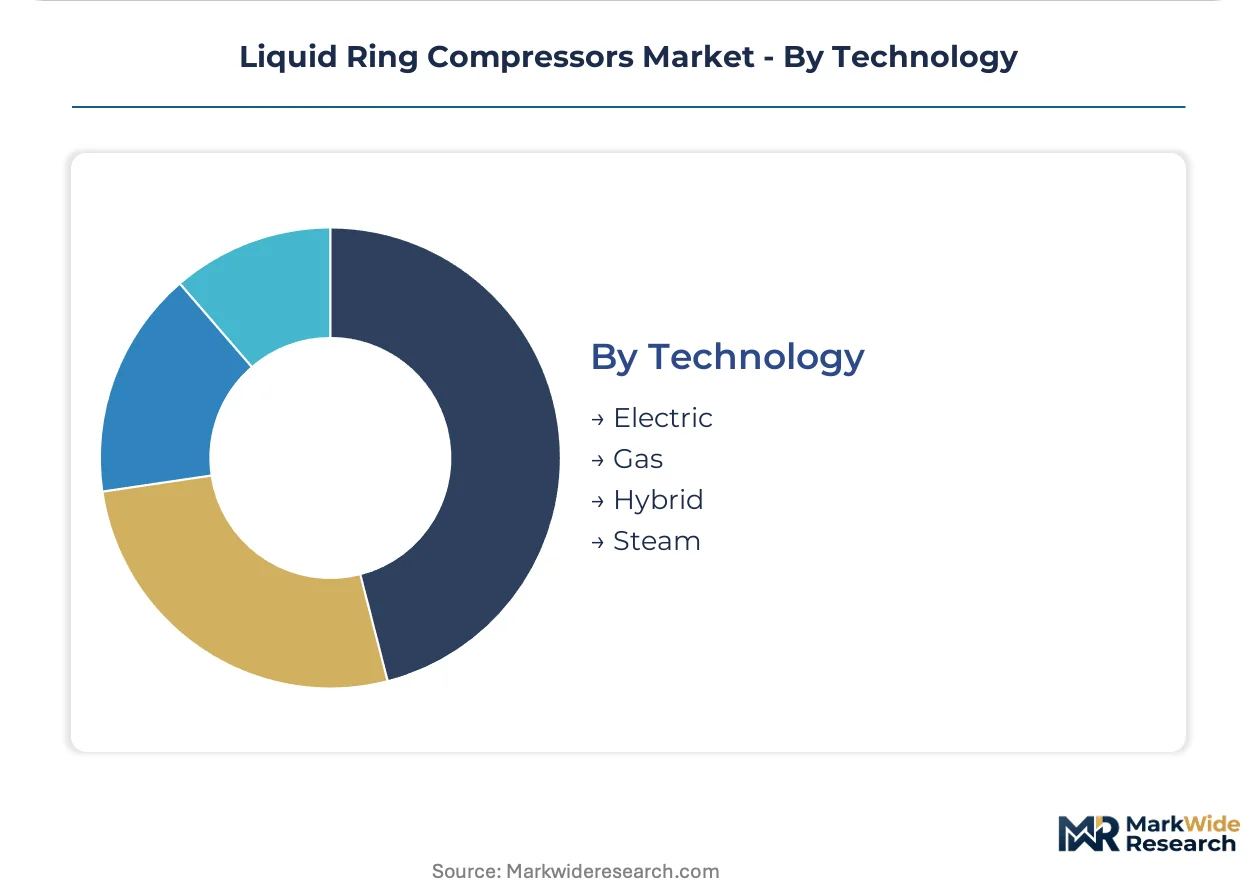
Technology:
Drive system selection reflects site infrastructure availability and operating cost accounting horizons.
- Electric:Grid-connected motors dominate new installations where energy efficiency ratings determine procurement scoring. Busch Vacuum Solutions competes on efficiency metrics across this portfolio segment.
- Gas:On-site fuel availability drives adoption in remote oil and gas production facilities.
- Hybrid:Dual-fuel flexibility addresses grid reliability concerns in process-critical applications.
- Steam:Cogeneration integration recovers waste heat for compression energy in integrated chemical complexes.
Dominant technology by unit volume: Electric. Climbing fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the US Gulf Coast and Germany's Ruhr region concentrate liquid ring compressor demand through petrochemical clustering and process engineering density.
United States
Petrochemical expansions in Louisiana and Texas drive replacement cycles for corrosion-resistant systems. EPA emissions thresholds force Gulf Coast processors toward sealed-system designs ahead of inspection windows. Houston anchors aftermarket service revenue through predictive maintenance contracts with chemical majors.
Germany
Process engineering clusters in North Rhine-Westphalia sustain equipment upgrade demand from chemical and pharmaceutical sectors. REACH material compliance obligations shape procurement scoring for freeze-drying applications. The Ruhr region's metallurgical repair capabilities fragment traditional OEM service relationships.
China
Coal chemical and shale gas processing expansions in Shandong and Sichuan provinces absorb medium-duty liquid ring capacity. The country's national environmental regulator tightens fugitive emissions standards for industrial vacuum equipment. Yangtze River Delta chemical parks favor domestic fabricators with rapid spare parts availability.
India
Specialty chemical investments in Gujarat and Maharashtra generate demand for wet gas handling systems. The Bureau of Indian Standards mandates material certifications for pressure equipment in hazardous processes. Mumbai-Pune industrial corridor operators prioritize total-cost-of-ownership over capital outlay in compressor selection.
Switzerland
Pharmaceutical freeze-drying facilities in Basel and Zurich command premium positioning for sealed-system designs. Swissmedic sterile process requirements drive magnetic bearing adoption for continuous-duty reliability. The country's precision manufacturing base supplies specialized components to German and French OEMs.
Liquid Ring Compressors Market Competitive Landscape
German producers anchor one tier; US Gulf Coast specialists hold project engineering margins through corrosion-resistant configurations. The vendor base stratifies across three tiers: diversified fluid handling conglomerates, vacuum technology pure-plays, and regional fabrication shops serving maintenance budgets. Strategic archetypes include aftermarket service integrators, metallurgical specialists for hydrogen sulfide duty, and energy efficiency rating leaders. Consolidation pressures concentrate around pre-certified platform designs that accelerate EPA compliance timelines.
Within the diversified industrial tier, Flowserve Corporation and Ingersoll Rand exemplify scale-driven positions spanning multiple compression technologies. DEKKER Vacuum Technologies occupies a specialist niche anchored in corrosive gas handling engineering. These three represent contrasting strategic postures: conglomerate breadth versus focused metallurgical expertise versus integrated service networks.
| Leading Market Players |
|---|
| Flowserve Corporation |
| DEKKER Vacuum Technologies |
| Busch Vacuum Solutions |
| Sulzer |
| Graham Corporation |
| Atlas Copco |
| Gardner Denver |
| OMEL |
| Ingersoll Rand |
| Others |
Supply & Pricing Matrix
Stainless steel alloy costs cascade through three-tier pricing structures across premium, standard, and economy levels, with specialty duplex grades commanding 40-60% markups over 316L standard configurations. German Ruhr region fabricators pass through nickel price volatility to petrochemical buyers under index-linked contracts, while Chinese Yangtze Delta producers absorb input fluctuations to maintain share in wastewater treatment tenders.
Pricing Analysis
Short lead-time premiums of 15-25% separate expedited double-acting units from standard-cycle single-acting configurations, with spot inventory discounts of 8-12% clearing obsolete frame sizes. Project-based pricing dominates chemical processing procurement, where EPA pre-certified platforms command quality-grade premiums over uncertified alternatives. Cost compression in economy-tier standardized units is intensifying because Indian domestic fabricators are flooding municipal wastewater segments with undifferentiated capacity. Pharmaceutical freeze-drying buyers exhibit least price sensitivity, prioritizing magnetic bearing reliability over capital outlay optimization.
Supply Chain Analysis
India's Bureau of Indian Standards localization mandates are reshaping sourcing patterns for pressure-bearing castings, forcing European OEMs to qualify secondary foundries in Gujarat and Maharashtra. Manufacturing gravity centers on Germany, China, and India, with precision-machined impellers drawing from Swiss and Japanese specialty tooling suppliers. Supply chain risk concentrates in single-source vulnerability for magnetic bearing assemblies, where two German producers control 70% of pharmaceutical-grade output. Distribution runs through authorized service networks in process engineering clusters rather than direct OEM-to-end-user transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgical repair capacity acts as the binding constraint propping aftermarket service pricing, with German Ruhr region technician scarcity extending predictive maintenance contract premiums.
For Market Incumbents: Acquire distressed aftermarket service networks in North Rhine-Westphalia to lock in predictive maintenance revenue streams before independent metallurgical specialists consolidate. Dry screw compressor OEMs are entering liquid ring niches through acquisition; preempt this threat by backward integration into magnetic bearing component supply. EPA pre-certification investments create switching costs that defend installed base positions in Louisiana and Texas chemical corridors. For New Entrants and Emerging Players: Magnetic bearing retrofit kits for legacy frame sizes offer technology-first entry into Swiss and German pharmaceutical freeze-drying upgrade cycles, bypassing capital-intensive new equipment manufacturing. Municipal wastewater biogas recovery in water-scarce Indian states represents the most penetrable white-space target, with lowest incumbent service density and tolerance for non-European certification. Go-to-market execution should anchor on total-cost-of-ownership modeling that quantifies sealant treatment savings against dry compressor alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive duplex stainless casting capabilities in Germany's Ruhr region, where foundry consolidation is creating acquisition opportunities below replacement cost. Long-term viability hinges on exposure to pharmaceutical freeze-drying rather than commodity chemical processing, given regulatory escalation favoring sealed-system reliability. Watch magnetic bearing adoption rates in Swissmedic-inspected facilities as the inflection signal separating premium-positioned from commodity-compressed returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Casting | Captive metallurgical capability defends margin against nickel price volatility in corrosive gas applications. |
| Magnetic Bearing Platform Launch | Swissmedic-qualifying sealed-system designs command pharmaceutical pricing premiums over mechanical seal alternatives. |
| Predictive Maintenance Network Acquisition | Ruhr region service density locks in recurring revenue from German chemical processing installed base. |
| EPA Pre-Certification Investment | Accelerated compliance timelines capture replacement cycles ahead of Gulf Coast inspection windows. |
| Joint Venture with Indian Fabricators | BIS-compliant local production accesses municipal wastewater tenders with domestic-content preferences. |
Research Methodology
Multi-period observation of order backlog durations, EPA certification filing timelines, and aftermarket service contract renewal rates anchored the trend analysis, supplemented by interviews with plant engineers at US Gulf Coast petrochemical facilities, procurement leads at German pharmaceutical OEMs, maintenance directors in Indian specialty chemical complexes, and aftermarket service heads in North Rhine-Westphalia. Secondary validation drew from EPA enforcement action databases, ECHA REACH substance registration records, BIS pressure equipment certification listings, and customs trade flow data for compressor components. Bottom-up unit shipment estimates triangulated against top-down capital expenditure tracking across chemical processing and wastewater treatment verticals.
Input-output matrices mapped compression capacity installations to downstream process unit expansions across the projection horizon, with segmentation dimensions spanning product architecture (single-acting versus double-acting), application severity (chemical processing, pharmaceutical, wastewater), and technology type (electric, hybrid, steam). CAGRs were derived from curve-fitting observed replacement cycles against regulatory compliance deadlines and announced capacity additions. Industry-specific forecast inputs included EPA inspection cycle phasing, EMA material compliance revision schedules, and municipal wastewater treatment investment pipelines in water-stressed jurisdictions.
Several conditions sit outside the modeled scope, including breakthrough dry compressor technologies achieving liquid-ring-equivalent wet gas tolerance, abrupt EPA enforcement discontinuities, and trade policy disruptions affecting German-Indian component flows. Forecasts reflect documented assumptions about regulatory trajectory continuity and specialty alloy price band stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Bus Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Root Blower Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Booster Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Scroll Compressor Market
Compressors
Middle East and Africa Booster Compressor Market