
 North America Centrifugal Compressor Market | 2026-2036
North America Centrifugal Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Centrifugal Compressor Market Analytics
Carbon fiber reinforced polymer is consolidating its position in centrifugal compressor impeller manufacturing as OEMs seek weight reduction and corrosion resistance. Atlas Copco Ltd leverages integrated drive train technology to anchor its position in the oil-free segment. Siemens Energy competes through advanced magnetic bearing systems, while Ingersoll Rand plc sustains broad manufacturing scale across the North American installed base.
A centrifugal compressor accelerates gas through a rotating impeller, converting kinetic energy into pressure via a diffuser section; operating speeds frequently exceed 20,000 RPM with pressure ratios ranging from 3:1 to 8:1 in industrial process service. Oil-free product types command premium positioning where process contamination risks dominate buyer specifications, particularly in chemical processing and food-grade applications. Variable speed drive technology leads technology adoption as end users prioritize energy recovery across power generation and HVAC installations.
EPA emissions standards and OSHA process safety management requirements shape compressor specification and maintenance protocols across U.S. petrochemical and natural gas processing facilities. The Department of Energy appliance efficiency rules influence HVAC end-user procurement criteria, while Canadian Standards Association certification governs cross-border equipment acceptance. Stakeholders must monitor evolving methane intensity regulations and assess magnetic bearing reliability claims against total lifecycle cost models.
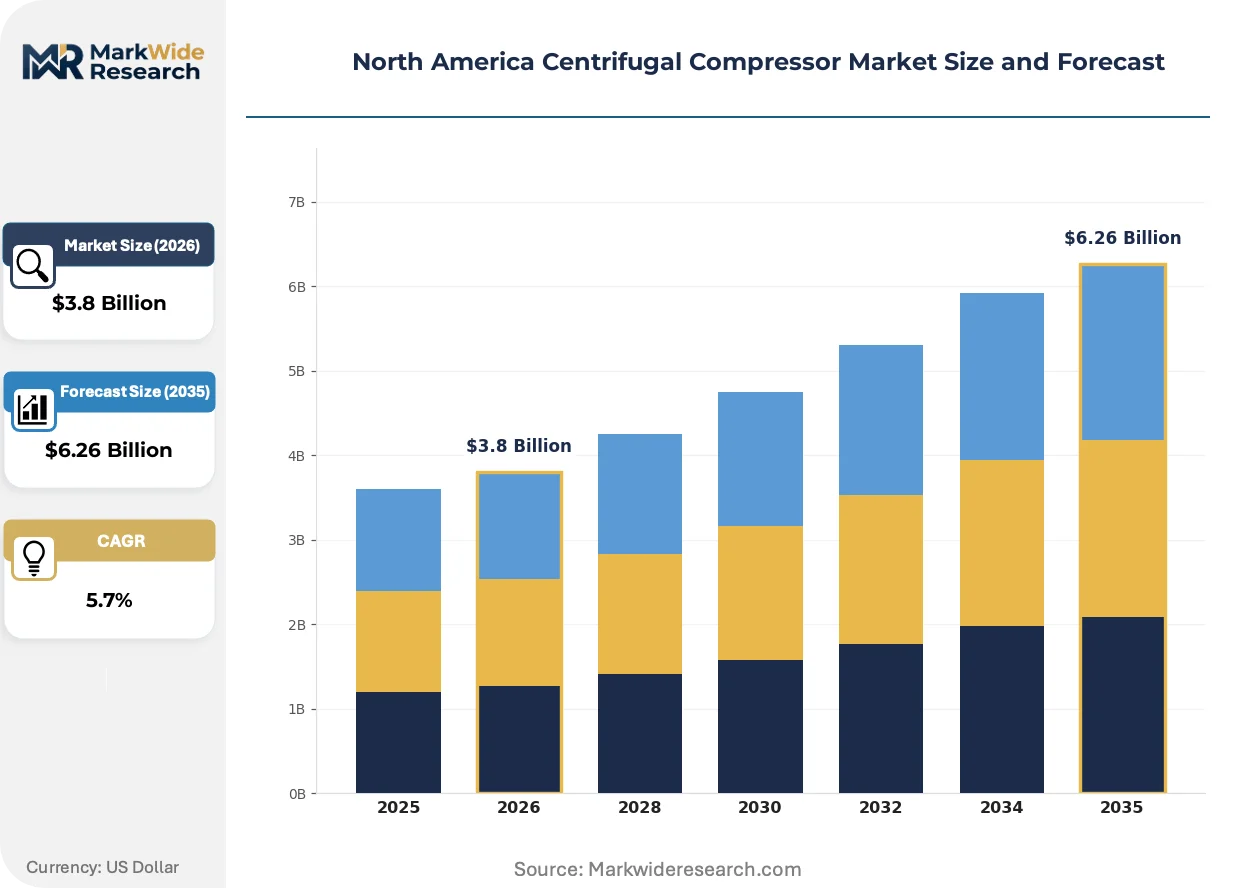
Market Dynamics
Magnetic bearing systems are compressing maintenance intervals and eliminating lubricant contamination risks across Texas Gulf Coast petrochemical clusters, forcing incumbent OEMs to reprice service contracts and retrofit offerings.
Growth Catalysts
- EPA methane intensity rules:Oil-free compressor architectures satisfy leak detection and repair mandates across natural gas processing facilities in Louisiana and Texas.
- Carbon fiber impeller adoption:Weight reduction and corrosion resistance properties extend equipment life in sour gas service along the Alberta oil sands corridor.
- HVAC electrification codes:Variable speed drive integration meets Department of Energy appliance efficiency standards in commercial building retrofits across California and New York.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for high-speed motors creates input cost volatility tied to Chinese export quotas.
- Magnetic bearing technical limitation:Load capacity ceilings restrict deployment in ultra-high-pressure synthesis loops above 100 bar discharge pressure.
- OSHA process safety management:Documentation and audit requirements extend commissioning timelines for new installations in chemical processing facilities.
Strategic Opportunities
- Hydrogen compression white space:Polymer electrolyte membrane electrolyzer integration creates demand for contaminant-free compression in Gulf Coast hydrogen hubs.
- Canadian carbon capture incentives:Investment tax credits under the federal budget accelerate amine-based capture system deployment requiring specialized CO2 compression.
- Digital twin convergence:Physics-based modeling combined with vibration sensor networks enables predictive maintenance contracts displacing scheduled overhauls.
Industry Challenges
- Magnetic bearing specialist scarcity:Electromechanical control system expertise gaps delay field commissioning teams in Permian Basin service territories.
- API 617 certification timelines:Third-party validation for high-speed integrally geared designs extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Centrifugal Compressor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-injected, Oil-free, Water-injected, Magnetic Bearing Application: Natural Gas Processing, Chemical Processing, Power Generation, Industrial Refrigeration End User: Mining, Manufacturing, Petrochemical, HVAC Technology: Variable Speed Drive, Direct Drive, Fixed Speed, Integrative Control |
| Companies Covered | Hitachi Ltd, Kaeser Compressors Inc, Atlas Copco Ltd, Siemens Energy, Bauer Compressors Inc, Ingersoll Rand plc, Gardner Denver Holdings Inc, FS-Elliott Co LLC, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Centrifugal Compressor Market Evolving Landscape
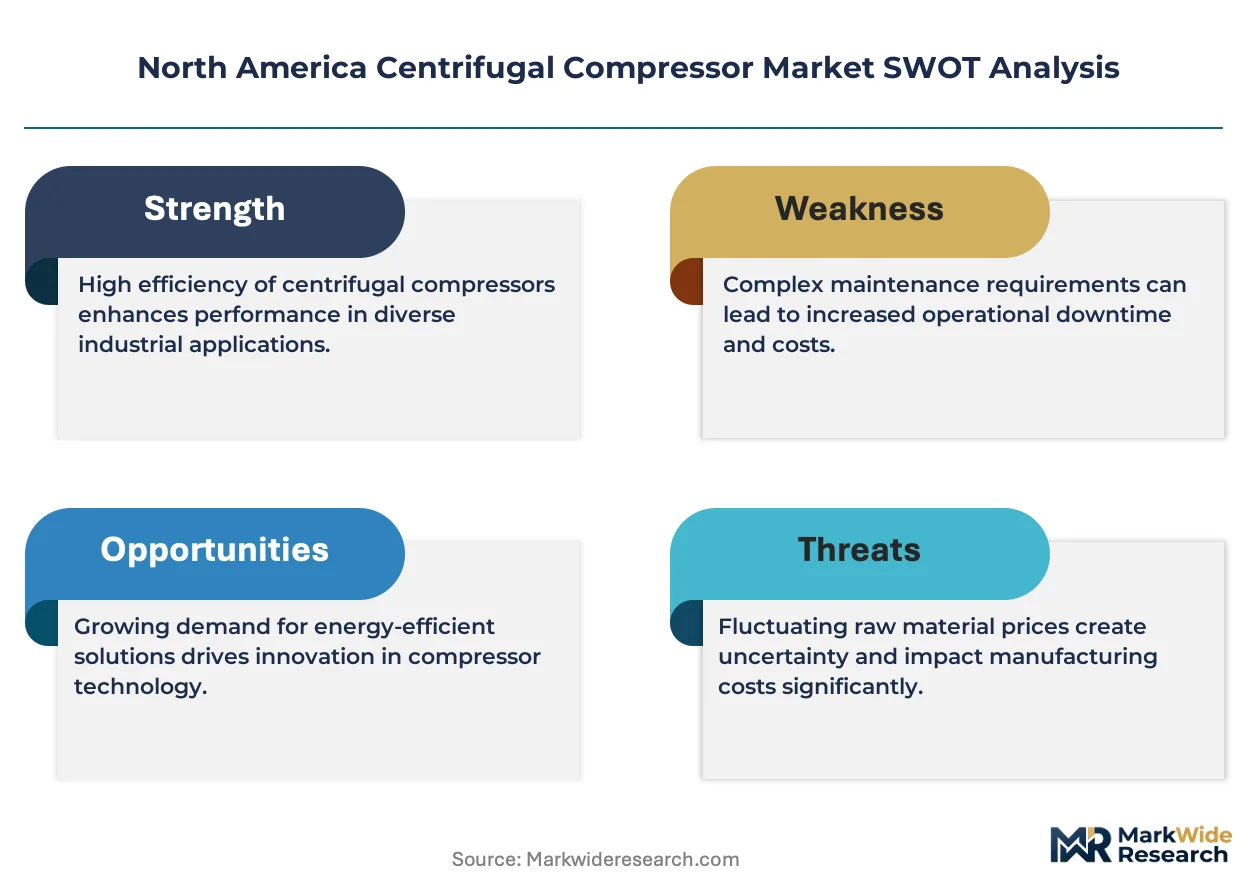
Electrification of drive systems and digitalization of asset management are restructuring how operators procure, operate, and maintain compression assets across North American industrial corridors.
High-speed permanent magnet motors paired with active magnetic bearings are electrifying the drive train architecture for centrifugal compressors above 5 MW. Petrochemical operators in Texas and Louisiana are specifying these packages for ethylene cracker charge gas service. The elimination of gearbox losses and lubrication systems is compressing energy consumption benchmarks and reshaping supplier qualification criteria.
EPA's updated methane performance standards for new and modified sources are tightening leak detection protocols across natural gas transmission and storage facilities. Compressor packagers must now integrate continuous emissions monitoring hardware into skid designs. The Permian Basin and Appalachian shale plays face the steepest compliance ramps, driving specification changes for seal systems and vent capture.
Performance-based service agreements are displacing time-and-material maintenance contracts among power generation and industrial gas buyers. Operators in the US Northeast and Ontario are unbundling compression assets from capital budgets, transferring availability risk to OEM service arms. Channel restructuring favors factory-trained technicians over independent service contractors for magnetic bearing diagnostics and rotor balancing.
North America Centrifugal Compressor Market Segmentation
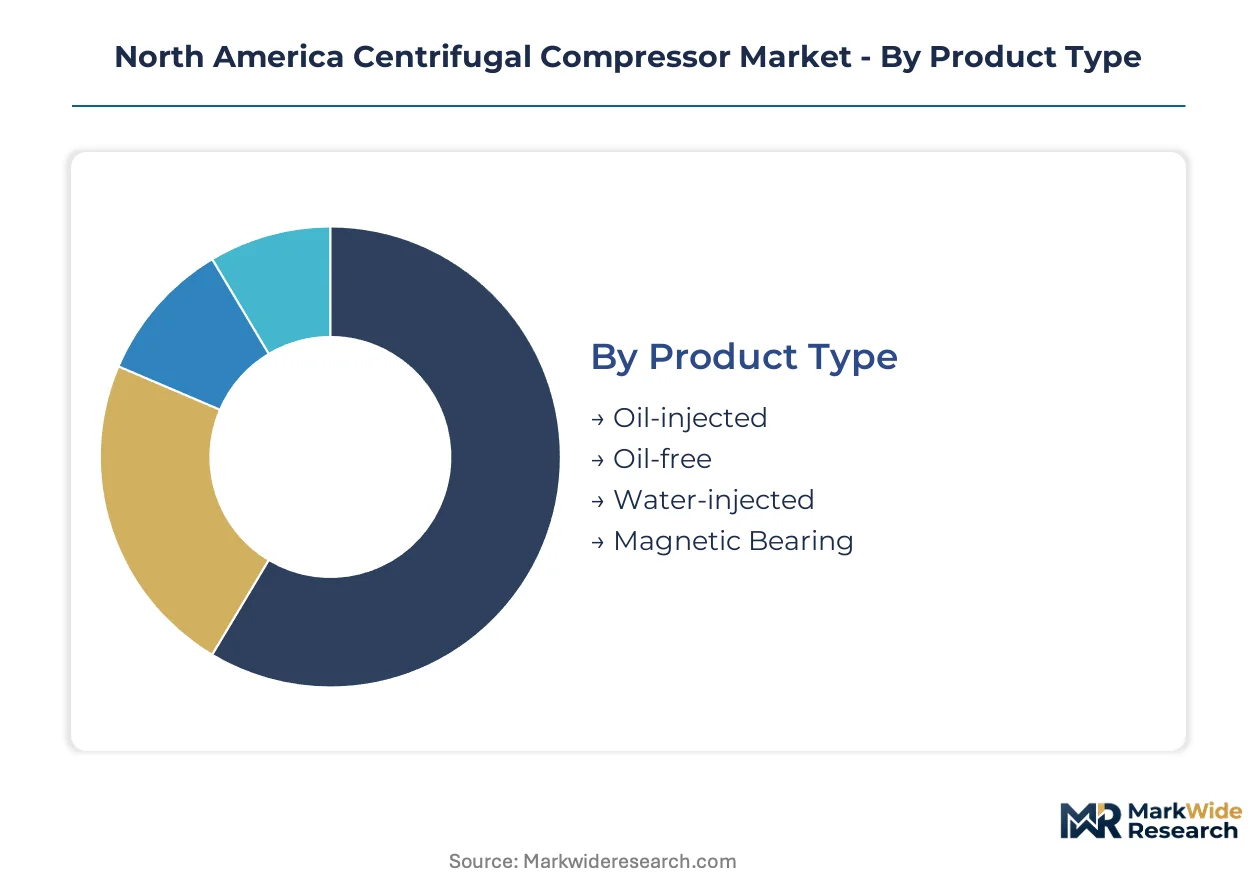
Centrifugal compressor procurement patterns diverge sharply between high-volume commodity applications and premium-specification process environments. Buyers segment specifications across product architecture, duty cycle, and contamination risk tolerance rather than treating compression as a uniform capital purchase.
Product Type:
Oil-free architectures command premium positioning in contamination-sensitive process streams, while oil-injected systems dominate high-volume industrial applications where lubricant carryover poses minimal risk.
- Oil-injected:Lubricated bearing and seal systems enable higher pressure ratios and simpler maintenance protocols in general manufacturing and mining applications. Demand concentrates across Great Lakes automotive stamping plants and Rocky Mountain mining operations where process gas purity requirements remain minimal and capital constraints dominate procurement criteria.
- Oil-free:Dry-running impeller and seal designs eliminate hydrocarbon contamination in chemical synthesis and food-grade gas streams. Texas Gulf Coast petrochemical clusters and California pharmaceutical manufacturing facilities specify these architectures to satisfy EPA leak detection mandates and FDA process validation requirements.
- Water-injected:Liquid ring compression provides intermediate contamination control for specialty chemical applications.
- Magnetic Bearing:Active magnetic levitation eliminates mechanical contact and lubrication entirely for ultra-high-speed duty.
Mature deployment sits with oil-injected compressors across bulk industrial gas applications. Newer deployment is concentrated in magnetic bearing systems for ethylene cracker charge gas service.
Application:
Process intensity and gas composition dictate specification complexity across end-use environments.
- Natural Gas Processing:Multi-stage compression trains handle inlet pressures from wellhead gathering through pipeline transmission specifications. Louisiana and Texas processing facilities deploy these systems for acid gas removal and dew point control, with EPA methane performance standards driving continuous emissions monitoring integration into skid designs.
- Chemical Processing:Synthesis gas and refrigerant compression demand materials compatibility with corrosive process streams. Alberta oil sands upgraders and Appalachian shale chemical complexes specify sour gas-resistant impeller alloys and seal systems.
- Power Generation:Combustion turbine fuel gas compression and combined cycle plant auxiliary services require rapid load-following capability.
- Industrial Refrigeration:Ammonia and CO2 compression for cold chain infrastructure operates at lower pressure ratios with specialized safety protocols.
Natural gas processing anchors current installed base volume. Chemical processing applications are expanding most quickly as shale-derived feedstock availability reshapes North American petrochemical capacity.
End User:
Capital intensity and operating regime separate continuous-process buyers from intermittent-duty procurement patterns.
- Petrochemical:Ethylene, propylene, and derivatives production requires 24/7 compression availability with 5-7 year turnaround cycles. Texas and Louisiana crackers specify API 617-compliant integrally geared designs with magnetic bearing options to minimize unplanned shutdown costs.
- HVAC:Commercial building chiller systems and district cooling networks prioritize part-load efficiency through variable speed integration. New York and California electrification codes are accelerating replacement of fixed-speed legacy equipment.
- Manufacturing:General industrial air and nitrogen supply spans fragmented demand across automotive, metal fabrication, and electronics assembly.
- Mining:Underground ventilation and mineral processing pneumatic systems operate in harsh ambient conditions with remote maintenance access.
Petrochemical end users concentrate premium specification demand. HVAC represents the steepest expansion trajectory as building electrification mandates reshape replacement cycles.
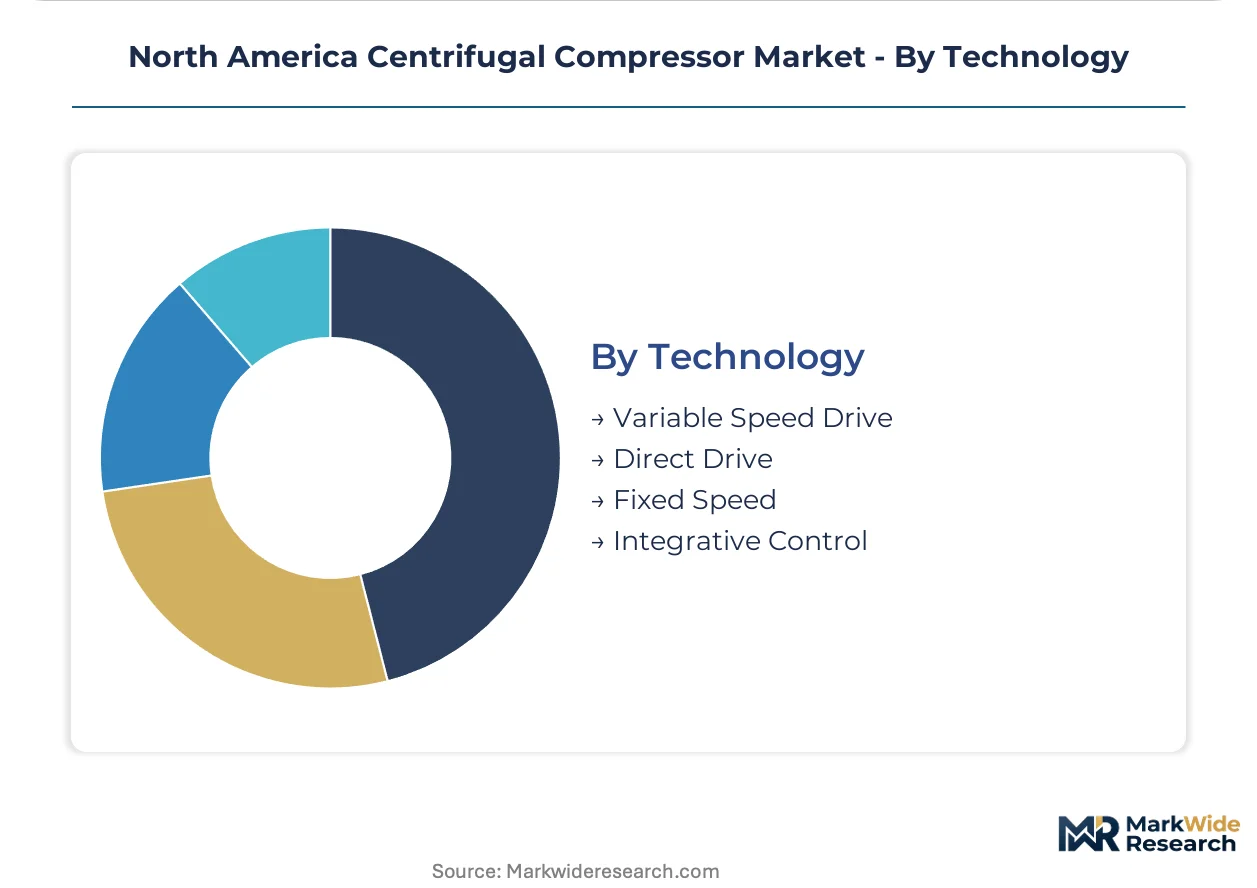
Technology:
Drive train architecture determines energy recovery potential and control precision across varying load profiles.
- Variable Speed Drive:Frequency-controlled permanent magnet motors match compressor output to instantaneous demand, eliminating throttling losses. Department of Energy efficiency standards are mandating VSD integration in new commercial and light industrial installations across California and the Northeast.
- Direct Drive:High-speed motors eliminate gearbox maintenance and efficiency losses in large process train applications. Texas ethylene producers are specifying direct drive magnetic bearing packages above 10 MW to compress energy benchmarks.
- Fixed Speed:Constant-speed induction motors with inlet guide vane or discharge valve control persist in legacy installations.
- Integrative Control:Unified compressor, motor, and process control architectures optimize system-level efficiency.
Fixed speed technology dominates legacy installed base. Variable speed drive adoption is climbing the fastest as electricity costs and efficiency regulations tighten procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor anchors North American centrifugal compressor demand through concentrated ethylene cracker investments and natural gas processing infrastructure.
United States
Texas and Louisiana petrochemical clusters drive specification demand for magnetic bearing systems in ethylene cracker charge gas service. EPA methane performance standards mandate continuous emissions monitoring integration into new compressor skid designs across Permian Basin gathering facilities. Houston-area engineering firms coordinate API 617 certification programs for high-speed integrally geared designs serving Gulf Coast export terminals.
Canada
Alberta oil sands upgraders specify sour gas-resistant impeller alloys for synthesis gas compression in bitumen processing facilities. Federal investment tax credits under the carbon capture framework accelerate amine-based capture system deployment requiring specialized CO2 compression trains. Calgary-based equipment distributors coordinate cross-border certification through Canadian Standards Association protocols for US-manufactured skids.
Mexico
Nuevo León industrial parks attract petrochemical investment requiring oil-free compressor architectures for specialty chemical production. Energy regulatory reforms under the national electricity framework influence procurement criteria for combined cycle plant auxiliary compression. Monterrey manufacturing clusters source mid-pressure systems for automotive supplier pneumatic networks serving US-Mexico-Canada Agreement trade corridors.
North America Centrifugal Compressor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium process applications while regional packagers serve standard industrial duty. The vendor structure concentrates around three strategic tiers: full-line compression houses with magnetic bearing capabilities, oil-free specialists leveraging integrated drive train technology, and regional service organizations maintaining legacy installed base. Dominant competitive moves center on factory-trained technician networks displacing independent contractors and predictive maintenance contract structures transferring availability risk to OEM balance sheets.
Among diversified industrial conglomerates, Atlas Copco Ltd, Siemens Energy, and Ingersoll Rand plc exemplify contrasting archetypes within the North American installed base. Atlas Copco Ltd occupies a position aligned with oil-free segment concentration through integrated drive train offerings. Siemens Energy represents magnetic bearing system specialization for high-speed process applications. Ingersoll Rand plc anchors broad manufacturing scale across maintenance-intensive legacy equipment populations.
| Leading Market Players |
|---|
| Hitachi Ltd |
| Kaeser Compressors Inc |
| Atlas Copco Ltd |
| Siemens Energy |
| Bauer Compressors Inc |
| Ingersoll Rand plc |
| Gardner Denver Holdings Inc |
| FS-Elliott Co LLC |
| General Electric Company |
| Others |
Value Network & Pricing Analysis
Neodymium price volatility cascades through North American centrifugal compressor manufacturing, compressing margins on magnetic bearing systems while amplifying cost differentials between oil-free and conventional lubricated architectures across petrochemical procurement tiers.
Pricing Analysis
Lead-time premiums dominate transactional pricing for API 617-certified integrally geared designs, with spot inventory of standard oil-injected units trading at discounts to booked orders. Three-tier pricing structure across premium magnetic bearing packages, standard oil-free architectures, and economy oil-injected systems reflects certification grade and aftermarket bundling intensity. Cost compression in mid-tier oil-free segments is intensifying because OEMs are absorbing rare earth magnet cost spikes to defend share in Texas Gulf Coast ethylene cracker projects. HVAC end users exhibit highest price sensitivity, while petrochemical operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale petrochemical buyer demand, while regional distributors serve fragmented manufacturing and mining accounts across the Great Lakes and Rocky Mountain territories. Rare earth magnet fabrication concentrates in China, with carbon fiber prepreg supply anchored in Japan and the United States, and high-grade steel casting capacity distributed across Germany, South Korea, and domestic foundries. Active magnetic bearing controllers draw from specialized semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability around neodymium processing creates tariff exposure and quota risk. Distribution runs through factory-certified service networks displacing independent contractors for magnetic bearing diagnostics and rotor balancing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA methane performance standards and OSHA process safety management requirements erect compliance moats that favor incumbent OEMs with established certification track records and factory-trained technician networks.
For Market Incumbents: To counter magnetic bearing specialist scarcity delaying field commissioning in Permian Basin territories, anchor position through captive technician training academies and predictive maintenance contract structures that transfer availability risk to your balance sheet. Deepen backward integration into carbon fiber impeller manufacturing to secure supply continuity for sour gas-resistant designs specified across Alberta oil sands corridors. For New Entrants and Emerging Players: Launch via digital twin-enabled predictive maintenance subscriptions targeting mid-scale chemical processors in Appalachia shale chemical complexes underserved by full-line OEM service arms. Hydrogen compression white space around Gulf Coast electrolyzer integration offers the most penetrable entry point, with polymer electrolyte membrane compatibility requirements favoring contaminant-free architectures from non-incumbent suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor magnetic bearing control system specialists with stranded intellectual property in Canadian carbon capture deployment corridors. Five-to-ten-year viability hinges on hydrogen hub funding trajectories and EPA enforcement consistency rather than commodity compressor replacement cycles. Watch API 617 certification backlog duration as the signal indicating whether technical barriers are widening or compressing for new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technician Certification Program | Factory-trained networks address specialist scarcity delaying Permian Basin commissioning timelines. |
| Carbon Fiber Impeller Backward Integration | In-house production of sour gas-resistant designs secures supply for Alberta oil sands upgraders. |
| Predictive Maintenance Contract Launch | Availability-risk transfer structures displace scheduled overhauls among Ontario power generators. |
| Hydrogen Compression Product Line Extension | Contaminant-free architectures capture electrolyzer integration demand across Gulf Coast hubs. |
| Digital Twin Platform Integration | Physics-based modeling with vibration sensor networks enables remote diagnostics for remote mining installations. |
Research Methodology
Trade association filings, customs import records, and SEC equipment manufacturer disclosures formed the secondary backbone, cross-referenced against primary interviews with maintenance directors at Texas and Louisiana petrochemical facilities, OEM procurement teams specifying magnetic bearing packages, aftermarket service heads managing legacy installed base populations, and plant engineers overseeing HVAC electrification retrofits. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across natural gas processing, chemical synthesis, and power generation end uses.
Historical trendline analysis of compressor procurement patterns across oil-injected, oil-free, and magnetic bearing architectures informed projection modeling throughout the forecast period. Segmentation dimensions included product architecture, application intensity, end-user capital discipline, and drive train technology adoption curves. CAGRs were derived from elasticity-adjusted demand functions incorporating EPA regulatory compliance cost burdens and Department of Energy efficiency standard phase-in schedules. Industry-specific inputs encompassed rare earth magnet price indices and API 617 certification timeline distributions.
Neodymium export quota disruptions, methane intensity regulation enforcement variance, and magnetic bearing load capacity breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding continued electrification code adoption in California and New York building markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Reciprocating Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Booster Compressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
Europe Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Portable Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Root Blower Market
Compressors
Process Gas Compressors Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
North America Compressor Market