
 Centrifugal Compressors Market | 2026-2036
Centrifugal Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Compressors Market Analysis
Multi-source procurement for critical rotating equipment is decoupling from decade-old sole-source contracts across downstream energy projects. Baker Hughes Company leverages integrated turbomachinery portfolios to anchor large-scale LNG train deployments. MAN Energy Solutions sustains engineering intensity in high-pressure barrel compressor designs for hydrogen pipeline injection. Atlas Copco AB competes aggressively in oil-free centrifugal systems for pharmaceutical clean air applications.
A centrifugal compressor accelerates gas through an impeller rotating at speeds typically exceeding 20,000 RPM, converting kinetic energy into pressure via a diffuser and volute casing. The device serves as the backbone of process gas handling, refrigeration cycles, and pipeline transmission where continuous flow and oil-free output prove essential. Oil-free product configurations command premium positioning as food-grade and electronic manufacturing tolerances tighten. High power ratings dominate installed value in base-load power generation and integrated gasification combined cycle plants. Skid-mounted installations are gaining preference in modular refinery expansions and remote upstream facilities where site assembly costs constrain project economics.
The EPA enforces methane performance standards under NSPS OOOOa that compel compressor seal upgrades and leak detection protocols across US natural gas infrastructure. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, redirecting demand toward centrifugal systems using ammonia or CO2 as working fluids. In India, the BIS certification mandate for imported rotating electrical machinery is extending certification timelines and filtering supplier participation. Stakeholders must track how regional carbon border adjustments and refrigerant phase-down schedules reshape equipment specification criteria across project portfolios.
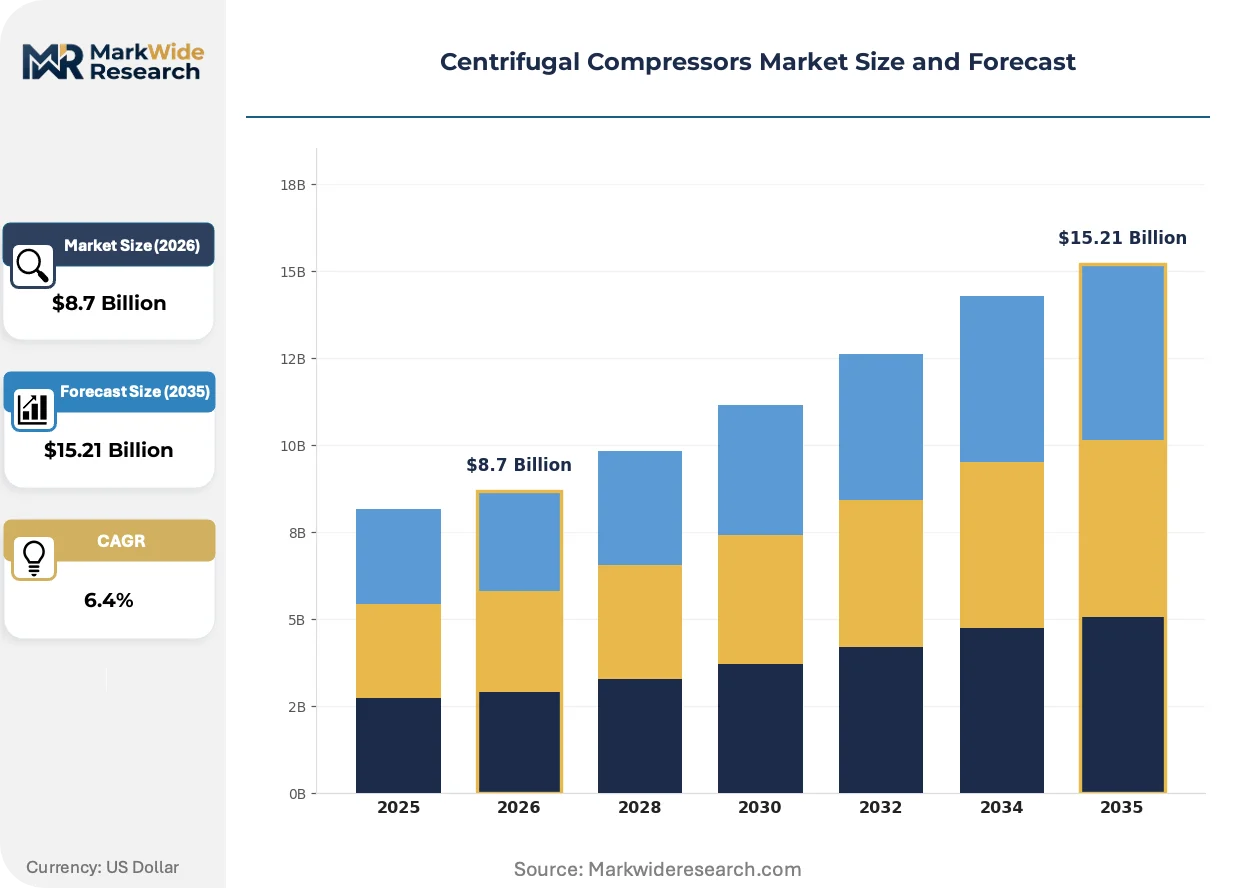
Market Dynamics
The centrifugal compressors market is reconfiguring around oil-free architectures as EPA methane performance standards and EU F-Gas Regulation force equipment replacements across process gas handling infrastructure.
Growth Catalysts
- NSPS OOOOa enforcement:EPA methane performance standards mandate seal upgrades and leak detection protocols across US natural gas infrastructure, compelling compressor fleet modernization.
- LNG infrastructure investment:Oil and gas operators are deploying high-capacity barrel compressors for liquefaction trains along the Gulf Coast petrochemical corridor.
- Hydrogen pipeline injection:High-pressure compression systems enable hydrogen blending into existing natural gas networks, creating demand for purpose-engineered impeller designs.
Market Restraints
- Specialized alloy input costs:Inconel and titanium impeller materials face price volatility from concentrated mining operations, pressuring manufacturing margins.
- Engineering talent scarcity:Aerodynamic design expertise for high-speed rotating machinery concentrates among a limited pool of turbomachinery specialists.
- Extended BIS certification timelines:India's mandatory certification for imported rotating electrical machinery is filtering supplier participation and delaying project execution.
Strategic Opportunities
- Pharmaceutical clean air applications:Oil-free centrifugal systems command premium positioning as food-grade and electronic manufacturing tolerances tighten.
- Ammonia and CO2 working fluid conversion:EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants redirects demand toward alternative refrigerant architectures.
- Skid-mounted modular deployments:Remote upstream facilities and modular refinery expansions favor pre-assembled compressor packages that minimize site construction costs.
Industry Challenges
- High-speed rotor balancing expertise:Impeller rotational speeds exceeding 20,000 RPM demand precision manufacturing capabilities that few facilities maintain.
- Legacy system integration complexity:Brownfield installations must interface centrifugal compressors with existing distributed control systems and pipeline infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Compressors Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Flooded, Oil-Free, Water-Cooled, Air-Cooled End User: Manufacturing, Oil & Gas, Power Generation, Chemical Processing Installation: Stationary, Portable, Skid-Mounted, Modular Power Rating: Low Power, Medium Power, High Power, Variable Speed |
| Companies Covered | Baker Hughes Company, MAN Energy Solutions, Atlas Copco AB, Elliott Group, GE Vernova, Ingersoll Rand Inc., Mitsubishi Heavy Industries Ltd, Sundyne, Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Compressors Market Emerging Trajectories
Equipment architecture is fragmenting into standardized sub-assemblies as project developers prioritize capital efficiency and field serviceability over bespoke engineering.
Magnetic bearing technology is modularizing compressor maintenance cycles by eliminating mechanical contact surfaces and enabling active vibration control. Pipeline operators and LNG terminal developers are specifying oil-free magnetic bearing systems for base-load applications where continuous availability outweighs first-cost premiums. This architecture is modularizing aftermarket service models by reducing scheduled maintenance intervals and enabling remote condition monitoring.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down through 2030, redirecting specification criteria toward ammonia and transcritical CO2 systems. Equipment manufacturers are expanding compressor portfolios optimized for natural refrigerants with modified pressure ratios and material compatibility. Process refrigeration and cold chain infrastructure in Northern Europe are converting fastest, with utility-scale district cooling projects leading adoption curves.
Multi-source procurement for critical rotating equipment is displacing sole-source contracting that dominated downstream energy projects for decades. EPC contractors now mandate dual-qualified vendors for LNG train deployments to mitigate supply concentration risk. This behavioral shift is most pronounced among integrated oil companies executing Gulf Coast petrochemical expansions, where project finance covenants require documented procurement redundancy.
Centrifugal Compressors Market Segmentation
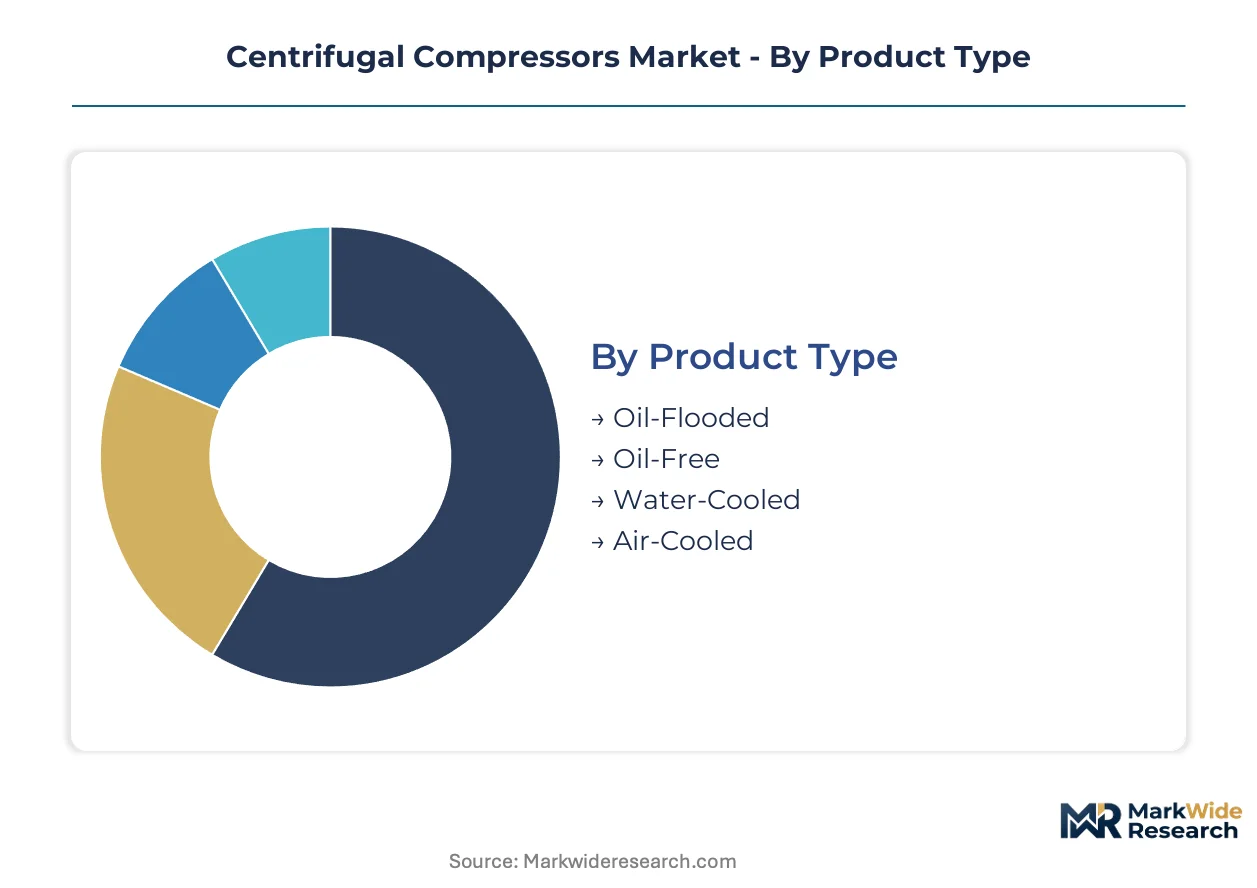
Centrifugal compressor procurement splits sharply between base-load industrial operators seeking maximum uptime and project developers prioritizing capital efficiency. Specification criteria diverge across end-use sectors, with oil-free architectures commanding premium positioning in food-grade applications while high-pressure barrel designs dominate LNG liquefaction trains.
Product Type:
Buyers in this category separate into contamination-sensitive process industries and cost-optimized general manufacturing operators.
- Oil-Free:Magnetic bearing and dry gas seal architectures eliminate lubricant contact with process streams. Pharmaceutical clean air systems and semiconductor fabrication facilities in Germany and Japan specify these configurations as EPA methane standards and EU F-Gas Regulation tighten emissions accountability.
- Oil-Flooded:Conventional lubricated designs deliver lower first-cost positioning for general industrial compressed air. Petrochemical corridors along the US Gulf Coast deploy these for non-critical utility air where continuous operation outweighs contamination risk.
- Water-Cooled:Closed-loop cooling circuits suit high-ambient installations in Middle Eastern desalination and power generation facilities.
- Air-Cooled:Eliminates cooling water infrastructure for remote upstream sites and modular refinery expansions.
Volume sits with Oil-Flooded systems; growth tilts toward Oil-Free architectures as regulatory compliance hardens across process industries.
End User:
Application intensity determines specification rigor, with continuous-duty process gas handling demanding fundamentally different engineering than intermittent manufacturing loads.
- Oil & Gas:Pipeline transmission and LNG liquefaction require barrel compressors rated for high-pressure hydrogen blending and sour gas service. Gulf Coast petrochemical operators are modernizing fleets under NSPS OOOOa methane performance standards, redirecting capital toward seal upgrade programs and leak detection infrastructure.
- Power Generation:Integrated gasification combined cycle plants specify high power ratings for syngas compression and carbon capture integration. Base-load facilities prioritize magnetic bearing systems where continuous availability justifies first-cost premiums.
- Chemical Processing:Ammonia and methanol synthesis demand corrosion-resistant impeller alloys for synthesis gas loops.
- Manufacturing:General industrial compressed air represents volume deployment with shorter replacement cycles.
Capital deployment concentrates in Oil & Gas; specification innovation accelerates fastest in Power Generation as hydrogen pipeline injection and carbon capture retrofits reshape impeller design requirements.
Installation:
Project delivery models are shifting toward factory-integrated packages that minimize field construction risk and accelerate commissioning timelines.
- Skid-Mounted:Pre-assembled compressor packages integrate lube oil systems, control panels, and auxiliary cooling on structural steel frames. Modular refinery expansions in Texas and Louisiana favor this architecture where skilled construction labor availability constrains site schedules.
- Modular:Standardized sub-assemblies enable replication across multiple LNG train deployments. EPC contractors executing Gulf Coast petrochemical expansions now mandate dual-qualified vendors to satisfy project finance covenants requiring procurement redundancy.
- Stationary:Permanent foundations dominate base-load power generation and large-scale chemical processing installations.
- Portable:Trailer-mounted units serve upstream wellhead compression and emergency pipeline maintenance.
Stationary installations retain the largest installed base; Skid-Mounted configurations are climbing the fastest as developers prioritize capital efficiency and field serviceability.
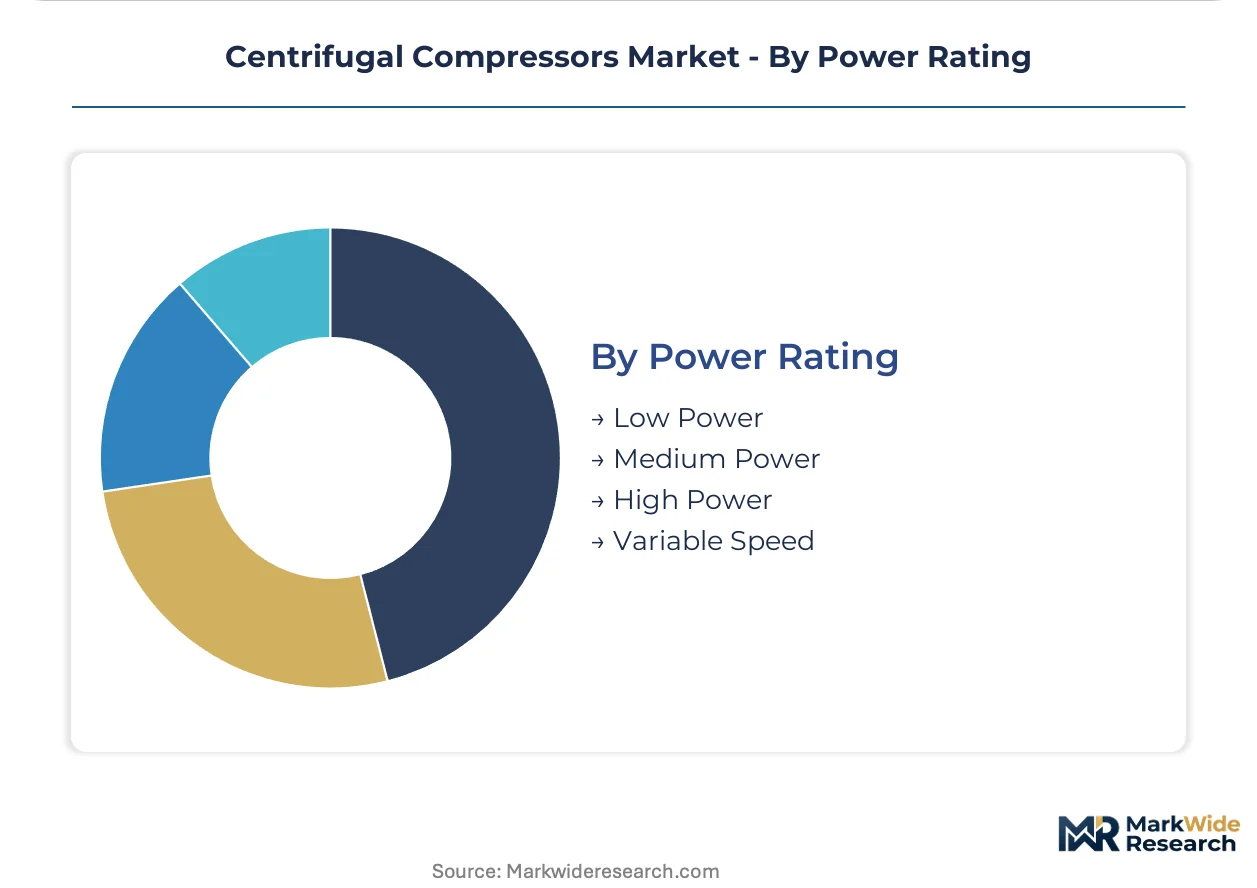
Power Rating:
Energy intensity and rotational speed requirements stratify manufacturing capabilities and supplier qualification tiers.
- High Power:Impeller rotational speeds exceeding 20,000 RPM demand Inconel and titanium alloys with precision balancing capabilities that few facilities maintain. Base-load LNG liquefaction and integrated gasification plants specify these for maximum throughput per installed train.
- Variable Speed:Adjustable frequency drives match compressor output to fluctuating pipeline demand and process load variations. Hydrogen blending into existing natural gas networks requires this flexibility to manage injection rate variability.
- Medium Power:Standardized designs serve chemical processing and general industrial applications with moderate pressure ratio requirements.
- Low Power:Compact units address pharmaceutical clean air and food-grade compressed air with oil-free mandatory specifications.
Revenue concentrates in High Power systems; Variable Speed drives are gaining share fastest as pipeline operators optimize energy consumption across fluctuating demand profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment in LNG liquefaction trains and hydrogen pipeline infrastructure concentrates procurement activity across the United States Gulf Coast, Germany's industrial heartland, and coastal China manufacturing clusters.
United States
Petrochemical operators along the Texas-Louisiana corridor are modernizing compressor fleets under EPA NSPS OOOOa methane performance standards. The regulation mandates seal upgrades and leak detection protocols across natural gas infrastructure. Corpus Christi and Lake Charles anchor LNG export terminal expansions requiring high-capacity barrel compressors.
Germany
EU F-Gas Regulation is redirecting specification criteria toward ammonia and transcritical CO2 refrigeration systems in chemical processing facilities. The country's national environmental regulator enforces progressive hydrofluorocarbon phase-down through 2030. BASF's Ludwigshafen complex and Bayer's Leverkusen operations are converting process refrigeration to natural refrigerant architectures.
China
State-owned oil majors are deploying high-pressure compression systems for hydrogen blending trials into existing natural gas networks. The Ministry of Ecology and Environment oversees dual carbon goals affecting industrial equipment standards. Yangtze River Delta petrochemical clusters in Shanghai and Ningbo are specifying magnetic bearing systems for base-load power generation.
India
BIS certification mandates for imported rotating electrical machinery are filtering supplier participation in refinery expansion projects. The Central Electricity Authority oversees grid integration standards for power generation equipment. Reliance Industries' Jamnagar complex and HPCL-Mittal Energy's Bhatinda refinery are navigating extended certification timelines for skid-mounted compressor packages.
Saudi Arabia
Saudi Aramco is integrating centrifugal compressors into blue hydrogen and ammonia export infrastructure under Vision 2030 industrial diversification targets. The Saudi Food and Drug Authority regulates equipment standards for downstream processing. Jubail Industrial City and Yanbu petrochemical complexes are specifying oil-free architectures for specialty chemical manufacturing.
Centrifugal Compressors Market Vendor Landscape
Portfolio diversification dominates the current landscape as turbomachinery specialists expand from core oil and gas applications into hydrogen and carbon capture verticals. The vendor base stratifies across three tiers: integrated energy technology conglomerates with full turbomachinery portfolios, precision engineering specialists focused on high-speed rotating equipment, and modular packaging firms serving remote upstream deployments. Strategic archetypes include integrated project solution providers, component specialists, and aftermarket service operators. M&A activity and technology licensing agreements represent the primary competitive moves as firms acquire magnetic bearing capabilities and aerodynamic design expertise.
Among integrated energy technology providers, Baker Hughes Company, MAN Energy Solutions, and Atlas Copco AB exemplify distinct positioning archetypes. Baker Hughes occupies a position representing full-stream turbomachinery integration for LNG train deployments. MAN Energy Solutions exemplifies the precision engineering specialist archetype with concentration in high-pressure process applications. Atlas Copco AB represents the oil-free system specialist tier serving contamination-sensitive industrial segments. These three firms collectively illustrate how competitive positioning fragments across project scale, technical specification intensity, and end-use contamination tolerance.
| Leading Market Players |
|---|
| Baker Hughes Company |
| MAN Energy Solutions |
| Atlas Copco AB |
| Elliott Group |
| GE Vernova |
| Ingersoll Rand Inc. |
| Mitsubishi Heavy Industries Ltd |
| Sundyne |
| Siemens Energy AG |
| Others |
Supply Flow & Price Mechanics
Magnetic bearing technology adoption in base-load LNG applications simultaneously elevates engineering cost thresholds and consolidates supplier qualification tiers around precision manufacturing capabilities in Germany, Japan, and the United States Gulf Coast. This dual shift compresses margins for conventional oil-flooded architectures while amplifying pricing power for certified oil-free system providers serving EPA NSPS OOOOa compliance mandates.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium magnetic bearing configurations from unbundled conventional compressor sales. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service intensity. Cost compression in oil-flooded segments intensifies because Inconel and titanium alloy volatility pressures manufacturing margins. Project developers executing Gulf Coast petrochemical expansions exhibit highest price sensitivity; pharmaceutical clean air operators demonstrate lowest sensitivity due to contamination risk premiums.
Supply Chain Analysis
Dual-sourcing requirements embedded in EPC contractor specifications now mandate qualified vendors for critical LNG train components across Germany, Japan, and the United States. Precision forging and high-speed rotor balancing capabilities draw from concentrated aerospace and nuclear industry supplier bases. Single-source vulnerability concentrates in specialized alloy supply chains subject to mining operation disruptions. Distribution runs through OEM-direct channel structures for large-project deployments, with aftermarket service networks handling spare parts and field retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centrifugal compressor procurement functions as a cost-of-compliance market where EPA NSPS OOOOa methane performance standards erect regulatory moats favoring incumbents with established certification infrastructure and field service networks.
For Market Incumbents: Anticipate margin compression from emerging modular packaging specialists by deepening captive supply of magnetic bearing subsystems and precision forging capacity. Prioritize certification investment in hydrogen-compatible impeller designs to preempt regulatory expansion beyond methane standards. Channel control through long-term service contracts anchors customer retention against low-cost entrants.
For New Entrants and Emerging Players: Digital aftermarket platforms offering remote condition monitoring and predictive maintenance represent the most penetrable entry vector. Target pharmaceutical clean air segments where oil-free mandatory specifications limit incumbent price aggression. Deploy direct-to-plant engineering sales to bypass established EPC procurement gatekeepers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated energy technology conglomerates seeking magnetic bearing capabilities. Long-term viability favors precision engineering specialists with demonstrated hydrogen pipeline injection project execution. Watch for inflection signals in EU F-Gas Regulation enforcement intensity accelerating ammonia refrigerant conversion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Enables oil-free system expansion into pharmaceutical clean air applications under tightening EPA standards. |
| Hydrogen-Compatible Impeller Development | Positions suppliers for pipeline blending trials in Germany and China's national hydrogen infrastructure programs. |
| Backward Integration into Titanium Forging | Reduces exposure to concentrated mining operations supplying Inconel and titanium for high-speed rotors. |
| Skid-Mounted Modular Packaging Expansion | Addresses labor constraints in Texas and Louisiana refinery expansions through factory-integrated delivery. |
| Dual-Vendor Qualification Programs | Satisfies project finance covenants for Gulf Coast LNG deployments requiring procurement redundancy documentation. |
Methodological Framework
Independent corroboration across turbomachinery engineering directors, EPC contractor procurement leads, and plant maintenance managers underwrites the qualitative findings. Primary interviews with aftermarket service heads and OEM sales engineers combined with secondary validation from customs trade data, FERC infrastructure filings, and SEC equipment manufacturer disclosures. Bottom-up project pipeline enumeration and top-down energy sector capital expenditure triangulation anchor volume estimates.
Rate-of-change decomposition across product type, end-use sector, installation format, power rating, and regional regulatory cluster shapes the analytical framework. CAGRs derive from segmented demand modeling incorporating LNG train deployment schedules, hydrogen pipeline injection pilot programs, and refrigerant phase-down compliance timelines. Forecast inputs include alloy price indices, engineering talent availability metrics, and certification timeline data from India's BIS regulatory filings.
The model holds under stable regulatory enforcement intensity and continuous LNG infrastructure investment; deviation in EPA methane standard stringency or EU F-Gas Regulation acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Oil-Free Air Compressor Market
Compressors
High Speed Blowers Market
Compressors
Industrial Air Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Compressor Rental Market
Compressors
PAG Compressor Oil Market
Compressors
Gas Compressors Market
Compressors
North America Air Compressor Market
Compressors
Compressor Wheel Market
Compressors
Liquid Ring Compressors Market
Compressors
Automotive Compressors Market
Compressors
Reciprocating Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Oil-Injected Screw Compressor Market