
 Axial Compressor Market | 2026-2036
Axial Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Axial Compressor Market Analysis
The axial compressor supply base is rebalancing between premium aerodynamic designs and commodity replacement units. Siemens Energy AG leverages in-house turbine integration to dominate integrated power-train packages for combined-cycle plants. Baker Hughes Company anchors its position through upstream control over precision casting foundries serving superalloy blade production.
An axial compressor is a dynamic turbomachine employing alternating rows of rotating rotor blades and stationary stator vanes to progressively increase gas pressure along the flow axis, typically achieving pressure ratios from 6:1 to over 40:1 in multi-stage configurations. Its primary purpose is to deliver large-volume, high-efficiency air compression for gas turbines, process plants, and aircraft engines. Multi Stage units capture the dominant margin pool where aerodynamic customization and materials science differentiate suppliers. Variable Speed technology is displacing fixed-speed architectures in power generation as grid flexibility mandates intensify.
EPA emissions standards under the Clean Air Act and EU F-Gas Regulation constrain refrigerant and working-fluid choices in compressor-adjacent systems, while FAA airworthiness directives govern aerospace blade integrity and lifecycle traceability. ISO 5389 performance testing protocols create compliance barriers for entrants lacking certified test rigs. Stakeholders must monitor how carbon border adjustment mechanisms reshape sourcing economics for cast and forged components before committing to capacity expansions.
Market Dynamics
Variable-speed drive integration is compressing fixed-speed compressor lifecycles as grid operators demand rapid load-following capability from gas turbine peakers. This technological pivot forces asset owners to weigh retrofit economics against full replacement.
Growth Catalysts
- EPA Clean Air Act amendments:Stationary gas turbine operators face escalating NOx and CO2 intensity thresholds that only higher-pressure-ratio axial stages can satisfy through improved thermodynamic efficiency.
- Superalloy casting advances:Directionally solidified blade manufacturing is extending hot-section durability, enabling longer maintenance intervals in combined-cycle baseload plants.
- US Gulf Coast LNG buildout:Cryogenic liquefaction trains require massive air separation and refrigeration compression capacity that multi-stage axial architectures deliver at scale.
Market Restraints
- Nickel-cobalt superalloy cost volatility:Aerospace-grade IN718 and Rene alloys face price swings tied to Congolese cobalt supply disruptions and Indonesian nickel export restrictions.
- Precision casting foundry concentration:Tier-one blade suppliers cluster in western Germany, eastern Poland, and South Carolina, creating single-source vulnerability for original equipment manufacturers.
- Intercooled recuperated cycle competition:Emerging closed-loop Brayton systems using supercritical CO2 threaten traditional axial compressor dominance in sub-50 MW distributed generation.
Strategic Opportunities
- India's ethanol-blending mandate:Sugar mill cogeneration retrofits and greenfield distilleries need process air compression that domestic fabricators currently underserve.
- EU Hydrogen Bank subsidies:Electrolyzer gigafactories in Rotterdam and Leuna require high-pressure hydrogen compression where multi-stage axial derivatives can displace reciprocating units.
- Digital twin convergence:Real-time aerodynamic modeling fused with blade-mounted fiber-optic strain sensing enables predictive maintenance contracts priced on availability guarantees.
Industry Challenges
- Computational fluid dynamics talent scarcity:Transonic blade row design requires specialized PhD-level aerodynamicists that OEMs and utilities compete to retain.
- ISO 5389 test rig certification delays:Third-party performance validation backlog stretches 14-18 months, gating new product introductions.
- Legacy SCADA integration friction:Variable-speed retrofits must interface with 1990s-era turbine control systems lacking native ethernet protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial Compressor Market |
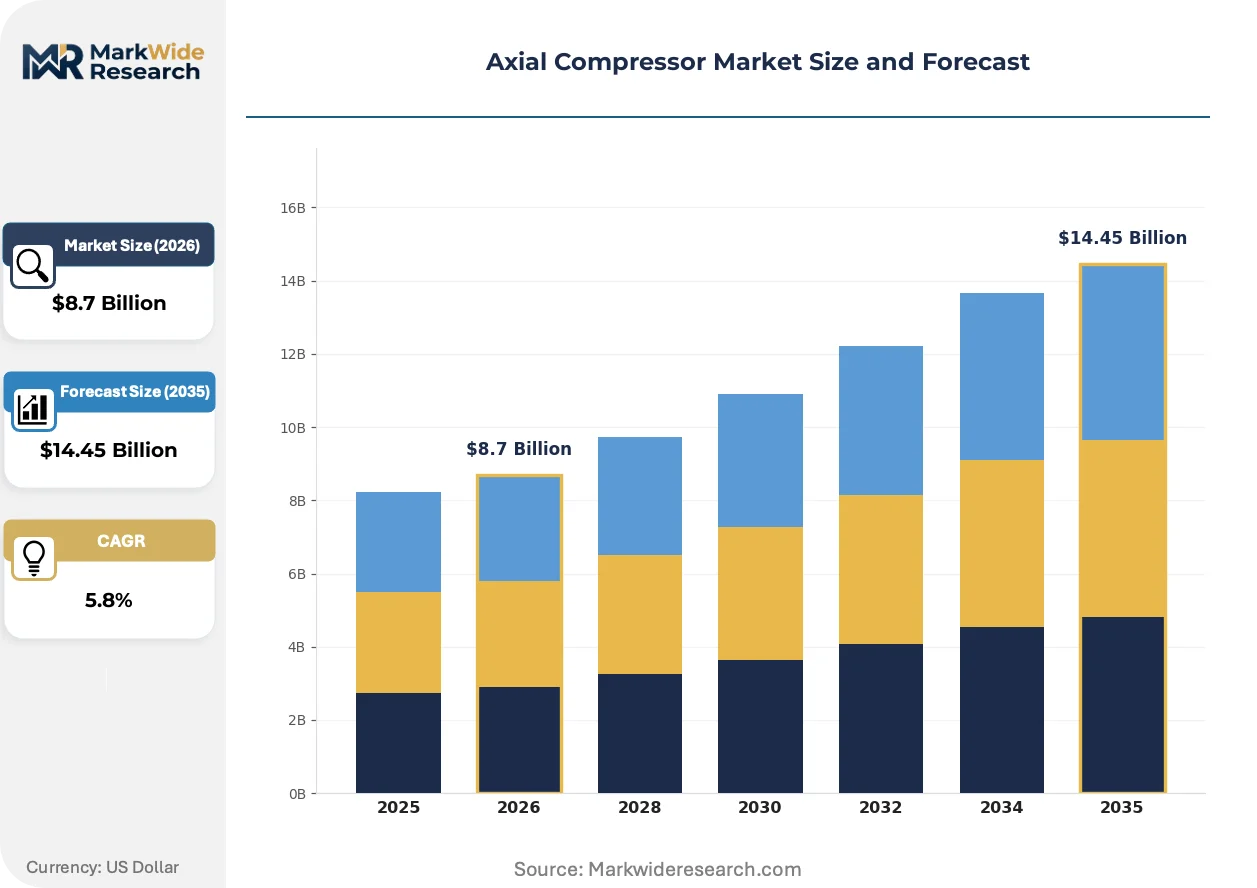
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Variable Speed, Turbocharger End User: Aerospace, Power Generation, Oil & Gas, Marine Technology: Smart Compressors, Variable Geometry, Dry Compressors, Integrated Systems Capacity: Small Capacity, Medium Capacity, Large Capacity, Ultra-Large Capacity |
| Companies Covered | MAN Energy Solutions SE, Atlas Copco AB, Siemens Energy AG, Howden Group Ltd, Ingersoll Rand Inc., General Electric Company, Baker Hughes Company, Ebara Elliott Energy, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial Compressor Market Emerging Trajectories
Additive manufacturing of nickel superalloy stator vanes is collapsing lead times for aerodynamic customization while introducing new quality-assurance protocols. This fabrication shift intersects with tightening emissions mandates and evolving procurement expectations.
Ceramic matrix composite blade inserts are electrifying hot-section temperature tolerance in aerospace derivatives. Pratt & Whitney and Rolls-Royce are qualifying these components for next-generation turbofan high-pressure compressors. The technology is compressing metal-alloy dependence and enabling pressure ratios beyond 50:1 in compact footprints.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon working fluids in process refrigeration systems adjacent to compressor trains. Equipment packagers in Germany and the Netherlands are redesigning intercooler circuits to accommodate natural refrigerants. Aerospace propulsion remains exempt, but stationary applications face retrofit deadlines driving hardware refresh cycles.
Power plant operators are unbundling long-term service agreements into component-level performance contracts. Instead of fixed-price overhaul commitments, buyers now negotiate blade-row availability pricing with penalties tied to forced outage rates. This pattern is most pronounced in Texas and PJM Interconnection markets where merchant generators bear full merchant risk.
Axial Compressor Market Segmentation
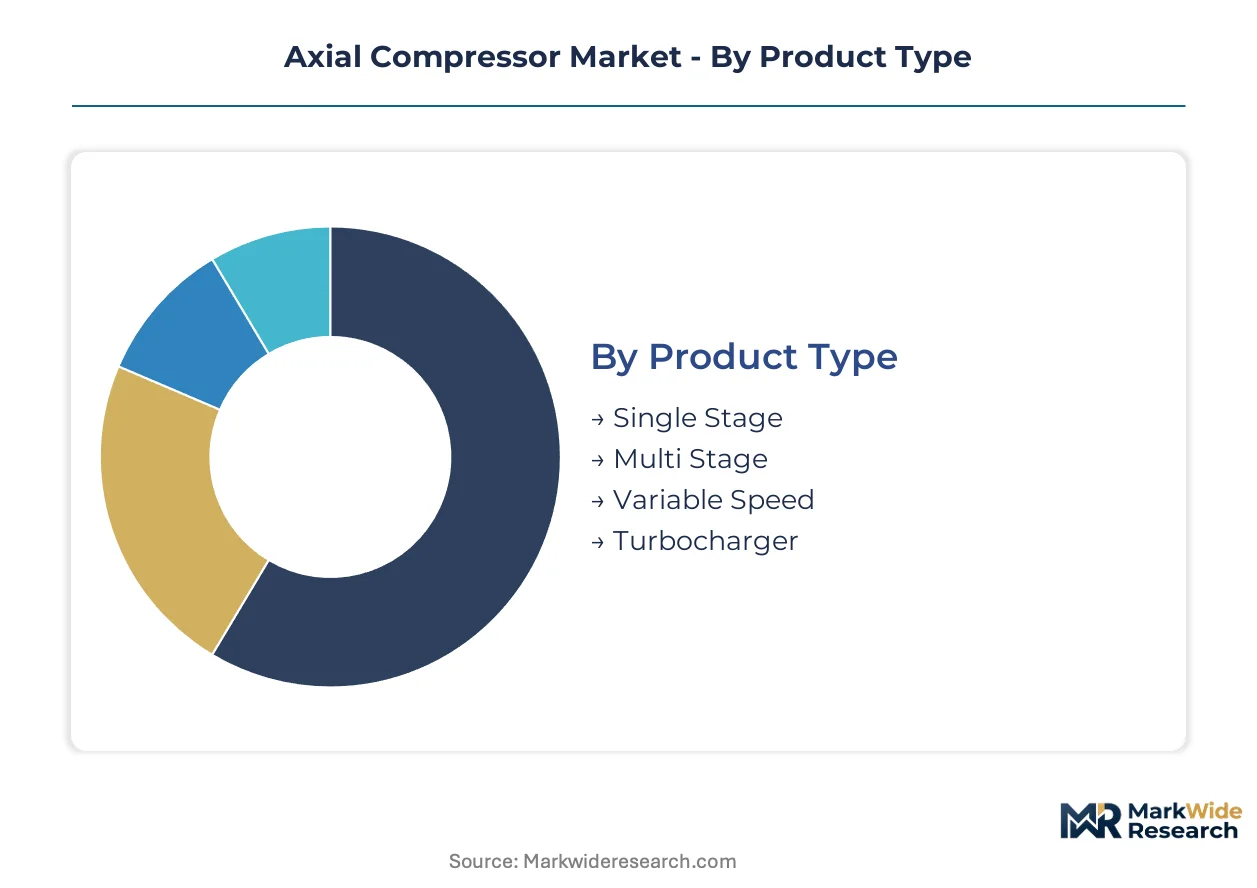
Axial compressor procurement decisions hinge on pressure ratio requirements, thermodynamic efficiency targets, and integration complexity. Each segmentation axis reveals distinct margin structures and supplier specialization patterns that shape competitive positioning.
Product Type:
Pressure ratio architecture defines the technical frontier across product categories.
- Multi Stage:Configurations stacking 8-20 blade rows achieve pressure ratios exceeding 40:1 through progressive compression. Demand concentrates in combined-cycle power plants across the United States where FERC grid reliability mandates require baseload efficiency above 62% LHV.
- Variable Speed:Integrated variable frequency drives enable 40-100% turndown without surge margin compromise. Grid operators in Texas and PJM Interconnection prioritize these units for 5-minute dispatch compliance in merchant power markets.
- Single Stage:Compact designs serve auxiliary air systems and industrial process blowers with pressure ratios below 6:1.
- Turbocharger:Radial-axial hybrid architectures dominate marine diesel and large reciprocating engine supercharging.
Multi Stage leads on scale; Variable Speed leads on momentum.
End User:
Application-specific duty cycles dictate materials selection and maintenance contracting models.
- Power Generation:Combined-cycle and simple-cycle gas turbines account for the dominant installed base. Operators in the United States face EPA Clean Air Act NOx intensity thresholds that force higher-pressure-ratio compressor retrofits.
- Aerospace:Commercial turbofan propulsion systems drive premium aerodynamic tolerances and superalloy blade investments.
- Oil & Gas:LNG liquefaction trains and gas processing facilities require cryogenic-compatible sealing and massive volumetric throughput.
- Marine:Naval and commercial propulsion systems prioritize shock resistance and salt-air corrosion protection in compressor casings.
Power Generation dominates current bookings; Aerospace commands the steepest expansion trajectory.
Technology:
Control system sophistication separates commodity hardware from performance-guaranteed solutions.
- Smart Compressors:Edge-computing-enabled units process blade-mounted sensor arrays for real-time surge prediction and autonomous clearance control.
- Variable Geometry:Adjustable stator vane scheduling optimizes part-load efficiency across ambient temperature swings in desert power plants.
- Dry Compressors:Oil-free bearing systems eliminate contamination risk in food-grade air and hydrogen compression service.
- Integrated Systems:Pre-engineered compressor-turbine-generator packages reduce field commissioning duration for EPC contractors.
Smart Compressors capture premium pricing; Variable Geometry expands most quickly in retrofit markets.
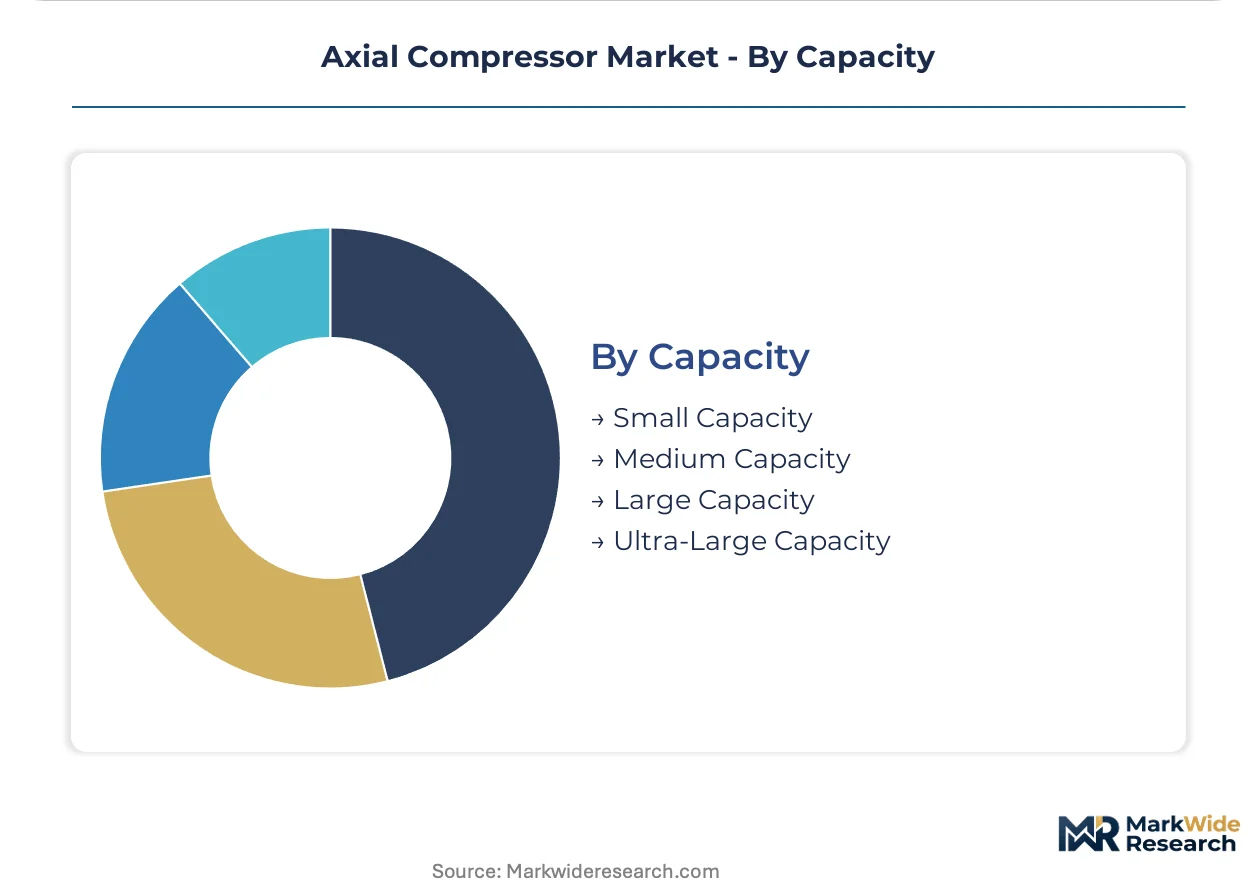
Capacity:
Unit scale determines manufacturing footprint and field service infrastructure requirements.
- Large Capacity:Units above 100 MW equivalent serve utility-scale power generation and baseload LNG liquefaction. Gulf Coast export terminal buildouts sustain order backlogs for these configurations.
- Ultra-Large Capacity:Custom-engineered trains exceeding 300 MW address air separation for green hydrogen electrolyzer gigafactories in Rotterdam and Leuna.
- Medium Capacity:Distributed generation and industrial cogeneration applications favor these units for capital efficiency.
- Small Capacity:Package units below 10 MW serve mechanical drive and auxiliary power roles.
Large Capacity anchors revenue concentration; Ultra-Large Capacity gains share fastest in hydrogen infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision casting foundry talent concentrates in western Germany, eastern Poland, and South Carolina, anchoring the industry's geographic footprint. These clusters supply superalloy blade production for multi-stage axial compressors. Regional procurement patterns diverge sharply between aerospace propulsion systems and stationary power generation.
United States
Shale gas processing and LNG export terminal buildouts sustain large-capacity orders along the Gulf Coast. EPA Clean Air Act amendments force combined-cycle operators toward higher-pressure-ratio retrofits. Houston anchors engineering services for cryogenic liquefaction trains requiring massive air separation compression.
Germany
Integrated power-train packaging for combined-cycle plants drives demand from Siemens Energy AG's domestic base. EU ETS carbon pricing accelerates efficiency upgrades across installed gas turbine fleets. Precision casting foundries in North Rhine-Westphalia supply directionally solidified blades for export markets.
China
Dual carbon goals under MEE frameworks push coal-to-gas switching in provincial power grids. Domestic fabricators scale multi-stage production for captive petrochemical complexes. Yangtze River Delta clusters concentrate on medium-capacity units for distributed generation.
India
Sugar mill cogeneration retrofits and greenfield ethanol distilleries need process air compression that domestic suppliers currently underserve. CEA grid reliability mandates favor variable-speed architectures for frequency regulation. Gujarat and Maharashtra industrial corridors attract foreign OEM joint ventures.
Japan
Commercial turbofan propulsion systems from Mitsubishi Heavy Industries drive premium aerodynamic tolerances. METI hydrogen roadmaps position axial derivatives for electrolyzer gigafactory compression service. Nagoya-Tokyo aerospace supply chains integrate ceramic matrix composite blade development.
Axial Compressor Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the axial compressor supply base. The market structure tilts toward consolidated integrated systems providers rather than component specialists. Three archetypes dominate: turbine-integrated power-train packagers, precision casting foundry owners, and aerodynamic design houses licensing intellectual property. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs secure captive blade supply.
Among German-based industrial conglomerates, MAN Energy Solutions SE and Siemens Energy AG exemplify the integrated power-train archetype. Atlas Copco AB represents Swedish engineering consolidation across compressed air and gas handling. Mitsubishi Heavy Industries, Ltd. anchors Japanese aerospace and heavy industrial compression capability. These entities occupy positions defined by backward integration into precision manufacturing and forward integration into long-term service contracting.
| Leading Market Players |
|---|
| MAN Energy Solutions SE |
| Atlas Copco AB |
| Siemens Energy AG |
| Howden Group Ltd |
| Ingersoll Rand Inc. |
| General Electric Company |
| Baker Hughes Company |
| Ebara Elliott Energy |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Utility-scale LNG terminal operators and combined-cycle plant developers concentrate procurement volumes, forcing OEMs toward performance-based contracting with availability guarantees replacing fixed-price hardware sales. This buyer consolidation compresses margin pools for commodity replacement units while elevating premiums for integrated power-train packages with long-term service attachments.
Pricing Analysis
Bundled long-term service agreements are fragmenting into component-level performance contracts priced on blade-row availability metrics. Pricing stratifies across aerodynamic customization tiers, with directionally solidified superalloy blades commanding substantial premiums over equiaxed castings. Cost compression in standard replacement hardware is intensifying because Chinese fabricators are scaling multi-stage production for captive petrochemical demand. Merchant generators in Texas and PJM Interconnection exhibit highest price sensitivity due to full merchant risk exposure, while aerospace propulsion systems show lowest sensitivity given FAA airworthiness traceability mandates.
Supply Chain Analysis
Dual-sourcing requirements from Siemens Energy AG and Mitsubishi Heavy Industries are forcing Tier-2 suppliers to qualify secondary foundries beyond their primary western Germany and South Carolina clusters. Superalloy feedstock draws from Indonesian nickel and Congolese cobalt channels, creating exposure to export restriction volatility. Single-source vulnerability concentrates in precision casting capacity for directionally solidified blades. Distribution runs through EPC contractor procurement desks for greenfield projects and OEM direct service channels for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU ETS carbon pricing differentials against US Gulf Coast regulatory environments reshape sourcing economics for cast and forged components.
For Market Incumbents: Acquire captive precision casting foundry capacity to secure superalloy blade supply against Indonesian nickel export volatility. Lock in long-term offtake agreements with cobalt suppliers to hedge Congolese supply disruption risk. Counter emerging intercooled recuperated cycle competition by accelerating variable-speed drive integration for grid flexibility mandates. For New Entrants and Emerging Players: Begin with India's ethanol-blending mandate segment where domestic fabricators underserve sugar mill cogeneration retrofits. Target medium-capacity variable-speed architectures for CEA frequency regulation compliance. Pursue joint venture structures with established OEMs to bypass ISO 5389 test rig certification backlogs. For Investors and Strategic Acquirers: Turbine-integrated power-train packagers are the most active acquirer in this space, consolidating aerodynamic design houses to capture intellectual property premiums. Five-to-ten year viability hinges on hydrogen infrastructure buildout trajectories. Watch EU Hydrogen Bank subsidy disbursement velocity as the critical inflection signal for ultra-large capacity order flow.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive superalloy blade supply secures margin pools against nickel-cobalt volatility. |
| Variable Speed Drive Retrofit Programs | Grid flexibility mandates in Texas and PJM Interconnection accelerate replacement cycles. |
| Ceramic Matrix Composite Qualification | Pratt & Whitney and Rolls-Royce adoption enables pressure ratios beyond 50:1. |
| Hydrogen Compression Derivative Development | Rotterdam and Leuna electrolyzer gigafactories displace reciprocating units. |
| Digital Twin Service Contract Unbundling | Real-time aerodynamic modeling supports availability-guaranteed pricing models. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each region combining structured interviews with gas turbine plant managers, LNG terminal procurement leads, aerospace OEM sourcing executives, and aftermarket service directors. Secondary validation draws from EPA Clean Air Act filings, EU ETS carbon pricing registries, FERC grid reliability reports, and IEA hydrogen infrastructure tracking. Bottom-up unit economics triangulate against top-down sectoral demand models.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include pressure ratio architecture, end-use application, control system sophistication, and unit capacity tier. CAGRs derive from installed base turnover analysis and greenfield project pipeline assessment. Forecast inputs incorporate EPA emissions threshold trajectories and EU F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including unannounced superalloy casting foundry closures and abrupt Indonesian nickel export moratoria. Forecasts reflect assumptions about grid flexibility mandate enforcement intensity and hydrogen subsidy disbursement continuity. Deviation in FAA airworthiness directive timing or ISO 5389 certification backlog duration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Hydrogen Compressor Market
Compressors
Air Compressor Market
Compressors
Gas Compressors Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Compressor Rental Market
Compressors
Oil-Free Air Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Europe Compressor Market
Compressors
Automotive Compressors Market
Compressors
Portable Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
USA Scroll Compressor Market