
 Europe Compressor Market | 2026-2036
Europe Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Compressor Market Foresight
Capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with captive casting and precision machining capabilities. Atlas Copco AB leverages its in-house airend production to sustain margin control across the rotary screw segment. KAESER KOMPRESSOREN anchors its position through dense service networks that dominate aftermarket revenue pools in German-speaking markets.
A compressor is a mechanical device that increases gas pressure by reducing its volume through positive displacement or dynamic action, typically achieving discharge pressures from a few bar to over 400 bar depending on stage configuration and cooling architecture. Its primary purpose is to power pneumatic tools, enable refrigeration cycles, and feed process gas streams across industrial facilities. Rotary screw compressors occupy the largest installed base in European manufacturing, while oil-free technology commands premium positioning in food processing and pharmaceutical applications where contamination risks carry regulatory penalties. Variable speed drives represent the fastest-expanding technology segment as end users pursue Part Load Efficiency Index compliance under EU ecodesign requirements.
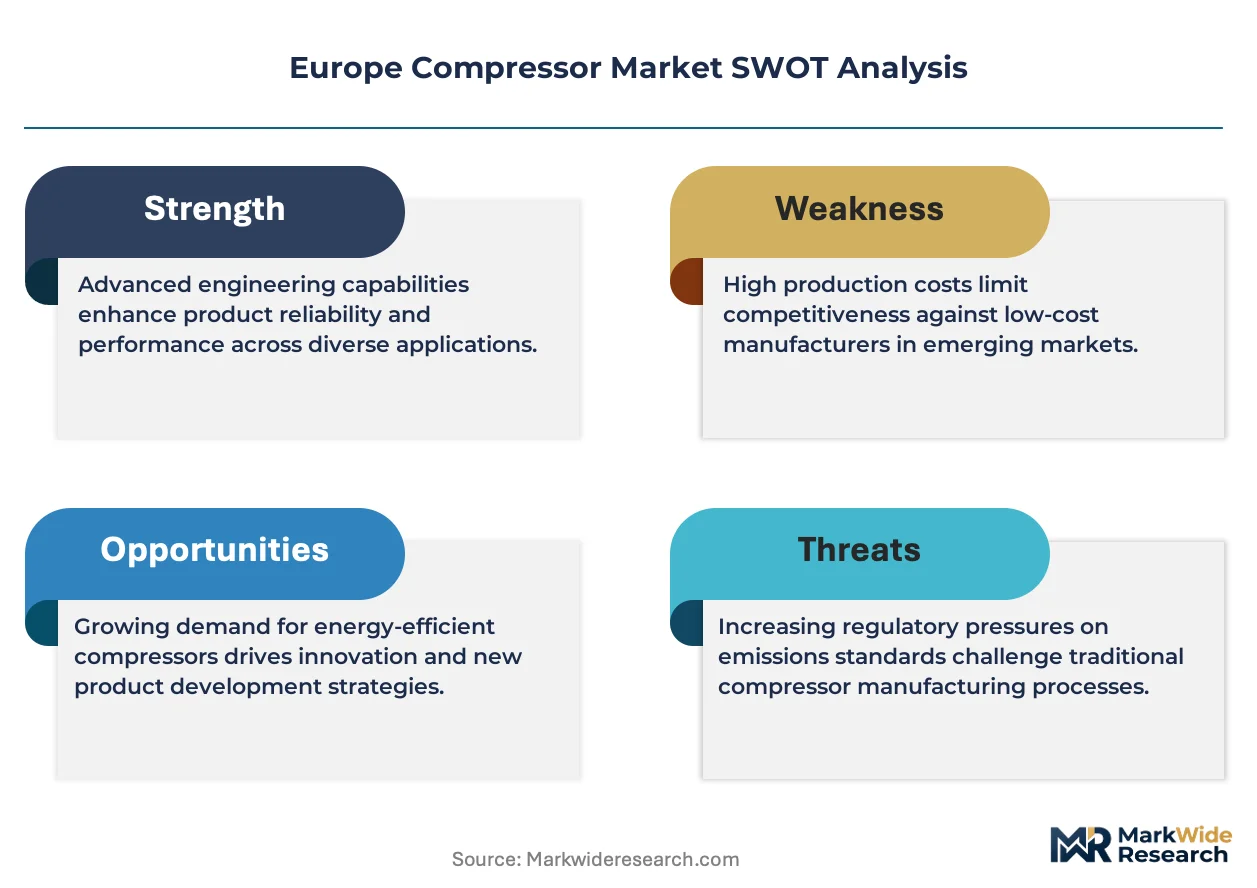
REACH and the EU F-Gas Regulation constrain material selection and refrigerant choices, while CE marking under the Machinery Directive governs safety compliance for compressor systems placed on the European market. Ecodesign regulations mandate minimum efficiency thresholds that disqualify fixed-speed models from new installations above certain power ratings. Stakeholders must monitor the EU Green Deal's emerging carbon border adjustments, which will reshape total cost of ownership calculations for imported compressor equipment against domestically manufactured alternatives.
Market Dynamics
EU F-Gas Regulation mandates are forcing accelerated equipment replacement cycles across European industrial facilities, compressing the transition timeline from high-GWP refrigerant systems to next-generation compressor architectures. This regulatory pressure is restructuring capital allocation patterns among end-users and OEMs alike.
Growth Catalysts
- HVAC Retrofit Mandates:Germany's building efficiency programs and France's renovation wave are generating concentrated demand for oil-free and variable-speed compressor technologies in commercial and residential applications.
- REACH Compliance:Material restrictions under ECHA guidelines are compelling manufacturers to redesign sealing systems and lubricant formulations, creating upgrade revenue for compliant equipment suppliers.
- Automotive Electrification:Precision manufacturing clusters in Baden-Württemberg and Bavaria require ultra-clean compressed air systems for battery cell assembly and electric drivetrain production.
Market Restraints
- Rare Earth Magnet Dependency:Permanent magnet motors in high-efficiency variable-speed compressors rely on neodymium supply chains concentrated in Chinese processing facilities.
- Casting Capacity Bottleneck:European foundry consolidation has reduced domestic grey iron and nodular iron supply for airend housings and pressure vessels.
- CE Marking Complexity:Machinery Directive conformity assessment timelines have extended due to notified body capacity constraints, delaying product launches.
Strategic Opportunities
- Poland Industrial Corridor:Manufacturing relocation from Western Europe is creating greenfield demand for compressed air infrastructure in Silesian and Greater Poland voivodeships.
- Heat Pump Convergence:Integration of compressor technology with residential heating systems opens addressable market expansion beyond traditional industrial boundaries.
- Service Network Gaps:Sparse aftermarket coverage in Iberian Peninsula and Balkan regions presents acquisition and partnership targets for independent service providers.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of engineers capable of integrating power electronics, thermal management, and control algorithms into variable-speed drive systems.
- Legacy System Integration:Retrofit installations must interface with existing pneumatic networks and SCADA architectures, complicating commissioning and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Compressor Market |
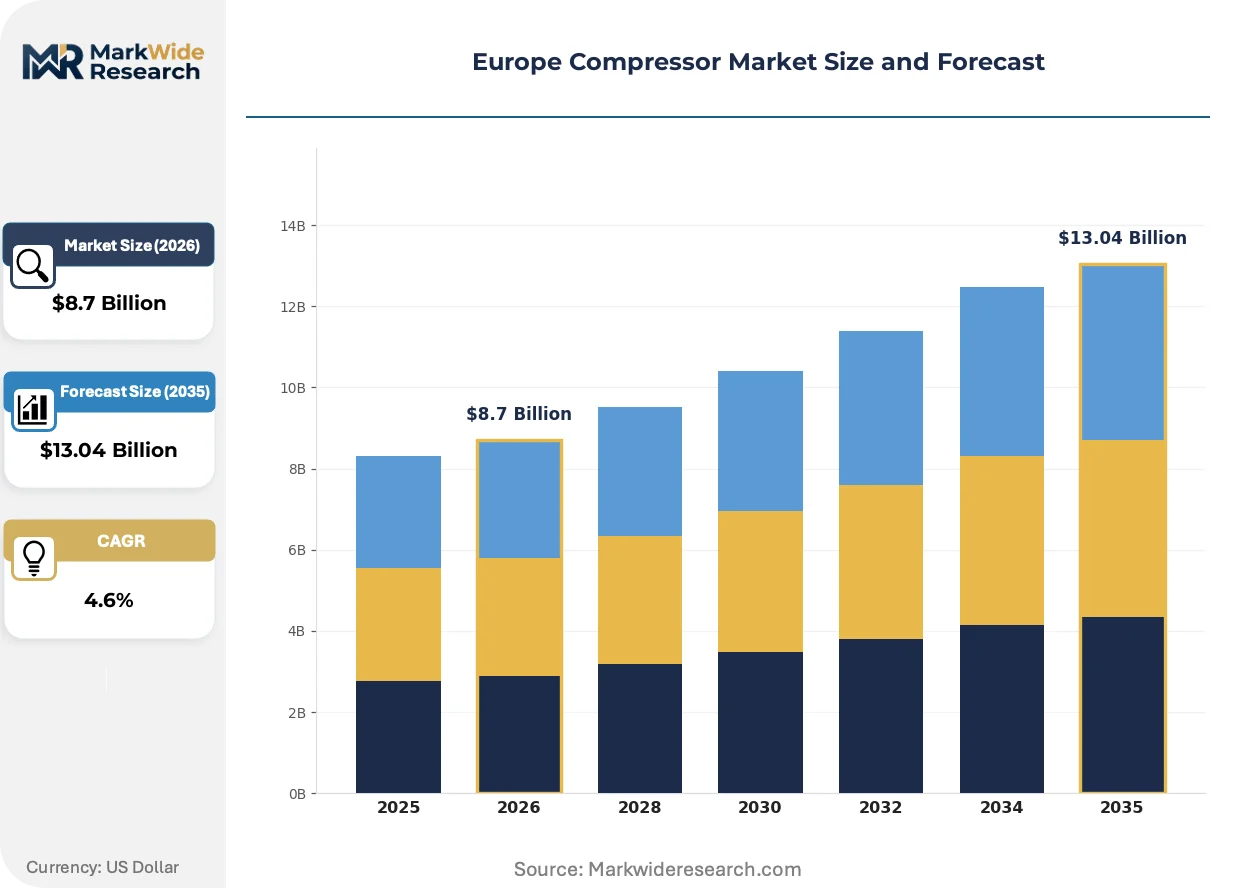
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll Application: Manufacturing, HVAC, Automotive, Food Processing End User: Industrial, Commercial, Residential, Research Technology: Oil-Free, Oil-Lubricated, Variable Speed, Fixed Speed |
| Companies Covered | Atlas Copco AB, KAESER KOMPRESSOREN, Siemens AG, Sulzer AG, Baker Hughes Co, Aerzener Maschinenfabrik GmbH, Ingersoll Rand, Burckhardt Compression Holding AG, BAUER COMP Holding GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Compressor Market Shifts & Advancements
Digital twin architectures and predictive maintenance platforms are converging with hardware efficiency improvements to redefine compressor lifecycle economics. Equipment vendors are repositioning around data-enabled service models rather than transactional sales.
Magnetic bearing centrifugal compressors are supplanting conventional oil-lubricated turbomachinery in large-scale HVAC and process cooling applications. Data center operators in Frankfurt and Amsterdam are adopting these systems to eliminate lubricant contamination risks and reduce maintenance intervals. Oil-free technology is supplanting legacy flooded designs in premium market tiers where regulatory compliance and uptime guarantees command price premiums.
EU Ecodesign regulations are tightening minimum efficiency thresholds for compressors above specific power ratings, disqualifying fixed-speed models from new installations. Manufacturers must redesign product portfolios to meet Part Load Efficiency Index requirements or exit the mid-power segment. German and Italian OEMs are responding fastest, leveraging existing variable-speed platforms to maintain market presence.
Compressed air as-a-service contracts are displacing capital purchase models among mid-sized manufacturing facilities seeking to offload asset management risk. End-users in Benelux and Nordic markets are prioritizing guaranteed uptime and energy performance over equipment ownership. Channel intermediaries are consolidating to offer bundled financing, maintenance, and efficiency guarantees.
Europe Compressor Market Segmentation
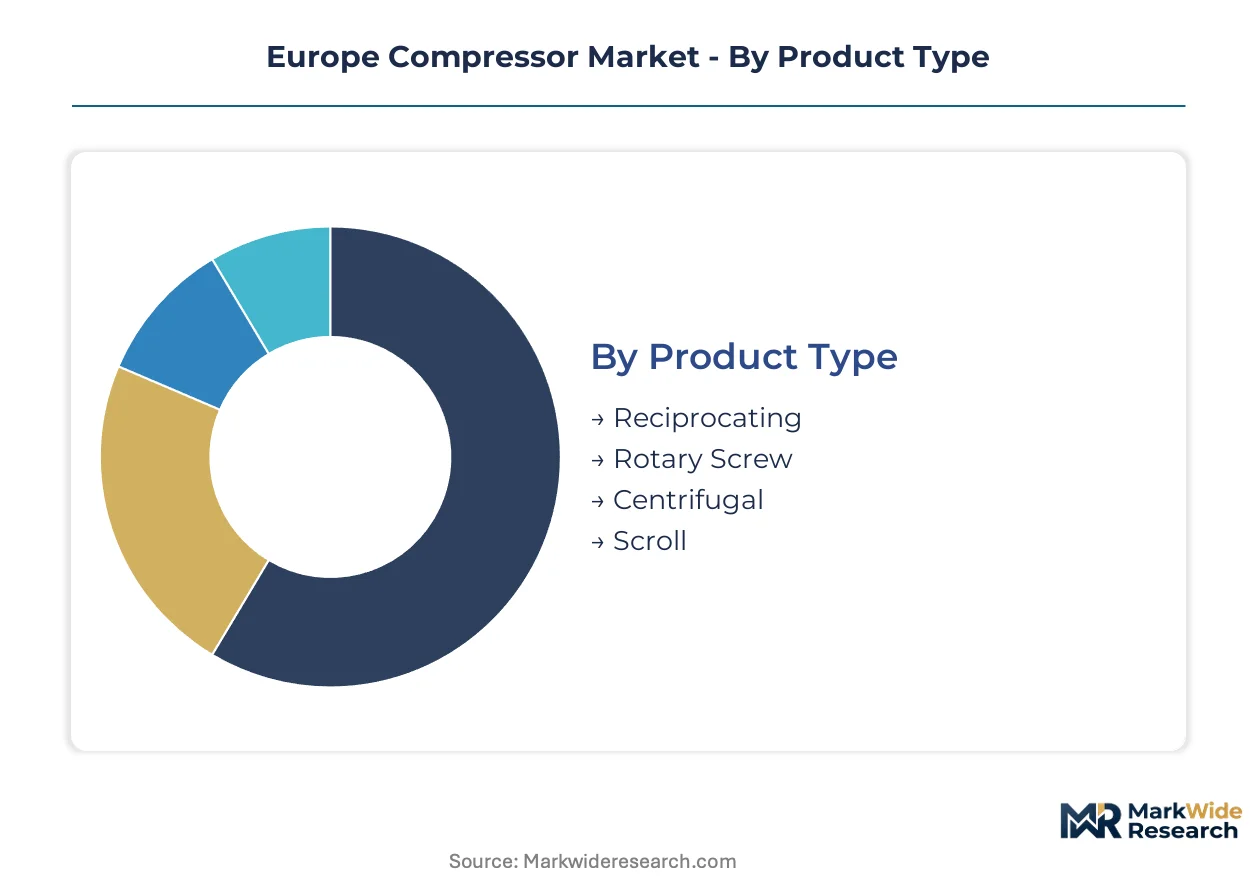
Segmentation in the Europe Compressor Market reveals how regulatory pressure and end-use specialization fragment revenue pools across technology tiers. Manufacturers must align portfolio depth with specific efficiency mandates and contamination standards rather than pursuing horizontal coverage.
Product Type:
Margin pools concentrate in rotary screw and centrifugal architectures where precision manufacturing and energy efficiency create pricing power.
- Reciprocating:Piston-driven compression achieves high pressure ratios through staged cylinders, suited for intermittent duty cycles. Demand persists in Italian and Spanish automotive repair shops where capital constraints favor lower first-cost equipment over lifecycle efficiency.
- Rotary Screw:Intermeshing helical rotors deliver continuous airflow with minimal pulsation, dominating manufacturing facilities across Germany's industrial belt. Baden-Württemberg precision engineering clusters specify these systems for their superior part-load performance under EU ecodesign requirements.
- Centrifugal:Dynamic compression through impeller acceleration serves large-scale HVAC installations in Frankfurt and Amsterdam data centers.
- Scroll:Orbiting spiral design enables oil-free operation with near-silent running, penetrating residential heat pump applications.
The dominant share belongs to rotary screw, while centrifugal is closing the gap fastest.
Application:
Cost tier stratification separates premium-specification food processing and automotive segments from price-sensitive manufacturing procurement.
- Manufacturing:General industrial compressed air supplies pneumatic automation, assembly tools, and material handling across European factory floors. German machinery OEMs in Bavaria and North Rhine-Westphalia drive specification toward variable-speed systems that reduce energy penalties during shift changes.
- HVAC:Climate control systems in commercial buildings and district heating networks require compressors optimized for refrigerant compatibility. France's renovation wave and Germany's building efficiency programs are accelerating replacement of fixed-speed equipment with oil-free and variable-speed alternatives.
- Automotive:Battery cell assembly and electric drivetrain production demand ISO 8573-1 Class 0 compressed air.
- Food Processing:Regulatory mandates under EFSA guidelines enforce oil-free compression to eliminate contamination risks in dairy and beverage packaging lines.
Manufacturing retains the largest installed base, though HVAC is expanding most quickly through retrofit mandates.
End User:
Customer type determines procurement modality, with industrial buyers favoring capital purchase and commercial segments shifting toward service contracts.
- Industrial:Heavy manufacturing, chemical processing, and metal fabrication operations constitute the core revenue pool. Facilities in Poland's Silesian industrial corridor are investing in greenfield compressed air infrastructure as manufacturing relocates from Western Europe.
- Commercial:Retail, healthcare, and hospitality facilities prioritize reliability guarantees over equipment ownership. Benelux and Nordic markets show strongest uptake of compressed air-as-a-service models that transfer operational risk to vendors.
- Residential:Heat pump integration is opening new demand channels beyond traditional industrial boundaries.
- Research:Laboratories and pharmaceutical development facilities require ultra-high-purity compressed gases with traceable certification.
Industrial users command the dominant share, while commercial is gaining share fastest through service model displacement.
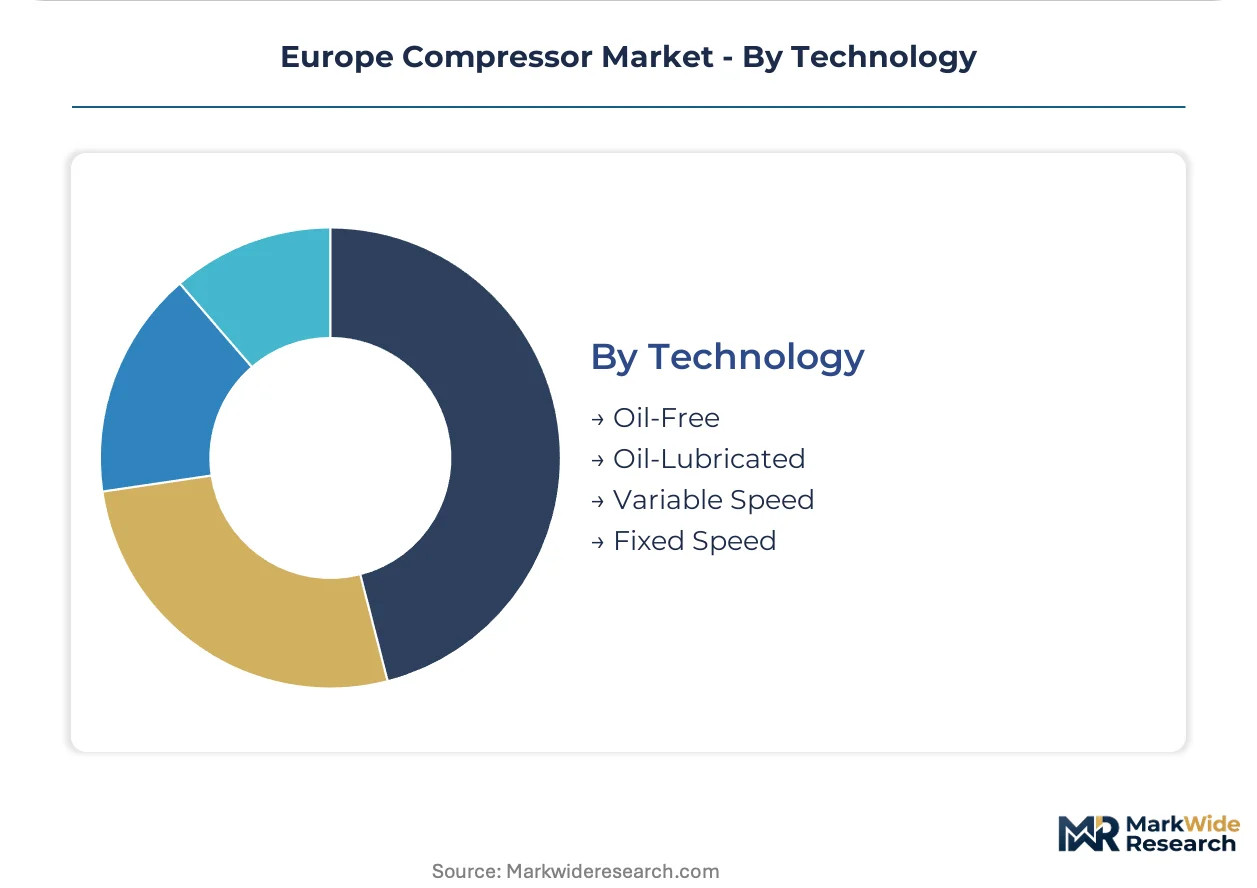
Technology:
Maturity gradients separate established oil-lubricated architectures from emerging variable-speed platforms that command technology premiums.
- Oil-Free:Elimination of lubricant contact with compressed air stream enables compliance with food, pharmaceutical, and electronics manufacturing standards. German and Italian OEMs have accelerated platform development to capture premium positioning as EFSA enforcement tightens.
- Oil-Lubricated:Flooded compression with mineral or synthetic lubricants maintains cost leadership in general industrial applications where air quality requirements permit minimal filtration.
- Variable Speed:Permanent magnet motors with frequency drives match output to demand, delivering Part Load Efficiency Index compliance.
- Fixed Speed:Constant-speed operation with load/unload modulation faces disqualification from new installations above threshold power ratings under tightening EU ecodesign regulations.
Oil-lubricated systems retain volume leadership, though variable speed is climbing the fastest as efficiency regulations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compressor manufacturers command pricing premiums that Polish and Czech suppliers cannot replicate, creating a two-tier procurement landscape across Central Europe. France and Italy occupy intermediate positions where specification sophistication varies by end-use sector. Nordic markets favor service-contract modalities over capital purchase.
Germany
Baden-Württemberg's precision engineering clusters and Bavaria's automotive electrification drive specification toward ISO 8573-1 Class 0 oil-free systems. The EU F-Gas Regulation accelerates HVAC retrofit demand in commercial buildings across Frankfurt and Munich. North Rhine-Westphalia's chemical processing corridor sustains installed base renewal for large-frame centrifugal compressors.
France
Île-de-France data centers and Auvergne-Rhône-Alpes pharmaceutical manufacturing anchor oil-free technology demand. The national building efficiency program generates renovation wave procurement for variable-speed HVAC compressors. Lyon and Grenoble industrial parks specify premium equipment with extended service guarantees.
Italy
Emilia-Romagna's packaging machinery OEMs and Lombardy's food processing lines enforce EFSA-compliant oil-free compression standards. REACH material restrictions compel sealing system redesigns among domestic manufacturers. Milan-Turin industrial corridor procurement favors Italian OEMs with localized service networks.
Poland
Silesian industrial corridor relocation from Western Europe generates greenfield compressed air infrastructure demand. EU Green Deal carbon border adjustments reshape total cost calculations for imported versus domestically sourced equipment. Greater Poland voivodeship manufacturing parks attract first-mover service network expansion.
Netherlands
Amsterdam and Rotterdam data center clusters adopt magnetic bearing centrifugal compressors to eliminate lubricant contamination risks. Compressed air-as-a-service models penetrate deepest here among mid-sized manufacturing facilities. Randstad logistics hubs specify equipment with predictive maintenance platform integration.
Europe Compressor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding margin control through captive casting and precision machining while component assemblers compete on first-cost positioning. The vendor base concentrates among three strategic tiers: full-system OEMs with dense aftermarket networks, specialized oil-free technology developers, and regional fabricators serving price-sensitive repair markets. Dominant competitive moves include M&A to close service network gaps and vertical integration into permanent magnet motor production.
Within the full-system OEM tier, Atlas Copco AB and KAESER KOMPRESSOREN occupy positions defined by aftermarket revenue dominance in German-speaking markets, while Siemens AG represents the industrial conglomerate archetype with cross-divisional technology leverage. These three exemplify how scale and service density create defensive moats against specialized challengers.
| Leading Market Players |
|---|
| Atlas Copco AB |
| KAESER KOMPRESSOREN |
| Siemens AG |
| Sulzer AG |
| Baker Hughes Co |
| Aerzener Maschinenfabrik GmbH |
| Ingersoll Rand |
| Burckhardt Compression Holding AG |
| BAUER COMP Holding GmbH |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance certification gates both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb redesign costs for low-GWP refrigerant compatibility while commanding premiums for validated architectures. Buyers in Germany's automotive belt pay configured-to-order premiums for ISO 8573-1 Class 0 oil-free systems, while price-sensitive repair shops in Southern Europe default to standard flooded compressors with minimal filtration.
Pricing Analysis
Configured-to-order pricing spreads 25-40% above standard catalog pricing for oil-free rotary screw systems with permanent magnet motors. Three-tier pricing structure across premium, standard, and economy levels stratifies by air quality certification, with Part Load Efficiency Index compliance commanding technology premiums. Pricing pressure stems from foundry consolidation in grey iron supply, compressing margins on airend housings. Tier 1 automotive buyers exhibit lowest price sensitivity, while independent Italian automotive repair shops drive economy-tier volume.
Supply Chain Analysis
Inventory buffers for permanent magnet motors have extended lead times to 16-22 weeks as neodymium processing concentrates in Chinese facilities. Grey iron and nodular iron casting draws from German, Italian, and Polish foundries, while precision-machined airend rotors hinge on Austrian and Swiss grinding equipment. Single-source vulnerability runs through rare earth magnet supply chains. Distribution runs through OEM-direct service networks in German-speaking markets and independent distributors in Iberia and the Balkans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable-speed drive penetration is disrupting fixed-speed incumbents as EU Ecodesign thresholds harden, compressing the transition window for technology migration. This regulatory inflection concentrates competitive advantage in firms with captive power electronics and thermal management capabilities.
For Market Incumbents: Fortify aftermarket revenue pools through predictive maintenance platform deployment and dense service network expansion in Poland's Silesian corridor. Atlas Copco and KAESER KOMPRESSOREN anchor defensible positions via installed base lock-in, but must accelerate permanent magnet motor backward integration to offset rare earth cost volatility. CE marking capacity constraints at notified bodies threaten product launch timelines. For New Entrants and Emerging Players: CE marking fast-track partnerships with German TÜVs enable rapid market entry before incumbents consolidate service gaps. The Iberian Peninsula and Balkan regions present the most penetrable white-space for independent aftermarket providers. Polish manufacturing relocation generates greenfield demand for mid-tier variable-speed systems with localized service guarantees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across oil-free technology platforms as EFSA enforcement tightens and R&D spend concentrates in magnetic bearing centrifugal architectures. Acquisition targets should profile specialized oil-free developers with validated refrigerant compatibility and sparse geographic coverage in Benelux or Nordic markets. The signal to watch is permanent magnet motor supply agreement announcements from Chinese processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive neodymium supply hedges against Chinese processing concentration and stabilizes variable-speed production costs. |
| Service Network Expansion in Poland | Silesian manufacturing relocation creates greenfield installed base capture before incumbent density hardens. |
| Predictive Maintenance Platform Deployment | Data-enabled uptime guarantees displace capital purchase models in Benelux and Nordic commercial segments. |
| CE Marking Fast-Track Partnership | Notified body capacity constraints extend conformity timelines, favoring pre-qualified suppliers in product launches. |
| Oil-Free Technology Platform Extension | EFSA enforcement tightens contamination standards in Emilia-Romagna packaging machinery and Lombardy dairy processing. |
Research Methodology
The analysis maps rotary screw, centrifugal, reciprocating, and scroll compressor sub-sectors, each validated through maintenance directors at German automotive OEMs, plant engineers in Poland's Silesian corridor, aftermarket service heads at Italian distributors, and procurement teams at French pharmaceutical manufacturers. Primary fieldwork combined with secondary validation from EU Ecodesign compliance databases, ECHA REACH substance restrictions, customs trade data for compressor imports, and SEC filings from listed industrial conglomerates. Bottom-up installed base estimates triangulated against top-down macroeconomic industrial production indices.
Consistency checks validated volume and value outputs against ECE industrial production statistics, Eurostat machinery investment surveys, and national building efficiency program disclosures across Germany and France. Segmentation modeling spanned product architecture, application vertical, end-user procurement modality, and technology maturity tier across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, regulatory phase-down schedules, and efficiency standard adoption curves. Forecast inputs incorporated F-Gas Regulation phase-down timelines and carbon border adjustment implementation progress.
Underlying assumptions cover stable neodymium supply chain continuity, continued EU Ecodesign threshold tightening, and Polish manufacturing relocation velocity, with deviation risk concentrated in rare earth export restrictions and notified body capacity bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Rental Air Compressors Market
Compressors
Portable Air Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Tandem Piston Compressors Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Air Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Regenerative Blowers Market
Compressors
LNG Compressor Market
Compressors
Portable Compressor Market
Compressors
Gas Compressors Market