
 Integrally Geared Centrifugal Compressor Market | 2026-2036
Integrally Geared Centrifugal Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Integrally Geared Centrifugal Compressor Market Foresight
Advanced polymer-composite labyrinth seals are broadening the operational envelope of integrally geared centrifugal compressors, cutting parasitic losses that once favored traditional metallic sealing arrays. Atlas Copco AB leverages its rotary compression R&D pipeline to dominate the oil-free product tier. Siemens Energy AG anchors European demand through captive service networks tied to petrochemical complexes. MAN Energy Solutions SE specializes in multi-stage configurations for natural gas processing, where pressure ratios exceed conventional single-impeller limits.
An integrally geared centrifugal compressor employs multiple pinion shafts driven from a central bull gear, enabling each impeller to spin at optimal speed for its pressure ratio while sharing a single motor input. Typical discharge pressures span 50 to 400 bar, with polytropic efficiencies reaching 85 percent in well-matched stage groupings; this architecture serves process industries requiring high-volume, oil-free gas compression with minimal footprint. Gas compressors command the largest revenue pool due to entrenched demand from pipeline transmission and underground storage injection, though oil-free compressors are gaining fastest as food-grade and pharmaceutical air standards tighten. Turbo compressors occupy the premium tier in power generation feedwater deaeration, where continuous-duty reliability contracts carry 15-year service obligations.
EPA methane regulations and the EU F-Gas Regulation are forcing compressor packagers to certify leak-free crankcases and shift refrigerant compressor lines toward lower-global-warming-potential working fluids. ISO 10439 and API 617 standards govern material selection and rotor dynamics verification, creating compliance barriers that favor incumbents with in-house testing loops. Stakeholders must weigh backward integration into precision gear grinding against partnerships with specialized drivetrain suppliers as lead times for high-speed pinion sets extend.
Market Dynamics
The integrally geared centrifugal compressor market faces a structural squeeze between EPA methane mandates tightening seal requirements and hydrogen liquefaction projects demanding higher pressure ratios than legacy designs can deliver. This tension forces packagers to reconfigure stage geometries while maintaining oil-free certification.
Growth Catalysts
- Hydrogen liquefaction buildout:Cryogenic hydrogen trains require discharge pressures above 200 bar, pulling integrally geared architectures into energy transition infrastructure. Germany's industrial gas cluster investments are accelerating replacement cycles for aging reciprocating units.
- EU F-Gas Regulation:Refrigerant compressor lines must shift to lower-global-warming-potential working fluids, favoring oil-free integrally geared designs that eliminate lubricant contamination risks in closed-loop systems.
- Polymer-composite labyrinth seals:Advanced seal materials cut parasitic losses that once favored traditional metallic arrays, expanding the operational envelope into food-grade and pharmaceutical air standards.
Market Restraints
- High-speed pinion supply concentration:Lead times for precision-ground pinion sets extend 18-24 months as specialized gear grinding capacity concentrates in Central European machine shops.
- API 617 compliance costs:Material selection and rotor dynamics verification requirements create capital barriers for new entrants lacking in-house testing loops.
- Magnetic bearing substitution:Active magnetic bearing turbocompressors eliminate gearbox maintenance entirely in sub-50 MW applications, threatening the lower end of the integrally geared range.
Strategic Opportunities
- Carbon capture compression:Post-combustion CO2 capture at 110-150 bar injection pressures matches the pressure-ratio sweet spot of multi-stage integrally geared trains, opening utility-scale power generation.
- India's PLI scheme:Production-linked incentives for green hydrogen create captive demand for domestic compressor assembly, rewarding early joint ventures with local precision manufacturing partners.
- Digital twin convergence:Real-time rotor dynamics monitoring fused with predictive maintenance platforms enables performance-guarantee contracts extending 15-year service obligations.
Industry Challenges
- Precision gear grinding talent scarcity:The specialized skill set for high-speed pinion manufacturing sits with an aging workforce in Bavaria and Baden-Württemberg machine shops.
- Legacy control system integration:DCS retrofit requirements in brownfield petrochemical complexes add engineering hours that compress project margins.
- ISO 10439 certification timelines:Third-party witness testing for rotor stability verification extends delivery schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrally Geared Centrifugal Compressor Market |
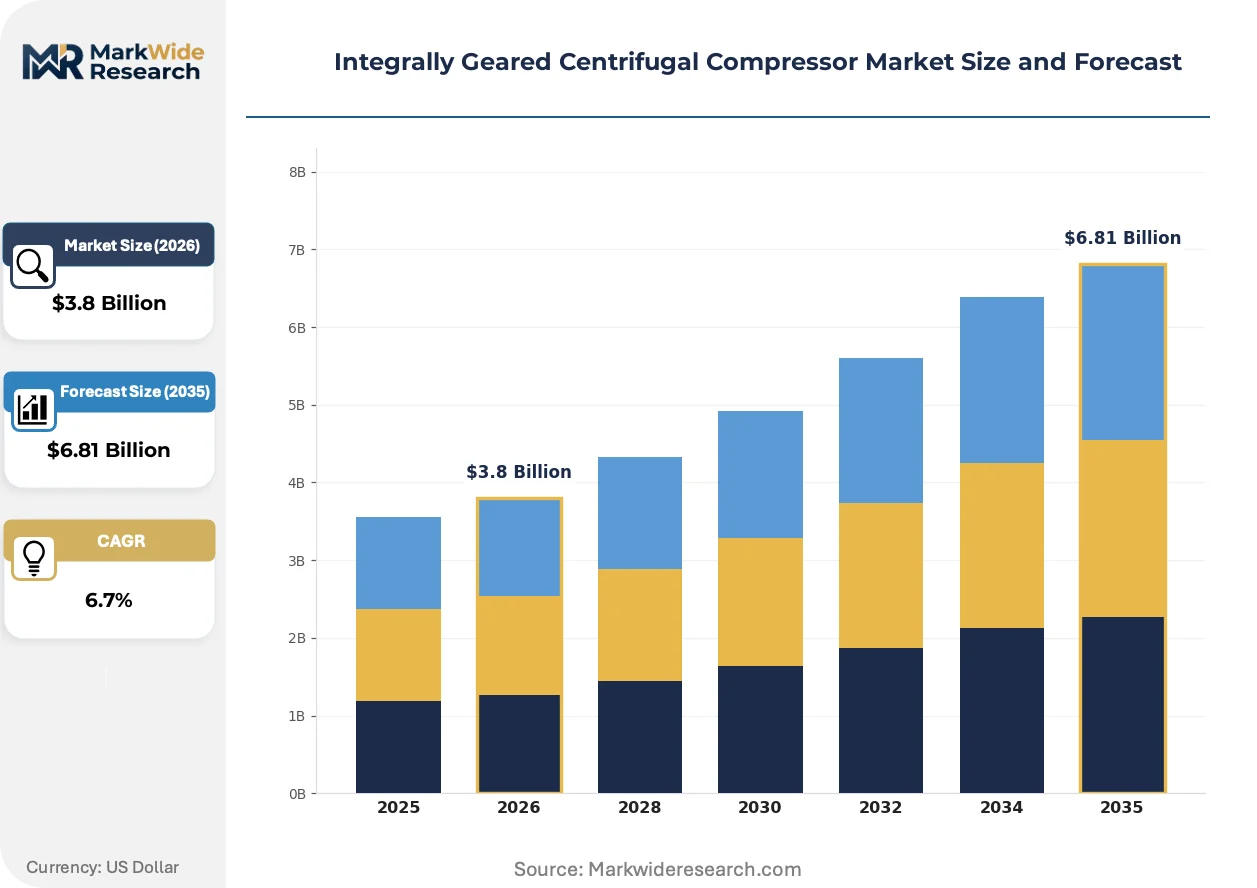
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Compressors, Oil-Free Compressors, Turbo Compressors, Multi-Stage Compressors Application: Natural Gas Processing, Chemical Processing, Power Generation, HVAC End User: Energy Sector, Manufacturing, Petrochemical Industry, Aviation Technology: Rotary Compression, Constant Pressure, Variable Speed Drive, High Efficiency |
| Companies Covered | Ingersoll Rand Inc., Mitsubishi Heavy Industries Ltd., Atlas Copco AB, IHI Corporation, Kobe Steel Ltd., Siemens Energy AG, Baker Hughes Company, FS-Elliott Co. LLC, MAN Energy Solutions SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrally Geared Centrifugal Compressor Market Shifts & Advancements
Active materials and digital instrumentation are compressing the traditional trade-off between efficiency and reliability in high-speed compression. Packagers now embed sensing directly into rotating components.
Additive manufacturing of titanium impeller wheels is rewriting the economics of low-volume, high-performance stage customization. Hydrogen liquefaction developers in the US Gulf Coast specify topology-optimized blading that cuts machining time by 60 percent. This technology is compressing minimum economic order quantities from ten units to two.
EPA methane regulations finalized in 2024 mandate sealed crankcases and quarterly leak detection for natural gas processing compressors. The rule forces packagers to certify oil-free architectures or install costly vapor recovery units. Pipeline transmission operators in the Permian Basin are accelerating procurement of hermetic designs to avoid ongoing monitoring costs.
Long-term availability contracting is displacing spot purchasing for high-pressure compression trains. Petrochemical complexes in the Antwerp-Rotterdam-Ghent cluster now specify 15-year parts-and-service bundles upfront, transferring operational risk to OEM service networks. This shift concentrates aftermarket revenue with vendors maintaining captive regional parts depots.
Integrally Geared Centrifugal Compressor Market Segmentation
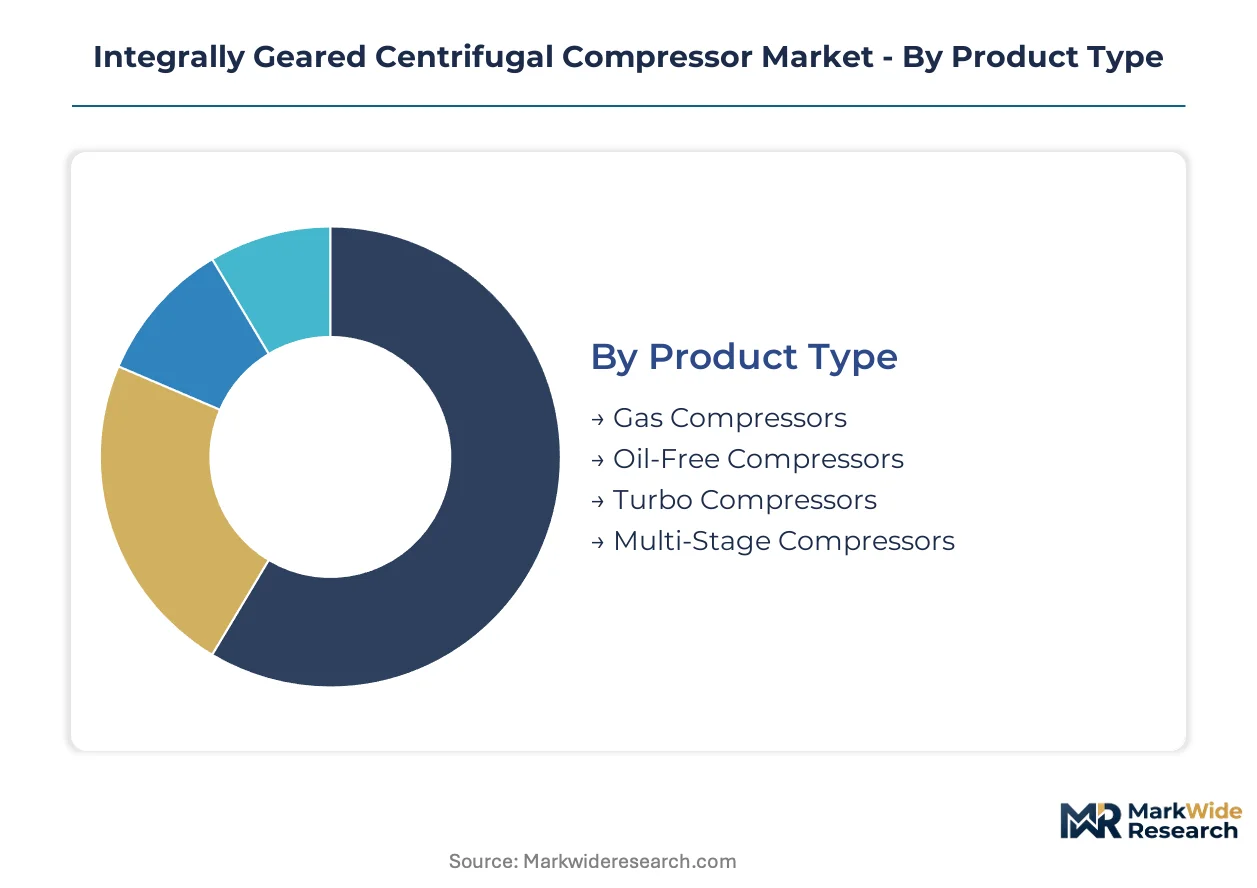
Segmentation in integrally geared centrifugal compressors reveals distinct capital deployment patterns across product architectures and end-use requirements. Equipment specifications diverge sharply between pipeline transmission duty and pharmaceutical-grade air systems, driving specialized procurement channels.
Product Type:
Capital intensity peaks in multi-stage configurations requiring precision-ground pinion sets and extended rotor dynamics verification timelines.
- Gas Compressors:These units handle hydrocarbon streams at discharge pressures spanning 50 to 400 bar, with polytropic efficiencies reaching 85 percent in optimized stage groupings. Demand concentrates in Germany's industrial gas cluster investments, where pipeline transmission and underground storage injection operators are accelerating replacement cycles for aging reciprocating units.
- Oil-Free Compressors:Sealed architectures eliminate lubricant contamination risks through hermetic crankcase designs certified under tightening EPA methane emissions standards. Food-grade and pharmaceutical air specifications in the Antwerp-Rotterdam-Ghent cluster are pulling procurement toward these configurations.
- Turbo Compressors:Premium-tier units serve power generation feedwater deaeration with continuous-duty reliability contracts.
- Multi-Stage Compressors:MAN Energy Solutions SE specializes in these configurations for natural gas processing where pressure ratios exceed single-impeller limits.
Most installed capacity flows through Gas Compressors. Expansion is steepest in Oil-Free Compressors.
Application:
Application selection tracks pressure ratio requirements and process fluid compatibility, with hydrogen liquefaction buildout reshaping demand distribution.
- Natural Gas Processing:Post-combustion CO2 capture at 110-150 bar injection pressures matches the pressure-ratio sweet spot of multi-stage integrally geared trains, opening utility-scale power generation opportunities.
- Chemical Processing:Process industries require high-volume, oil-free gas compression with minimal footprint; polymer-composite labyrinth seals are broadening operational envelopes previously limited to metallic sealing arrays.
- Power Generation:Feedwater deaeration applications specify 15-year service obligations.
- HVAC:Refrigerant compressor lines must shift to lower-global-warming-potential working fluids under EU F-Gas Regulation.
Procurement volume concentrates in Natural Gas Processing. Chemical Processing is climbing the fastest.
End User:
End-user procurement patterns reflect risk transfer preferences, with petrochemical complexes increasingly specifying long-term parts-and-service bundles.
- Energy Sector:Hydrogen liquefaction developers on the US Gulf Coast specify topology-optimized titanium impeller wheels produced through additive manufacturing, cutting machining time substantially.
- Petrochemical Industry:Brownfield complexes in the Antwerp-Rotterdam-Ghent cluster now require DCS retrofit engineering that compresses project margins.
- Manufacturing:India's PLI scheme for green hydrogen creates captive demand for domestic compressor assembly.
- Aviation:Specialized applications demand ISO 10439 certification with third-party witness testing extending delivery schedules.
The Petrochemical Industry holds the largest installed base. The Energy Sector is gaining share fastest.
Technology:
Technology selection determines maintenance burden and operational envelope, with active magnetic bearings threatening substitution at the lower power range.
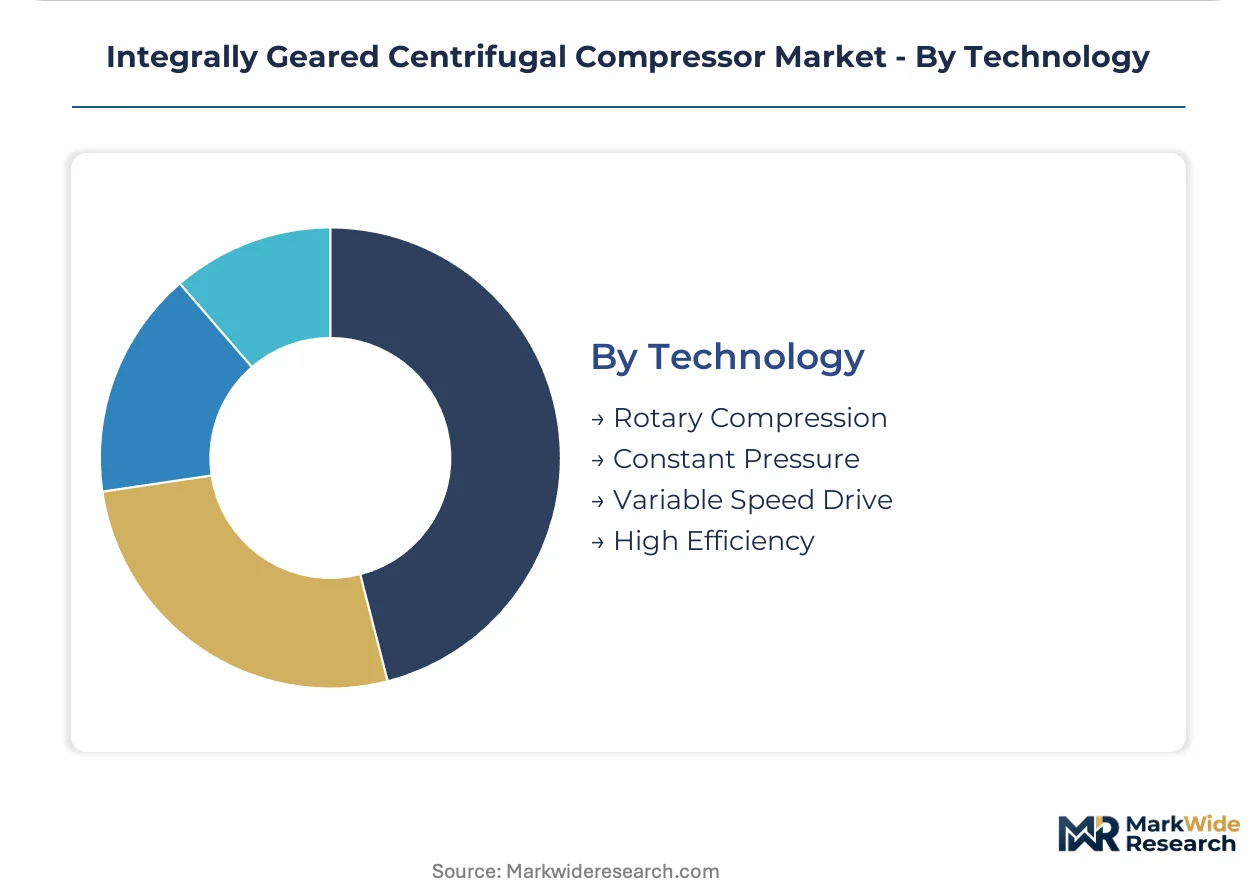
- Variable Speed Drive:Real-time rotor dynamics monitoring fused with predictive maintenance platforms enables performance-guarantee contracts extending 15-year service obligations.
- High Efficiency:Advanced polymer-composite labyrinth seals cut parasitic losses that once favored traditional metallic arrays.
- Rotary Compression:Atlas Copco AB leverages this R&D pipeline to dominate the oil-free product tier.
- Constant Pressure:Baseline architecture for standard industrial applications.
Variable Speed Drive deployments dominate new orders. High Efficiency configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Antwerp-Rotterdam-Ghent industrial corridor concentrates procurement volume for high-pressure compression trains serving petrochemical and hydrogen liquefaction applications.
United States
Hydrogen liquefaction developers on the Gulf Coast specify topology-optimized titanium impeller wheels produced through additive manufacturing. The EPA's 2024 methane regulations mandate sealed crankcases and quarterly leak detection for natural gas processing compressors. Pipeline transmission operators in the Permian Basin are accelerating procurement of hermetic designs to avoid ongoing monitoring costs.
Germany
Industrial gas cluster investments are accelerating replacement cycles for aging reciprocating units across chemical processing facilities. The EU F-Gas Regulation forces refrigerant compressor lines toward lower-global-warming-potential working fluids. Bavarian and Baden-Württemberg machine shops concentrate specialized gear grinding capacity for high-speed pinion sets with 18-24 month lead times.
India
The PLI scheme for green hydrogen creates captive demand for domestic compressor assembly partnerships with local precision manufacturing partners. Central Electricity Authority guidelines are tightening efficiency standards for power generation feedwater systems. Manufacturing investment is concentrating in Gujarat and Maharashtra where petrochemical complexes require DCS retrofit engineering.
China
Dual carbon goals under MIIT directives are driving carbon capture compression deployment at 110-150 bar injection pressures matching multi-stage integrally geared trains. National hydrogen infrastructure buildout requires discharge pressures above 200 bar for cryogenic liquefaction trains. Yangtze River Delta industrial zones are specifying 15-year parts-and-service bundles transferring operational risk to OEM service networks.
Saudi Arabia
Utility-scale power generation projects are integrating post-combustion CO2 capture systems requiring multi-stage compression architectures. The national regulator is aligning industrial emissions standards with EU F-Gas Regulation frameworks for refrigerant applications. Eastern Province petrochemical complexes are deploying oil-free configurations to meet tightening process air quality specifications.
Integrally Geared Centrifugal Compressor Market Competitive Landscape
Long-term availability contracting dominates the current landscape as petrochemical complexes displace spot purchasing with 15-year parts-and-service bundles. The vendor base concentrates around three tiers: diversified industrial conglomerates with captive service networks, specialized compressor packagers with precision gear grinding capabilities, and emerging regional assemblers leveraging PLI scheme incentives. Strategic archetypes include technology licensors pursuing backward integration into precision manufacturing and mid-scale specialists defending position through ISO 10439 certification speed. Geographic expansion partnerships and additive manufacturing licensing represent the dominant competitive moves.
Within the diversified industrial tier, Atlas Copco AB and Siemens Energy AG exemplify contrasting strategic positions. Atlas Copco leverages rotary compression R&D pipelines to anchor oil-free product tiers, while Siemens Energy ties European demand to captive service networks at petrochemical complexes. MAN Energy Solutions SE occupies the multi-stage configuration specialist position where pressure ratios exceed conventional single-impeller limits. Japanese industrial conglomerates including Mitsubishi Heavy Industries Ltd. and IHI Corporation represent the precision manufacturing archetype with concentrated high-speed pinion production capabilities.
| Leading Market Players |
|---|
| Ingersoll Rand Inc. |
| Mitsubishi Heavy Industries Ltd. |
| Atlas Copco AB |
| IHI Corporation |
| Kobe Steel Ltd. |
| Siemens Energy AG |
| Baker Hughes Company |
| FS-Elliott Co. LLC |
| MAN Energy Solutions SE |
| Others |
Supply & Pricing Matrix
Petrochemical complexes in the Antwerp-Rotterdam-Ghent cluster anchor pricing power through 15-year parts-and-service bundles that transfer operational risk to OEM captive service networks. This concentration of long-term contracting among integrated industrial buyers compresses spot-market liquidity and elevates vendor switching costs.
Pricing Analysis
Input-cost pass-through from precision-ground pinion sets and titanium impeller materials shapes contract structures across the market. Three-tier pricing structure across premium, standard, and economy levels separates API 617-certified multi-stage trains from ISO 10439 baseline units and non-certified regional assembly. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because additive manufacturing licensing fees and extended rotor dynamics verification timelines inflate engineering overhead. Pipeline transmission operators exhibit highest price sensitivity due to commoditized compression specifications, while hydrogen liquefaction developers show lowest sensitivity given project finance structures that absorb capital intensity.
Supply Chain Analysis
Dual-sourcing requirements for high-speed pinion sets mandate multi-supplier qualification across German and Japanese machine shops as lead time vulnerability concentrates in Bavarian and Baden-Württemberg grinding capacity. Component sourcing draws from Germany for precision gears, Japan for advanced bearing assemblies, and the United States for topology-optimized titanium impellers produced through additive manufacturing. Single-source vulnerability in specialized gear grinding talent pools creates structural exposure as the aging workforce concentrates in Central European facilities. Distribution runs through OEM captive service networks with regional parts depots rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrally geared centrifugal compressor market functions as a regulatory compounder where EPA methane mandates and EU F-Gas Regulation revisions continuously reset equipment replacement cycles and certification thresholds.
For Market Incumbents: Deploy backward integration into precision gear grinding capacity to capture margin erosion from 18-24 month pinion set lead times. Anchor defensive positioning through ISO 10439 certification speed against emerging regional assemblers in India leveraging PLI scheme incentives. Magnetic bearing turbocompressors threaten substitution below 50 MW; incumbents must accelerate polymer-composite seal R&D to expand oil-free operational envelopes into food-grade and pharmaceutical air standards. For New Entrants and Emerging Players: Begin with carbon capture compression at 110-150 bar injection pressures where multi-stage integrally geared trains match utility-scale power generation specifications without API 617 compliance barriers. India's PLI scheme for green hydrogen offers the most penetrable geography through joint ventures with Gujarat and Maharashtra precision manufacturing partners. Go-to-market execution should target DCS retrofit engineering contracts in brownfield petrochemical complexes where legacy control system integration compresses incumbent project margins. For Investors and Strategic Acquirers: Industrial conglomerates with captive service networks are the most active acquirer in this space, consolidating aftermarket revenue concentration. Long-term viability across the projection horizon rests on 15-year service obligation penetration and hydrogen liquefaction infrastructure buildout. Acquisition targets should exhibit precision gear grinding capabilities or additive manufacturing licensing for titanium impeller topology optimization. The signal to watch is EPA enforcement intensity on quarterly leak detection mandates for natural gas processing compressors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gear Grinding | Captures margin from 18-24 month pinion set lead times concentrated in German machine shops. |
| Additive Manufacturing Licensing for Titanium Impellers | Compresses minimum economic order quantities from ten units to two for hydrogen liquefaction developers. |
| Long-Term Parts-and-Service Bundling | Transfers operational risk from Antwerp-Rotterdam-Ghent petrochemical complexes to OEM captive networks. |
| Joint Ventures under India's PLI Scheme | Creates domestic assembly capacity for green hydrogen infrastructure buildout in Gujarat and Maharashtra. |
| Polymer-Composite Labyrinth Seal Development | Expands oil-free operational envelope into food-grade and pharmaceutical air standards tightening under EPA methane regulations. |
Research Methodology
Bottom-up hydrogen liquefaction and carbon capture project modeling reconciled against top-down compressor packager order book tracking forms the analytical core. Primary interviews with maintenance directors at petrochemical complexes, OEM procurement teams, aftermarket service heads, and plant engineers in natural gas processing facilities combined with secondary validation from EPA regulatory filings, EU ETS compliance databases, and customs data on high-speed pinion set imports. The analysis triangulates equipment specifications, certification timelines, and regional replacement cycle acceleration patterns.
Input-output matrix framing connects stage configuration counts to discharge pressure requirements across natural gas processing, chemical processing, power generation, and hydrogen liquefaction applications. Segmentation dimensions modeled include product architecture, pressure ratio tier, end-use industry, certification standard, and regional regulatory cluster. CAGRs derive from equipment replacement cycle velocity and infrastructure investment trajectories. Forecast inputs incorporate EU F-Gas Regulation refrigerant line conversion schedules and EPA methane rule enforcement intensity across the projection horizon.
Several conditions sit outside the modeled scope, including unannounced magnetic bearing turbocompressor cost reductions below 50 MW, sudden precision gear grinding capacity expansion in non-traditional manufacturing geographies, and geopolitical disruptions to titanium sponge supply chains. Forecasts reflect assumptions on regulatory enforcement continuity and hydrogen liquefaction project financing availability. Deviation in EPA quarterly leak detection mandate enforcement or EU carbon border adjustment implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Rental Air Compressors Market
Compressors
Liquid Ring Compressors Market
Compressors
Hydrogen Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Centrifugal Air Compressor Market
Compressors
Axial Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
USA Scroll Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Air Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Gas Compressors Market