
 AC Electric Vehicle Charging Station Market | 2026-2036
AC Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
AC Electric Vehicle Charging Station Market Insights
The EU Green Deal is expanding mandates for building-integrated EV readiness across commercial and residential developments. ChargePoint leverages its software-integrated hardware platform to dominate North American workplace and retail deployments. ABB E-mobility anchors European utility-scale projects through its Terra AC portfolio. Siemens sustains R&D intensity in bidirectional charging interfaces for grid-stabilization applications.
AC electric vehicle charging stations convert grid alternating current to vehicle-compatible power through onboard rectifiers, typically delivering 3.7 kW to 22 kW via single-phase or three-phase connections for overnight or dwell-time replenishment. Wall-mounted chargers occupy the largest installed base due to lower hardware and installation costs in residential and workplace settings. Smart chargers represent the fastest-expanding category as electric mobility operators demand load-balancing, payment integration, and remote diagnostics. Fleet depots concentrate margin pools because volume procurement agreements and long-term service contracts reduce customer acquisition costs for manufacturers.
The EU F-Gas Regulation and CE marking requirements shape product compliance for equipment sold across European member states, while China's GB standards and NMPA-aligned quality protocols govern domestic manufacturing and import certification. The US NHTSA and state-level building codes increasingly mandate EV-ready infrastructure in new construction, channeling demand toward pre-wired AC installations. Stakeholders must monitor how grid interconnection standards evolve to determine whether bidirectional-capable AC hardware becomes a baseline requirement or premium differentiator.
Market Dynamics
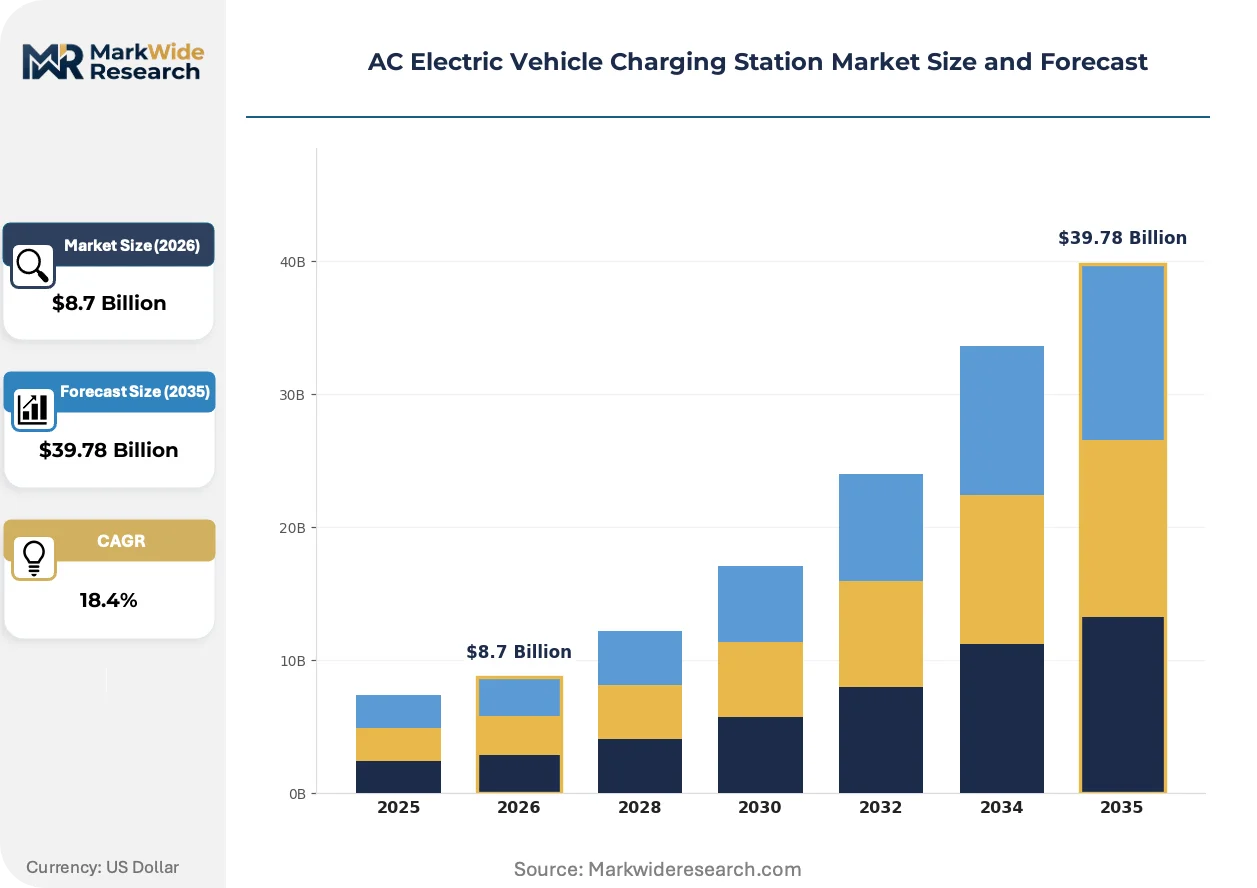
Fleet electrification mandates and building-integrated charging requirements are compressing deployment timelines across residential, workplace, and depot segments. Hardware manufacturers face simultaneous pressure to reduce unit costs while embedding bidirectional power electronics and cloud-native management platforms.
Growth Catalysts
- EU Green Deal transport targets:Binding emission reductions for commercial fleets are compelling logistics operators to install overnight AC infrastructure at depots.
- Workplace charging subsidies:Germany's tax-advantaged employer-provided charging is accelerating wall-mounted unit deployment across office parks.
- Smart load-balancing algorithms:Grid operators in California are incentivizing managed charging to defer distribution upgrades.
Market Restraints
- Copper and silicon carbide cost volatility:Power semiconductor shortages and metal price swings constrain margin expansion for hardware producers.
- Installation labor scarcity:Certified electrician availability bottlenecks deployment velocity in dense urban markets.
- Onboard charger limitations:Vehicle-side rectifier capacity caps (typically 11-22 kW) prevent AC stations from delivering faster replenishment regardless of station rating.
Strategic Opportunities
- India's commercial vehicle electrification:State-level mandates for urban bus fleets create depot charging infrastructure gaps.
- V2H bidirectional integration:Home energy management systems converging with AC chargers open residential storage-as-a-service models.
- Retail parking monetization:Grocery and big-box chains are deploying dwell-time charging to extend customer visit duration.
Industry Challenges
- Interoperability certification delays:Multi-vendor testing for ISO 15118-2 Plug and Charge integration extends product launch timelines.
- Grid connection queue backlogs:Utility interconnection studies for multi-port depot installations stretch 12-18 months in high-demand service territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Electric Vehicle Charging Station Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Chargers, Pedestal Chargers, Smart Chargers, Portable Chargers, Compact Chargers Connector Type: Type 1, Type 2, J1772, Mennekes, Tesla Connector Application: Residential Parking, Commercial Complexes, Fleet Depots, Public Parking Lots, Workplace Parking End User: Electric Mobility Operators, Parking Service Providers, Fleet Managers, Real Estate Developers, Retail Establishments |
| Companies Covered | ChargePoint, ABB E-mobility, Siemens, Schneider Electric, Alfen, Wallbox, Blink Charging, bp pulse, EVBox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Electric Vehicle Charging Station Market Trends and Innovations
Intelligent power management and seamless vehicle-grid communication are displacing passive charging hardware. Software-defined charging platforms now determine competitive positioning more than raw power output ratings.
Autonomous charge scheduling is automating fleet depot operations. Cloud-based energy management systems coordinate hundreds of AC ports against time-of-use tariffs and vehicle departure requirements. Logistics operators in the Netherlands and California are deploying these platforms to minimize electricity procurement costs. The technology is automating what previously required manual dispatch decisions, compressing operational staffing models.
CE marking under the EU F-Gas Regulation is tightening refrigerant-based thermal management requirements for AC charging equipment. Manufacturers must redesign cooling systems or eliminate active cooling entirely for lower-power units. The German and French certification bodies are enforcing these standards most stringently, pushing suppliers toward passive thermal designs.
Subscription-based charging-as-a-service is displacing capital purchase models among small and mid-sized fleet operators. Hardware vendors in the United States and Germany are bundling installation, maintenance, and energy management under per-port monthly fees. This shift transfers utilization risk from buyers to suppliers while locking in multi-year revenue streams.
AC Electric Vehicle Charging Station Market Segmentation
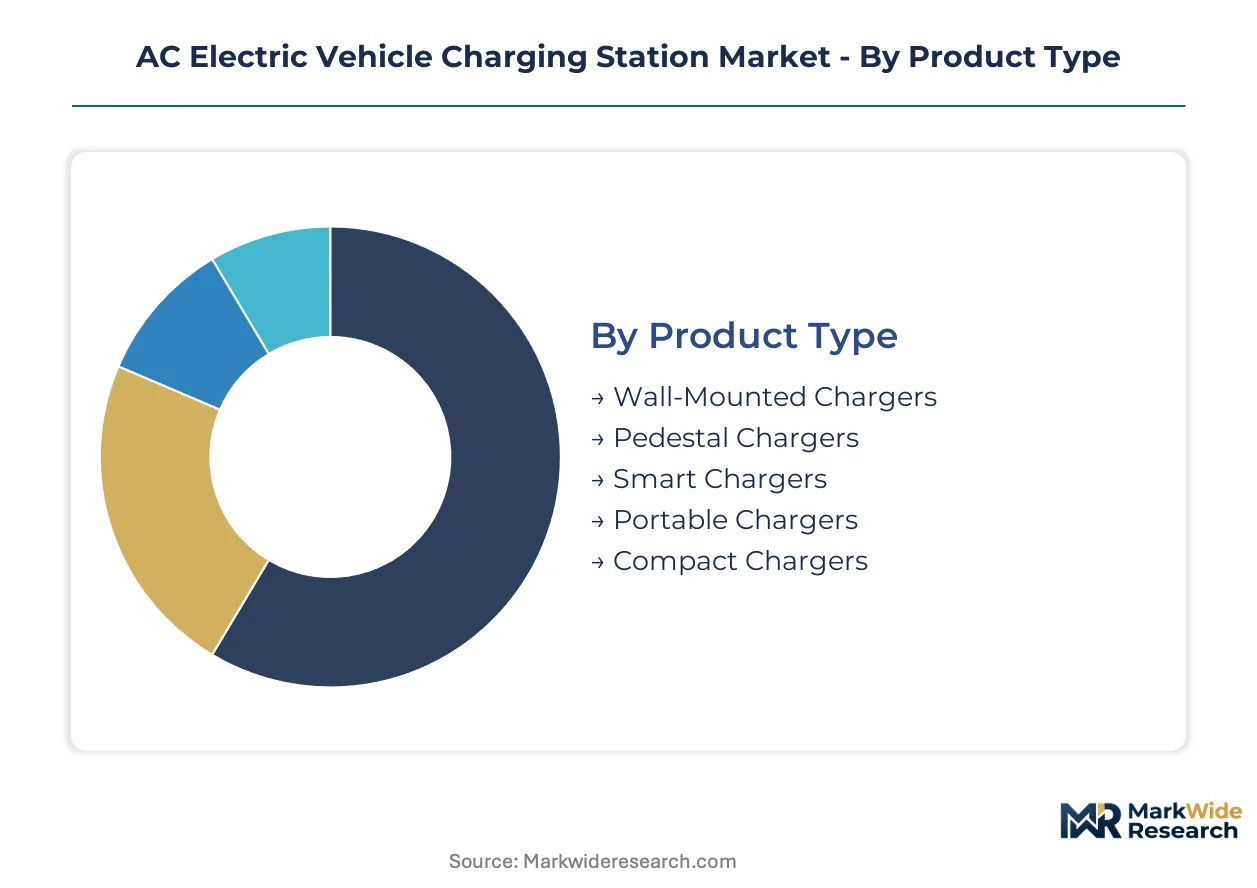
Segmentation in the AC EV charging market reveals how hardware specifications, installation constraints, and user economics split demand across divergent deployment models. Product architecture and connector standards determine interoperability boundaries, while application context shapes procurement scale and service intensity.
Product Type:
Physical form factor and intelligence integration define the hardware hierarchy across residential, commercial, and fleet deployments.
- Wall-Mounted Chargers:Fixed installations attach directly to building structures, delivering 3.7 kW to 22 kW through single-phase or three-phase connections. Germany's tax-advantaged workplace charging subsidies have concentrated wall-mounted deployment across office parks and residential garages, though installation labor scarcity in dense urban markets constrains rollout velocity.
- Smart Chargers:Cloud-connected units embed load-balancing algorithms, payment integration, and remote diagnostics capabilities. California's grid operators incentivize managed charging programs to defer distribution upgrades, directing fleet operators and commercial developers toward intelligent hardware that coordinates against time-of-use tariffs.
- Pedestal Chargers:Freestanding posts serve curbside and open-lot installations where wall attachment is impractical. Municipalities in the Netherlands deploy these for public parking networks.
- Portable Chargers:Mobile units with interchangeable plugs address emergency and travel use cases. Ride-hailing drivers in India carry these as backup infrastructure.
- Compact Chargers:Reduced-footprint designs target space-constrained urban installations. Japanese multi-unit residential developments specify these for parking bay retrofits.
Mature deployment sits with wall-mounted chargers in residential and workplace settings. Newer deployment is concentrated in smart chargers as grid-interactive capabilities become procurement requirements.
Connector Type:
Regional regulatory frameworks and vehicle manufacturer specifications have fragmented physical interface standards across markets.
- Type 2:The European standard supports three-phase power delivery up to 22 kW through the Mennekes interface. EU member states mandate Type 2 compatibility for public charging subsidies, compelling hardware vendors to prioritize this specification for CE-marked equipment under the EU F-Gas Regulation.
- J1772:The North American standard delivers single-phase AC power through a five-pin configuration. NHTSA-aligned state building codes in California and New York require J1772-ready pre-wiring in new construction, channeling residential and commercial demand toward this connector family.
- Type 1:Single-phase standard prevalent in Japanese and early North American vehicles. Legacy fleet compatibility sustains residual demand.
- Mennekes:German-engineered variant of Type 2 with enhanced weather sealing. KBA certification requirements favor this specification for heavy-duty commercial installations.
- Tesla Connector:Proprietary interface transitioning toward NACS standardization. Tesla's opening of the connector specification to other manufacturers is reshaping procurement patterns among US fleet operators.
Connector standardization is concentrating around Type 2 in Europe and J1772 in North America, with Tesla's NACS emerging as a potential convergence point in the United States.
Application:
Site characteristics and dwell-time economics segment deployment contexts from overnight replenishment to opportunistic top-up charging.
- Fleet Depots:Centralized facilities serving logistics and ride-hailing operators with dozens to hundreds of AC ports. Volume procurement agreements and long-term service contracts reduce customer acquisition costs for manufacturers, concentrating margin pools in this segment despite extended grid interconnection queue backlogs stretching 12-18 months.
- Workplace Parking:Employer-subsidized installations capitalize on multi-hour vehicle dwell periods. Germany's tax-advantaged charging benefits accelerate deployment across corporate campuses.
- Residential Parking:Single-family home and multi-unit dwelling installations dominate unit volumes. US state-level building codes increasingly mandate EV-ready infrastructure in new construction.
- Commercial Complexes:Retail and mixed-use developments deploy charging as amenity infrastructure. Grocery chains in California use dwell-time charging to extend customer visit duration.
- Public Parking Lots:Municipal and third-party operated facilities serve opportunistic charging needs. Revenue uncertainty constrains operator enthusiasm relative to captive-use applications.
Revenue concentration favors fleet depots and workplace parking where utilization predictability supports service contracting models. Public parking lots remain challenging due to fragmented operator structures and pricing transparency gaps.
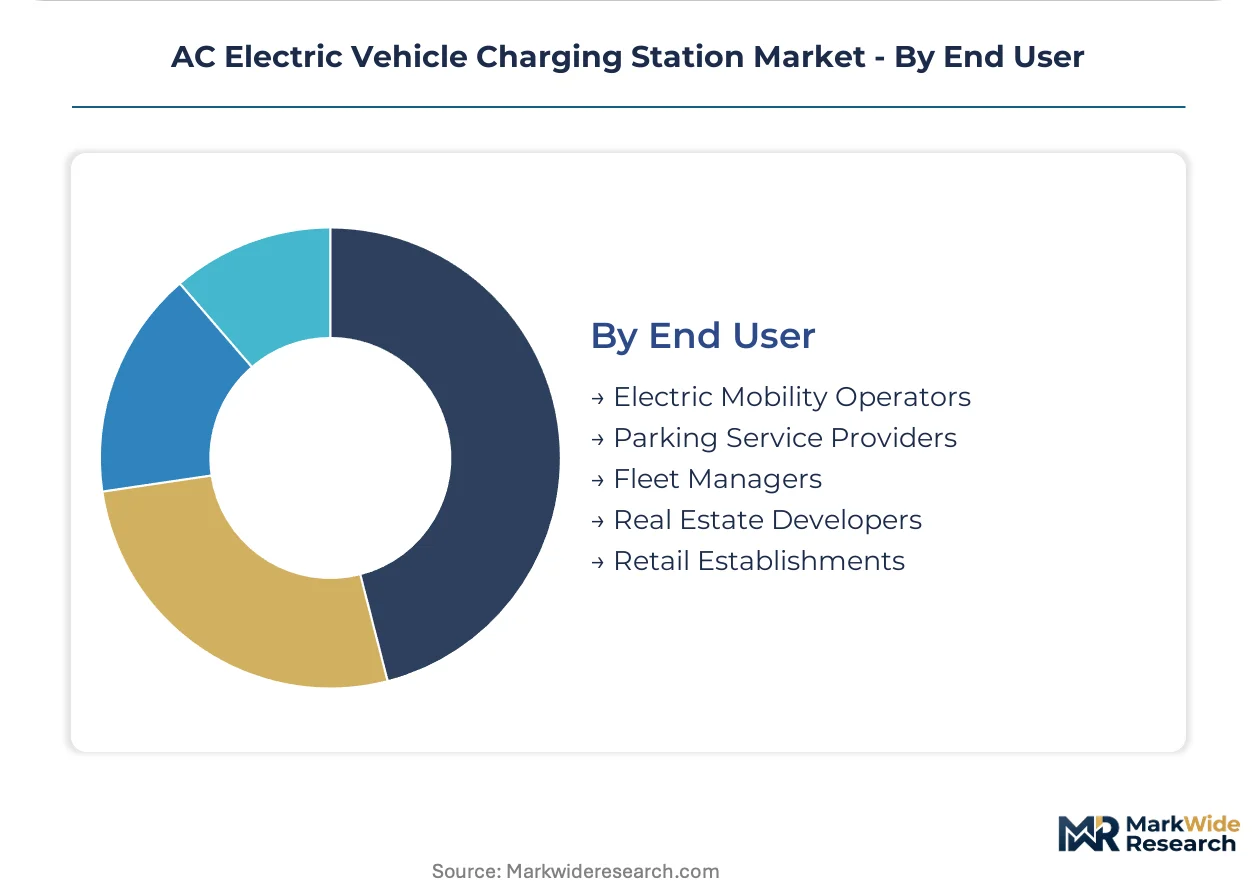
End User:
Procurement authority and operational sophistication determine how charging infrastructure investment decisions flow through the value chain.
- Electric Mobility Operators:Specialized firms managing charging networks as core business. Subscription-based charging-as-a-service models are displacing capital purchases among smaller operators in the United States and Germany.
- Fleet Managers:Logistics and ride-hailing operators electrifying vehicle pools. Binding EU Green Deal emission targets for commercial transport compel overnight depot infrastructure investment.
- Parking Service Providers:Operators integrating charging into existing facility management. The EU Green Deal's building-integrated EV readiness mandates expand their addressable market.
- Real Estate Developers:Construction-phase installation of EV-ready infrastructure. Pre-wiring requirements in new building codes shift their procurement toward lower-power AC units.
- Retail Establishments:Big-box and grocery chains deploying customer-facing charging. Visit duration extension drives business case development.
Procurement sophistication is highest among electric mobility operators and fleet managers with dedicated energy management staff. Retail establishments represent the fastest-expanding customer category as dwell-time monetization strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication concentrates in Germany and China, while consumption spreads across fleet depots and workplace installations in multiple markets. The EU Green Deal and state-level building codes reshape procurement patterns differently across jurisdictions.
Germany
Fleet depot electrification and workplace charging subsidies drive hardware demand. KBA certification requirements under the EU F-Gas Regulation enforce stringent Type 2 connector standards. The Ruhr industrial corridor and Bavarian manufacturing clusters host concentrated AC charging production for European export markets.
United States
State building codes in California and New York mandate EV-ready pre-wiring in new construction. NHTSA-aligned regulations channel demand toward J1772-compatible installations. The San Francisco Bay Area and Southern California deploy dense urban charging networks for logistics and ride-hailing fleets.
China
Domestic electric vehicle production scales drive AC charging infrastructure deployment. GB standards and NMPA-aligned quality protocols govern manufacturing certification. The Yangtze River Delta and Pearl River Delta manufacturing bases supply hardware for domestic fleet electrification and export markets.
Netherlands
Municipal parking network expansion and logistics fleet electrification create procurement volume. CE marking requirements under EU F-Gas Regulation shape equipment compliance. The Randstad urban corridor leads curbside pedestal charger deployment for public charging access.
India
State-level mandates for urban bus fleet electrification generate depot charging demand. The country's national automotive regulator enforces evolving quality protocols for imported and domestic equipment. Maharashtra and Karnataka deploy early AC infrastructure for commercial vehicle electrification pilots.
AC Electric Vehicle Charging Station Market Competitive Landscape
The competitive structure tilts toward integrated hardware-software platforms over standalone equipment vendors. European and North American players dominate workplace and retail deployments through cloud-native management systems. Three archetypes define positioning: utility-scale project specialists, software-integrated platform providers, and regional installation service integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure fleet operator volume agreements.
Among the software-integrated platform providers, ChargePoint and Wallbox exemplify the cloud-native archetype that bundles load-balancing algorithms with hardware deployment. ABB E-mobility anchors the utility-scale project tier through its European infrastructure focus. These three occupy positions that reflect divergent bets on whether fleet depots or workplace retail installations will concentrate margin pools over the forecast period.
| Leading Market Players |
|---|
| ChargePoint |
| ABB E-mobility |
| Siemens |
| Schneider Electric |
| Alfen |
| Wallbox |
| Blink Charging |
| bp pulse |
| EVBox |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement concentration around volume depot contracts anchors contract-based long-term offtake as the dominant pricing model, compressing unit economics for hardware vendors while embedding multi-year service obligations.
Pricing Analysis
Cost-down pressure on standard AC hardware accelerates because copper and silicon carbide power semiconductor shortages constrain margin buffers. Three-tier pricing structure across premium bidirectional units, standard smart chargers, and economy wall-mounted boxes differentiates by certification grade and after-sales bundling intensity. Small fleet operators exhibit highest price sensitivity, driving subscription-based charging-as-a-service adoption, while electric mobility operators with dedicated energy staff prioritize interoperability certification over unit cost.
Supply Chain Analysis
CE marking under EU F-Gas Regulation and NMPA-aligned GB standards gate market access, forcing component sourcing from qualified tier-1 suppliers. Manufacturing concentrates in Germany, China, and the United States, with power electronics drawing from Taiwanese semiconductor foundries and copper busbar suppliers. Single-source vulnerability in silicon carbide MOSFETs creates supply chain risk. Distribution runs through certified electrical contractors and direct OEM relationships for fleet-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around software-integrated platform providers as copper volatility and certification burdens force pure-play hardware vendors toward acquisition or exit.
For Market Incumbents: Acquire cloud-native energy management platforms to defend against emerging software-first entrants. Secure backward integration into power electronics manufacturing to buffer silicon carbide cost swings. Prioritize KBA and NMPA certification investments to lock out regional competitors from EU and China depot tenders. For New Entrants and Emerging Players: Enter via India's state-level bus fleet electrification mandates, where depot infrastructure gaps outstrip incumbent deployment capacity. Target Maharashtra and Karnataka pilot programs with compact AC units tailored to space-constrained urban depots. Pursue charging-as-a-service partnerships with local electrical contractors to bypass direct utility interconnection queue exposure. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive software stacks and fleet operator relationships. Long-term viability hinges on bidirectional capability integration and grid-interactive certification depth. Watch California CPUC managed charging incentive expansion as the signal for when V2H-enabled hardware becomes table stakes versus premium differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Cloud-native load-balancing algorithms differentiate ChargePoint and Wallbox from commodity hardware vendors. |
| Backward Integration into Power Electronics | In-house silicon carbide sourcing buffers ABB E-mobility and Siemens against semiconductor shortage volatility. |
| Certification Investment Acceleration | CE marking and KBA compliance under EU F-Gas Regulation gates European depot procurement for compliant suppliers. |
| Fleet Operator Partnership Lock-in | Long-term service contracts with logistics operators concentrate margin pools and reduce customer acquisition costs. |
| Geographic Manufacturing Footprint | Ruhr corridor and Yangtze River Delta production clusters optimize duty exposure for EU and China market access. |
Research Methodology
Regulatory filings, customs trade databases, and utility interconnection queue records formed the secondary backbone, cross-referenced against primary interviews with fleet electrification managers, electrical contractor procurement leads, charging network operations directors, and grid interconnection planners. Bottom-up and top-down triangulation validated hardware shipment estimates against fleet operator deployment disclosures and state-level building code adoption tracking.
Bottom-up modeling aggregated unit economics across product tiers, connector specifications, and installation contexts, while top-down analysis triangulated against EU Green Deal transport target compliance trajectories and NHTSA-aligned state code adoption. Segmentation dimensions spanned physical form factor, intelligence integration, connector standard, and application context across fleet depot, workplace, residential, and commercial deployments. CAGRs derived from deployment velocity modeling against binding emission reduction timelines and building code mandate phase-ins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes and utility interconnection study delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market