
 Non-Ferrous Scrap Recycling Market | 2026-2036
Non-Ferrous Scrap Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Ferrous Scrap Recycling Market Intelligence
Automotive stampers is unwinding from construction sheet buyers as the dominant scrap aluminum offtake channel. Aurubis leverages its European smelter network to capture high-grade copper cathode premiums from shredded wire feedstock. Sims Metal Management anchors its North American footprint through port-adjacent shredding capacity that competes on logistics cost with domestic integrated mills. Kuusakoski specializes in aerospace-grade titanium and nickel alloy segregation, differentiating its offering from commodity mixed-load processors.
Non-ferrous scrap recycling encompasses the recovery and reprocessing of base and precious metals excluding iron and steel, typically involving feedstocks with less than 50 ppm iron content processed through pyrometallurgical or hydrometallurgical routes to achieve LME-grade purity specifications. The primary industrial purpose is to displace energy-intensive primary metal extraction, with secondary aluminum production consuming roughly 5% of the electricity required for electrolytic smelting of bauxite-derived alumina. Aluminum scrap dominates volume flows through established beverage can and automotive casting closed-loop systems, while copper scrap commands margin concentration due to stringent CDA conductivity standards that reward clean bare bright segregation. Pyrometallurgical processing leads installed capacity but faces displacement pressure from hydrometallurgical methods as the EU's Industrial Emissions Directive tightens dioxin and furan discharge limits.
The EPA's RCRA hazardous waste classifications and the EU's REACH annex XVII restrictions on lead content in consumer goods reshape sorting protocols and market access for mixed non-ferrous residues crossing jurisdictional boundaries. China's GB standards for imported scrap quality and its dual carbon goals are redirecting regional trade flows toward Southeast Asian intermediate processing hubs. Stakeholders must monitor how carbon border adjustment mechanisms redefine the competitive calculus between primary and secondary metal sourcing across transatlantic supply chains.
Market Dynamics
China's GB standards for imported scrap quality are fragmenting established trade corridors and forcing feedstock rerouting through Southeast Asian intermediate hubs, compressing margins for direct exporters while elevating toll-processing premiums.
Growth Catalysts
- Automotive lightweighting mandates:OEM stamping plants in Germany and the United States are accelerating aluminum scrap offtake to meet NHTSA and EU fleet efficiency targets, displacing primary ingot in body-in-white applications.
- EU Critical Raw Materials Act:The framework imposes collection infrastructure obligations on copper and nickel-bearing residues, creating guaranteed feedstock pipelines for secondary smelters in Belgium and Poland.
- Pyrometallurgical efficiency gains:Advanced oxy-fuel burner retrofits are cutting energy intensity in rotary furnace operations, narrowing the cost gap with hydrometallurgical alternatives for mixed non-ferrous concentrates.
Market Restraints
- Copper concentrate supply concentration:Chilean and Peruvian mine disruptions transmit volatility into scrap pricing benchmarks, exposing processors to margin compression when primary metal spikes.
- REACH annex XVII lead restrictions:The EU's consumer goods limits complicate sorting protocols for mixed residues containing solder-bearing electronics, requiring costly segregation infrastructure.
- Lithium-ion substitution in powertrain electrification:Battery-electric vehicle architectures reduce aluminum casting volumes per vehicle, threatening long-term scrap generation rates from automotive shredder residue.
Strategic Opportunities
- India's PLI scheme for specialty metals:The production-linked incentive framework for copper and aluminum downstream processing is attracting toll-smelter investments in Gujarat and Odisha to serve domestic cable and auto component manufacturers.
- Aerospace-grade titanium segregation:Precision sorting of Ti-6Al-4V and Inconel alloys from MRO shop floor waste commands 40-60% premiums over commodity mixed loads, rewarding capital investment in XRF-based identification systems.
- Carbon border adjustment mechanism arbitrage:The EU CBAM's phased implementation creates pricing advantages for verified low-carbon secondary aluminum and copper cathode against primary imports from coal-intensive smelting regions.
Industry Challenges
- Hydrometallurgical chemistry expertise scarcity:The shift toward leaching-based recovery of rare earth elements and battery metals requires metallurgical chemists with solvent extraction experience, a skill set concentrated in primary mining rather than scrap processing.
- LME-grade certification timelines:Achieving London Metal Exchange brand registration for secondary copper cathode demands 18-24 months of continuous batch testing, delaying market access for new entrant smelters.
- Legacy shredding plant reconfiguration:Retrofitting existing automobile shredder residue lines to capture zorba fines and heavy non-ferrous concentrates requires substantial conveyor and eddy-current separator upgrades with extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Ferrous Scrap Recycling Market |
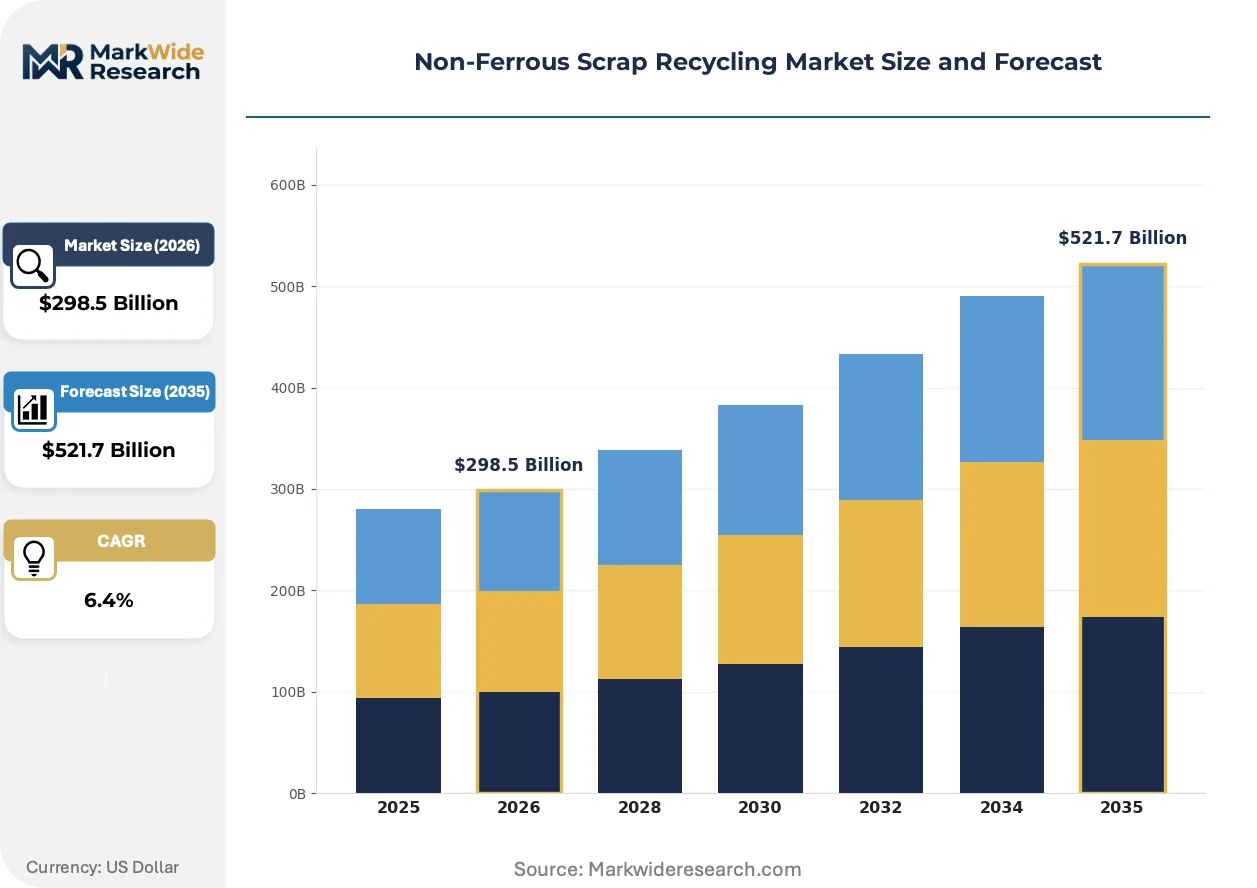
| Market Size in 2026 | $298.5 Billion |
| Market Size in 2035 | $521.7 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Copper, Lead, Zinc Recycling Process: Shredding, Melting, Sorting, Cleaning End User: Automotive Sector, Construction Industry, Electrical Sector, Consumer Goods Methodology: Hydrometallurgical, Pyrometallurgical, Mechanical, Biotechnological |
| Companies Covered | Aurubis, Sims Metal Management, Hindalco Industries, OmniSource, SA Recycling, Kuusakoski, TSR Recycling, Schnitzer Steel Industries, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Ferrous Scrap Recycling Market Strategic Shifts & Innovations
Sensor-based sorting and digital traceability protocols are compressing the information asymmetry between scrap generators and smelter buyers, enabling real-time quality verification that reshapes contract structures and logistics optimization.
Artificial intelligence-driven robotic picking is fragmenting the economics of manual sorting lines. European and North American processors are deploying computer-vision systems trained on alloy-specific spectral signatures to replace hand-picking of zorba and zurik concentrates. The technology compresses labor cost differentials between high-wage and low-wage jurisdictions, enabling regionalized processing rather than export to manual-sorting destinations.
The EU's Industrial Emissions Directive is tightening dioxin and furan discharge limits for pyrometallurgical operations. Secondary copper smelters in Germany and Belgium are retrofitting baghouse filters and activated carbon injection systems to meet the BAT-AEL benchmarks, adding 8-12% to capital intensity for furnace rebuilds. The regulation accelerates interest in hydrometallurgical alternatives for complex feedstocks containing halogenated plastics.
Automotive OEMs are consolidating scrap procurement under direct mill agreements rather than merchant broker channels. Stampers in the Yangtze River Delta and the US Midwest are negotiating closed-loop contracts that bypass traditional scrap yards, capturing logistics savings and carbon accounting transparency. The behavior is most visible in aluminum sheet and extrusion offtake, where automakers seek Scope 3 emissions verification for ESG reporting.
Non-Ferrous Scrap Recycling Market Segmentation
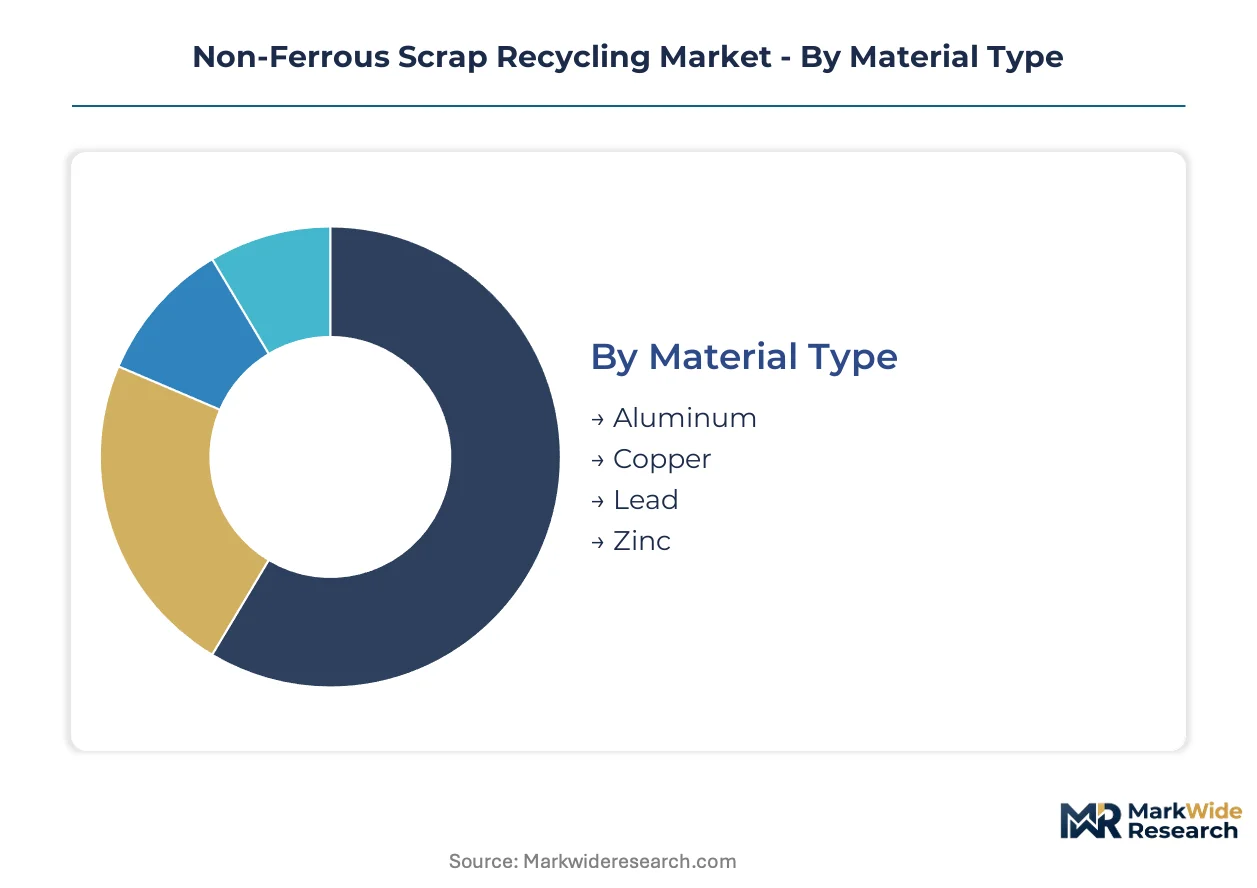
Segmentation in non-ferrous scrap recycling determines which feedstock grades flow through merchant broker networks versus direct mill contracts, with purity thresholds and volume scalability dictating channel economics. Material type and processing methodology together shape margin structures, as high-grade copper cathode commands toll-smelter premiums while mixed aluminum zorba concentrates compete on logistics arbitrage.
Material Type:
Channel allocation varies sharply by material type, with aluminum scrap flowing predominantly through closed-loop automotive agreements while copper and lead residues concentrate in toll-processing arrangements with secondary smelters.
- Aluminum:Post-consumer beverage can stock and automotive casting scrap dominate volume flows, with UBC closed-loop systems achieving 60-day turnaround from collection to remelt. OEM stamping plants in Germany and the US Midwest are displacing primary ingot through direct mill contracts that bypass traditional scrap yards entirely.
- Copper:Bare bright wire and No. 1 copper tubing command the steepest premiums due to CDA conductivity standards, with shredded wire feedstock flowing to European smelters capturing cathode premiums. Chilean mine disruptions transmit volatility directly into scrap pricing benchmarks, compressing processor margins during primary metal spikes.
- Lead:Battery scrap concentrates within regulated hazardous waste channels under EPA RCRA classifications, with auto battery retailers serving as captive collection points for secondary smelters.
- Zinc:Galvanized steel residue and die-casting scrap flow through intermediate processing hubs, with zinc oxide recovery from electric arc furnace dust commanding specialized pyrometallurgical capacity.
Aluminum dominates installed base. Copper is where expansion concentrates.
Recycling Process:
Cost tier differentiation separates capital-intensive melting operations from labor-dependent sorting stages, with shredding capacity anchoring regional logistics competitiveness.
- Shredding:Port-adjacent shredding plants in North America compete on logistics cost with domestic integrated mills, with automobile shredder residue lines requiring substantial conveyor upgrades to capture zorba fines.
- Melting:Advanced oxy-fuel burner retrofits in rotary furnace operations are narrowing the cost gap with hydrometallurgical alternatives for mixed non-ferrous concentrates.
- Sorting:AI-driven robotic picking trained on alloy-specific spectral signatures is displacing manual hand-picking of zorba concentrates, compressing labor cost differentials between high-wage and low-wage jurisdictions.
- Cleaning:De-coating and delacquering stages for aluminum UBC feedstock determine final ingot quality specifications, with organic contaminant levels dictating furnace yield rates.
Melting commands the highest capital intensity. Sorting is where technology substitution accelerates most rapidly.
End User:
Application-specific purity requirements create divergent procurement patterns, with automotive and electrical sectors driving premium-grade segregation while construction absorbs commodity mixed loads.
- Automotive Sector:Body-in-white stamping plants source aluminum sheet and extrusion scrap through closed-loop contracts with Scope 3 emissions verification, bypassing merchant brokers for carbon accounting transparency.
- Construction Industry:Window frame extrusion and architectural sheet scrap flow through traditional dealer networks, with lower purity tolerance enabling mixed-load processing.
- Electrical Sector:Cable manufacturers demand CDA-certified copper cathode with guaranteed conductivity, requiring clean bare bright segregation that commands 15-20% premiums over No. 2 grades.
- Consumer Goods:Electronics manufacturers face REACH annex XVII lead restrictions complicating solder-bearing residue sorting, requiring costly segregation infrastructure for mixed non-ferrous feedstocks.
Automotive procurement is consolidating under direct mill agreements. Electrical sector demand is climbing the fastest.
Methodology:
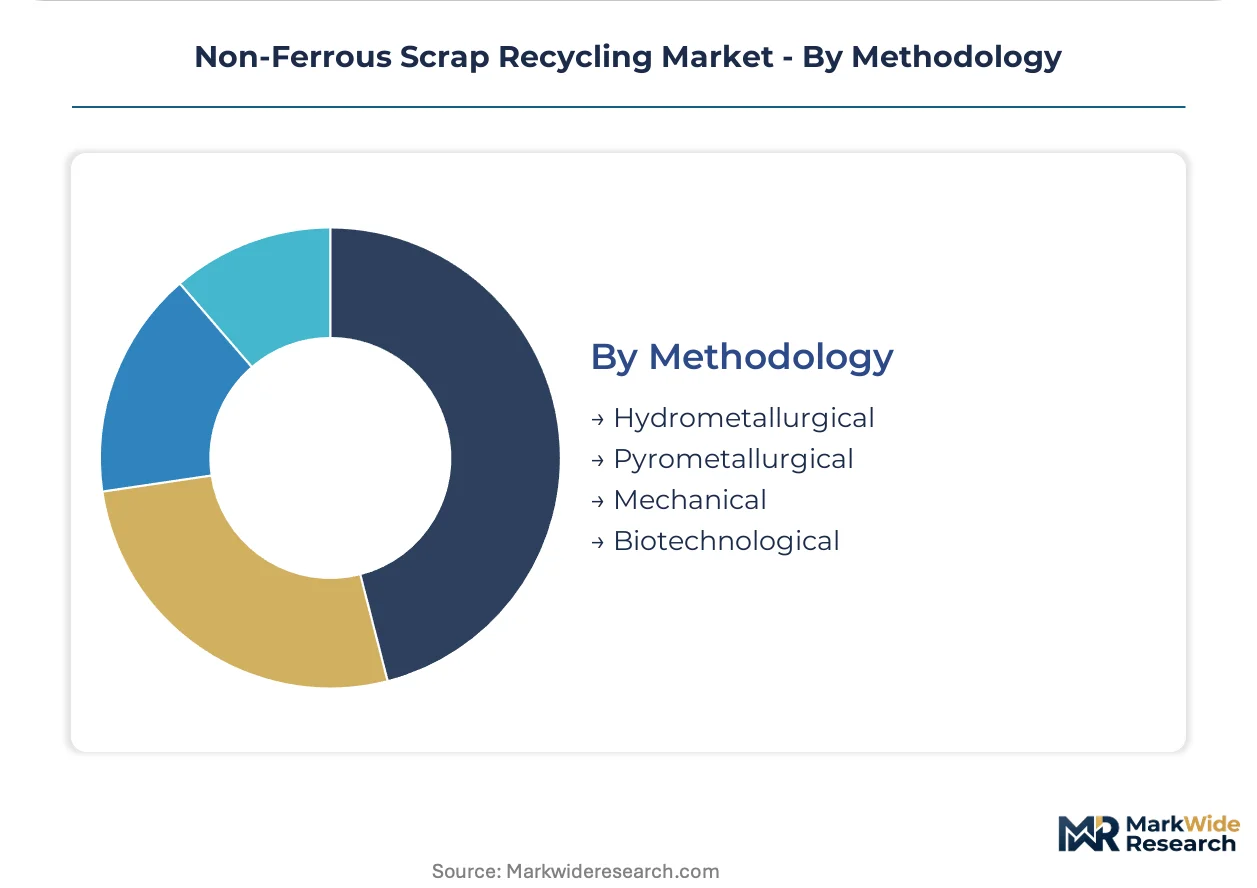
Supply concentration favors pyrometallurgical incumbents while hydrometallurgical entrants capture complex feedstocks unsuited to furnace processing.
- Hydrometallurgical:Leaching-based recovery of rare earth elements and battery metals requires scarce metallurgical chemists with solvent extraction experience, a skill set concentrated in primary mining rather than scrap processing.
- Pyrometallurgical:Secondary copper smelters in Germany and Belgium are retrofitting baghouse filters to meet EU Industrial Emissions Directive dioxin limits, adding 8-12% to capital intensity for furnace rebuilds.
- Mechanical:Eddy-current and X-ray fluorescence separation systems enable aerospace-grade titanium and nickel alloy segregation from MRO shop floor waste, commanding 40-60% premiums over commodity mixed loads.
- Biotechnological:Bioleaching applications for low-grade copper and zinc residues remain at pilot scale, with microbial consortium cultivation requiring extended residence times that limit throughput economics.
Pyrometallurgical capacity dominates installed base. Hydrometallurgical methods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's deep-water terminals and bonded warehousing infrastructure anchor Europe's non-ferrous scrap gateway, handling transshipment flows that redistribute shredded aluminum and copper concentrates to inland smelters.
United States
Automotive stamping plants in Michigan and Ohio drive aluminum scrap offtake through closed-loop direct mill contracts. EPA RCRA hazardous waste classifications reshape battery lead collection protocols. The Midwest manufacturing belt concentrates shredder capacity that feeds secondary smelters via rail-linked logistics corridors.
Germany
Aurubis anchors European copper cathode production from high-grade wire feedstock processed through its Hamburg and Lünen facilities. The EU Industrial Emissions Directive mandates baghouse retrofits for dioxin compliance. The Ruhr industrial cluster hosts secondary smelters capturing toll-processing premiums from mixed non-ferrous concentrates.
China
Yangtze River Delta secondary smelters source half their feedstock from imported scrap circuits diverted through Southeast Asian intermediate hubs. GB standards for imported scrap quality fragment established trade corridors. Shanghai's bonded zone concentrates toll-processing capacity serving domestic cable manufacturers.
India
The PLI scheme for specialty metals attracts toll-smelter investments in Gujarat and Odisha serving domestic auto component and cable manufacturers. BIS quality standards reshape import protocols for copper and aluminum scrap. Mundra Port's logistics infrastructure enables coastal processing clusters competing on feedstock arbitrage.
Belgium
The EU Critical Raw Materials Act imposes collection infrastructure obligations on copper and nickel-bearing residues. Secondary smelters in the Antwerp port zone capture guaranteed feedstock pipelines. The Flanders industrial corridor concentrates pyrometallurgical capacity retrofitting for BAT-AEL emission benchmarks.
Non-Ferrous Scrap Recycling Market Key Industry Players
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven shredder networks coexist with precision segregation boutiques. The market fragments vertically rather than horizontally, with port-adjacent logistics specialists, toll-smelter operators, and aerospace-grade alloy processors occupying distinct margin strata. Three archetypes dominate: integrated metal producers with captive scrap intake, independent merchant processors competing on logistics arbitrage, and precision segregation specialists commanding alloy-specific premiums. Competitive moves concentrate on M&A consolidation of regional shredding capacity and backward integration into collection infrastructure.
Within the precision segregation tier, Kuusakoski exemplifies the aerospace-grade specialist archetype through its positioning in titanium and nickel alloy recovery. Among integrated metal producers, Hindalco Industries and Nucor Corporation occupy positions that bridge primary smelting with secondary feedstock integration. Aurubis anchors the European toll-smelter vector, representing the copper cathode premium capture model that rewards high-grade shredded wire feedstock.
| Leading Market Players |
|---|
| Aurubis |
| Sims Metal Management |
| Hindalco Industries |
| OmniSource |
| SA Recycling |
| Kuusakoski |
| TSR Recycling |
| Schnitzer Steel Industries |
| Nucor Corporation |
| Others |
Cost & Logistics Intelligence
Secondary aluminum's displacement of primary ingot in automotive body-in-white applications simultaneously reroutes feedstock flows from commodity scrap yards toward direct mill contracts and compresses toll-processing premiums across European and North American smelter networks. This substitution dynamic concentrates pricing power with OEM stamping plants while fragmenting merchant broker margins.
Pricing Analysis
Volume-discount tiering structures separate aerospace-grade titanium and nickel alloy segregation from commodity mixed-load processing, with clean bare bright copper commanding 15-20% premiums over No. 2 grades due to CDA conductivity certification. Price differentiation hinges on alloy-specific purity thresholds and guaranteed chemistry specifications rather than geographic arbitrage. Cost compression in mixed aluminum zorba concentrates intensifies as AI-driven robotic picking narrows labor cost differentials between high-wage and low-wage jurisdictions. Automotive OEMs exhibit the lowest price sensitivity due to Scope 3 emissions verification requirements, while construction sector buyers of window frame extrusion scrap remain highly price-elastic.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive closed-loop systems, while strategic stockpiling concentrates among secondary copper smelters hedging against Chilean and Peruvian mine disruption volatility. Supply concentrates in China's Yangtze River Delta cluster, Germany's Ruhr industrial corridor, and India's Gujarat coastal processing zones. The network draws from imported scrap circuits, MRO shop floor waste, and auto shredder residue as primary inputs. Single-source vulnerability runs through Southeast Asian intermediate hubs rerouting feedstock blocked by China's GB standards. Distribution runs through port-adjacent shredding capacity competing on logistics cost with rail-linked inland smelters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-ferrous scrap recycling operates within a cyclical recovery phase driven by automotive lightweighting mandates accelerating aluminum scrap offtake across OEM stamping networks.
For Market Incumbents: Compound regional shredding capacity through targeted M&A of port-adjacent logistics assets to defend margin position against hydrometallurgical entrants capturing complex feedstocks. Prioritize backward integration into collection infrastructure obligated under the EU Critical Raw Materials Act to secure guaranteed copper and nickel-bearing residue pipelines.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for specialty metals, where toll-smelter investments in Gujarat and Odisha serve underpenetrated domestic cable and auto component manufacturers. Target aerospace-grade titanium segregation from MRO shop floor waste, leveraging XRF-based identification systems to capture 40-60% premiums over commodity mixed loads.
For Investors and Strategic Acquirers: Capital is best deployed toward precision segregation boutiques with aerospace-grade alloy capabilities rather than scale-driven shredder networks facing technology substitution pressure. Long-term viability over a multi-year horizon rests on carbon border adjustment mechanism arbitrage positioning. Watch for EU CBAM phased implementation crossing enforcement thresholds as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | EU Critical Raw Materials Act obligations create captive feedstock pipelines for secondary smelters in Belgium and Poland. |
| AI-Driven Robotic Picking Deployment | Computer-vision systems trained on alloy-specific spectral signatures displace manual sorting labor cost differentials. |
| Port-Adjacent Shredding Capacity Expansion | Rotterdam and Mundra deep-water terminals enable logistics cost competition with domestic integrated mills. |
| Hydrometallurgical Chemistry Investment | Solvent extraction expertise scarcity concentrates value capture for rare earth element and battery metal recovery. |
| Closed-Loop Direct Mill Contracting | OEM stamping plants in Germany and the US Midwest bypass merchant brokers for carbon accounting transparency. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed metal processors, EU Industrial Emissions Directive compliance disclosures, and national scrap import statistics. Primary interviews engaged secondary smelter operations directors, scrap yard procurement managers, OEM stamping plant materials engineers, and toll-processing contract negotiators. Bottom-up volume estimates from shredding capacity utilization rates triangulate against top-down metal consumption forecasts from automotive and electrical sector demand models.
Segmentation dimensions modeled include material type purity grades, pyrometallurgical versus hydrometallurgical processing routes, and end-use sector application requirements across the projection horizon. CAGRs derive from regression analysis of historical scrap-to-primary metal price spreads, capacity expansion pipelines, and regulatory threshold implementation schedules. Industry-specific forecast inputs incorporate automotive lightweighting program timelines and EU CBAM carbon intensity verification protocols.
Underlying assumptions cover sustained automotive aluminum casting demand, continued Chinese GB standard enforcement, and stable Chilean copper concentrate supply, with deviation risk concentrated in lithium-ion powertrain substitution rates and hydrometallurgical technology cost curves. Revision becomes warranted when battery-electric vehicle architecture penetration crosses thresholds that structurally reduce per-vehicle aluminum casting volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Japan Recycled Plastics Market