
 Saudi Arabia Plastic Components Market | 2026-2036
Saudi Arabia Plastic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Plastic Components Market Analytics
Maintenance contracts for injection molding tooling is pivoting from cost centers into recurring revenue streams for equipment suppliers. SABIC leverages its upstream polymer position to anchor captive demand for specialized resin grades. Zamil Plastic competes through geographic proximity to Jubail's feedstock hub. Arabian Plastics Industrial Company Limited differentiates via custom mold fabrication for automotive tier-one suppliers.
Plastic components encompass engineered polymer parts produced through injection molding, extrusion, blow molding, or thermoforming processes, typically specified by melt flow index, tensile strength, and dimensional tolerance parameters for load-bearing or containment functions. These components serve as structural, aesthetic, or barrier elements across automotive, packaging, medical, and consumer product assemblies. Injection Molding dominates value capture due to precision tolerances in Medical Devices and Automotive Interiors, while Blow Molding extends fastest in Packaging Solutions driven by pharmaceutical and dairy barrier requirements. Thermoforming occupies a mature cost-optimized niche in consumer disposables with thinner margin pools.
SFDA governs food-contact and medical-grade plastic safety standards, while SASO administers technical conformity assessments for imported resin and finished components, together elevating compliance costs for non-certified suppliers. The Saudi Standards, Metrology and Quality Organization (SASO) Technical Regulation for Plastic Products mandates traceability and restricted substance limits that reshape formulation choices across the value chain. Stakeholders must monitor how Vision 2030 localization incentives alter the competitive balance between domestic molders and historically dominant import channels.
Market Dynamics
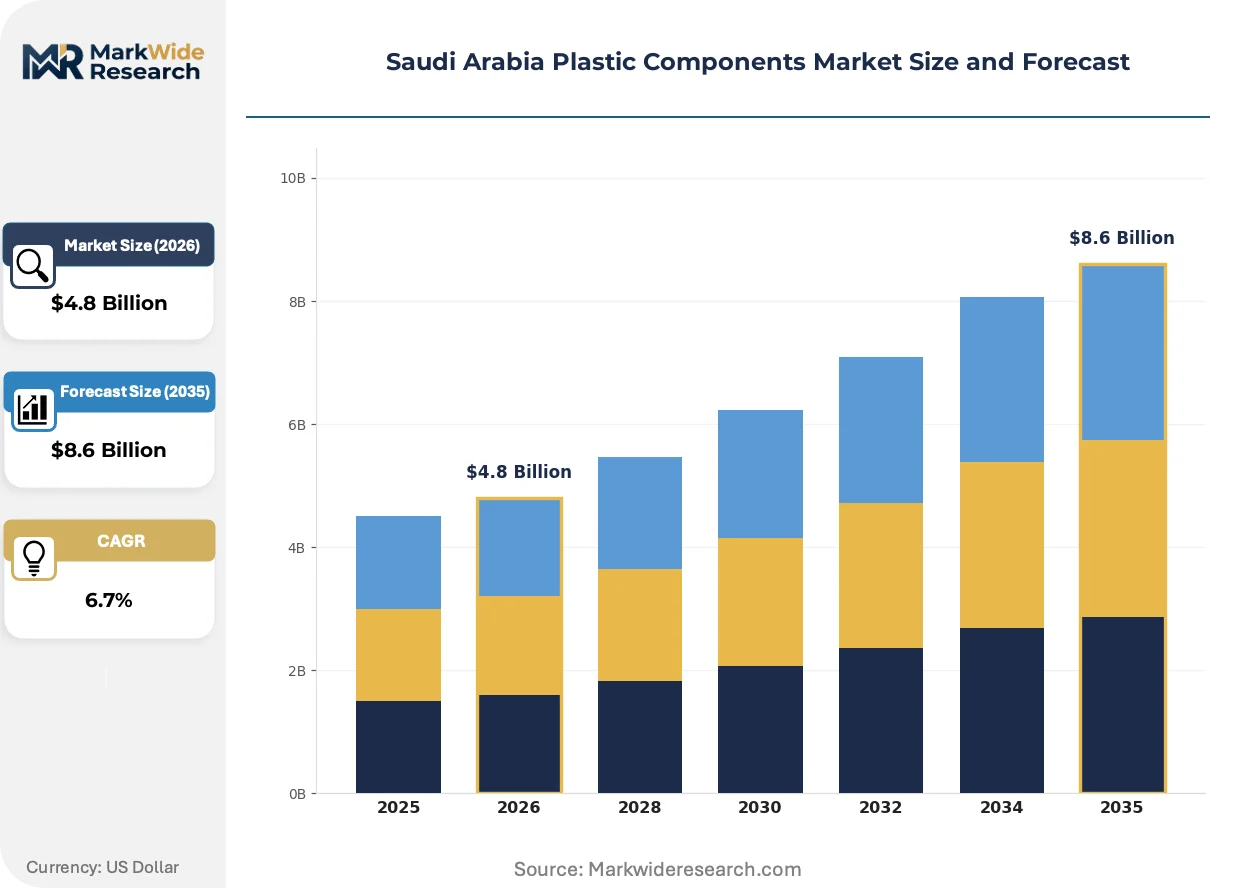
SFDA food-contact material regulations and Saudi Vision 2030 industrial localization mandates are redirecting procurement toward domestic molders, compressing import channels while elevating compliance costs for non-certified suppliers across the value chain.
Growth Catalysts
- SASO Technical Regulation for Plastic Products:Traceability mandates and restricted substance limits are reformulating resin choices across packaging and medical-grade applications.
- Jubail Petrochemical Cluster:Proximity to SABIC feedstock infrastructure reduces raw material logistics costs for domestic injection molding operations.
- Injection Molding Precision:Tight dimensional tolerances specified for automotive interiors and medical devices are capturing premium value pools.
Market Restraints
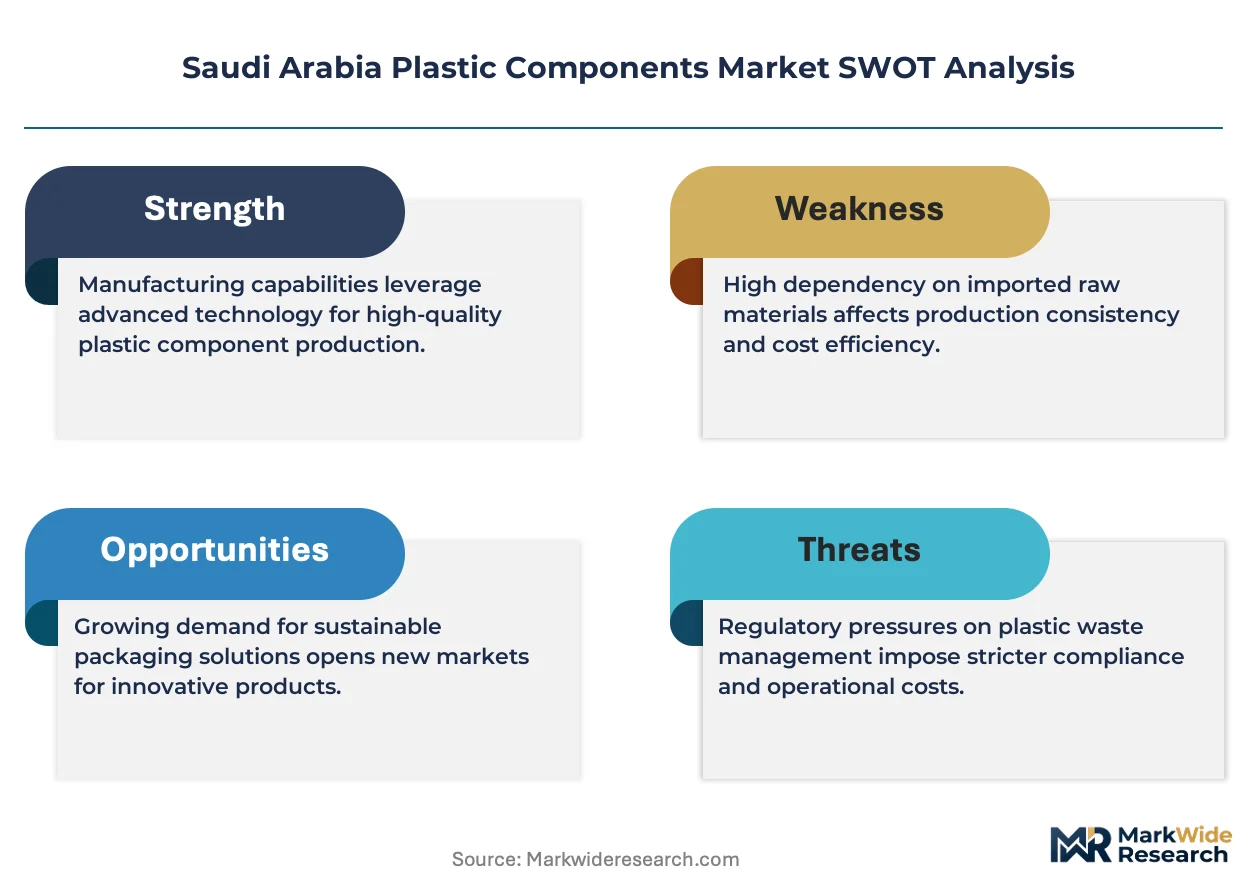
- Polymer Price Volatility:Crude-linked naphtha feedstock costs transmit directly to resin pricing, compressing margin stability for non-integrated molders.
- Import Channel Concentration:Historically dominant Asian suppliers retain scale advantages in commodity-grade components, limiting domestic share expansion.
- Blow Molding Barrier Limitations:Oxygen and moisture transmission rates in dairy and pharmaceutical packaging constrain shelf-life extension versus glass and metal alternatives.
Strategic Opportunities
- Eastern Province Manufacturing Corridor:Jubail and Dammam industrial zones offer underutilized conversion capacity for export-oriented automotive tier-one supply.
- SFDA Medical Device Grade Certification:Regulatory tailwinds favor domestic molders achieving sterile packaging validation for pharmaceutical distribution.
- Digital Melt Flow Monitoring:Convergence of IoT sensors with statistical process control is enabling real-time quality assurance for high-tolerance automotive components.
Industry Challenges
- Tooling Design Engineering Talent:Shortage of mold flow simulation specialists delays new product qualification timelines for complex geometries.
- SASO Conformity Assessment Duration:Extended certification timelines for imported resin batches disrupt just-in-time production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Plastic Components Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Blow Molding, Thermoforming Application: Automotive Interiors, Packaging Solutions, Consumer Goods, Medical Devices End User: Manufacturers, Wholesalers, Retailers, Service Providers Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Arabian Plastics Industrial Company Limited, Zamil Plastic, Rowad National Plastic Company Ltd, Takween Advanced Industries, Tamam Plastic Factory, SABIC, Saudi Arabian Amiantit Company, Al Watania Plastics, Napco National, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Plastic Components Market Evolving Landscape
Digital manufacturing integration and regulatory-driven material reformulation are compressing traditional production cycles while opening premium positioning for certified domestic suppliers in food-contact and medical-grade segments.
All-electric injection molding systems is electrifying precision manufacturing by eliminating hydraulic fluid contamination risks in cleanroom medical device production. Pharmaceutical packaging converters in Riyadh are adopting these systems at accelerated replacement cycles. The technology is electrifying competitive positioning by enabling sub-micron repeatability that commands pricing premiums over hybrid and hydraulic alternatives.
SFDA food-contact material safety standards are tightening migration limits for heavy metals and plasticizers in packaging applications. Domestic compounders are reformulating masterbatch additives to meet restricted substance schedules ahead of enforcement dates. Medical device and dairy packaging segments are responding fastest, with procurement teams demanding batch-level test documentation from qualified Saudi molders.
Buyer consolidation among food and beverage distributors is compressing supplier qualification cycles and unbundling tooling maintenance from per-unit pricing. Tier-one retail chains are mandating direct relationships with certified molders, bypassing traditional trading intermediaries. The shift is most visible in Riyadh's packaged foods corridor, where centralized procurement teams now specify mold ownership transfer clauses in multi-year supply agreements.
Saudi Arabia Plastic Components Market Segmentation
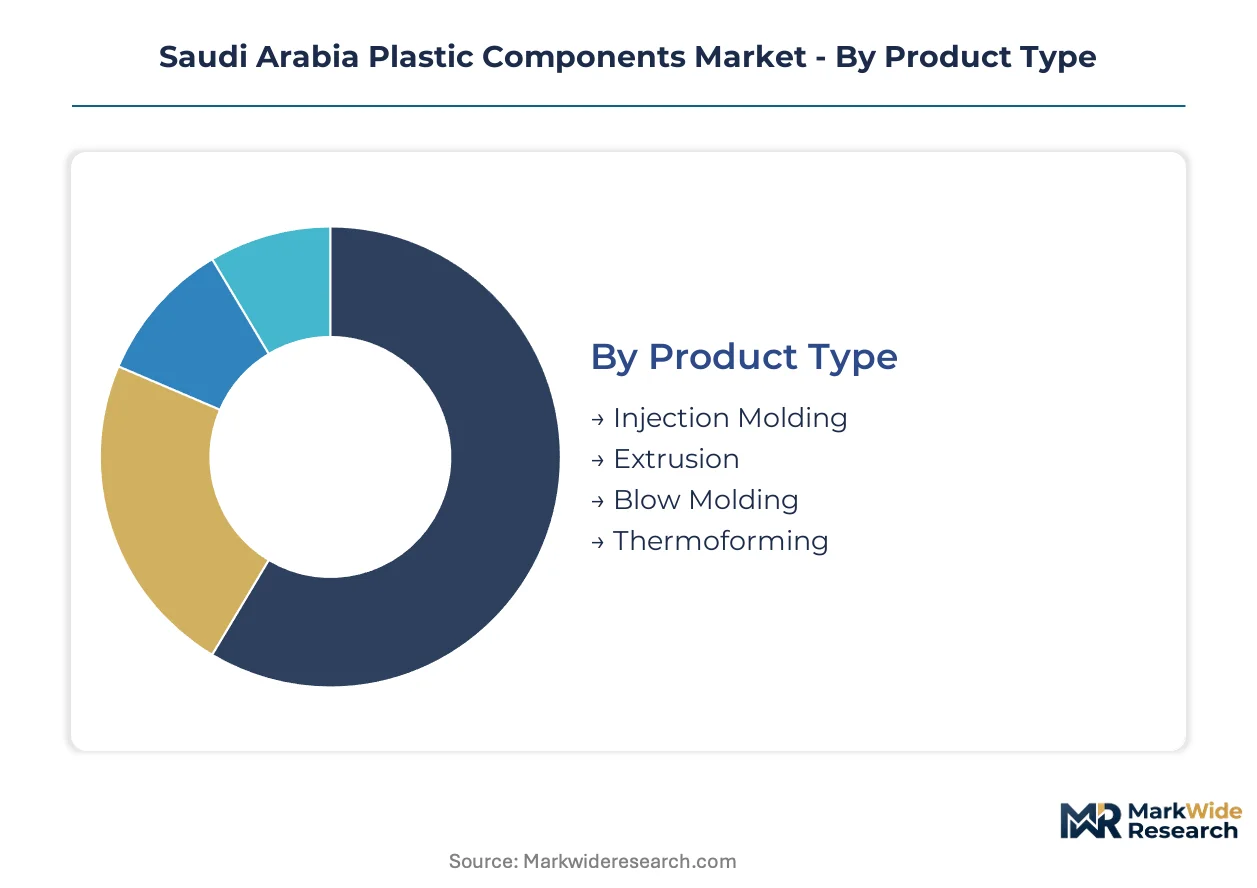
Segmentation in the Saudi Arabia Plastic Components Market exposes how production technology, end-use application, and procurement channel each concentrate value differently. Buyers in Riyadh's manufacturing corridor and Jubail's petrochemical cluster display sharply divergent specifications across these dimensions.
Product Type:
Supply concentration in the Eastern Province favors conversion technologies with direct feedstock pipeline access from SABIC infrastructure.
- Injection Molding:High-pressure polymer injection into precision steel tooling achieves dimensional tolerances critical for automotive interior panels and medical device housings. Demand concentrates in Riyadh's automotive tier-one supplier parks where SFDA medical-grade validation requirements command batch-level documentation premiums.
- Blow Molding:Extrusion or injection of parison tubes followed by compressed air expansion produces hollow containers with barrier-layer configurations for pharmaceutical and dairy packaging. Jubail-based converters leverage proximity to HDPE and PP resin supply to capture pharmaceutical distribution contracts requiring oxygen transmission rate specifications below 0.5 cc/pkg/day.
- Extrusion:Continuous profile shaping through heated dies generates sheet, film, and pipe geometries for construction and agricultural applications.
- Thermoforming:Heated sheet vacuum or pressure forming into disposable trays and clamshells occupies thin-margin consumer disposables with limited barrier performance requirements.
Today's leader: Injection Molding. Tomorrow's challenger: Blow Molding.
Application:
End-use specification intensity separates premium-grade segments demanding regulatory certification from commodity-grade segments competing on unit economics.
- Packaging Solutions:Multi-layer barrier films, closures, and rigid containers engineered for shelf-life extension in food, beverage, and pharmaceutical distribution. Demand concentrates in centralized procurement teams at Riyadh-based retail chains where SFDA food-contact migration limits are tightening additive formulations.
- Automotive Interiors:Dashboard assemblies, door panels, and HVAC ducting molded to OEM surface quality and flammability specifications. Eastern Province manufacturing zones near Dammam anchor tier-one supplier qualification programs requiring IATF 16949 certification and sub-50ppm odor emission testing.
- Medical Devices:Sterile packaging, surgical instrument housings, and diagnostic consumables requiring ISO 13485 traceability and USP Class VI biocompatibility validation.
- Consumer Goods:Household durables, electronics enclosures, and personal care packaging with lower regulatory barriers and price-sensitive procurement patterns.
Packaging Solutions currently captures the dominant revenue share. Medical Devices displays the steepest expansion trajectory driven by SFDA sterile validation mandates.
End User:
Procurement authority concentration among large-scale manufacturers is compressing intermediary margins and reshaping channel economics.
- Manufacturers:Tier-one automotive assemblers, pharmaceutical packagers, and food processors specifying direct molder relationships with mold ownership transfer clauses. Riyadh-based packaged food producers now mandate batch-level SFDA compliance documentation bypassing traditional trading intermediaries.
- Wholesalers:Regional distributors consolidating commodity-grade component volumes for resale to smaller fabricators and construction contractors.
- Retailers:Hypermarket and pharmacy chains sourcing private-label packaging with centralized quality audits.
- Service Providers:Maintenance, repair, and overhaul operations requiring aftermarket component replacement with reduced qualification overhead.
Direct manufacturer procurement is displacing wholesale intermediation fastest in food-contact and medical-grade segments.
Distribution Channel:
Channel selection correlates with order complexity, certification requirements, and geographic proximity to production clusters.
- Direct Sales:Long-term supply agreements between certified molders and large-scale manufacturers with embedded tooling maintenance and technical service provisions. Jubail-based SABIC affiliates and Zamil Plastic operations dominate this channel for high-volume automotive and packaging accounts.
- Distributors:Inventory-bearing intermediaries serving fragmented construction and agricultural equipment sectors with standard extruded profiles.
- Online Sales:Digital procurement platforms gaining traction in commodity-grade consumer goods and standard mold catalog items.
- Retail Stores:Limited to small-lot hardware and DIY applications with minimal technical specification requirements.
Direct Sales commands the premium relationship tier. Distributors retain relevance in geographically dispersed construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's plastic components sector outpaces Gulf neighbors in conversion capacity depth, while the UAE leverages Dubai's logistics hub status for re-export positioning. This divergence shapes procurement patterns across the Arabian Peninsula.
Riyadh
Central Region manufacturing corridors anchor food packaging and automotive interior demand, with centralized retail procurement teams mandating direct molder relationships. SFDA food-contact compliance documentation requirements compress qualification timelines for domestic suppliers. The Riyadh-based packaged foods corridor concentrates injection molding operations serving hypermarket private-label programs.
Eastern Province
Jubail's petrochemical cluster feeds HDPE and PP resin directly into blow molding operations for pharmaceutical barrier packaging. SABIC's upstream infrastructure enables oxygen transmission rate specifications below 0.5 cc/pkg/day for dairy and drug distribution. Dammam industrial zones host tier-one automotive supplier parks requiring IATF 16949 certification and sub-50ppm odor emission testing protocols.
Western Region
Jeddah's Red Sea port facilities handle resin import volumes for construction-grade extruded profiles and agricultural piping. SASO conformity assessment timelines for imported resin batches disrupt just-in-time scheduling for smaller fabricators. The Makkah corridor shows emerging demand for medical device packaging tied to hospital network expansion.
NEOM Northwest
Giga-project construction schedules are accelerating specification of large-diameter extruded pipe and structural polymer components for modular building systems. Vision 2030 localization mandates redirect procurement toward Saudi-certified molders for infrastructure-grade applications. The Tabuk supply base remains underdeveloped, creating logistics complexity for just-in-time delivery requirements.
Saudi Arabia Plastic Components Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with petrochemical-integrated players capturing resin supply advantages while independent molders compete on customization velocity. Market structure tilts toward upstream integration, as feedstock proximity determines margin sustainability in commodity-grade segments. Three archetypes dominate: SABIC-affiliated operations with captive resin access, Jubail-proximate converters leveraging logistics cost advantages, and Riyadh-based specialists targeting regulatory-intensive food-contact and medical-grade certifications. Capacity expansion and certification acceleration represent the dominant competitive moves, as import channel compression under Vision 2030 localization intensifies qualification races.
Among Eastern Province-integrated fabricators, SABIC anchors the petrochemical-affiliated tier with upstream polymer positioning, while Zamil Plastic occupies proximity-driven conversion capacity near Jubail feedstock infrastructure. Arabian Plastics Industrial Company Limited exemplifies the Riyadh-based specialist archetype targeting automotive tier-one supplier qualification programs. These three represent distinct strategic postures: captive supply control, logistics-optimized conversion, and certification-premium positioning.
| Leading Market Players |
|---|
| Arabian Plastics Industrial Company Limited |
| Zamil Plastic |
| Rowad National Plastic Company Ltd |
| Takween Advanced Industries |
| Tamam Plastic Factory |
| SABIC |
| Saudi Arabian Amiantit Company |
| Al Watania Plastics |
| Napco National |
| Others |
Value Network & Pricing Analysis
Centralized procurement mandates from Riyadh-based retail chains are compressing supplier qualification timelines and forcing domestic molders to absorb tooling ownership costs upfront, elevating working capital requirements while creating pricing stratification between certified and non-certified supply tiers.
Pricing Analysis
Capacity additions in Jubail's petrochemical corridor are reshaping price floors for HDPE and PP resin grades, transmitting downstream cost advantages to blow molding converters serving pharmaceutical packaging. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-validated medical-grade batches from commodity food-contact and construction-grade volumes. Pricing pressure stems from crude-linked naphtha volatility compressing margin stability for non-integrated molders. Tier-one automotive suppliers demonstrate least price sensitivity due to IATF 16949 certification barriers, while construction-grade extrusion buyers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Dammam and Riyadh operate hub-and-spoke patterns feeding manufacturing corridors across the Central and Eastern Provinces. Raw material supply draws from Saudi Arabia's Jubail cluster, supplemented by resin imports through Jeddah's Red Sea port facilities. Feedstock dependency rests on SABIC's upstream polymer production and imported specialty grades subject to SASO conformity assessment delays. Single-source vulnerability concentrates in medical-grade masterbatch additives where European compounders retain formulation dominance. Distribution runs through direct sales agreements for high-volume automotive and packaging accounts, with distributors serving fragmented construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in medical-grade certification premiums and maintenance-contract recurring revenue, as SFDA validation requirements and buyer consolidation elevate pricing power for qualified domestic molders.
For Market Incumbents: Acquire mold flow simulation engineering talent to compress new product qualification timelines for complex automotive interior geometries. Backward integration into specialty resin compounding capabilities secures formulation control ahead of restricted substance enforcement deadlines. Defensive positioning requires accelerating sterile packaging validation for pharmaceutical distribution contracts before import channel compression intensifies under Vision 2030 mandates. For New Entrants and Emerging Players: Digital procurement platforms serving commodity-grade consumer goods offer lowest barrier entry points with reduced certification overhead. White-space targets concentrate in NEOM infrastructure-grade extruded pipe and modular building components where localization mandates redirect procurement from established import channels. Direct-to-manufacturer positioning bypasses wholesale intermediation fastest in construction segments with standardized technical specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with Riyadh-based specialists holding concurrent SFDA food-contact and medical-grade certifications. Long-term viability favors molders with captive maintenance contract revenue streams and mold ownership transfer clauses embedded in multi-year supply agreements. Watch for SASO enforcement acceleration on imported resin batches as inflection indicator for domestic share expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Medical Device Grade Certification | Regulatory tailwinds favor domestic molders achieving sterile packaging validation for pharmaceutical distribution. |
| Backward Integration into Specialty Resin Compounding | Formulation control ahead of restricted substance limits reshapes competitive positioning for food-contact applications. |
| Digital Melt Flow Monitoring Deployment | IoT-enabled statistical process control commands pricing premiums in high-tolerance automotive interior supply. |
| Tooling Maintenance Contract Expansion | Recurring revenue streams pivot equipment suppliers from transactional mold sales toward embedded service relationships. |
| Eastern Province Capacity Expansion | Proximity to Jubail feedstock infrastructure reduces logistics costs for export-oriented automotive tier-one supply. |
Research Methodology
Direct dialogue with injection molding plant managers, automotive tier-one procurement leads, pharmaceutical packaging technical directors, and SFDA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from SASO technical regulations, SFDA food-contact material guidelines, SABIC polymer supply disclosures, and customs trade data for resin import volumes. Bottom-up modeling of individual facility capacities and top-down reconciliation against petrochemical feedstock flows ensured cross-verified demand estimates.
Segment-level value outputs across the projection horizon reflect disaggregation by conversion technology, end-use application intensity, and procurement channel concentration. Modeled dimensions encompass injection versus blow versus extrusion versus thermoforming process economics, packaging versus automotive versus medical versus consumer goods specification tiers, and direct sales versus distributor versus digital channel structures. CAGRs derive from elasticity-adjusted demand curves incorporating Vision 2030 localization policy implementation trajectories and crude-linked resin price transmission coefficients.
Polymer price volatility, SASO certification timeline extensions, and buyer consolidation acceleration are the dominant revision risks that could compress or extend domestic molder share expansion trajectories. Forecasts reflect documented assumptions around regulatory enforcement schedules and petrochemical capacity commissioning sequences. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Graphite Recycling Market