
 Indonesia Plastics Market | 2026-2036
Indonesia Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastics Market Foresight
Food-grade and engineering-grade specification tiers is bifurcating Indonesia's plastics landscape as converters chase higher-margin contracts. PT Polychem Indonesia Tbk leverages its integrated petrochemical feedstock position to supply standardized resin at scale. PT. Engineering Plastics Asia (EPA) differentiates through specialty compounding for automotive and electronics OEMs. PT Plastin Eka Prakarsa anchors the flexible packaging segment with blown film extrusion capacity serving palm oil and instant noodle exporters.
Plastics comprise synthetic or semi-synthetic organic polymers—typically carbon backbone chains with hydrogen, oxygen, nitrogen, sulfur, or chlorine substituents—processed through injection molding, extrusion, blow molding, or thermoforming to achieve melt flow indices between 0.3 and 50 g/10 min for targeted mechanical performance. Polyethylene and polypropylene together dominate resin consumption by tonnage, reflecting their dominance in flexible packaging films and rigid containers across Indonesia's food processing and FMCG supply chains. Molded parts and extruded products capture divergent margin pools, with injection-molded automotive components commanding premium pricing over commodity construction pipes where BIS-equivalent SNI certification creates entry barriers.
Indonesia's Ministry of Environment and Forestry enforces extended producer responsibility mandates under Law No. 18/2008 on Waste Management, while the National Standardization Agency (BSN) administers SNI marking for food-contact plastics and construction-grade PVC. These frameworks compel domestic processors to reformulate with recycled content or biodegradable additives to retain market access. Stakeholders must track enforcement intensity around import restrictions on scrap plastics and the evolving SNI technical requirements for recycled-content products before committing capital to capacity expansion.
Market Dynamics
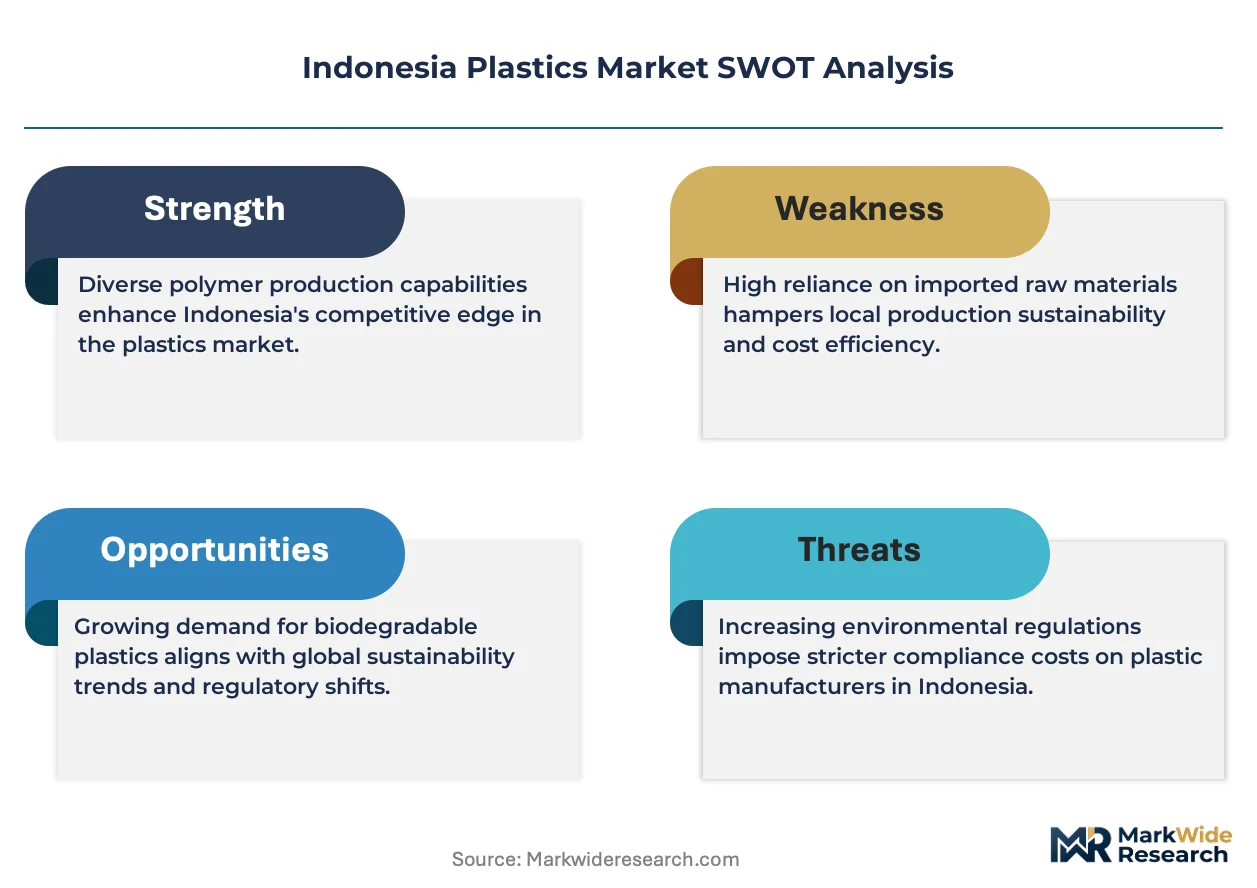
Extended producer responsibility mandates from Indonesia's Ministry of Environment and Forestry are forcing converters to reformulate product lines around recycled content and biodegradable additives, compressing margins for commodity resin processors while opening premium positioning for compliant specialists.
Growth Catalysts
- Food-contact SNI certification:BSN marking requirements for palm oil and instant noodle packaging are pulling investment into food-grade blown film capacity around Surabaya's industrial zones.
- Automotive lightweighting:Engineering-grade compounded resins for interior panels and under-hood components are displacing metal stampings as Japanese and Korean OEMs expand Indonesian assembly operations.
- Java demand concentration:Jakarta's manufacturing belt and surrounding satellite cities generate sustained offtake for rigid containers serving FMCG distribution networks.
Market Restraints
- Naphtha feedstock volatility:Integrated petrochemical producers face margin compression when regional naphtha benchmarks spike, disadvantaging non-backward-integrated compounders.
- Import dependency for specialty additives:Flame retardants, UV stabilizers, and impact modifiers concentrate supply with Chinese and Korean chemical exporters, exposing converters to freight cost swings and currency risk.
- Mechanical recycling contamination limits:Post-consumer feedstock quality variability restricts output suitability for food-contact applications, capping recycled-content penetration in premium packaging tiers.
Strategic Opportunities
- Eastern Indonesia logistics gap:Sulawesi and Papua present underpenetrated demand for construction-grade PVC piping where imported alternatives face freight disadvantages.
- Chemical recycling scale-up:Pyrolysis and depolymerization investments can convert mixed plastic waste into virgin-equivalent feedstock, bypassing mechanical recycling quality ceilings.
- Biodegradable mulch films:Ministry of Agriculture pilot programs for cassava and rubber plantations are creating first-mover openings for PLA and starch-blend formulations.
Industry Challenges
- Compounding technician scarcity:Formulation chemistry and twin-screw extrusion operation skills lag demand growth, extending commissioning timelines for new specialty lines.
- SNI certification backlog:BSN testing queue delays for recycled-content food-contact products extend product launch timelines by four to eight months.
- Legacy injection molding retrofit costs:Converters face capital intensity when adapting older presses for bioplastic processing with narrower temperature windows and moisture sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastics Market |
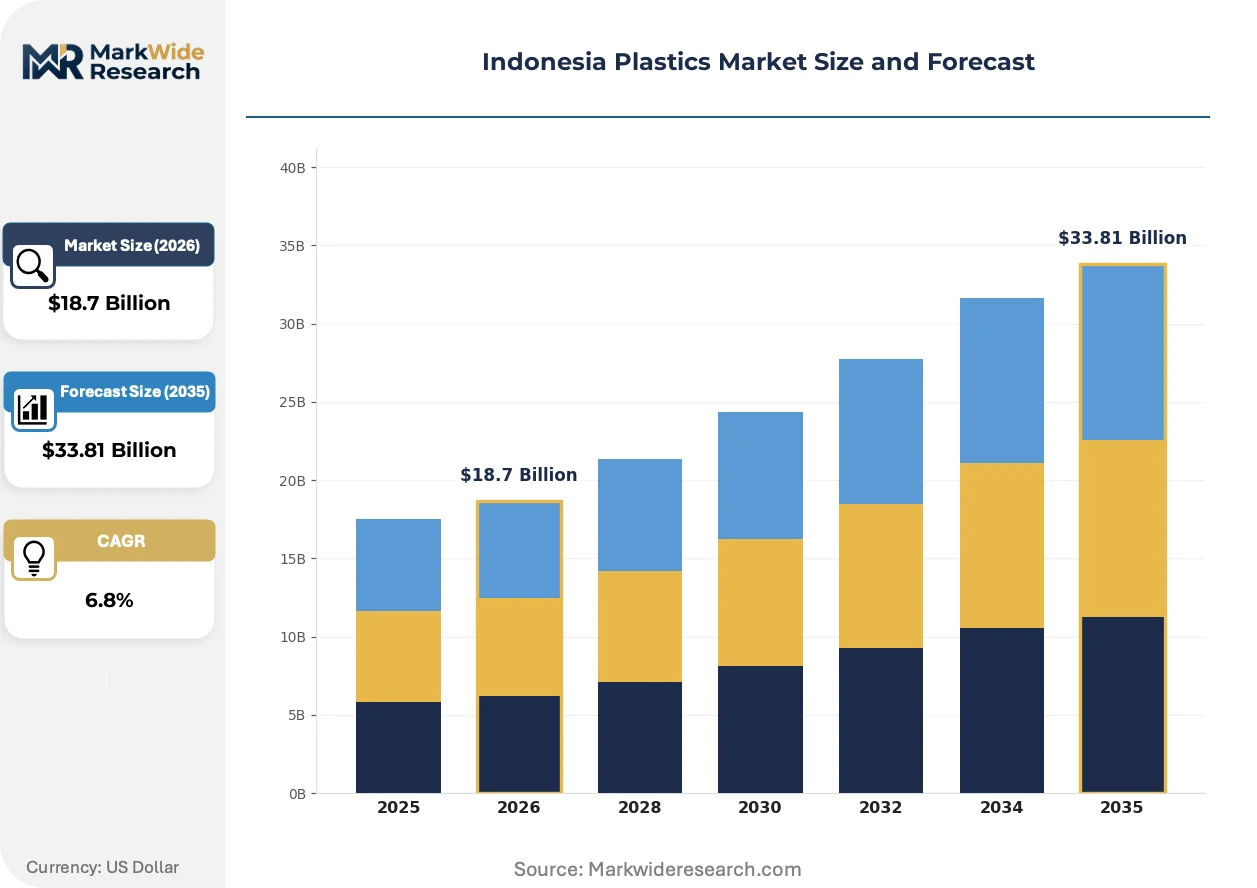
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Packaging, Automotive, Construction, Consumer Goods Form: Films, Sheets, Molded Parts, Extruded Products Application: Containers, Bottles, Pipes, Automotive Components |
| Companies Covered | PT. Dinito Jaya Sakti, PT Centraplast Indonesia, PT Plastin Eka Prakarsa, PT Deltapack Industri, PT. Cave Sumber Berkat, PT. Indah Varia Ekaselaras (IVES), PT. Kreasi Dasatama (Impraboard), PT Polychem Indonesia Tbk, PT. Engineering Plastics Asia (EPA), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastics Market Shifts & Advancements
Converters across Java are reconfiguring production lines around sustainability-linked specifications and digital process control, shifting competitive advantage from scale economies to formulation agility and certification velocity.
Barrier-coated mono-material films are displacing multi-layer laminates in snack and confectionery packaging. Nestlé and Indofood suppliers are adopting metallized or SiOx-coated polyethylene structures to meet recyclability pledges while preserving oxygen and moisture barriers. This displacement is compressing demand for adhesive lamination equipment and EVOH coextrusion lines in favor of coating and metallizing capacity expansions.
Indonesia's Ministry of Environment and Forestry is tightening enforcement timelines for Law No. 18/2008 waste management provisions, with draft regulations specifying 30 percent recycled content floors for rigid containers by 2030. Brand owners are accelerating supplier audits and pre-qualifying converters with verified post-consumer feedstock traceability. Food and beverage multinationals with Indonesian manufacturing footprints are most exposed, pushing reformulation partnerships with domestic recyclers.
Direct mill procurement contracts are fragmenting traditional distributor channels for standard-grade polyethylene and polypropylene. Large flexible packaging groups in Tangerang and Sidoarjo are negotiating resin offtake directly with Chandra Asri and Lotte Chemical Titan, bypassing regional traders. This channel compression is most visible in high-volume film applications where price transparency and logistics integration outweigh distributor credit terms.
Indonesia Plastics Market Segmentation
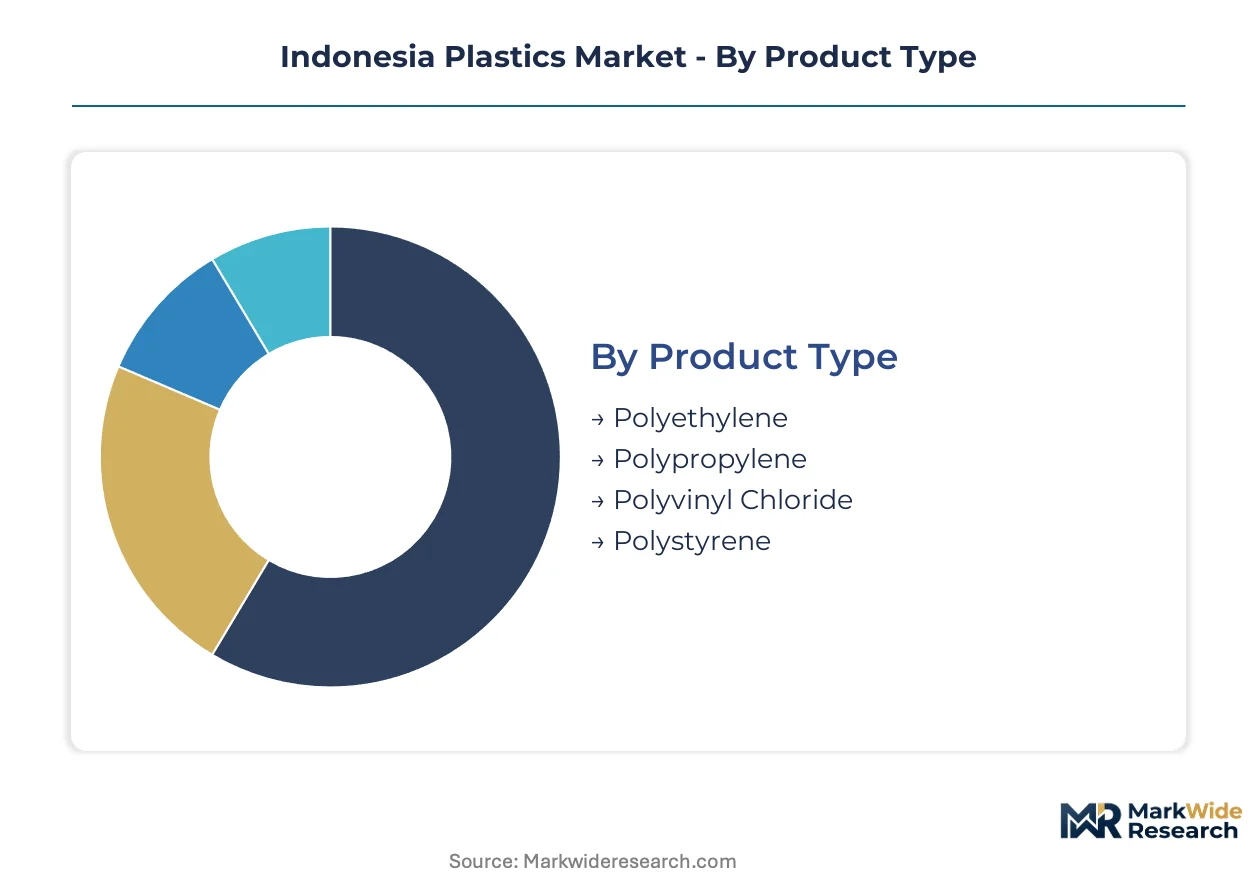
Segmentation in Indonesia's plastics market reveals how regulatory pressure and feedstock integration reshape competitive boundaries. Converters must align product portfolios with SNI certification tiers and extended producer responsibility mandates to secure offtake from multinational brand owners.
Product Type:
BSN marking requirements and food-contact safety standards create divergent compliance burdens across resin chemistries, splitting the competitive landscape between commodity scale players and specialty compounders.
- Polyethylene:Linear low-density and high-density grades dominate flexible packaging films for palm oil and instant noodle exports. Demand clusters around Surabaya's industrial zones where blown film extruders serve FMCG supply chains requiring food-grade SNI certification.
- Polypropylene:Homopolymer and copolymer variants command premium pricing in rigid containers and automotive interior panels. Japanese and Korean OEM assembly expansions in Java are pulling compounded grades with tailored melt flow indices for injection molding efficiency.
- Polyvinyl Chloride:Construction-grade formulations face SNI-equivalent certification barriers for piping applications, with demand concentrated in Jakarta's infrastructure build-out and Eastern Indonesia logistics gaps.
- Polystyrene:General-purpose and high-impact grades serve consumer goods and food service disposables, though single-use restrictions under Law No. 18/2008 are compressing growth trajectories in favor of biodegradable alternatives.
Polyethylene handles the majority of throughput; polypropylene is expanding most quickly on share as automotive lightweighting accelerates.
End User:
Customer procurement patterns fragment between direct mill contracts for volume buyers and distributor channels for smaller converters, with margin structures varying by order scale and certification complexity.
- Packaging:Flexible films and rigid containers for food processing, palm oil, and instant noodles represent the dominant value pool. Nestlé and Indofood suppliers are reconfiguring lines around barrier-coated mono-material structures to meet recyclability pledges.
- Automotive:Engineering-grade compounded resins for interior panels and under-hood components displace metal stampings. Japanese OEMs expanding Indonesian assembly operations specify flame-retardant and UV-stabilized formulations requiring imported additives.
- Construction:PVC piping and extruded profiles serve Jakarta's manufacturing belt infrastructure and Eastern Indonesia development gaps where imported alternatives face freight disadvantages.
- Consumer Goods:Molded household items and electronics housings compete on cycle time and surface finish, with price pressure from Chinese import competition squeezing domestic processor margins.
Packaging captures the largest volume position; automotive is climbing the fastest as OEM localization deepens.
Form:
Processing technology selection determines capital intensity and formulation flexibility, with twin-screw extrusion and injection molding commanding distinct technician skill premiums.
- Films:Blown and cast extrusion outputs serve flexible packaging with metallized or SiOx-coated mono-material structures displacing multi-layer laminates. Surabaya converters are expanding coating capacity to meet Nestlé supplier sustainability specifications.
- Sheets:Thermoforming feedstock for trays and clamshells requires tight gauge control for food-contact applications, with SNI certification queues extending launch timelines.
- Molded Parts:Injection-molded automotive components and consumer goods command premium pricing over commodity extrusion, though legacy press retrofit costs for bioplastic processing narrow temperature windows.
- Extruded Products:Construction pipes and profiles face BIS-equivalent SNI certification entry barriers, with demand concentrated in Java and underpenetrated Eastern Indonesia markets.
Films absorb the greatest resin tonnage; molded parts are gaining share fastest as automotive specifications tighten.
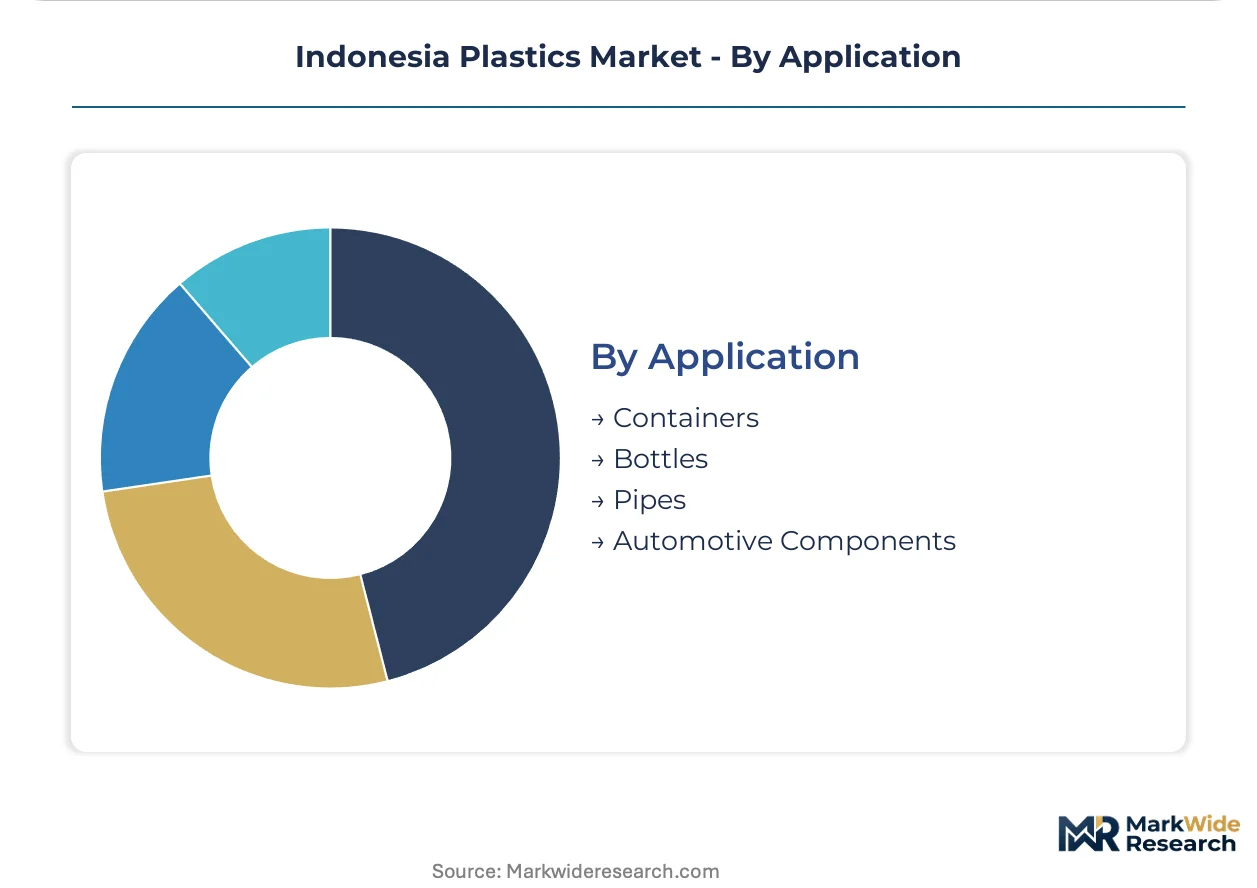
Application:
Functional performance requirements and recyclability mandates reshape specification trajectories, with mono-material designs displacing complex multi-layer structures.
- Containers:Rigid polyethylene and polypropylene vessels for FMCG distribution networks face draft regulations specifying recycled content floors. Brand owners are pre-qualifying converters with verified post-consumer feedstock traceability.
- Bottles:Blow-molded packaging for beverages and personal care competes on weight reduction and clarity, with chemical recycling investments targeting virgin-equivalent feedstock quality.
- Pipes:PVC and PE pressure piping for water infrastructure and construction requires SNI marking, with Eastern Indonesia logistics gaps creating regional supply advantages for domestic producers.
- Automotive Components:Interior panels, bumpers, and under-hood parts specify engineering-grade compounds with flame retardancy and impact resistance, importing additives from Chinese and Korean chemical exporters.
Containers represent the dominant application volume; automotive components are expanding most steeply as OEM sourcing localizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian resin production clusters around integrated petrochemical complexes in Banten and East Java, with converter demand radiating outward from Jakarta's manufacturing belt and Surabaya's industrial zones. Provincial governments are layering local content requirements onto national environmental mandates, reshaping investment flows across the archipelago.
Java
Java absorbs the majority of national resin offtake, with Jakarta's satellite cities generating sustained demand for rigid FMCG containers and Tangerang flexible packaging groups negotiating direct mill contracts. The Ministry of Environment and Forestry's extended producer responsibility enforcement concentrates inspection capacity on this island. Surabaya's blown film extruders are expanding metallizing capacity to meet Nestlé supplier sustainability specifications.
Sumatra
Sumatra's palm oil processing complexes drive food-grade film demand, with Medan converters serving edible oil export packaging requirements. Provincial environmental agencies are implementing Law No. 18/2008 waste management provisions with varying intensity across North Sumatra and Riau. Batam's free trade zone attracts specialty compounders seeking duty advantages on imported additives.
Sulawesi
Sulawesi presents underpenetrated construction-grade PVC demand where imported piping faces freight disadvantages against domestic extruders. Regional infrastructure budgets are accelerating water distribution network rollouts. Makassar's industrial corridor is emerging as a distribution hub for Eastern Indonesia markets.
Kalimantan
Kalimantan's mining and plantation economies generate niche industrial packaging requirements distinct from Java's FMCG concentration. Provincial governments are piloting biodegradable mulch film programs for oil palm and rubber smallholders. Balikpapan's port infrastructure supports resin import logistics for Borneo-based converters.
Indonesia Plastics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's plastics value chain. Integrated petrochemical producers with captive naphtha cracking dominate commodity resin supply, while specialty compounders command premium positioning through formulation chemistry capabilities. The competitive structure bifurcates between scale-driven standard resin suppliers and agility-focused engineering-grade specialists. Dominant competitive moves include backward integration into recycled feedstock sourcing and strategic partnerships with brand owners for pre-qualified supplier status.
Within the integrated petrochemical tier, PT Polychem Indonesia Tbk exemplifies scale-driven commodity resin supply. PT. Engineering Plastics Asia (EPA) occupies a position among specialty compounders serving automotive and electronics OEMs. PT Plastin Eka Prakarsa anchors the flexible packaging segment with blown film capacity serving export-oriented food processors.
| Leading Market Players |
|---|
| PT. Dinito Jaya Sakti |
| PT Centraplast Indonesia |
| PT Plastin Eka Prakarsa |
| PT Deltapack Industri |
| PT. Cave Sumber Berkat |
| PT. Indah Varia Ekaselaras (IVES) |
| PT. Kreasi Dasatama (Impraboard) |
| PT Polychem Indonesia Tbk |
| PT. Engineering Plastics Asia (EPA) |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day resin inventory cycles at Java-based converters signal supply-chain rigidity that amplifies pricing power for integrated petrochemical producers during naphtha volatility spikes. This lead-time compression concentrates procurement leverage with backward-integrated suppliers while forcing non-integrated compounders into spot-market exposure.
Pricing Analysis
Law No. 18/2008 on Waste Management dictates the pricing tier structure across Indonesia's plastics value chain, with SNI-certified food-grade resins commanding premium positioning over commodity construction grades. Three-tier pricing structure across premium, standard, and economy levels separates compliant specialty compounds from uncertified commodity resin. Cost compression in standard-grade polyethylene is intensifying because direct mill procurement contracts are fragmenting distributor channels. Small-scale converters in Eastern Indonesia exhibit highest price sensitivity, while automotive OEMs demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory management among integrated producers, while just-in-tight logistics constrain smaller converters to hand-to-mouth procurement. Naphtha feedstock draws from Singapore, South Korea, and regional Middle Eastern suppliers, with specialty additives sourcing anchored in China and Korea. Single-source vulnerability concentrates in flame retardant and UV stabilizer supply chains. Distribution runs through direct mill contracts for volume buyers and regional trader networks for smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plastics market functions as a defensive-moat arena where SNI certification entrenchment creates switching costs that protect incumbent positioning against commodity erosion.
For Market Incumbents: Secure pre-qualified supplier status with Nestlé and Indofood sustainability programs before draft recycled-content regulations crystallize. Deepen backward integration into post-consumer feedstock sourcing to bypass mechanical recycling quality ceilings. Channel control through direct mill contracts represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Specialty compounding technician training services present a service-layer gap where incumbents under-serve converter capability building needs. Sulawesi construction-grade PVC piping and Kalimantan biodegradable mulch films represent the most penetrable white-space targets. A technical partnership model with provincial agricultural extension offices unlocks first-mover positioning in Eastern Indonesia. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with non-core plastics assets lacking SNI certification velocity. Five-to-ten-year viability centers on regulatory compliance infrastructure rather than commodity scale. Watch for BSN testing queue clearance rates as the inflection indicator for certification-constrained converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captures post-consumer supply chains before Law No. 18/2008 enforcement tightens. |
| SNI Certification Acceleration | Compresses BSN testing timelines to secure food-contact market access ahead of competitors. |
| Eastern Indonesia Distribution Buildout | Exploits freight disadvantages facing imported PVC piping in Sulawesi infrastructure markets. |
| Specialty Compounding Capacity Expansion | Serves Japanese OEM lightweighting specifications with flame-retardant engineered resins. |
| Biodegradable Formulation Partnerships | Aligns with Ministry of Agriculture pilot programs for cassava plantation mulch films. |
Research Methodology
The analysis maps polyethylene grades, polypropylene compounds, PVC formulations, and polystyrene variants, each validated through extrusion plant managers, automotive procurement leads at Japanese OEMs, flexible packaging technical directors, and BSN certification officers. Primary interview insights triangulate against customs trade data, Ministry of Environment enforcement disclosures, SNI technical requirement documents, and SEC filings from listed petrochemical producers. Bottom-up resin consumption estimates reconcile with top-down macroeconomic drivers across the analysis window.
Consistency checks validate volume and value outputs against regional naphtha consumption patterns and converter capacity utilization surveys. The analytical framework segments by resin chemistry, end-use industry, processing technology, and geographic demand cluster across the projection horizon. CAGRs derive from regression modeling of historical consumption elasticities against GDP and industrial production indices, with automotive localization rates and palm oil export volumes serving as industry-specific forecast inputs.
Underlying assumptions cover SNI enforcement timelines and naphtha price band stability, with deviation risk concentrated in recycled-content regulation finalization and specialty additive import policy shifts. Revision becomes warranted when BSN certification backlog durations or chemical recycling investment flows cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Drums Market