
 Recyclability-Optimized Impact Modifiers for Polyolefins Market | 2026-2036
Recyclability-Optimized Impact Modifiers for Polyolefins Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclability-Optimized Impact Modifiers for Polyolefins Market Insights
Compatibilizer technology is fragmenting as maleic anhydride grafted polymers and styrene-ethylene-butylene-styrene systems diverge in performance profiles for closed-loop recycling. Dow leverages its polyethylene expertise to anchor North American supply chains for post-consumer polyolefin upcycling. BASF competes through differentiated additive architectures that sustain impact strength across multiple regrind cycles. Mitsui Chemicals specializes in Asian automotive qualification programs for recycled-content dashboards and bumper substrates.
Recyclability-optimized impact modifiers for polyolefins are functional additives, typically 5-20 wt% loading, that restore or maintain Izod impact resistance and elongation-at-break in reprocessed polyethylene and polypropylene without compromising melt flow index or optical properties. Their primary purpose is enabling mechanical recycling streams to produce specification-grade resins for demanding applications rather than downcycled products. Ethylene-propylene rubber modifiers dominate current volume due to mature supply chains and broad polyolefin compatibility, though maleic anhydride grafted polymers capture expanding margin pools where polar contamination requires reactive compatibilization. Polypropylene random copolymer represents the fastest-growing substrate category as appliance and automotive OEMs specify higher recycled content in injection-molded components.
The EPA promotes recycled content procurement through federal purchasing guidelines, while the EU Green Deal and REACH constrain legacy additive chemistries in circular material flows. FDA food-contact recycling notifications shape which modifier packages qualify for packaging film applications in the United States. Stakeholders must monitor how evolving Extended Producer Responsibility frameworks in California, Germany, and Japan redefine acceptable modifier chemistries and performance certification protocols for next-generation recycled polyolefin grades.
Market Dynamics
Closed-loop recycling mandates from the EU Green Deal and Japan's resource circulation policies are forcing reformulation of polyolefin compounds across automotive and packaging supply chains, compressing qualification timelines for impact modifier suppliers.
Growth Catalysts
- REACH-compliant additive packages:ECHA restrictions on legacy plasticizers are accelerating migration to maleic anhydride grafted compatibilizers that maintain performance across regrind cycles.
- Automotive circular economy mandates:Germany's End-of-Life Vehicle Directive revisions require dashboard and bumper substrates to achieve 30% recycled content without Izod impact degradation.
- Post-consumer resin upcycling infrastructure:Mechanical recycling lines in the US Southeast are installing advanced melt filtration that tolerates broader modifier chemistries.
Market Restraints
- Ethylene-propylene rubber supply concentration:Southeast Asian EPR production clusters expose modifier formulators to monomer price volatility and force majeure risk.
- Reactive compatibilization complexity:Maleic anhydride grafting requires precise control of graft density; off-spec batches contaminate entire regrind streams.
- FDA food-contact notification timelines:Packaging film applications face 18-24 month approval cycles that freeze modifier selection during brand owner sustainability pivots.
Strategic Opportunities
- Polypropylene random copolymer specification:Appliance OEMs in Italy and Spain are qualifying higher recycled-content injection-molded components for dishwasher and washing machine housings.
- Extended Producer Responsibility frameworks:California's SB 54 implementation creates compliance-driven demand for certified recyclability in flexible packaging films.
- Blockchain-tracked material passports:Digital provenance systems enable premium pricing for modifiers bundled with verified regrind cycle documentation.
Industry Challenges
- Multi-cycle performance certification:Automotive Tier-1 suppliers demand Izod and elongation data across five regrind iterations; testing protocols lack standardization.
- Reactive extrusion scale-up:Pilot-scale maleic anhydride grafting successes fail to translate to continuous production due to residence time distribution mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclability-Optimized Impact Modifiers for Polyolefins Market |
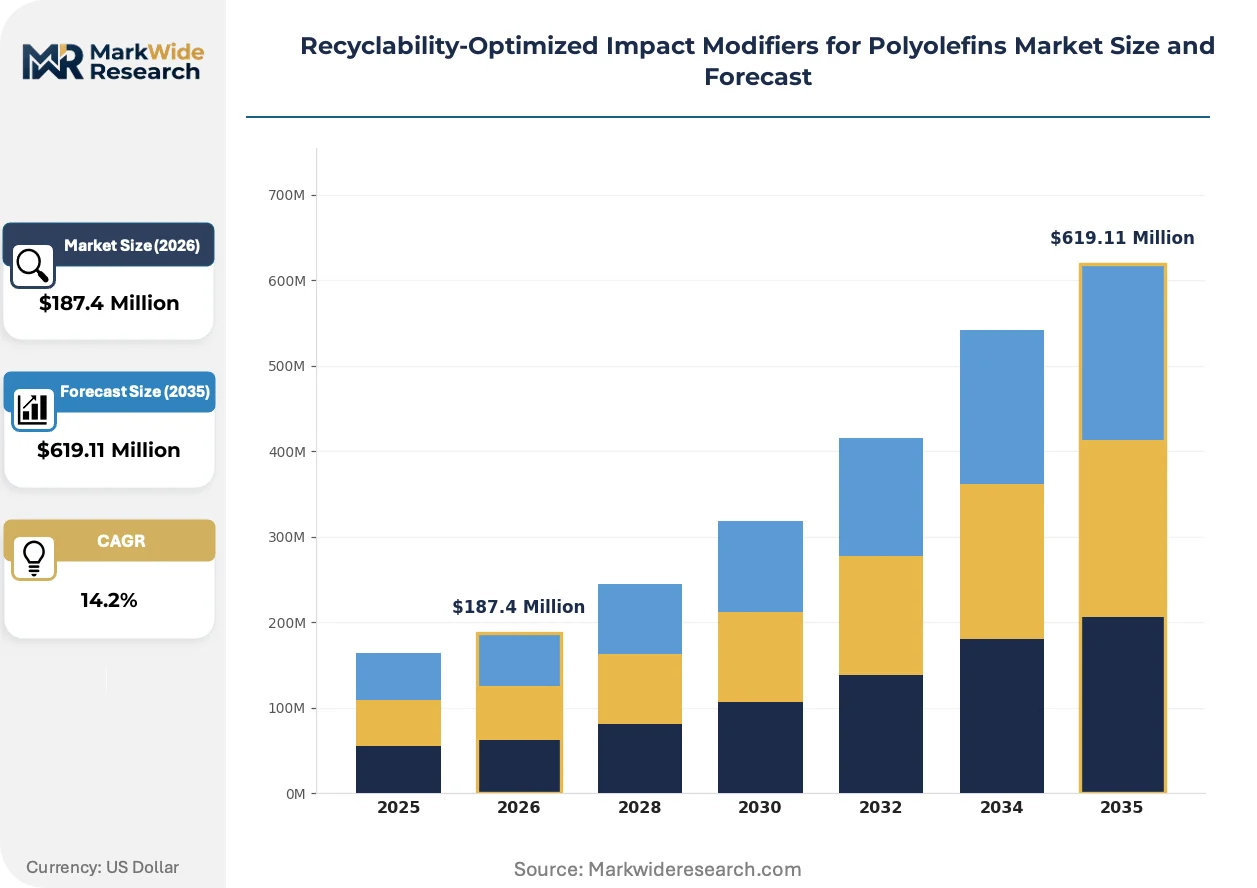
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Modifier Type: Ethylene-Propylene Rubber, Styrene-Butadiene Rubber, Polyacrylate, Styrene-Ethylene-Butylene-Styrene, Maleic Anhydride Grafted Polymers Polyolefin Type: High-Density Polyethylene, Low-Density Polyethylene, Linear Low-Density Polyethylene, Polypropylene Homopolymer, Polypropylene Random Copolymer Application: Packaging Films, Automotive Components, Electrical Insulation, Consumer Goods, Construction Materials End User Industry: Packaging Manufacturers, Automotive Suppliers, Electronics Producers, Building Material Suppliers, Consumer Products Companies |
| Companies Covered | Dow, ExxonMobil, BASF, Mitsui Chemicals, LyondellBasell, SABIC, LG Chem, Borealis, Avient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclability-Optimized Impact Modifiers for Polyolefins Market Trends and Innovations
Modifier architectures are converging with digital tracking systems and reactive processing advances that compress the gap between mechanical recycling output and virgin resin performance specifications.
Bio-based impact modifiers derived from tall oil fatty acids and lignin derivatives are collapsing the price premium between sustainable and petroleum-derived additive packages. Packaging compounders in the Netherlands and Denmark are qualifying these systems for frozen food films. The technology is collapsing traditional resistance to bio-based feedstocks in cost-sensitive polyolefin applications.
REACH authorization requirements for certain phthalate-based legacy additives are forcing reformulation of flexible PVC replacement compounds in automotive interior applications. Modifier suppliers must now demonstrate SVHC compliance across entire regrind cascade documentation. European automotive OEMs are responding by consolidating approved supplier lists to those with full substance transparency.
Compounders are bundling technical service with modifier supply, embedding rheology optimization and failure analysis into standard contracts. This unbundles traditional resin distributor roles and shifts margin capture toward formulation-integrated suppliers. The pattern is most visible in German automotive supply chains where just-in-sequence delivery requires real-time viscosity adjustment support.
Recyclability-Optimized Impact Modifiers for Polyolefins Market Segmentation
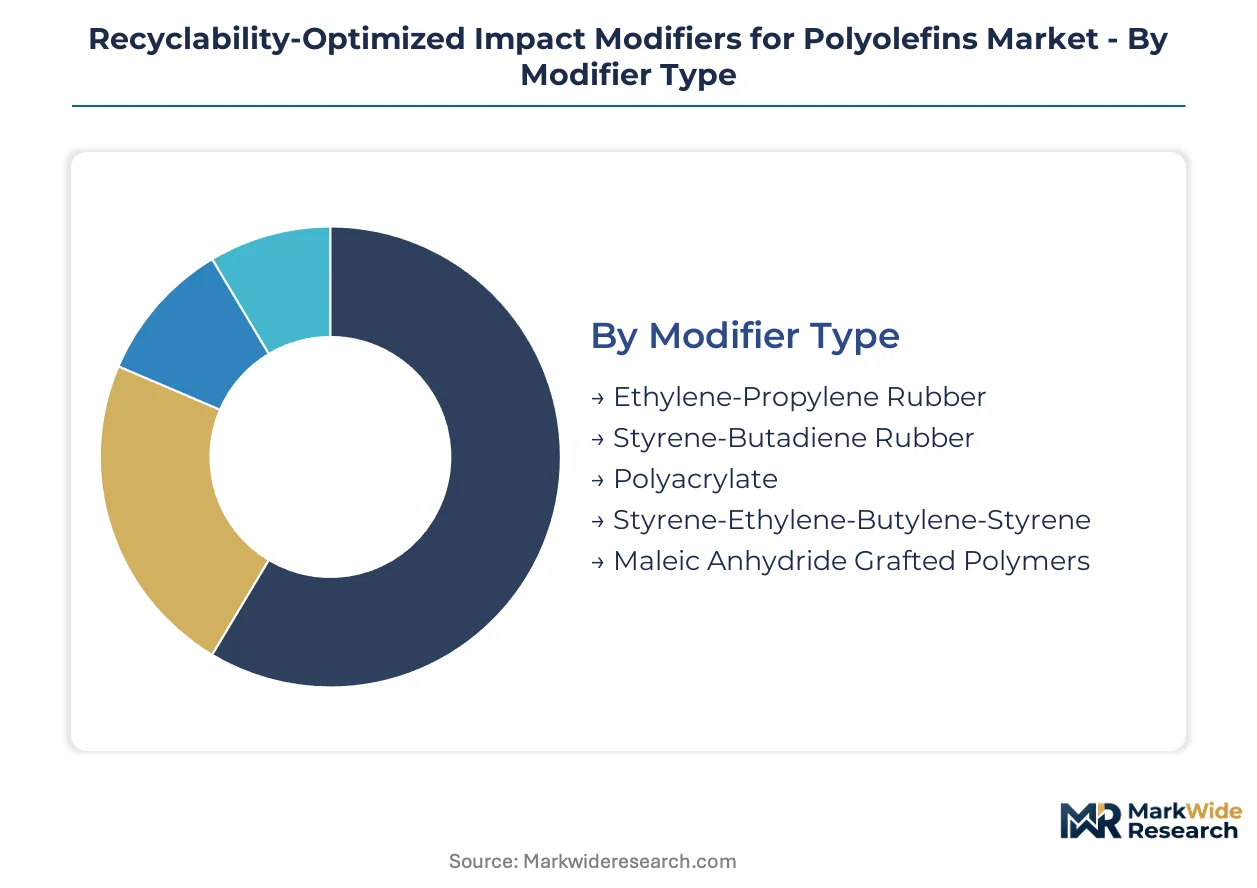
Modifier selection determines regrind cycle tolerance and end-use qualification timelines. Each segmentation dimension reveals distinct technical service intensity patterns and margin structures across the value chain.
Modifier Type:
After-sales service intensity varies sharply by modifier chemistry, with reactive systems demanding extrusion-line technical support and non-reactive grades shipping as commodity additives.
- Ethylene-Propylene Rubber:Non-polar elastomer with broad polyolefin compatibility and mature supply chains. Demand concentrates in German automotive bumper substrates where End-of-Life Vehicle Directive compliance requires predictable multi-cycle impact retention. EPR volumes dominate current procurement but face margin compression from bio-based alternatives.
- Maleic Anhydride Grafted Polymers:Reactive compatibilizers restore interfacial adhesion in contaminated post-consumer streams. Italian packaging compounders specify these for frozen food films requiring FDA notification clearance, though 18-24 month approval timelines constrain rapid formulation pivots.
- Styrene-Butadiene Rubber:Cost-effective impact restoration for non-critical consumer goods applications.
- Polyacrylate:Optical clarity preservation in transparent packaging films.
- Styrene-Ethylene-Butylene-Styrene:Premium automotive interior applications requiring low VOC emissions.
By volume, Ethylene-Propylene Rubber leads. By growth pace, Maleic Anhydride Grafted Polymers are climbing the fastest.
Polyolefin Type:
Substrate selection dictates modifier loading rates and melt processing windows, with copolymer architectures commanding formulation-integrated supplier relationships.
- Polypropylene Random Copolymer:Ethylene incorporation disrupts crystallinity for enhanced impact absorption in thin-wall injection molding. Spanish and Italian appliance OEMs specify this substrate for dishwasher housings with 30% recycled content targets under EU Green Deal packaging waste directives.
- High-Density Polyethylene:Stiffness-dominant substrate for structural automotive components. German Tier-1 suppliers demand five-regrind-cycle Izod certification for HDPE bumper beams, forcing modifier suppliers to embed rheology optimization into standard contracts.
- Low-Density Polyethylene:Flexible packaging films requiring optical property preservation.
- Linear Low-Density Polyethylene:Stretch film and industrial sack applications.
- Polypropylene Homopolymer:Cost-sensitive rigid packaging with limited regrind tolerance.
Polypropylene Random Copolymer captures the steepest expansion trajectory as automotive and appliance OEMs escalate recycled-content mandates.
Application:
Application-specific qualification protocols create divergent margin pools, with automotive certification timelines stretching 24-36 months versus 12-18 months for packaging.
- Automotive Components:Dashboard substrates and bumper systems requiring crash-performance retention across mechanical recycling cascades. Japan's resource circulation policies and Germany's ELV Directive revisions compress supplier qualification windows while demanding full substance transparency documentation.
- Packaging Films:Flexible and rigid formats for food contact. California's SB 54 Extended Producer Responsibility framework creates compliance-driven demand for blockchain-tracked material passports verifying modifier package recyclability.
- Electrical Insulation:Wire and cable jacketing with dielectric stability requirements.
- Consumer Goods:Durable household products with moderate performance thresholds.
- Construction Materials:Geosynthetics and pipe applications with long service life demands.
Automotive Components generate the highest per-kilogram modifier value. Packaging Films are expanding most quickly under regulatory pressure.
End User Industry:
Customer concentration patterns shape pricing architecture, with consolidated automotive suppliers extracting volume discounts and fragmented packaging compounders accepting formulation-integrated service premiums.
- Automotive Suppliers:Tier-1 injection molders in Germany and Japan consolidating approved supplier lists to modifiers with REACH-compliant additive packages and full SVHC documentation. Just-in-sequence delivery requirements force real-time viscosity adjustment support.
- Packaging Manufacturers:Dutch and Danish compounders qualifying bio-based tall oil fatty acid modifiers for frozen food films, collapsing historical price premiums between sustainable and petroleum-derived systems.
- Electronics Producers:Flame-retardant compatibility requirements in connector housings.
- Building Material Suppliers:Geosynthetic applications with 50-year durability specifications.
- Consumer Products Companies:Cost-optimized formulations with minimal technical service engagement.
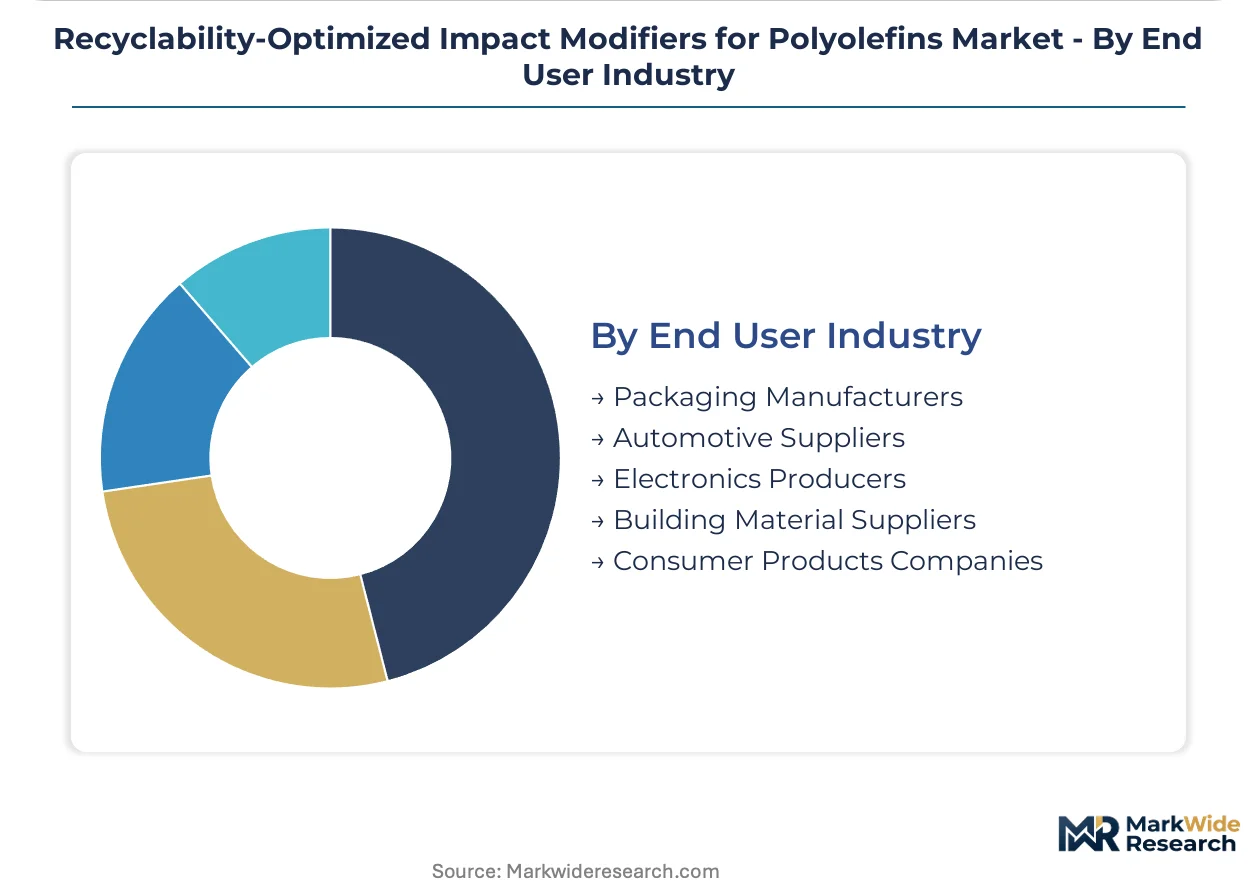
Automotive Suppliers concentrate procurement volume. Packaging Manufacturers are gaining share fastest as EPR frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive Tier-1 suppliers in Germany and Japan concentrate procurement volume for recyclability-optimized impact modifiers. Packaging compounders in Italy and the Netherlands drive fastest-growing demand under Extended Producer Responsibility frameworks. Regulatory divergence across major economies fragments qualification protocols for modifier suppliers.
United States
Mechanical recycling operators in the US Southeast install advanced melt filtration systems that tolerate broader modifier chemistries. The EPA promotes recycled content procurement through federal purchasing guidelines. Dow leverages its polyethylene expertise to anchor North American supply chains for post-consumer polyolefin upcycling.
Germany
German automotive suppliers consolidate approved supplier lists to modifiers with full SVHC documentation under REACH. The End-of-Life Vehicle Directive revisions mandate 30% recycled content in dashboard and bumper substrates. BASF competes through differentiated additive architectures that sustain impact strength across multiple regrind cycles.
Japan
Japanese automotive OEMs specify recycled-content dashboards and bumper substrates under resource circulation policies. METI drives circular economy standardization across material flows. Mitsui Chemicals specializes in Asian automotive qualification programs for these demanding applications.
Italy
Italian appliance OEMs qualify higher recycled-content injection-molded components for dishwasher and washing machine housings. EU Green Deal packaging waste directives accelerate reformulation requirements. Packaging compounders in northern industrial clusters specify maleic anhydride grafted polymers for frozen food films.
Netherlands
Dutch packaging compounders qualify bio-based tall oil fatty acid modifiers for frozen food films, collapsing historical price premiums between sustainable and petroleum-derived systems. REACH authorization requirements for legacy additives force rapid reformulation. Blockchain-tracked material passports enable premium pricing for modifiers with verified regrind cycle documentation.
Recyclability-Optimized Impact Modifiers for Polyolefins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The vendor base fragments between multinational petrochemical conglomerates with captive modifier production and independent additive houses with formulation-integrated service capabilities. Three strategic archetypes dominate: integrated resin suppliers, standalone modifier specialists, and regional compounders with backward integration into additive blending. Capacity expansion and portfolio diversification represent the dominant competitive moves as suppliers race to certify multi-cycle performance data.
Within the integrated petrochemical tier, Dow, BASF, and Mitsui Chemicals exemplify distinct geographic anchoring strategies. Dow represents North American supply chain control through polyethylene expertise. BASF occupies a position within European regulatory compliance architecture. Mitsui Chemicals anchors Asian automotive qualification pathways. These three entities collectively illustrate how modifier suppliers embed technical service intensity into standard contracts to capture margin from formulation-integrated relationships.
| Leading Market Players |
|---|
| Dow |
| ExxonMobil |
| BASF |
| Mitsui Chemicals |
| LyondellBasell |
| SABIC |
| LG Chem |
| Borealis |
| Avient |
| Others |
Pricing and Supply Chain Analysis
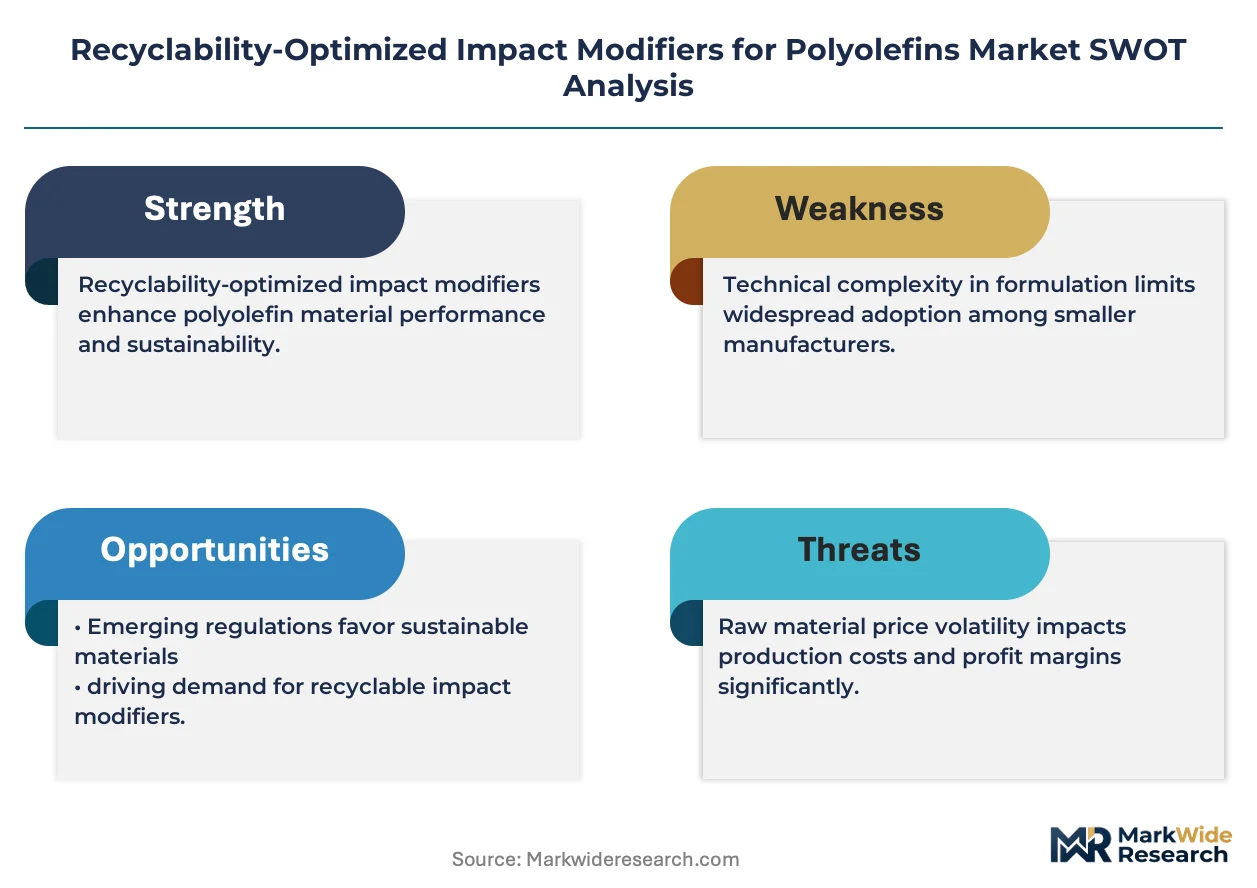
Underutilized EPR production clusters in Southeast Asia are forcing modifier suppliers to accept ethylene-propylene rubber indexation clauses tied to regional monomer benchmarks, compressing margin buffers while accelerating procurement consolidation among German automotive Tier-1 buyers seeking supply security.
Pricing Analysis
Cost-plus contracts with ethylene and propylene monomer indexation dominate modifier procurement, with premium-mid-economy pricing differentiation separating REACH-certified additive packages from commodity-grade alternatives. Price differentiation hinges on multi-cycle performance certification and embedded technical service intensity. Cost compression in standard-grade ethylene-propylene rubber is intensifying because bio-based tall oil fatty acid alternatives are collapsing historical sustainability premiums. Packaging compounders in Italy and the Netherlands exhibit highest price sensitivity due to fragmented procurement volumes, while German automotive suppliers accept formulation-integrated service premiums for just-in-sequence delivery support.
Supply Chain Analysis
Contract manufacturing concentration rests on specialty chemical producers in Germany, Japan, and the United States that operate captive modifier blending lines adjacent to automotive and packaging customer clusters. Raw material feeds draw from Southeast Asian ethylene-propylene rubber production, maleic anhydride derivatives from Gulf Coast petrochemical complexes, and tall oil fatty acids from Nordic pulp processing. Single-source vulnerability around EPR elastomer supply exposes formulators to force majeure disruption during regional monomer shortages. Distribution runs through formulation-integrated technical service relationships rather than traditional resin distributor channels, with BASF and Dow embedding rheology optimization directly into standard supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in reactive compatibilizer architectures as REACH authorization requirements displace legacy additive packages, creating niches for suppliers with full SVHC documentation and multi-cycle certification capabilities.
For Market Incumbents: Insulate margin position by deepening backward integration into maleic anhydride grafting capacity in Germany and Japan, while accelerating blockchain-tracked material passport deployment to capture premium pricing from automotive OEMs demanding verified regrind cycle documentation. Consolidate approved supplier status with German Tier-1 injection molders before ELV Directive revisions compress qualification windows further. For New Entrants and Emerging Players: Pursue white-space opportunity in bio-based tall oil fatty acid modifiers for Dutch and Danish frozen food film applications, where collapsing price premiums against petroleum-derived systems enable rapid volume capture. Target appliance OEM procurement in Spain and Italy for dishwasher housing specifications requiring 30% recycled content compliance. Lead with formulation-integrated technical service bundled with rheology optimization to differentiate from commodity additive distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation-integrated modifier specialists with embedded technical service contracts and automotive qualification pipelines. Long-term viability over the next decade favors suppliers with REACH-compliant additive architectures and multi-regrind-cycle performance data. Acquisition priority rests on independent additive houses with backward integration into reactive extrusion capabilities and established FDA food-contact notification pathways. Monitor California SB 54 implementation timelines as inflection signal for compliance-driven packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reactive Extrusion | Captive maleic anhydride grafting capacity secures supply continuity for German automotive qualification programs. |
| Blockchain-Tracked Material Passports | Digital provenance systems enable premium pricing from Dutch packaging compounders under Extended Producer Responsibility frameworks. |
| Bio-Based Feedstock Qualification | Tall oil fatty acid modifiers collapse sustainability premiums and open frozen food film applications in Denmark. |
| Multi-Cycle Performance Certification | Five-regrind Izod documentation satisfies German Tier-1 supplier consolidation of approved vendor lists. |
| Formulation-Integrated Technical Service | Real-time viscosity adjustment support captures margin from just-in-sequence automotive delivery requirements. |
Research Methodology
Operator-level perspectives from modifier plant managers, procurement leads at German automotive Tier-1 suppliers, Italian packaging compounder technical directors, and Dutch sustainability officers anchored the qualitative base. Primary interview insights combined with secondary validation from ECHA REACH authorization databases, EU Green Deal policy trackers, SEC 10-K disclosures from petrochemical conglomerates, and customs trade data for ethylene-propylene rubber flows. Bottom-up volume modeling across modifier chemistries triangulated against top-down demand projections from automotive production and packaging film output data.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning modifier type, polyolefin substrate, application category, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating recycled-content mandate trajectories in Germany, Japan, and California. Industry-specific forecast inputs included automotive OEM recycled-content specification timelines and FDA food-contact notification clearance rates for packaging film applications.
Sensitivities concentrate around EPR supply disruption, REACH authorization delays for legacy additives, and automotive qualification timeline compression. Forecasts reflect documented assumptions on regulatory enforcement intensity and mechanical recycling infrastructure deployment rates. Quarterly review of ECHA SVHC candidate list updates, California SB 54 implementation milestones, and German ELV Directive revision schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Plastic Ignition Holders Market