
 Plastic Compounds Market | 2026-2036
Plastic Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Compounds Market Intelligence
REACH restrictions on phthalate plasticizers are shifting the cost-of-entry calculus for European compounders, forcing reformulation investments that favor producers with integrated additive capabilities. BASF SE leverages its backward integration into specialty plasticizers to sustain margin structures that smaller blenders cannot replicate. SABIC anchors its position through captive petrochemical feedstock access across Saudi Arabia and the Netherlands. DuPont de Nemours, Inc. differentiates in high-heat automotive underhood segments where polyamide 66 compounds face supply constraints.
Plastic compounds are thermoplastic or thermosetting resin systems blended with fillers, stabilizers, colorants, and reinforcements to achieve specified mechanical, thermal, or electrical properties, typically processed through twin-screw extrusion or Banbury mixing to produce pelletized feedstock for injection molding and extrusion. Polypropylene compounds dominate volume flows in automotive bumper and interior applications where talc and glass fiber loading ratios determine dimensional stability. Polyethylene formulations in packaging materials command widening specification spreads between metallocene linear low-density grades and recycled-content blends. Granule form remains the default delivery format for OEMs, though powder compounds gain traction in rotational molding and dip-coating processes where melt uniformity requirements differ.
EPA regulations under the Toxic Substances Control Act govern new chemical notifications for modified polymer structures, while EU REACH compliance obligations cascade through supply chains to demand full material disclosure from compounders serving automotive parts and consumer goods. China's SAMR enforces GB standards for food-contact plastics that restrict specific additive migrations, creating non-tariff barriers for imported compounds. India's BIS certification mandates for polyvinyl chloride piping compounds similarly condition market access. Stakeholders must monitor regulatory divergence between jurisdictions where divergent substance restrictions threaten product portability and compel regional formulation specialization.
Market Dynamics
Automotive lightweighting mandates in Germany, China, and the United States are compressing material substitution timelines, forcing compounders to validate glass-filled nylon and engineered polypropylene grades against shorter design cycles than historical resin qualification protocols allowed.
Growth Catalysts
- REACH plasticizer restrictions:ECHA's phthalate limitations are redirecting European formulation investment toward bio-based and specialty plasticizer alternatives, expanding addressable market for integrated additive producers.
- China GB recycled content standards:SAMR mandates for post-consumer material incorporation are stimulating domestic compounding capacity expansion to serve certified food-grade packaging applications.
- Glass fiber loading optimization:Twin-screw extrusion advances enabling 40-60% fiber content in polyamide compounds are penetrating automotive underhood segments previously served by metal stampings.
Market Restraints
- Caprolactam supply concentration:Polyamide 66 feedstock availability remains tethered to limited adipic acid and hexamethylenediamine producers in the United States and Western Europe, exposing compounders to force majeure volatility.
- Recycled polypropylene feedstock quality variance:Inconsistent melt flow index and contamination levels in post-consumer streams constrain food-contact application certification rates.
- Per- and polyfluoroalkyl substance substitution:PFAS restrictions under EPA TSCA and EU REACH are eliminating processing aids that enabled high-speed thin-wall injection molding, requiring slower cycle times or reformulation investment.
Strategic Opportunities
- India packaging conversion sector:Domestic film and rigid container demand is outpacing local compounding capacity, creating import substitution and greenfield investment openings for food-grade certified producers.
- Battery electric vehicle thermal management:Polypropylene compounds with enhanced thermal conductivity are penetrating battery module housings and cooling plate applications as OEMs redesign powertrain architectures.
- Chemical recycling feedstock integration:Pyrolysis-derived naphtha qualification for virgin-quality polymer production is enabling circular content claims that satisfy brand owner sustainability procurement criteria.
Industry Challenges
- Color matching across distributed compounding networks:Achieving Lot-to-Lot consistency in custom-matched automotive interior specifications requires spectrophotometry calibration protocols that smaller regional blenders struggle to maintain.
- Multi-jurisdiction substance disclosure:SCIP database entries for EU REACH, EPA TSCA new chemical notifications, and China's MEE environmental registration impose parallel documentation burdens that fragment quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Compounds Market |
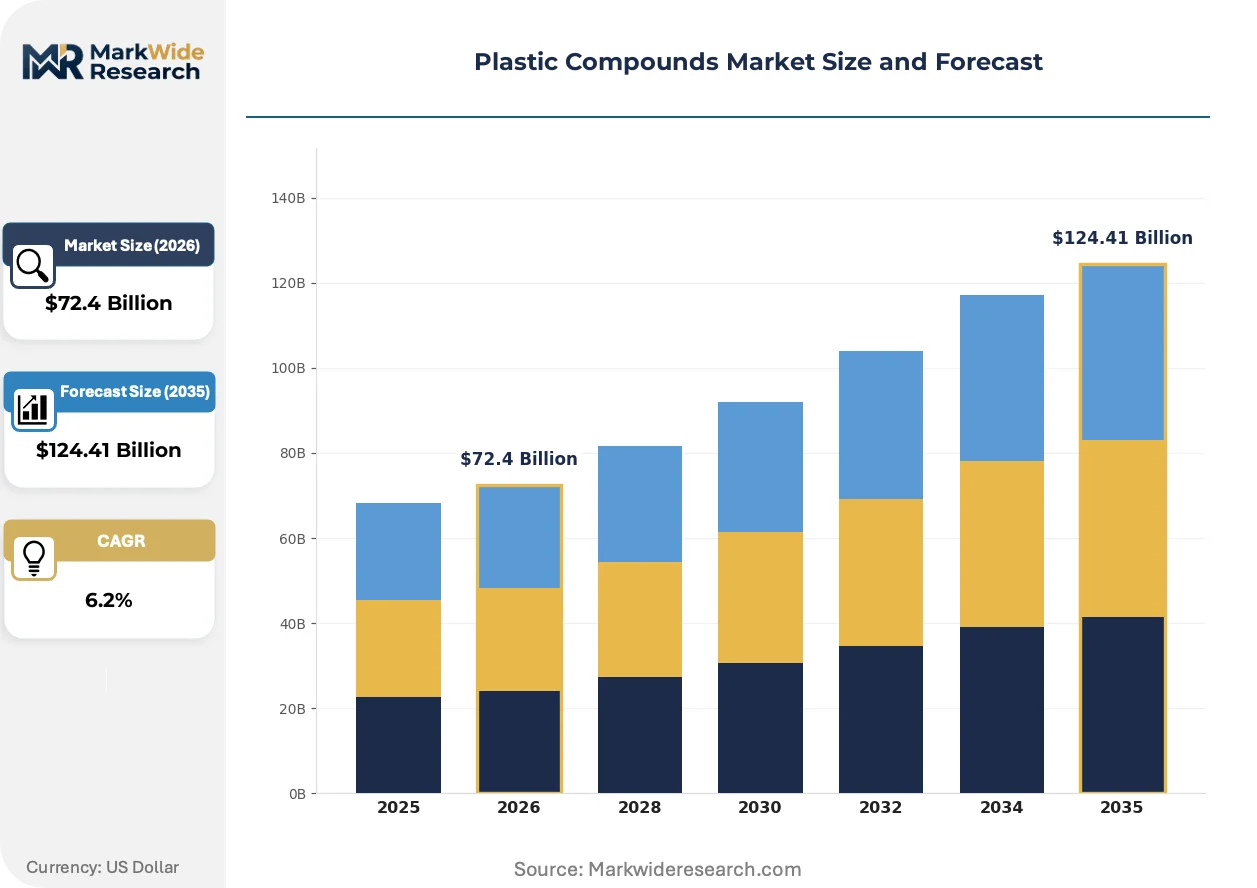
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $124.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Polypropylene, Polyethylene, Polystyrene Application: Automotive Parts, Consumer Goods, Packaging Materials, Construction Components Form: Granules, Powders, Sheets, Composites End User: Manufacturers, Retailers, Distributors, OEMs |
| Companies Covered | BASF SE, SABIC, LyondellBasell Industries Holdings B.V., DuPont de Nemours, Inc., Covestro AG, Asahi Kasei Corporation, Celanese Corporation, RTP Company, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Compounds Market Strategic Shifts & Innovations
Compounding technology convergence with real-time rheology monitoring is compressing formulation development cycles, while regulatory substance restrictions are fragmenting specification portability across jurisdictions.
Reactive extrusion compounding with in-situ compatibilization is unifying immiscible polymer blends into single-phase morphologies previously requiring separate alloying steps. Tier one automotive suppliers in Stuttgart and Shanghai are adopting these systems for recycled-content bumper formulations. The technology is unifying scrap reintegration with virgin-equivalent mechanical performance, collapsing the historical quality penalty that segregated recycled compounds into downgraded applications.
ECHA's SCIP database requirements under EU REACH Waste Framework Directive are mandating full article-level substance disclosure for automotive parts and consumer goods containing Candidate List substances above threshold. Compounders must now transmit Safe Use Information through supply chains to downstream assemblers. Automotive interior trim suppliers in Germany and France are responding by consolidating supplier bases to reduce disclosure complexity and audit burden.
Direct compounder-to-OEM procurement contracts are displacing distributor-mediated purchasing for high-volume engineered resin programs. Tier one automotive molders in Michigan and Bavaria are establishing annual volume commitments with specified property windows rather than spot-buying off-the-shelf grades. This pattern concentrates most visibly in powertrain-underhood applications where heat-aging specifications require co-development relationships rather than catalog selection.
Plastic Compounds Market Segmentation
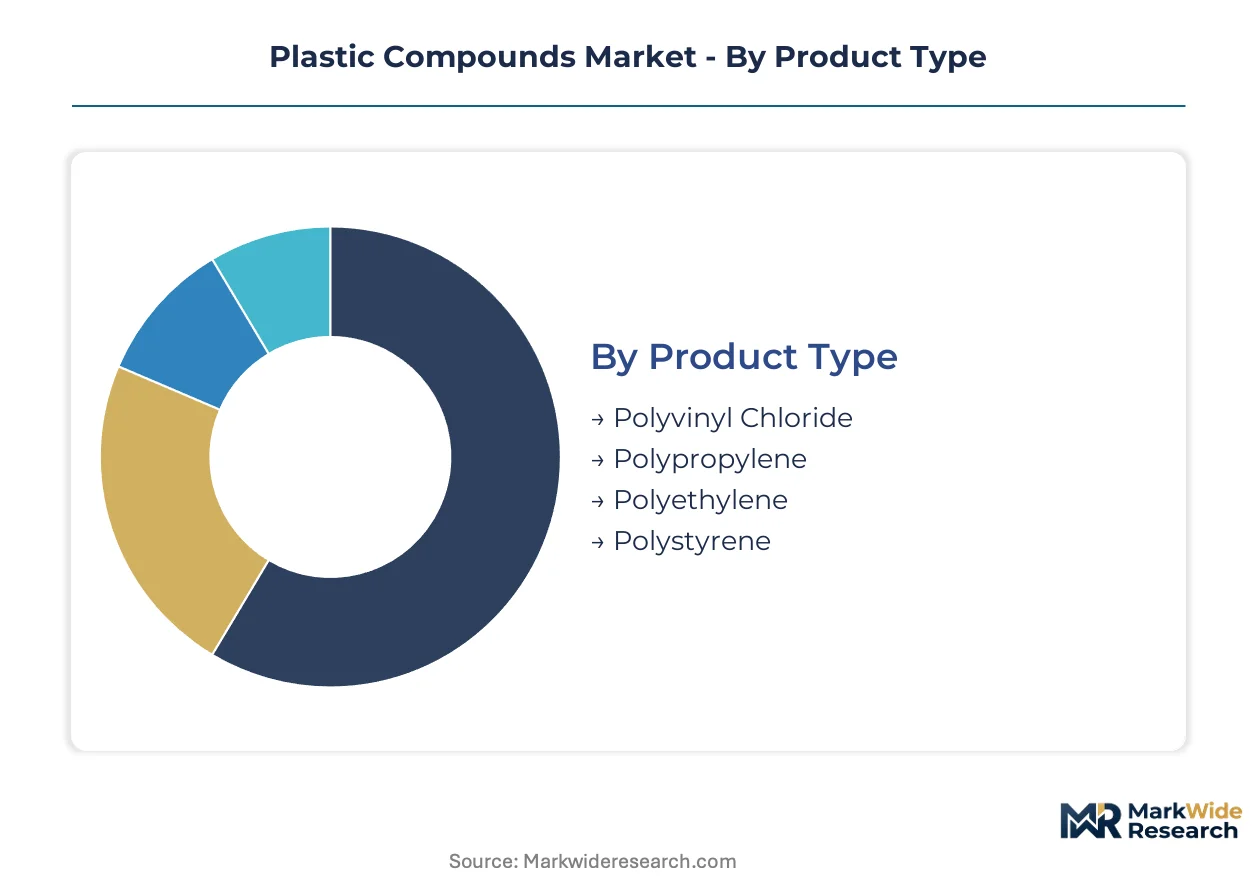
Plastic compounds demand fragments across formulation chemistries, processing formats, and downstream value chain positions. Each segmentation axis reveals distinct margin structures and qualification barriers that determine supplier competitiveness.
Product Type:
Material substitution cycles in automotive and packaging applications are reshaping volume flows across polymer families as compounders reformulate to meet recycled content mandates and thermal performance specifications.
- Polyvinyl Chloride:Chlorinated polymer systems stabilized with calcium-zinc or organotin heat stabilizers for rigid pipe and wire insulation applications. Construction sector demand in India concentrates around BIS-certified piping grades where lead-free formulations are displacing legacy stabilizer packages.
- Polypropylene:Talc and glass fiber reinforced grades dominate automotive bumper and interior panel specifications. German OEM lightweighting programs are accelerating consumption of 20-40% glass-filled compounds in underhood structural brackets.
- Polyethylene:Metallocene linear low-density and recycled-content blends serve flexible packaging film specifications. China's GB standards for food-contact recycled content are stimulating domestic compounding capacity expansion for certified grades.
- Polystyrene:High-impact and general-purpose grades for consumer electronics housings and disposable food service items. EFSA migration limits on residual styrene monomer constrain formulation flexibility for European food-contact applications.
Polypropylene sits at the top of the volume ranking, with polyethylene climbing the fastest as recycled-content certification protocols mature.
Application:
End-use specifications determine additive loading requirements, thermal aging protocols, and regulatory compliance burdens that fragment compounder addressable markets.
- Automotive Parts:Glass-filled nylon and engineered polypropylene compounds for powertrain underhood and structural interior applications. NHTSA fuel economy standards are compressing material substitution timelines against metal stampings.
- Consumer Goods:Color-matched ABS and polycarbonate blends for electronics housings and appliance components. ECHA SCIP database disclosure requirements are consolidating supplier bases among German and French OEMs.
- Packaging Materials:Metallocene polyethylene and clarified polypropylene for food-grade film and rigid containers. India's domestic conversion sector is outpacing local compounding capacity, creating import substitution openings.
- Construction Components:Rigid PVC and polyethylene compounds for pipe, siding, and geomembrane specifications. EPA stormwater management regulations are expanding demand for high-density polyethylene drainage systems in US infrastructure projects.
Automotive parts command the highest specification premiums, while packaging materials show the steepest expansion trajectory as sustainability procurement criteria harden.
Form:
Physical delivery formats align with downstream processing equipment constraints and melt uniformity requirements that differentiate compounder technical service capabilities.
- Granules:Pelletized feedstock for twin-screw extrusion and injection molding processes. Default format for high-volume automotive OEM programs where lot-to-lot consistency protocols require spectrophotometry calibration.
- Powders:Fine particle size distributions for rotational molding and dip-coating applications. Water tank and playground equipment producers favor powder compounds for uniform wall thickness formation.
- Sheets:Extruded flat stock for thermoforming and fabrication into signage and packaging trays. PET and polystyrene sheet specifications tighten as FDA food-contact migration limits evolve.
- Composites:Long fiber reinforced thermoplastic pellets and bulk molding compounds for structural applications. Battery electric vehicle battery module housings are penetrating this format as thermal conductivity grades qualify.
Granules maintain volume dominance across all end-use sectors, with composites gaining share fastest in electrification-driven automotive redesigns.
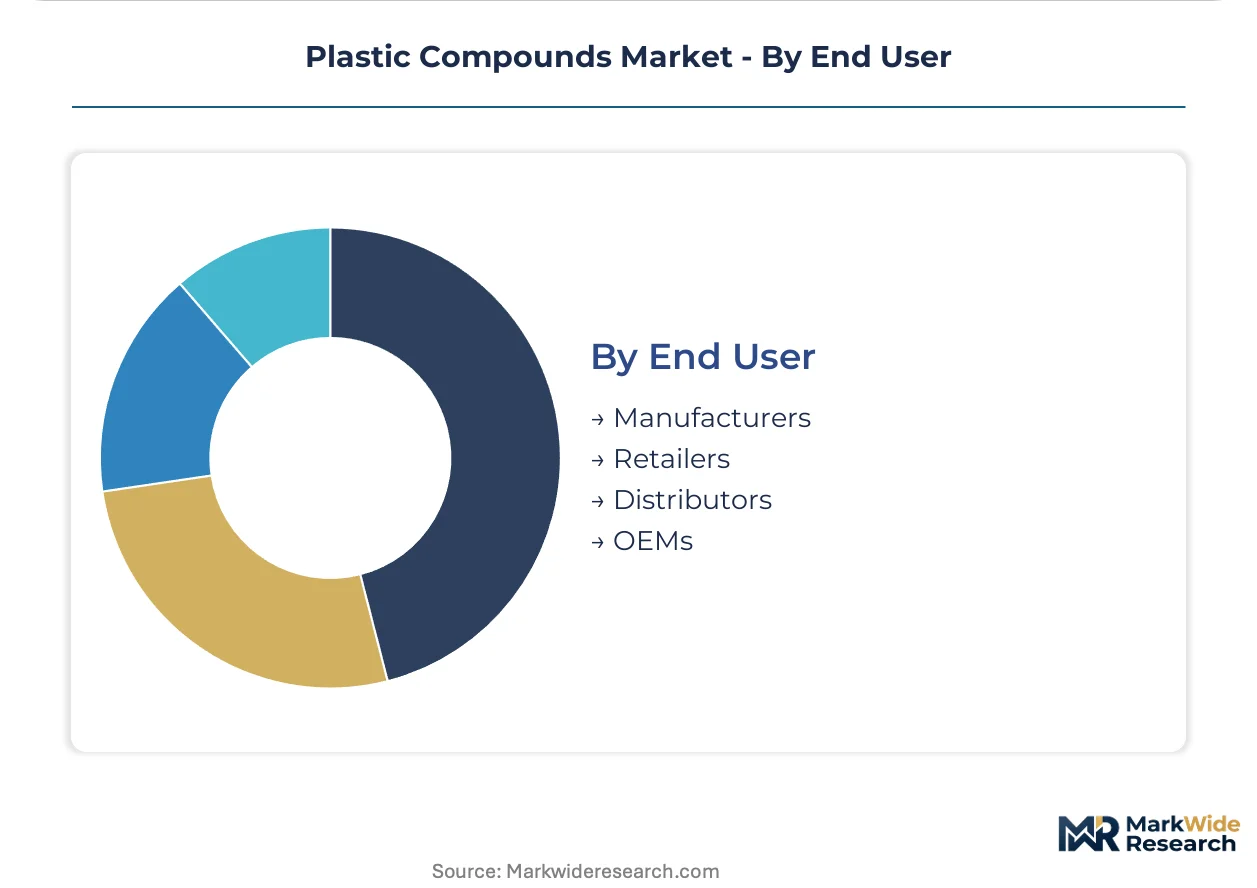
End User:
Procurement relationships vary from spot-market distributor purchases to multi-year direct compounder contracts with specified property windows and audit protocols.
- Manufacturers:Injection molders and extrusion converters purchasing feedstock for parts production. Tier one automotive suppliers in Michigan and Bavaria are displacing distributor-mediated purchasing with annual volume commitments.
- Retailers:Private label brand owners specifying recycled content and sustainability certifications for packaging. China's SAMR GB standards are conditioning procurement criteria for domestic food-grade film applications.
- Distributors:Regional warehousing and technical service intermediaries serving fragmented small-lot demand. Margin compression from direct compounder-to-OEM contracts is consolidating distributor relevance in specialty grades.
- OEMs:Original equipment manufacturers with co-development relationships for application-specific formulations. Powertrain underhood specifications require heat-aging validation protocols that catalog grades cannot satisfy.
Manufacturers represent the largest addressable base by volume, with OEMs expanding most quickly as direct procurement patterns displace distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and process engineers cluster around automotive manufacturing corridors and petrochemical hubs, anchoring regional compounding capacity to downstream assembly demand.
United States
NHTSA fuel economy standards are accelerating glass-filled nylon substitution for metal powertrain components. EPA TSCA notifications govern new chemical introductions for modified polymer structures. Michigan and Ohio house the densest concentrations of automotive compounding technical centers serving Detroit Three OEMs.
Germany
Lightweighting mandates for electric vehicle architectures are compressing material qualification timelines. ECHA REACH phthalate restrictions are redirecting formulation investment toward bio-based plasticizer alternatives. Stuttgart and Munich anchor the highest-value automotive compounding relationships with integrated additive capabilities.
China
Domestic packaging conversion demand is outpacing local food-grade compounding capacity. SAMR GB standards for recycled content and food-contact migration limits are conditioning procurement criteria. Yangtze River Delta cities host the fastest-expanding certified film and rigid container compound operations.
India
Construction sector PVC piping demand is driving BIS-certified lead-free formulation adoption. FSSAI food-contact regulations are tightening additive migration specifications for packaging applications. Maharashtra and Gujarat are absorbing the majority of greenfield film and container compounding investments.
Saudi Arabia
Captive petrochemical feedstock access is sustaining cost positions in bulk polyolefin compounds. SFDA and regional harmonization initiatives are standardizing food-contact certification requirements. Eastern Province industrial cities concentrate integrated polymer production and downstream compounding operations.
Plastic Compounds Market Key Industry Players
The competitive structure tilts toward integrated petrochemical conglomerates with captive feedstock positions. Three to five European and Asian chemical majors command disproportionate share in engineered grades, while regional blenders fragment the commodity polyolefin segment. Strategic archetypes separate into backward-integrated resin producers, specialty additive compounders, and distributed toll-blending networks. Capacity expansion in China and India and direct compounder-to-OEM procurement contracts represent the dominant competitive moves reshaping channel relationships.
Within the integrated chemical major tier, BASF SE and SABIC exemplify archetypes built on captive raw material access and multi-continent manufacturing footprints. DuPont de Nemours, Inc. occupies a position in high-performance engineered compounds where thermal aging specifications require co-development relationships rather than catalog selection. These three anchors demonstrate how competitive positioning fragments across feedstock integration depth, application specialization intensity, and geographic coverage breadth.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| DuPont de Nemours, Inc. |
| Covestro AG |
| Asahi Kasei Corporation |
| Celanese Corporation |
| RTP Company |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
Polypropylene homopolymer spot prices on the US Gulf Coast cascade through compounding value chains into three distinct pricing tiers that separate captive-feedstock producers from toll blenders and regional distributors. Naphtha-linked resin contracts in Asia and Europe transmit volatility downstream where compounders with backward-integrated additive capabilities capture margin premiums unavailable to formulation-only competitors.
Pricing Analysis
Compounding services split between bundled formulation-plus-technical-support contracts and unbundled resin-only spot transactions. Three-tier pricing structure across premium, standard, and economy levels separates automotive co-development programs from catalog grades and commodity polyolefin blends. Pricing pressure stems from recycled-content certification costs that compounders must absorb to meet brand owner sustainability procurement criteria. Small-lot packaging converters exhibit highest price sensitivity while automotive OEMs prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for critical grades, fragmenting volume across qualified compounders rather than concentrating with single sources. Feedstock dependence draws from Saudi Arabia, the United States, and South Korea for virgin polyolefins while China and India expand domestic compounding capacity. Single-source vulnerability concentrates in adipic acid and hexamethylenediamine for polyamide 66 compounds. Distribution runs through direct compounder-to-OEM contracts displacing distributor channels in high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock cost arbitrage between Middle Eastern petrochemical hubs and European regulatory compliance burdens creates geographic positioning advantages for compounders with multi-continent manufacturing footprints. ECHA REACH disclosure requirements impose documentation costs that favor integrated producers over regional blenders.
For Market Incumbents: Anchor margin structures through captive specialty plasticizer production that smaller blenders cannot replicate under phthalate restriction timelines. Consolidate supplier relationships with automotive OEMs seeking to reduce SCIP database audit complexity. Expand compounding technical centers in Michigan and Bavaria to defend against direct procurement displacement of distributor channels.
For New Entrants and Emerging Players: Reactive extrusion technology with in-situ compatibilization offers entry into recycled-content automotive formulations where established compounders lag qualification timelines. Target India's packaging conversion sector where domestic food-grade capacity trails demand growth. Pursue toll-blending partnerships with regional distributors to bypass capital-intensive extrusion infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale compounders possessing BIS-certified lead-free PVC formulations and established relationships with Indian construction sector distributors. Five-to-ten-year viability hinges on chemical recycling feedstock integration capabilities that satisfy brand owner circular content claims. Monitor pyrolysis-derived naphtha qualification progress as inflection indicator for circular economy positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Plasticizers | BASF's captive additive production sustains margins unreachable by formulation-only competitors under REACH phthalate limits. |
| Greenfield Compounding Capacity in India | Maharashtra and Gujarat investments capture packaging conversion demand outpacing domestic food-grade supply. |
| Long-term Direct Supply Agreement with Automotive OEMs | Annual volume commitments with specified property windows displace spot purchasing in powertrain underhood segments. |
| Joint Venture for Chemical Recycling Feedstock | Pyrolysis-derived naphtha partnerships enable circular content claims satisfying sustainability procurement criteria. |
| Certification Investment for GB Standards Compliance | SAMR food-contact mandates create non-tariff barriers favoring pre-qualified domestic compounders. |
Research Approach
Direct dialogue with polymer chemists, automotive Tier 1 procurement managers, packaging converter operations heads, and regulatory compliance officers grounded qualitative findings in operational realities. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical majors, and ECHA substance registration databases. Bottom-up volume estimates from compounding capacity utilization and top-down demand segmentation from end-use consumption patterns were triangulated to reconcile figures.
Segmented outputs across polymer chemistry, reinforcement loading tier, delivery format, and regional production hub fed into analytical framework calculations throughout the projection horizon. CAGRs derived from regression analysis against automotive production forecasts, packaging demand indices, and construction sector investment cycles. Industry-specific inputs incorporated glass fiber loading optimization curves and recycled-content certification adoption rates by geography.
The model holds under stable petrochemical feedstock pricing and incremental regulatory tightening; deviation in caprolactam supply disruption or accelerated PFAS restriction timelines would shift compounder margin structures and regional competitiveness materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
BPA Free Plastic Market