
 Asia-Pacific Plastic Waste Management Market | 2026-2036
Asia-Pacific Plastic Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plastic Waste Management Market Insights
Fast-moving consumer goods manufacturers are rotating procurement priorities toward post-consumer resin offtake agreements. Hitachi Zosen Corporation leverages its incineration-to-energy engineering base across Japanese prefectures. Banyan Nation anchors India's domestic mechanical recycling capacity with proprietary contamination-removal systems. SUEZ competes through integrated collection-sorting-reprocessing contracts with Australian state governments.
Asia-Pacific plastic waste management encompasses the systematic collection, sorting, processing, and disposal of polymer discards across municipal, industrial, and agricultural streams, typically operating at throughput rates of 50–500 tonnes per day for regional material recovery facilities. The discipline serves to recover embedded calorific and material value while mitigating marine leakage and soil contamination. Packaging waste dominates feedstock volumes entering mechanical recycling lines, though chemical recycling is capturing margin pools from mixed-flexible streams that mechanical processes cannot valorize. Collection method infrastructure varies sharply by national income tier, with deposit return systems generating the cleanest input fractions and curbside collection scaling fastest in Southeast Asian megacities.
Japan's Ministry of Environment enforces container and packaging recycling laws that mandate extended producer responsibility for brand owners. India's Central Pollution Control Board implements plastic waste management rules banning select single-use items and mandating minimum recycled content thresholds. Australia's Environment Protection Authority coordinates interstate waste transport protocols that shape regional processing capacity allocation. Stakeholders must monitor regulatory divergence between national extended producer responsibility schemes and sub-national enforcement capacity gaps that determine actual compliance costs.
Market Dynamics
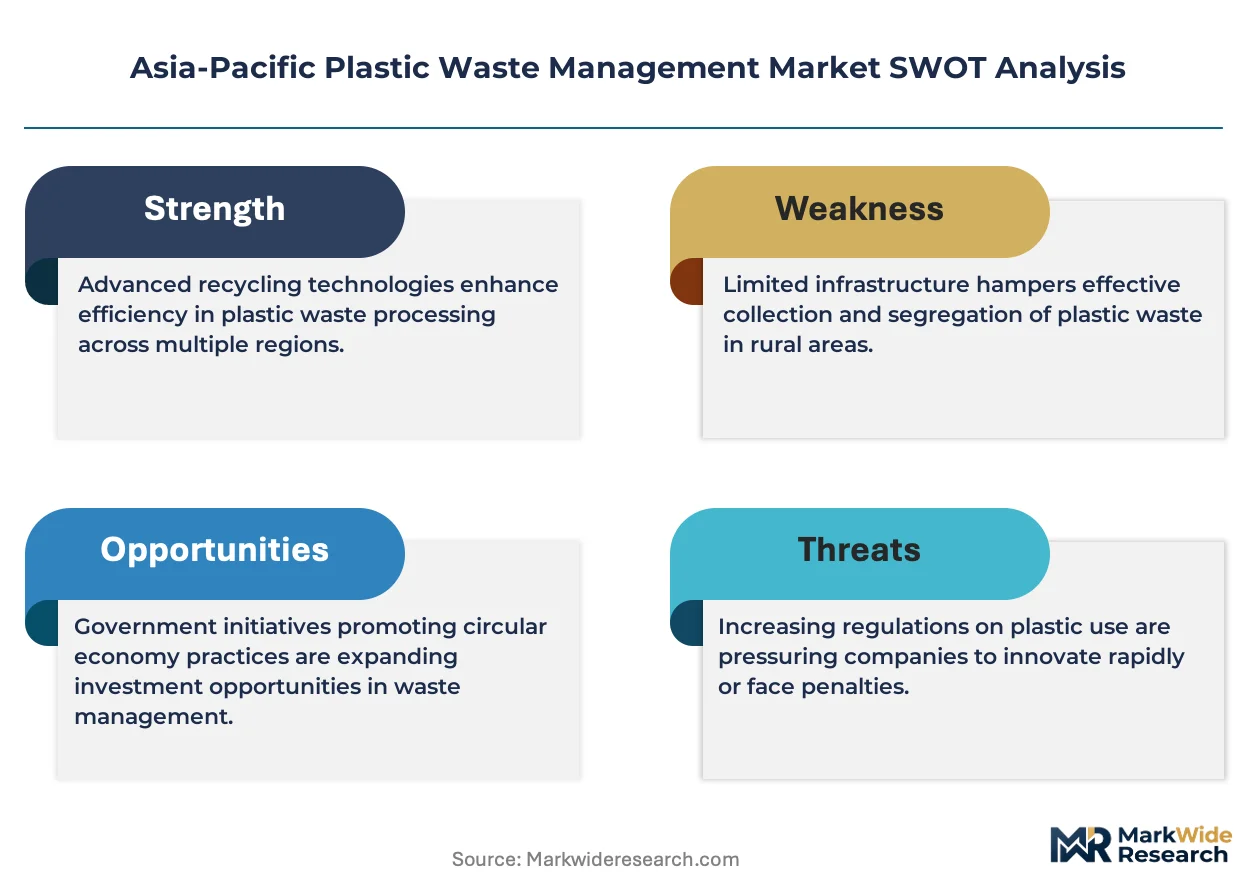
Japan's container deposit legislation and India's extended producer responsibility mandates are compressing informal collection networks while accelerating formal infrastructure buildout across Southeast Asian megacities.
Growth Catalysts
- Deposit-Return Systems:Japan's Ministry of Environment enforces container and packaging recycling laws that generate clean polyethylene terephthalate input streams for mechanical reprocessors.
- Urban Generation Surge:Indian municipalities face plastic waste volumes that outpace existing landfill capacity, forcing investment in material recovery facilities and pyrolysis pilots.
- Chemical Recycling Scale-Up:Pyrolysis and gasification technologies are unlocking valorization pathways for mixed-flexible polymer streams that mechanical sorting cannot economically process.
Market Restraints
- Feedstock Price Volatility:Virgin polymer prices tied to naphtha and natural gas liquids create margin compression for post-consumer resin producers when oil markets soften.
- Collection Infrastructure Gaps:Informal sector dominance across Indonesian and Philippine urban corridors limits standardized feedstock quality for automated sorting lines.
- Regulatory Enforcement Variance:Sub-national implementation lags behind national plastic waste management rules in India, creating compliance cost uncertainty for integrated operators.
Strategic Opportunities
- Vietnamese Coastal Provinces:Marine plastic leakage reduction targets are unlocking blended finance for collection fleet electrification and port-based compaction hubs.
- Australian Interstate Arbitrage:Environment Protection Authority transport protocols create processing capacity allocation inefficiencies that contract-integrated operators can exploit.
- Post-Consumer Resin Mandates:India's Central Pollution Control Board minimum recycled content thresholds for rigid packaging are generating offtake agreement demand from fast-moving consumer goods manufacturers.
Industry Challenges
- Contamination Removal Expertise:Mechanical recycling lines require operators capable of managing multi-layer film separation and odor elimination at throughput rates above 200 tonnes per day.
- Chemical Recycling Capex Burden:Pyrolysis reactor construction and hydrogen supply integration demand capital commitments that strain mid-scale regional processors.
- Certification Timeline Friction:Food-grade post-consumer resin approval processes through national food safety regulators extend commercialization cycles for packaging applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plastic Waste Management Market |
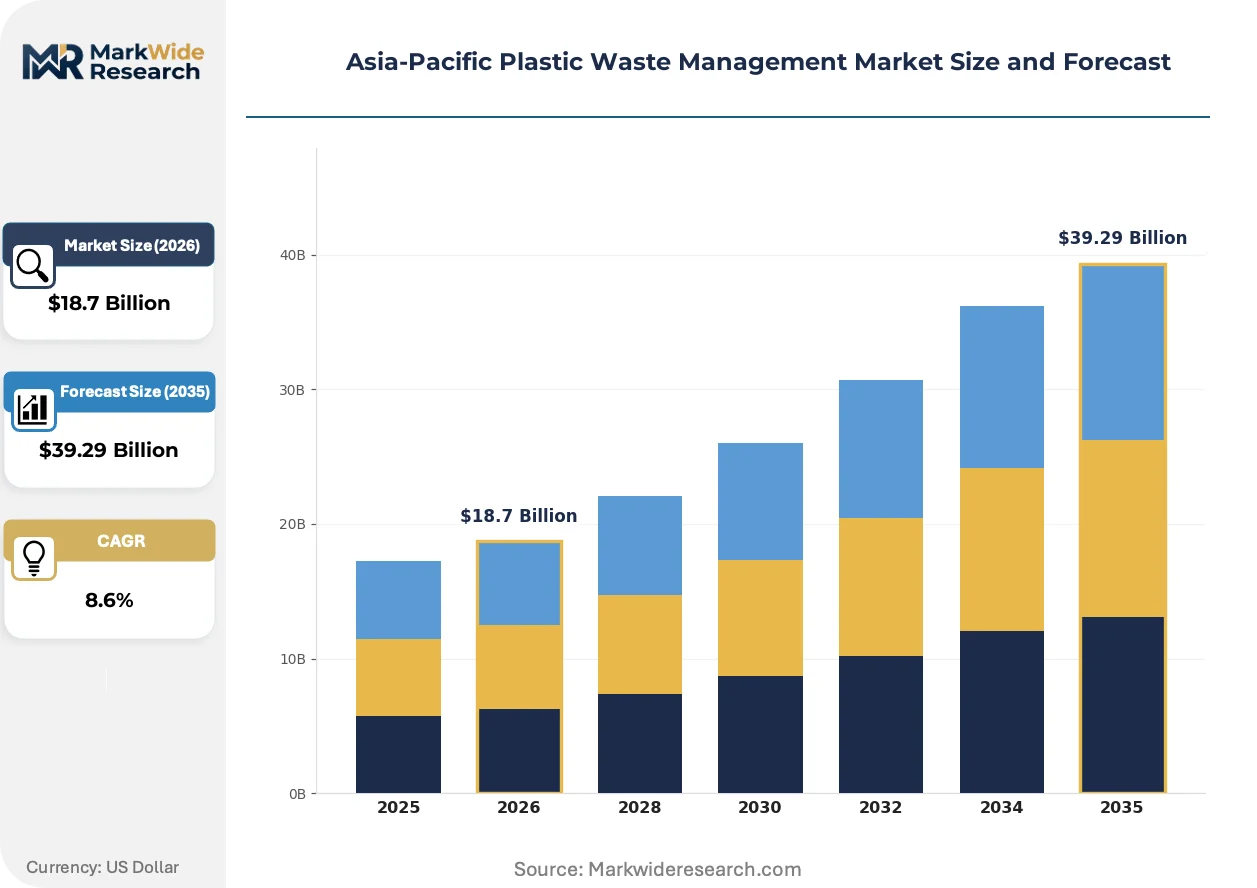
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Single-Use Plastics, Packaging Waste, Industrial Plastics, Agricultural Plastics Recycling Method: Mechanical Recycling, Chemical Recycling, Energy Recovery, Landfilling End User: Manufacturers, Retailers, Government Bodies, Environmental Agencies Collection Method: Curbside Collection, Drop-off Centers, Deposit Return Systems, Industrial Collection |
| Companies Covered | Hitachi Zosen Corporation, Polimaster, Banyan Nation, Lucro, Recity, SUEZ, Waste Management Inc., Cleanaway, Veolia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plastic Waste Management Market Trends and Innovations
Chemical recycling infrastructure is bifurcating competitive positioning between mechanical reprocessors serving clean mono-streams and pyrolysis operators capturing mixed-flexible premiums.
Pyrolysis technology is bifurcating the Asia-Pacific plastic waste landscape. Japanese prefectural governments and industrial consortia are deploying thermal cracking units to process contaminated agricultural film and multi-layer pouches. The technology enables polymer-to-polymer molecular recycling that mechanical washing and extrusion cannot achieve. This bifurcation is compressing margins for pure mechanical players while creating captive feedstock advantages for integrated petrochemical-waste operators.
India's plastic waste management rules are mandating extended producer responsibility compliance through centralized national portals. Brand owners must register packaging volumes and fund collection infrastructure proportional to market presence. The regulation most affects multinational fast-moving consumer goods companies with distributed supply chains, which are responding by anchoring long-term offtake agreements with domestic mechanical recyclers.
Post-consumer resin procurement is consolidating around multi-year offtake contracts with embedded price collars. Australian state governments and Japanese beverage manufacturers are displacing spot-market purchasing with structured agreements that transfer feedstock risk to processors. This shift is most visible in rigid polyethylene terephthalate bottle applications, where brand owners seek supply security ahead of recycled content mandate deadlines.
Asia-Pacific Plastic Waste Management Market Segmentation
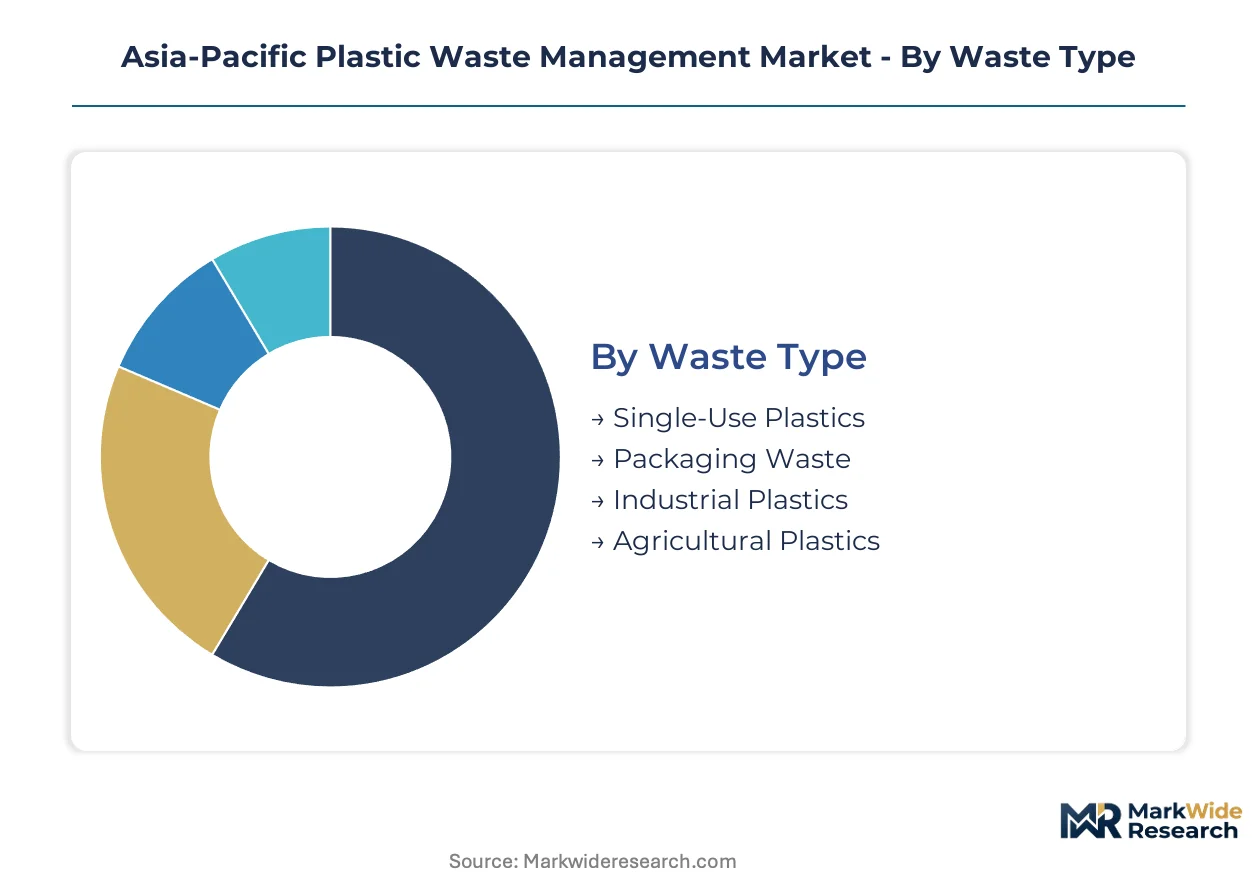
Segmentation in Asia-Pacific plastic waste management reveals how margin pools concentrate around feedstock quality tiers and processing technology sophistication. Understanding these divisions exposes where capital deployment meets regulatory enforcement gaps.
Waste Type:
Margin pools concentrate in high-volume, low-contamination streams that mechanical recyclers can process without expensive preprocessing.
- Packaging Waste:Polyethylene terephthalate bottles and rigid polyethylene containers dominate feedstock volumes entering Asian material recovery facilities. Japanese beverage manufacturers and Indian fast-moving consumer goods companies are locking in multi-year offtake agreements for food-grade post-consumer resin ahead of minimum recycled content mandates.
- Single-Use Plastics:Banned items across Indian states and Philippine cities are redirecting volumes toward pyrolysis pilots or controlled energy recovery. Thailand's Ministry of Natural Resources and Environment enforcement of single-use restrictions is compressing informal collection networks while creating formal infrastructure opportunities.
- Industrial Plastics:Manufacturing scrap and post-industrial film from Vietnamese electronics and automotive suppliers generate clean mono-streams with minimal contamination removal costs.
- Agricultural Plastics:Contaminated mulch film and greenhouse sheeting from Chinese and Japanese farming regions require chemical recycling or specialized washing lines that few regional processors operate profitably.
Packaging waste holds installed capacity. Single-use plastics is rotating up the share rankings.
Recycling Method:
Technology choice determines feedstock flexibility and output pricing power across the region's processing landscape.
- Mechanical Recycling:Washing, sorting, and extrusion lines achieve throughput rates of 200–500 tonnes per day for clean polyethylene terephthalate and high-density polyethylene streams. Indian mechanical recyclers including Banyan Nation are deploying proprietary contamination-removal systems to meet brand owner specifications.
- Chemical Recycling:Pyrolysis and gasification units process mixed-flexible polymers that mechanical sorting cannot economically valorize. Japanese prefectural governments are subsidizing thermal cracking capacity for agricultural film and multi-layer pouches that lack mechanical pathways.
- Energy Recovery:Incineration-to-energy facilities in Tokyo and Osaka prefectures extract calorific value from residual waste streams with high moisture or contamination levels that preclude material recovery.
- Landfilling:Remaining disposal route for contaminated or mixed waste in Indonesian and Philippine provinces where collection infrastructure outruns processing capacity.
Mechanical recycling retains volume leadership. Chemical recycling is climbing the fastest.
End User:
Procurement authority and compliance liability distribute unevenly across public and private demand pools.
- Manufacturers:Brand owners face extended producer responsibility mandates through India's centralized national portal and Japan's container and packaging recycling laws. Procurement teams are rotating toward post-consumer resin offtake agreements with embedded price collars.
- Government Bodies:Municipal corporations across Southeast Asian megacities are expanding curbside collection fleet electrification and port-based compaction hubs with blended finance support.
- Retailers:Supermarket chains in Australia and South Korea are implementing reverse logistics networks for private-label packaging takeback.
- Environmental Agencies:Australia's Environment Protection Authority coordinates interstate waste transport protocols that shape regional processing capacity allocation and contract terms.
Manufacturers command procurement volume. Government bodies are gaining share fastest.
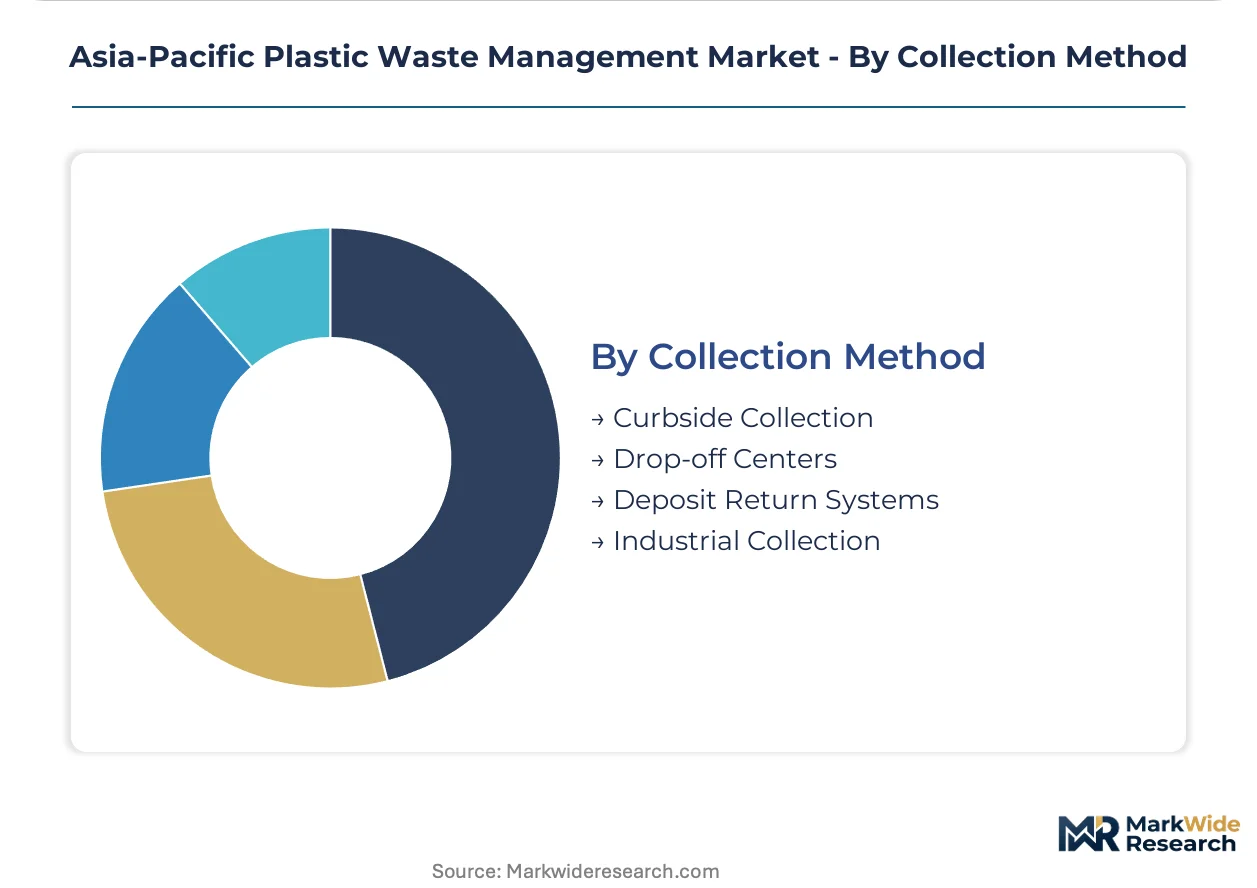
Collection Method:
Input stream quality and standardization vary sharply by collection infrastructure maturity.
- Deposit Return Systems:Japan's Ministry of Environment enforcement generates cleanest polyethylene terephthalate input fractions with standardized container formats and consumer participation rates above 80 percent.
- Curbside Collection:Scaling fastest across Jakarta, Manila, and Ho Chi Minh City megacities where municipal governments are replacing informal sector dominance with scheduled fleet operations.
- Drop-off Centers:Supplementary collection points in Australian suburbs and Japanese rural prefectures serve low-density populations outside curbside routes.
- Industrial Collection:Direct pickup from manufacturing facilities generates post-industrial scrap with known polymer composition and minimal sorting requirements.
Deposit return systems hold quality premiums. Curbside collection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese processors export post-industrial scrap to Chinese chemical recycling facilities along the South China Sea corridor, while Australian operators arbitrage interstate waste transport protocols to capture processing premiums.
Japan
Container deposit legislation generates clean polyethylene terephthalate streams with consumer participation exceeding 80 percent. METI subsidizes pyrolysis pilots for contaminated agricultural film. Tokyo and Osaka prefectures operate incineration-to-energy networks extracting calorific value from residual waste.
India
Urban plastic generation outpaces landfill capacity across Delhi-NCR and Mumbai metropolitan regions. The Central Pollution Control Board mandates minimum recycled content thresholds for rigid packaging. Banyan Nation anchors mechanical recycling capacity in Telangana with proprietary contamination-removal systems.
Australia
State governments displace spot-market purchasing with multi-year post-consumer resin offtake agreements. The Environment Protection Authority coordinates interstate waste transport protocols creating capacity allocation inefficiencies. New South Wales and Victoria concentrate material recovery facility investments near port infrastructure.
Vietnam
Marine plastic leakage reduction targets unlock blended finance for collection fleet electrification. Coastal provinces deploy port-based compaction hubs serving Mekong Delta agricultural zones. Ho Chi Minh City municipal corporations replace informal sector dominance with scheduled curbside operations.
Indonesia
Jakarta megacity curbside collection scales fastest where municipal fleet expansion outruns informal network compression. National plastic waste management rules face sub-national enforcement gaps in outer island provinces. Java-based processors struggle with feedstock quality standardization from heterogeneous collection sources.
Asia-Pacific Plastic Waste Management Market Competitive Landscape
Player mix skews toward integrated engineering conglomerates with incineration-to-energy foundations alongside specialized mechanical recyclers deploying proprietary contamination-removal technology. Market structure concentrates around three strategic archetypes: petrochemical-waste operators capturing mixed-flexible premiums through pyrolysis, municipal contractors securing integrated collection-sorting-reprocessing agreements, and domestic mechanical specialists serving brand owner offtake mandates. Dominant competitive moves include capacity expansion in chemical recycling corridors and strategic partnerships anchoring long-term resin supply security.
Within the integrated engineering tier, Hitachi Zosen Corporation and SUEZ occupy positions leveraging incineration infrastructure across Japanese prefectures and Australian state contracts respectively. Banyan Nation exemplifies the domestic mechanical specialist archetype in India. These three entities represent the competitive spectrum from thermal treatment engineering to proprietary sorting technology deployment.
| Leading Market Players |
|---|
| Hitachi Zosen Corporation |
| Polimaster |
| Banyan Nation |
| Lucro |
| Recity |
| SUEZ |
| Waste Management Inc. |
| Cleanaway |
| Veolia |
| Others |
Pricing and Supply Chain Analysis
Multi-year offtake agreements with embedded price collars anchor feedstock access and cost visibility for Japanese beverage manufacturers and Indian fast-moving consumer goods companies navigating virgin polymer volatility.
Pricing Analysis
Mechanical recycling lines command premium pricing over pyrolysis output for food-grade polyethylene terephthalate streams, while chemical recycling operators capture margin pools from mixed-flexible polymers that lack mechanical pathways. Price differentiation rests on contamination removal certification and volume scale commitments. Cost compression in mechanical recycling is intensifying because virgin naphtha-linked resins soften when oil markets decline. Municipal contractors exhibit highest price sensitivity due to budget constraints, whereas integrated petrochemical-waste operators demonstrate lowest sensitivity through captive feedstock advantages.
Supply Chain Analysis
Port congestion across the Strait of Malacca constrains feedstock flows from Indonesian collection networks to Vietnamese processing hubs. Supply concentrates in Japan, India, and Vietnam for mechanical recycling capacity, while China and South Korea anchor chemical recycling reactor manufacturing. Raw material dependencies include post-consumer bale supply, hydrogen feedstock for pyrolysis, and specialized sorting equipment. Single-source vulnerability runs through Japanese incineration-to-energy engineering providers. Distribution runs through municipal collection contracts and brand owner direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility portals are transforming this market into a platform-economics inflection, where interoperability between national compliance systems and processor registration databases determines competitive access.
For Market Incumbents: Fortify mechanical recycling margins through backward integration into collection fleet operations across Southeast Asian megacities. Invest in proprietary contamination-removal certification to defend against chemical recycling substitution for mixed-flexible streams. Prioritize long-term offtake anchoring ahead of India's minimum recycled content mandate enforcement.
For New Entrants and Emerging Players: Informal sector formalization services in Indonesian and Philippine urban corridors represent the most penetrable white-space target. Municipal governments lack standardized feedstock quality systems for automated sorting lines. Pursue blended finance structures for port-based compaction hubs serving marine plastic leakage reduction targets.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic mechanical specialists with proprietary sorting technology and established brand owner relationships. Long-term viability hinges on chemical recycling capex efficiency and food-grade certification timelines. Watch for pyrolysis operator consolidation signals as Japanese prefectural subsidies mature.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Fleet Operations | Municipal contractors in Jakarta and Ho Chi Minh City secure standardized feedstock quality for automated sorting lines. |
| Proprietary Contamination-Removal Certification Investment | Indian mechanical recyclers meet Central Pollution Control Board specifications for fast-moving consumer goods offtake agreements. |
| Chemical Recycling Capacity Expansion | Japanese prefectural governments subsidize pyrolysis pilots for agricultural film lacking mechanical valorization pathways. |
| Long-Term Post-Consumer Resin Offtake Agreements | Australian state governments displace spot-market purchasing with structured contracts transferring feedstock risk to processors. |
| Blended Finance Structuring for Marine Plastic Infrastructure | Vietnamese coastal provinces unlock electrified collection fleets and port-based compaction hubs through development capital. |
Research Methodology
Initial hypotheses were tested against primary input from municipal waste management officers, mechanical recycling plant managers, chemical recycling technology providers, and fast-moving consumer goods procurement leads, then refined against customs trade data, Central Pollution Control Board filings, Japanese Ministry of Environment enforcement reports, and SEC disclosures from integrated operators. Bottom-up facility capacity estimates and top-down national waste generation statistics were triangulated to reconcile volume figures.
Variance decomposition across waste type, recycling method, end user, and collection method segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific inputs included informal sector participation rates, extended producer responsibility compliance timelines, and chemical recycling technology cost curves.
Forecasts assume regulatory continuity in India's plastic waste management rules and Japan's container deposit legislation; material policy shifts would require re-modeling feedstock availability and compliance cost structures. Practitioners should keep alternative scenarios live as sub-national enforcement capacity and virgin polymer price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
US Plastics Market