
 Circular Plastic Feedstock Traceability Market | 2026-2036
Circular Plastic Feedstock Traceability Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Plastic Feedstock Traceability Market Insights
The EU Green Deal's mandatory recycled content targets is consolidating demand for verified feedstock tracking across European polymer supply chains. Circularise leverages blockchain architecture to map material flows from post-consumer waste through chemical recycling stages. Circulor sustains competitive positioning through rare-earth and plastic traceability overlap, serving overlapping industrial client bases. SAP dominates enterprise-grade ERP integration, embedding traceability modules within existing procurement workflows.
Circular plastic feedstock traceability encompasses digital systems that record chain-of-custody data across collection, sorting, recycling, and reprocessing stages, typically capturing mass-balance ratios, contamination levels, and polymer degradation indices to certify recycled origin claims. Polyethylene Terephthalate traceability commands the largest technology spend due to beverage sector compliance deadlines, while Blockchain deployments expand fastest as consortium networks achieve interoperability across competing platforms. Packaging Materials applications anchor current revenue, though Automotive Components represents the emerging margin pool as OEMs mandate recycled content verification for interior and under-hood parts.
EMA chemical recycling guidelines, EU Green Deal delegated acts, and REACH Article 33 obligations collectively mandate auditable provenance documentation for recycled plastics entering consumer goods. Germany's national packaging regulator enforces stricter verification thresholds than baseline EU requirements, accelerating RFID and optical sensor deployment across sorting infrastructure. Stakeholders must monitor emerging mass-balance certification rules from ECHA and prepare for interoperability demands between national blockchain registries and SAP-dominated enterprise systems.
Market Dynamics
Blockchain and RFID integration is automating chain-of-custody verification across European recycling infrastructure, compressing audit timelines from weeks to hours while ECHA mass-balance rules harden compliance thresholds.
Growth Catalysts
- EU Green Deal delegated acts:Mandatory recycled content targets for packaging materials are forcing polymer producers to deploy traceability systems or face market exclusion.
- Chemical recycling expansion:Mass-balance certification requirements at BASF and Neste complexes in Germany's Rhine corridor are pulling RFID and optical sensor demand.
- Beverage sector compliance deadlines:Polyethylene Terephthalate traceability mandates are concentrating technology spend in bottle-to-bottle recycling chains.
Market Restraints
- RFID tag cost volatility:Silicon chip supply constraints and rare-earth price swings are inflating hardware deployment budgets for sorting facilities.
- Legacy ERP integration friction:SAP-dominated procurement workflows resist modular traceability insertion without expensive middleware development.
- Interoperability gaps:Competing blockchain consortiums lack standardized data protocols, fragmenting verification networks across national registries.
Strategic Opportunities
- Automotive Components:OEM recycled content mandates for interior and under-hood parts are opening margin pools beyond packaging applications.
- AI-optical sorting convergence:Machine vision paired with polymer spectroscopy is enabling real-time contamination detection at lower capex than pure RFID.
- REACH Article 33 obligations:Substance-of-very-high-concern disclosure rules are expanding traceability scope to hazardous additive tracking.
Industry Challenges
- Blockchain developer scarcity:Supply chain cryptography expertise sits concentrated in fintech, creating talent poaching wars with logistics software vendors.
- Mass-balance audit complexity:ECHA certification timelines stretch 18-24 months, delaying revenue recognition for chemical recycling operators.
- Retrofit capex intensity:Optical sensor installation at legacy mechanical sorting plants requires line shutdowns that compress throughput during peak collection seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Plastic Feedstock Traceability Market |
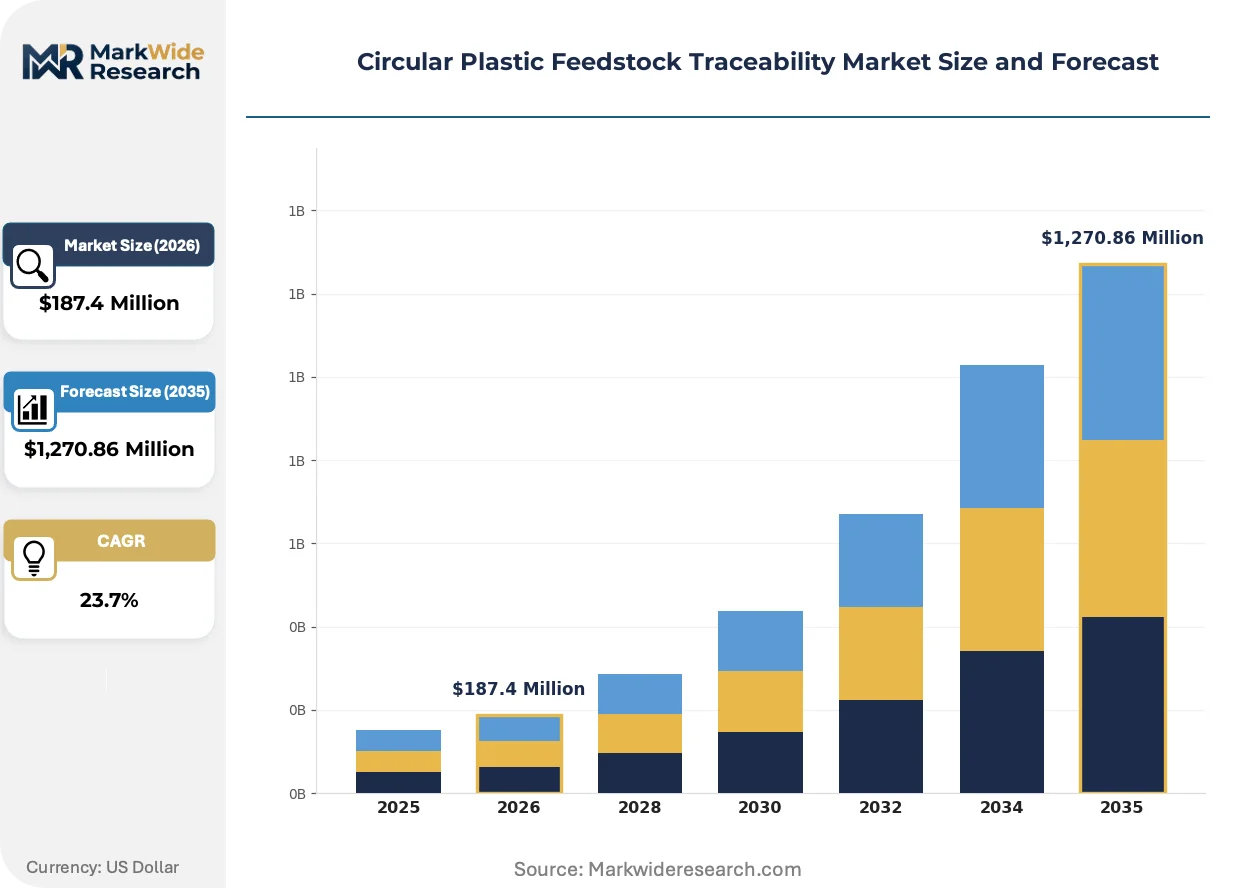
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride, Bioplastics Technology: Radio Frequency Identification, Blockchain, Near Field Communication, Optical Sensors, Barcode Systems, Cloud Computing Application: Packaging Materials, Automotive Components, Consumer Electronics, Construction Materials, Textiles, Household Goods End User Industry: Manufacturers, Waste Management Companies, Recycling Facilities, Plastic Converters, Regulatory Authorities, Environmental Organizations |
| Companies Covered | Circularise, Circulor, SAP, Recyda, ISCC System, BASF, Neste, Sphera, OPTEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Plastic Feedstock Traceability Market Trends and Innovations
Digital verification architectures are compressing certification cycles while regulatory granularity hardens, forcing technology vendors to choose between interoperability investment or proprietary lock-in.
AI-powered optical sorting is automating polymer identification at conveyor speeds exceeding manual sampling capacity. German sorting hubs along the Rhine corridor are deploying these systems to meet KBA automotive supplier audit requirements. The technology is automating contamination detection that previously required laboratory gas chromatography, collapsing verification from days to minutes.
REACH Article 33 disclosure obligations are mandating substance-level tracking through reprocessing stages. ECHA guidance on recycled content calculation methods is forcing traceability providers to capture additive degradation data, not just polymer type. Packaging materials producers face the steepest compliance ramps, with beverage sector deadlines 18 months ahead of industrial applications.
Certification-driven procurement is consolidating buyer power among mass-balance-accredited suppliers. Automotive OEMs in Germany are disqualifying unverified feedstock sources from interior component contracts. Tier-1 suppliers respond by mandating blockchain documentation from their reprocessing partners, compressing the viable vendor base.
Circular Plastic Feedstock Traceability Market Segmentation
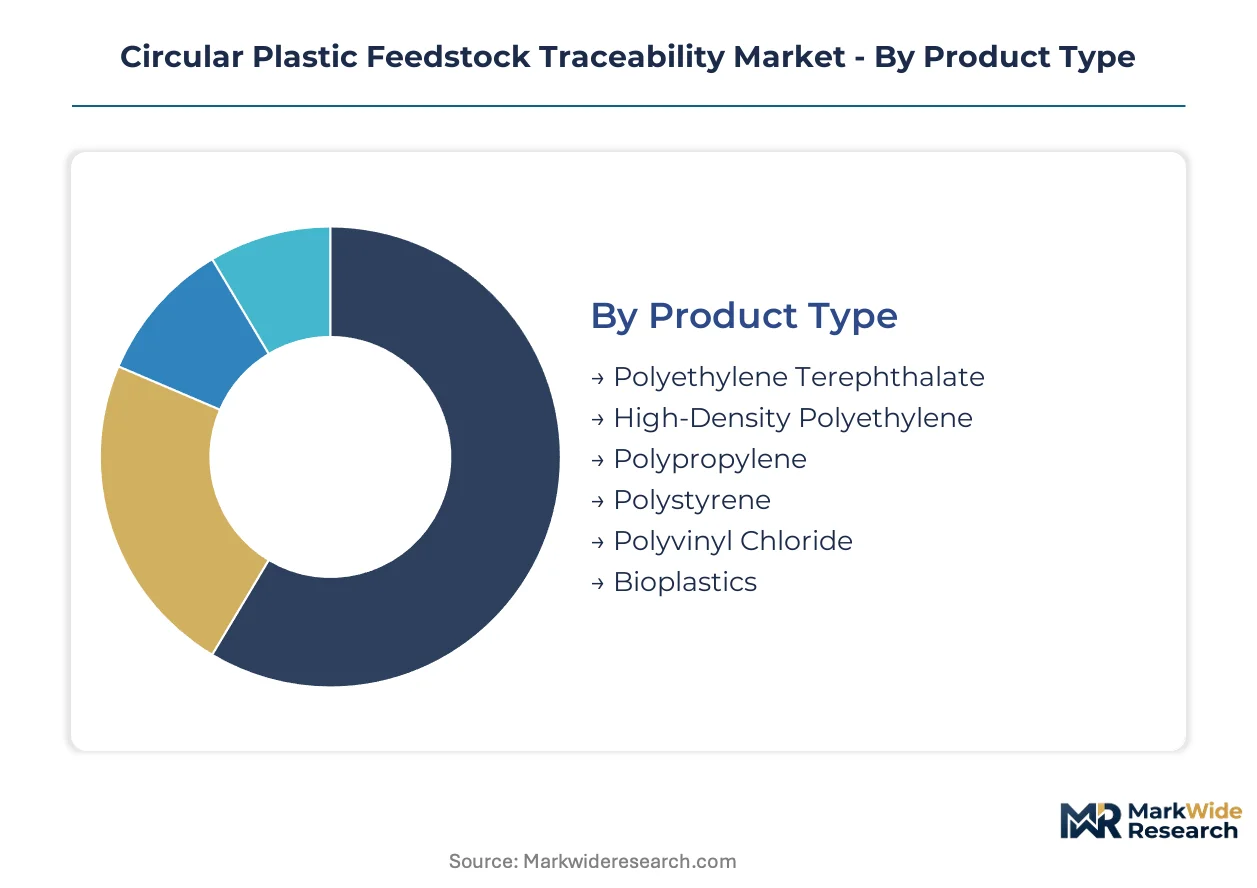
Traceability requirements diverge sharply across polymer chemistries and processing stages, forcing technology vendors to architect modular platforms that scale from mechanical recycling verification to mass-balance chemical recycling certification. Segmentation reveals where standardization yields economies of scale versus where customization commands premium pricing.
Product Type:
Standardization dominates commodity thermoplastics with established testing protocols, while bioplastics demand bespoke verification frameworks due to heterogeneous feedstock origins and degradation profiles.
- Polyethylene Terephthalate:Crystalline thermoplastic with established infrared spectroscopic fingerprinting protocols. Beverage sector compliance deadlines in Germany's Rhine corridor concentrate technology spend here, though mechanical recycling contamination thresholds create verification bottlenecks at depolymerization facilities.
- High-Density Polyethylene:Semi-crystalline polymer requiring melt-flow index tracking alongside chain-of-custody documentation. Blow-molded container producers in France's industrial north are mandating RFID-tagged bales to satisfy retailer audit requirements, compressing supplier qualification timelines.
- Polypropylene:Copolymer variants complicate spectroscopic identification, demanding multi-sensor fusion approaches at sorting hubs.
- Polystyrene:Foamed and solid grades require separate mass-balance accounting due to density differentials in chemical recycling feedstock.
- Polyvinyl Chloride:Additive loadings and plasticizer migration necessitate substance-level tracking beyond polymer origin verification.
- Bioplastics:Heterogeneous feedstocks spanning PLA, PHA, and starch blends resist standardized testing, forcing custom certification pathways.
Leading the category by volume: Polyethylene Terephthalate. Expanding most quickly: Bioplastics.
Technology:
Hardware deployment costs stratify adoption across facility tiers, with cloud infrastructure enabling smaller operators to access enterprise-grade verification without capex intensity.
- Radio Frequency Identification:Passive UHF tags embedded in bale strapping enable automated gate-to-gate tracking. Silicon chip supply constraints and rare-earth price volatility are inflating deployment budgets at Dutch sorting facilities, delaying rollout timelines.
- Blockchain:Distributed ledger architectures provide immutable chain-of-custody records for mass-balance certification. Interoperability gaps between competing consortium networks are fragmenting verification ecosystems across national registries, complicating cross-border feedstock trading.
- Near Field Communication:Short-range protocols suit container-level tracking at reprocessing facilities with controlled handling environments.
- Optical Sensors:Machine vision paired with polymer spectroscopy enables real-time contamination detection at conveyor speeds exceeding manual sampling capacity.
- Barcode Systems:Legacy linear and 2D codes persist at mechanical recycling operations with limited digitization budgets.
- Cloud Computing:SaaS traceability platforms reduce middleware requirements for SAP-integrated procurement workflows.
Dominant by deployment scale: Radio Frequency Identification. Steepest expansion trajectory: Blockchain.
Application:
Margin structures vary with compliance timeline urgency, as beverage sector deadlines force premium pricing for expedited certification while automotive mandates create longer-term contract visibility.
- Packaging Materials:Flexible and rigid formats anchor current revenue, with EU Green Deal delegated acts mandating recycled content verification. German packaging producers face the steepest compliance ramps, with verification thresholds exceeding baseline EU requirements.
- Automotive Components:Interior and under-hood parts are emerging as margin pools as OEMs mandate recycled content verification. KBA audit requirements are disqualifying unverified feedstock sources from Tier-1 supplier contracts, compressing the viable vendor base.
- Consumer Electronics:RoHS substance restrictions overlap with origin verification, expanding tracking scope to hazardous additive documentation.
- Construction Materials:Long product lifecycles delay feedstock return to recycling streams, complicating closed-loop verification.
- Textiles:Fiber-to-fiber recycling chains require distinct mass-balance methodologies from polymer reprocessing.
- Household Goods:Diverse product formats resist standardized tagging protocols, fragmenting technology requirements.
Highest current revenue concentration: Packaging Materials. Gaining share fastest: Automotive Components.
End User Industry:
Procurement sophistication varies with regulatory exposure, as manufacturers face direct compliance liability while waste management operators serve as verification data originators without downstream accountability.
- Manufacturers:Brand owners and converters bear direct liability for recycled content claims under EU Green Deal and REACH Article 33 obligations. ECHA mass-balance certification timelines stretching 18-24 months are delaying revenue recognition and forcing advance contracting with accredited suppliers.
- Waste Management Companies:Collection and sorting operators generate primary chain-of-custody data. Retrofit capex for optical sensor installation at legacy mechanical plants requires line shutdowns that compress throughput during peak collection seasons.
- Recycling Facilities:Mechanical and chemical reprocessors require mass-balance documentation for output certification.
- Plastic Converters:Injection and blow molders need polymer degradation index tracking to certify performance equivalence.
- Regulatory Authorities:National packaging regulators and ECHA enforce verification thresholds and audit protocols.
- Environmental Organizations:NGOs and certification bodies provide third-party validation and public transparency reporting.
Largest technology procurement scale: Manufacturers. Climbing the fastest: Regulatory Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Rhine corridor anchors European traceability deployment, with BASF and Neste operating integrated chemical recycling complexes that demand mass-balance certification systems. This concentration pulls technology investment toward verification infrastructure that can satisfy ECHA audit timelines.
Germany
KBA automotive supplier requirements and EU Green Deal packaging mandates drive traceability procurement across the Rhine corridor. The national packaging regulator enforces verification thresholds stricter than baseline EU requirements. BASF's Ludwigshafen complex and Neste's Rotterdam-connected operations pull RFID and optical sensor demand through mass-balance certification needs.
France
Blow-molded container producers in the industrial north mandate RFID-tagged bales to satisfy retailer audit timelines. REACH Article 33 obligations expand tracking scope to hazardous additive documentation. The country's chemical recycling pilot projects near Lyon require blockchain-based chain-of-custody systems for output certification.
Netherlands
Dutch sorting facilities face silicon chip supply constraints and rare-earth price volatility inflating hardware deployment budgets. The Port of Rotterdam serves as a feedstock gateway connecting chemical recycling operators to German industrial demand. National regulators align with ECHA guidance while pushing faster digitization timelines than neighboring jurisdictions.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for polymer producers serving EU markets. London-based fintech talent pools supply blockchain cryptography expertise to traceability vendors. The country's packaging extended producer responsibility schemes drive adoption of cloud-based verification platforms.
Italy
Mechanical recycling concentration in the northern industrial belt generates demand for retrofit optical sensor installations. The country's textile sector explores fiber-to-fiber mass-balance methodologies distinct from polymer reprocessing. Milan-based packaging converters face beverage sector compliance deadlines ahead of industrial applications.
Circular Plastic Feedstock Traceability Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade differentiation, with mass-balance-accredited suppliers commanding pricing power over unverified feedstock sources. The vendor base stratifies into three tiers: enterprise ERP integrators, blockchain-native specialists, and hardware-focused sensor providers. Two dominant competitive moves are shaping positioning—strategic partnerships between chemical recyclers and verification platforms, and vertical integration of optical sorting technology into legacy mechanical recycling operations.
Within the blockchain-native tier, Circularise and Circulor exemplify divergent architectural approaches to distributed ledger deployment. SAP anchors the enterprise integration segment, embedding traceability modules within procurement workflows that dominate German industrial buyers. Among chemical sector incumbents, BASF and Neste occupy positions as demand generators whose mass-balance certification requirements pull technology adoption through their supplier networks.
| Leading Market Players |
|---|
| Circularise |
| Circulor |
| SAP |
| Recyda |
| ISCC System |
| BASF |
| Neste |
| Sphera |
| OPTEL |
| Others |
Pricing and Supply Chain Analysis
Captive integration into German chemical recycling complexes anchors supply positioning and pricing power for mass-balance-certified feedstock. BASF's Ludwigshafen operations and Neste's Rotterdam-connected facilities pull verified material through controlled supplier networks, compressing viable vendor bases while sustaining premium realizations for blockchain-documented provenance.
Pricing Analysis
Throughput-linked pricing tiers dominate as chemical recyclers tie software licensing to verified tonnage processed rather than seat-based subscriptions. Certification grade separates ECHA-accredited mass-balance documentation from mechanical recycling origin claims, with automotive OEMs absorbing premiums for KBA-compliant feedstock. Cost compression in hardware deployment runs through silicon chip supply constraints and rare-earth volatility, pressuring RFID tag budgets at Dutch sorting facilities. Waste management operators exhibit highest price sensitivity due to thin collection margins, while polymer producers under EU Green Deal mandates accept premium positioning to secure market access.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based silicon foundries supplying UHF RFID chipsets deployed across European bale-tracking infrastructure. Hardware assembly concentrates in China, Germany, and the Netherlands, with optical sensor fabrication anchored in German industrial clusters. Supply chain risk centers on rare-earth price volatility for neodymium-doped magnet components in automated sorting equipment. Distribution runs through chemical recycling complexes in Germany's Rhine corridor, where mass-balance certification requirements gate downstream access to automotive and packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures intensify as ECHA mass-balance certification timelines stretch 18-24 months, forcing capital-constrained traceability vendors toward strategic exit or acquisition.
For Market Incumbents: To counter interoperability fragmentation across competing blockchain consortiums, SAP-integrated players should deepen API standardization investments while acquiring optical sensor specialists to control hardware-data fusion capabilities. Certification moats around ECHA-accredited mass-balance documentation provide defensive positioning against modular entrants. For New Entrants and Emerging Players: Cloud-native SaaS platforms offer the most penetrable wedge as mid-sized French blow-molded container producers seek SAP alternatives without middleware development costs. Target automotive component traceability ahead of KBA audit deadline clustering, leveraging AI-optical sorting convergence to undercut pure-RFID capex requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to enterprise software vendors seeking supply chain sustainability modules. Five-to-ten year viability favors blockchain-native specialists with live mass-balance certification deployments over hardware-pure plays exposed to silicon supply volatility. Watch ECHA guidance on recycled content calculation methods as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Consortium Interoperability Investment | Reduces fragmentation across national registries and enables cross-border feedstock trading for German chemical recyclers. |
| Optical Sensor Specialist Acquisition | Secures real-time contamination detection capabilities required by ECHA mass-balance audit protocols. |
| SAP-Native Traceability Module Development | Captures procurement workflow integration demand from Rhine corridor polymer producers facing EU Green Deal deadlines. |
| Automotive Tier-1 Supplier Partnership | Locks in long-term offtake visibility as KBA requirements disqualify unverified feedstock from interior component contracts. |
| REACH Article 33 Compliance Expansion | Captures hazardous additive tracking scope beyond polymer origin verification for packaging materials producers. |
Research Methodology
Regulatory filings from ECHA and KBA, trade data from Eurostat and UN Comtrade, and chemical sector disclosures from BASF and Neste formed the secondary backbone. Primary interviews with sorting facility operators, chemical recycling plant managers, automotive procurement leads, and packaging converter sustainability officers validated demand assumptions. Bottom-up facility deployment counts across Germany, France, and the Netherlands were triangulated against top-down software licensing revenue estimates from SAP-integrated traceability modules.
Historical trendline analysis examined RFID tag deployment trajectories and blockchain consortium formation patterns across the analysis window. Segmentation modeling captured polymer chemistry, technology type, application vertical, and end-user industry dimensions. CAGRs were derived from facility capex pipelines and mass-balance certification queue lengths. Forecast inputs included EU Green Deal delegated act implementation timelines and ECHA guidance revision schedules.
Caveats apply where silicon chip supply constraints, rare-earth price volatility, or ECHA mass-balance rule changes could materially shift the outlook. Forecasts reflect assumptions about certification timeline stability and interoperability protocol adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
US Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Modified Polypropylene Market