
 Fiber-Reinforced Plastic (FRP) Recycling Market | 2026-2036
Fiber-Reinforced Plastic (FRP) Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Reinforced Plastic (FRP) Recycling Market Foresight
Aerospace-grade reclaimed carbon fiber specification tiers is collapsing toward broader industrial acceptance as pyrolysis quality improves. Vartega Inc leverages proprietary sizing chemistry to sustain fiber mechanical properties through multiple recovery cycles. Owens Corning anchors North American supply through integrated mechanical shredding and compounding operations. Toray Industries Inc dominates Asian chemical recycling scale with continuous carbon fiber recovery lines.
Fiber-reinforced plastic recycling encompasses the collection, size reduction, thermal decomposition, and reprocessing of polymer matrices reinforced with glass, carbon, or aramid fibers to recover reusable fiber and resin fractions. Pyrolysis temperatures between 450°C and 700°C under inert atmosphere preserve tensile strength above 85% of virgin fiber values for non-structural applications. Thermoset composites occupy the largest volume share due to wind blade decommissioning waves and boat hull retirement schedules. Chemical recycling via solvolysis captures the fastest expansion trajectory as supercritical fluid processes achieve aerospace qualification for secondary laminates. Hybrid composites concentrate margin pools where multi-fiber separation technologies command premium recovery yields.
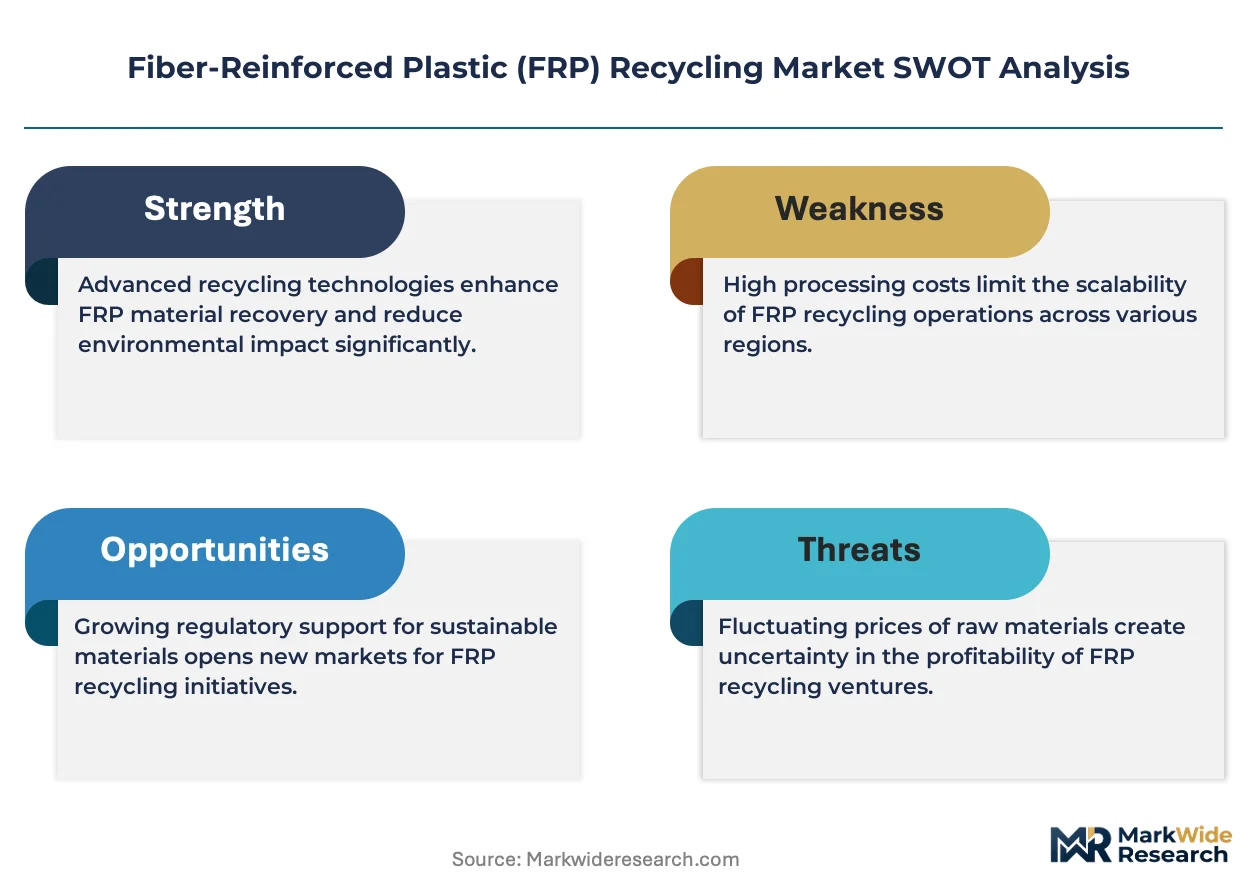
EPA hazardous waste classifications for thermoset dust and EU REACH substance of very high concern listings for bisphenol-based resins are tightening landfill diversion mandates across North America and Europe. ECHA authorization requirements for styrene in unsaturated polyester resins are accelerating substitution toward recyclable thermoplastic matrices in marine and construction applications. Stakeholders must monitor solvolysis scale-up economics against mechanical route unit costs as fiber quality certification standards crystallize.
Market Dynamics
Pyrolysis technology maturation is collapsing aerospace-grade reclaimed carbon fiber specification tiers toward broader industrial acceptance, while EU REACH substance of very high concern listings for bisphenol-based resins tighten landfill diversion mandates across Europe.
Growth Catalysts
- EU Waste Framework Directive:Thermoset composite disposal rules are tightening across Germany, France, and the United Kingdom, concentrating demand for aerospace-grade recycled fiber feedstock.
- Wind blade decommissioning:Scheduled retirement waves for turbine installations are generating predictable feedstock volumes for mechanical shredding and pyrolysis operations.
- Automotive closed-loop programs:Manufacturers are expanding carbon fiber component recovery systems to meet circular economy mandates and reduce virgin material procurement.
Market Restraints
- Energy input volatility:Pyrolysis operations require sustained thermal input between 450°C and 700°C, exposing processors to natural gas and electricity price swings.
- Asian chemical recycling concentration:Continuous carbon fiber recovery line capacity clusters in Japan and China, creating supply security exposure for European and North American compounders.
- Thermoset matrix limitation:Cross-linked polymer structures resist conventional re-melting, forcing capital-intensive thermal decomposition or solvolysis for fiber liberation.
Strategic Opportunities
- Supercritical fluid solvolysis:Chemical recycling via supercritical processes is achieving aerospace qualification for secondary laminates, opening premium pricing tiers.
- Marine sector substitution:ECHA authorization requirements for styrene in unsaturated polyester resins are accelerating thermoplastic matrix adoption in boat hull construction.
- Hybrid composite separation:Multi-fiber recovery technologies command premium yields where glass-carbon-aramid combinations concentrate in aerospace and sporting goods scrap.
Industry Challenges
- Fiber quality certification timelines:Aerospace and automotive OEMs require multi-year qualification cycles for reclaimed carbon fiber in structural applications, compressing near-term revenue recognition.
- Sizing chemistry IP complexity:Proprietary fiber surface treatments that preserve mechanical properties through recovery cycles involve tightly held patent estates, complicating technology licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Reinforced Plastic (FRP) Recycling Market |
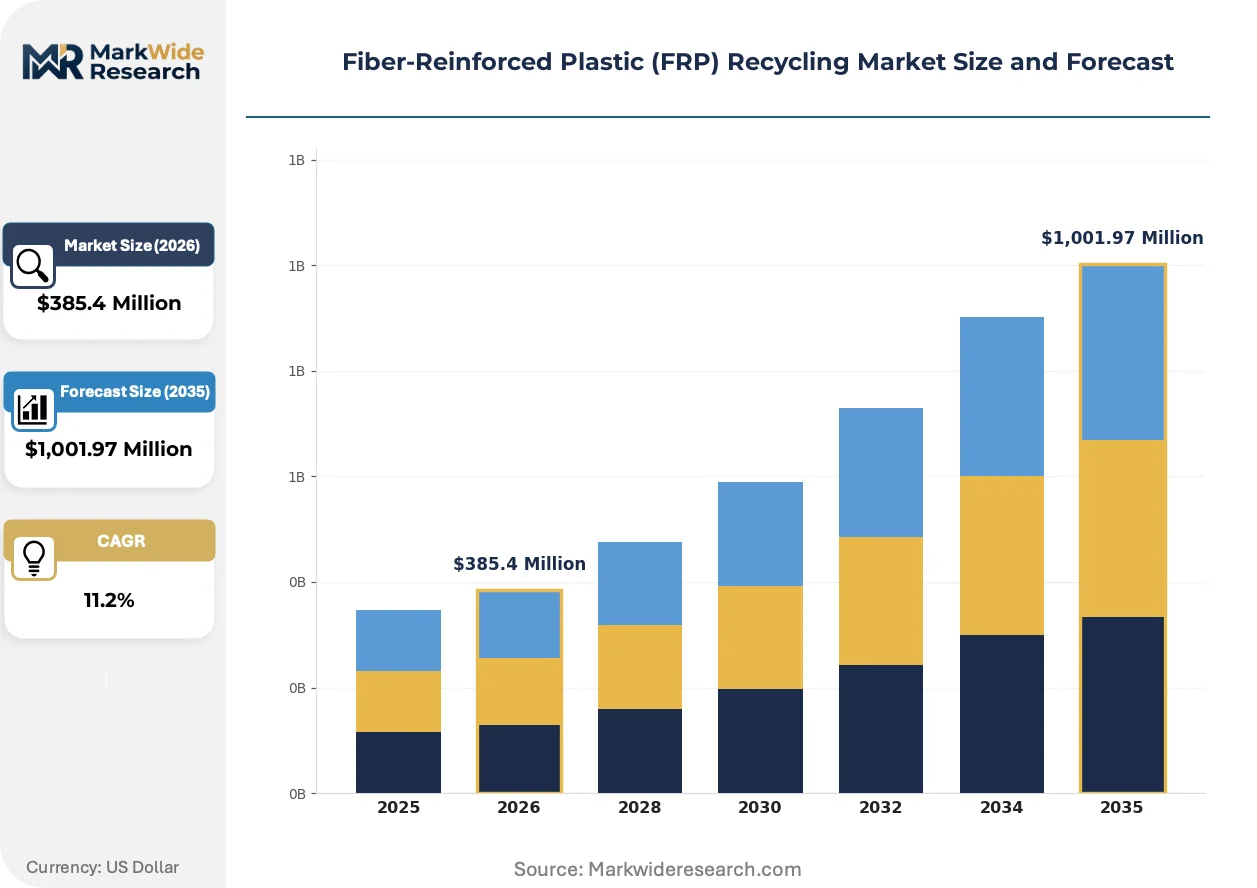
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Composites, Thermoplastic Composites, Hybrid Composites, Others End User: Aerospace, Automotive, Construction, Electronics Recycling Method: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Solvolysis Application: Transportation, Building Materials, Consumer Goods, Sports Equipment |
| Companies Covered | Vartega Inc, Solvay Group, Ucomposites AS, Owens Corning, Hexcel Corporation, Gen 2 Carbon Limited, Toray Industries Inc., Mitsubishi Chemical Holdings, Carbon Conversions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Reinforced Plastic (FRP) Recycling Market Shifts & Advancements
Recovery technology economics are reshaping competitive positioning between mechanical shredding, pyrolysis, and emerging solvolysis routes as fiber quality certification standards crystallize across end-use verticals.
Pyrolysis reactor design is fragmenting across batch, semi-continuous, and fully continuous configurations as equipment suppliers target distinct feedstock scales and fiber quality tiers. Wind blade processors favor large-batch systems for irregular geometry incoming material, while aerospace scrap generators demand continuous lines for consistent tow output. This fragmentation is enabling mid-scale regional processors to compete with integrated chemical conglomerates on feedstock proximity rather than unit scale.
REACH substance of very high concern listings for bisphenol A diglycidyl ether in epoxy resins are forcing compounders to document supply chain provenance for recycled fiber feedstock. The industrial consequence is accelerated investment in batch-level tracking systems and third-party certification partnerships. Marine and construction sectors in Northern Europe are responding fastest, substituting toward bio-based and thermoplastic matrices that simplify end-of-life handling.
Automotive OEMs are consolidating recycled carbon fiber procurement under direct mill relationships rather than distributor intermediaries, compressing traditional compounder margins. Tier-1 suppliers in Germany and the United States are establishing captive pyrolysis partnerships or equity stakes in recovery operators to secure aerospace-grade fiber quotas. This disintermediation is most visible in electric vehicle battery enclosure programs where lightweighting targets coincide with circular economy reporting requirements.
Fiber-Reinforced Plastic (FRP) Recycling Market Segmentation
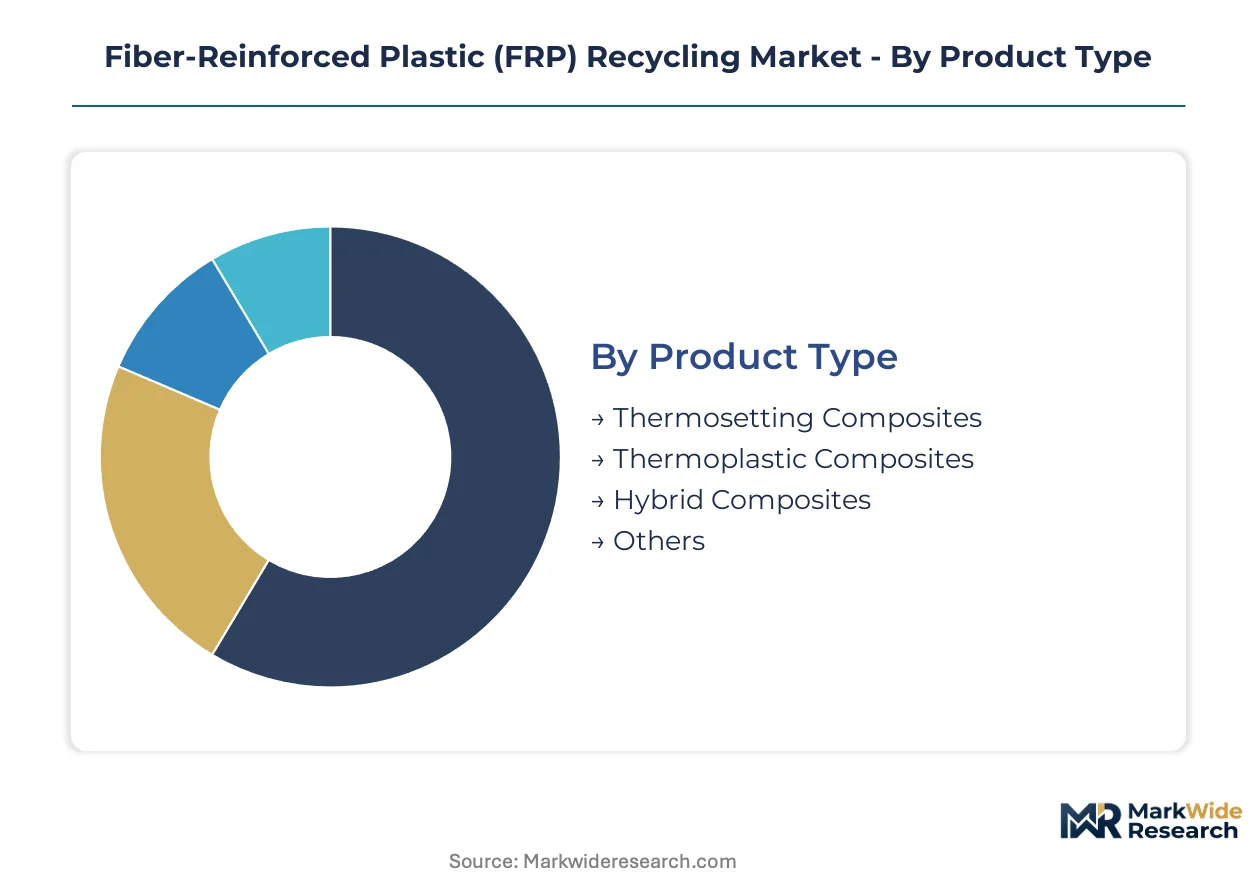
FRP recycling economics diverge sharply across matrix chemistry and fiber type, with thermoset cross-linking dictating capital-intensive recovery routes while thermoplastic streams enable simpler reprocessing. Segmentation clarity helps processors match technology selection to feedstock characteristics and end-use qualification requirements.
Product Type:
REACH substance of very high concern listings for bisphenol-based resins impose stricter documentation burdens on thermoset handlers than thermoplastic processors across European operations.
- Thermosetting Composites:Cross-linked epoxy, polyester, and vinyl ester matrices resist remelting, forcing pyrolysis or solvolysis for fiber liberation. Wind blade decommissioning in Germany and Denmark generates predictable feedstock volumes for large-batch thermal decomposition systems.
- Thermoplastic Composites:Meltable polyamide, polypropylene, and PEEK matrices allow direct recompounding without chemical breakdown. Automotive carpet and bumper scrap from Stuttgart and Detroit assembly plants concentrates demand for mechanical shredding and melt filtration lines.
- Hybrid Composites:Multi-fiber constructions combining glass, carbon, and aramid layers complicate separation economics but command premium recovery yields where aerospace trim scrap accumulates.
- Others:Niche bio-composite and natural fiber-reinforced materials remain marginal to commercial recycling infrastructure.
Thermosetting Composites handles the majority of throughput; Hybrid Composites is the fastest mover on share.
End User:
Qualification timelines stretch across customer tiers, with aerospace OEMs demanding multi-year certification cycles that compress near-term revenue recognition against faster-moving automotive programs.
- Aerospace:Boeing and Airbus specification tiers for reclaimed carbon fiber in secondary laminates require continuous tow output and batch-level traceability. Supercritical solvolysis achieves aerospace qualification for non-structural applications, opening premium pricing tiers.
- Automotive:BMW and Volkswagen closed-loop programs for carbon fiber hoods and roof panels prioritize feedstock proximity over fiber grade perfection. Electric vehicle battery enclosure lightweighting targets coincide with circular economy reporting requirements.
- Construction:Bridge decking and rebar applications tolerate lower mechanical property retention, expanding addressable supply for pyrolysis output.
- Electronics:Laptop chassis and smartphone frame scrap generates small-format, high-value fiber suitable for compounding into EMI shielding compounds.
Automotive captures the largest volume commitment; Aerospace shows the steepest expansion trajectory as qualification bottlenecks clear.
Recycling Method:
Capital intensity and energy input requirements stratify processor economics, with mechanical routes dominating low-value feedstock and chemical methods penetrating specification-sensitive end uses.
- Mechanical Recycling:Shredding, milling, and compounding operations anchor North American supply through integrated fiber recovery and pellet production. Owens Corning operations concentrate capacity near glass fiber manufacturing clusters.
- Chemical Recycling:Solvolysis and supercritical fluid processes achieve fiber surface cleanliness standards required for aerospace secondary laminates. Toray Industries dominates Asian continuous carbon fiber recovery line scale.
- Thermal Recycling:Pyrolysis between 450°C and 700°C preserves tensile strength above 85% of virgin values for non-structural applications. Batch configurations suit irregular wind blade geometry; continuous lines serve aerospace scrap generators.
- Solvolysis:Supercritical alcohol and water processes represent the emerging technology frontier with highest fiber quality output but unproven unit economics at commercial scale.
Thermal Recycling manages the bulk of current installed capacity; Solvolysis is climbing the fastest as supercritical scale-up economics improve.
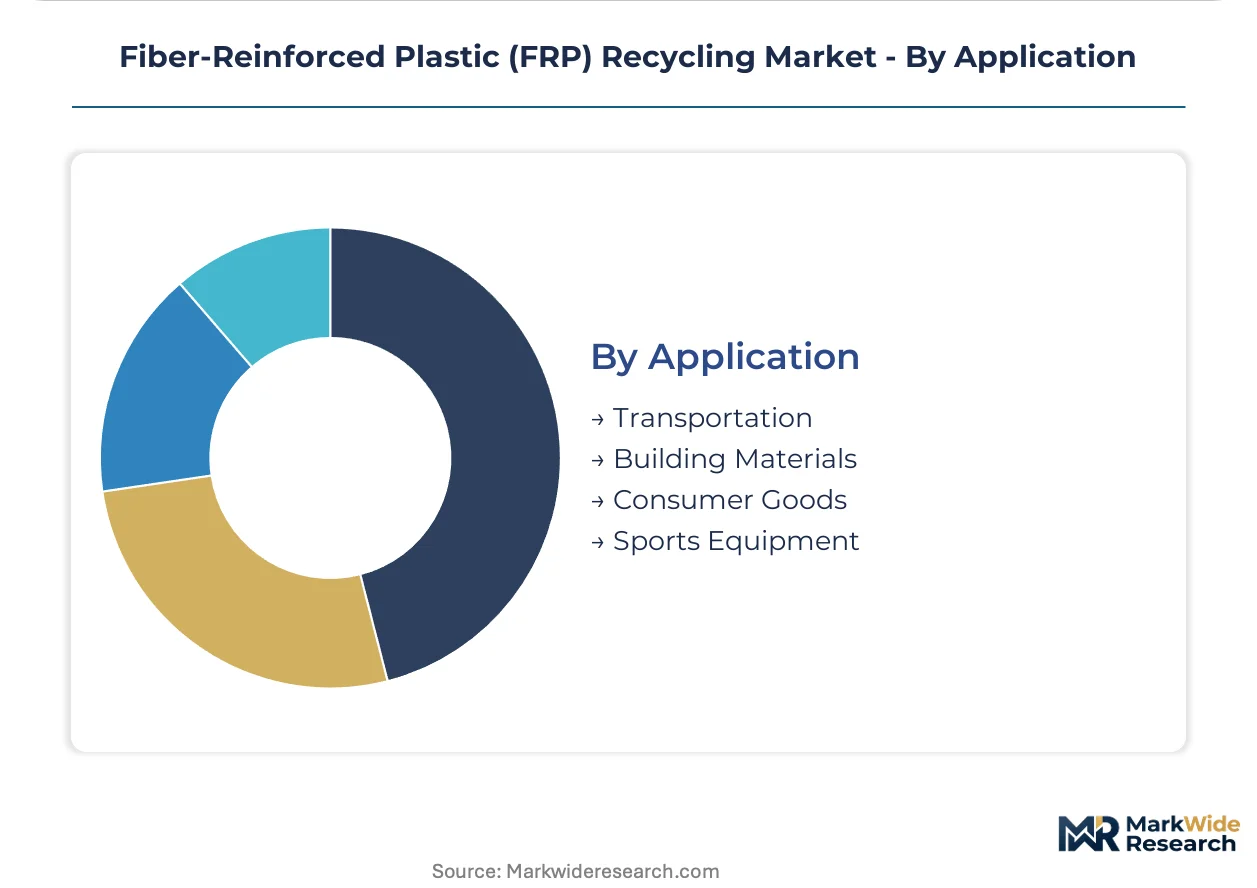
Application:
Performance requirements and regulatory exposure vary across downstream sectors, with transportation applications tolerating broader fiber quality ranges than sports equipment specifications.
- Transportation:Automotive and rail applications absorb reclaimed fiber in underbody shields, interior panels, and non-structural brackets where weight reduction meets cost targets.
- Building Materials:Concrete reinforcement and facade cladding applications exploit lower-grade recycled glass fiber output from construction demolition streams.
- Consumer Goods:Furniture and appliance housings utilize compounded recycled fiber for stiffness and dimensional stability.
- Sports Equipment:Bicycle frames, hockey sticks, and golf club shafts demand higher mechanical property retention, limiting supply to chemical recycling output.
Transportation absorbs the greatest volume; Sports Equipment commands the highest unit value premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Continuous carbon fiber recovery line capacity clusters in Japan and China, creating supply security exposure for European and North American compounders seeking aerospace-grade feedstock.
Germany
Wind blade decommissioning in Schleswig-Holstein and Lower Saxony generates predictable feedstock volumes for large-batch thermal decomposition systems. The EU Waste Framework Directive tightens thermoset composite disposal rules across federal states. Stuttgart automotive clusters concentrate closed-loop carbon fiber recovery programs for BMW and Volkswagen supply chains.
United States
EPA hazardous waste classifications for thermoset dust accelerate landfill diversion mandates across Texas and California processing hubs. The Inflation Reduction Act circular economy provisions support domestic pyrolysis capacity expansion. Detroit automotive assembly plants drive demand for mechanical shredding and melt filtration lines serving recycled fiber compounding.
Japan
Toray Industries anchors Asian chemical recycling scale with continuous carbon fiber recovery lines serving aerospace specification tiers. METI dual carbon goals pressure manufacturers toward thermoplastic matrix substitution in marine applications. Nagoya industrial corridors concentrate supercritical solvolysis pilot programs targeting commercial scale-up.
United Kingdom
Gen 2 Carbon Limited operations in the West Midlands exemplify mid-scale regional processors competing on feedstock proximity. ECHA authorization requirements for styrene in unsaturated polyester resins accelerate construction sector substitution toward recyclable matrices. Yorkshire wind blade retirement schedules align with batch pyrolysis reactor configurations for irregular geometry material.
France
ANSM compliance documentation for bisphenol-based resins forces compounders to track supply chain provenance for recycled fiber feedstock. The EU Green Deal industrial transition funding supports aerospace-grade reclaimed carbon fiber qualification programs. Toulouse aeronautics clusters concentrate demand for secondary laminate applications in non-structural aircraft components.
Fiber-Reinforced Plastic (FRP) Recycling Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialized fiber recovery operators rather than diversified materials conglomerates. Owens Corning anchors North American supply through integrated mechanical shredding and compounding operations near glass fiber manufacturing clusters. Three archetypes dominate: continuous-line chemical recyclers serving aerospace qualification tiers, batch-system regional processors exploiting wind blade proximity, and captive automotive partnerships securing closed-loop fiber quotas. Competitive moves center on strategic partnerships with Tier-1 suppliers and technology licensing for proprietary sizing chemistry.
Within the integrated chemical conglomerate tier, Toray Industries Inc. and Mitsubishi Chemical Holdings exemplify scale-driven positioning across Asian continuous recovery line deployment. Vartega Inc occupies a specialist position representing proprietary fiber surface treatment approaches that sustain mechanical properties through multiple recovery cycles. Owens Corning anchors the mechanical recycling archetype with North American compounding integration.
| Leading Market Players |
|---|
| Vartega Inc |
| Solvay Group |
| Ucomposites AS |
| Owens Corning |
| Hexcel Corporation |
| Gen 2 Carbon Limited |
| Toray Industries Inc. |
| Mitsubishi Chemical Holdings |
| Carbon Conversions |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for aerospace-grade reclaimed carbon fiber concentrate pricing power with continuous-line operators in Japan and Germany, while batch-system regional processors compete on feedstock proximity rather than scale economics. This lead-time compression shapes how automotive OEMs negotiate direct mill relationships versus distributor intermediaries.
Pricing Analysis
EU REACH substance of very high concern listings dictate the pricing tier structure across European operations, forcing compounders to document supply chain provenance for recycled fiber feedstock. Three-tier pricing structure across aerospace-qualified, automotive-grade, and construction-tier output separates specification-sensitive laminates from non-structural applications. Pricing pressure stems from automotive OEM procurement consolidation under direct mill relationships, compressing traditional compounder margins. Construction applications show highest price sensitivity due to lower mechanical property requirements, while aerospace secondary laminates command premium resilience.
Supply Chain Analysis
Strait of Malacca transit vulnerability for pyrolysis equipment components underwrites supply security exposure for European and North American processors scaling thermal recycling capacity. Raw material flows draw from decommissioning wind blades in Northern Germany, automotive scrap clusters around Stuttgart and Detroit, and aerospace trim accumulation near Toulouse. Single-source vulnerability concentrates in continuous carbon fiber recovery line technology held by Japanese chemical conglomerates. Distribution runs through captive automotive partnerships and Tier-1 supplier equity stakes rather than open-market spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fiber surface treatment expertise represents the critical bottleneck constraining entry, as proprietary sizing chemistry that sustains mechanical properties through multiple recovery cycles remains tightly held within patent estates. New market participants face multi-year qualification timelines and capital-intensive thermal decomposition or solvolysis infrastructure requirements.
For Market Incumbents: Consolidate regional feedstock access through equity stakes in wind blade decommissioning operators and automotive closed-loop program partnerships. Toray Industries and Owens Corning demonstrate how backward integration into pyrolysis capacity insulates against energy input volatility. Certification investment in aerospace-grade reclaimed carbon fiber specifications preserves margin differentiation against emerging solvolysis competitors. For New Entrants and Emerging Players: Lead with supercritical fluid solvolysis scale-up targeting marine sector thermoplastic matrix substitution, where ECHA authorization requirements for styrene accelerate addressable market expansion. White-space concentrates in mid-scale batch pyrolysis systems serving irregular wind blade geometry in Yorkshire and Schleswig-Holstein. Go-to-market positioning emphasizes batch-level tracking systems and third-party certification partnerships for REACH compliance documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core fiber recovery operations as circular economy reporting requirements intensify. Long-term viability favors operators with demonstrated aerospace qualification timelines and proprietary sizing chemistry IP. The signal to watch is automotive OEM direct procurement consolidation compressing distributor-dependent compounder margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | Captive thermal recycling insulates German automotive suppliers from natural gas price volatility. |
| Aerospace Qualification Investment | Continuous tow output certification opens premium pricing tiers for secondary laminate applications. |
| Supercritical Solvolysis Scale-Up | Commercial deployment near Nagoya industrial corridors targets METI dual carbon compliance requirements. |
| Batch-Level Tracking Systems | Supply chain provenance documentation satisfies ANSM compliance for bisphenol-based resin handling. |
| Wind Blade Decommissioning Partnerships | Feedstock proximity agreements in Lower Saxony secure predictable volumes for large-batch thermal systems. |
Research Methodology
Desk research of customs trade data, EPA hazardous waste classifications, and ECHA authorization registries preceded structured interviews with pyrolysis plant managers, aerospace procurement leads at Tier-1 suppliers, marine composite engineers, and regulatory affairs directors at compounders. Primary fieldwork combined with secondary validation from SEC filings of integrated chemical conglomerates, EU Waste Framework Directive implementation reports, and wind blade decommissioning schedules. Bottom-up feedstock volume estimates triangulated against top-down end-use demand projections across automotive, aerospace, and construction verticals.
Variance decomposition across matrix chemistry, fiber type, recycling method, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation modeling incorporated thermoset versus thermoplastic composite splits, mechanical versus chemical versus thermal recovery route economics, and qualification tier differentiation across aerospace, automotive, construction, and sports equipment end uses. CAGRs derived from installed capacity buildout trajectories, feedstock availability curves, and fiber quality certification timeline assumptions.
Forecasts assume regulatory continuity in EU REACH implementation and EPA hazardous waste classifications; material policy shifts would require re-modeling landfill diversion mandate stringency and aerospace qualification pathway modifications. Practitioners should keep alternative scenarios live as supercritical solvolysis scale-up economics and automotive OEM procurement consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Aluminum Recycling Market