
 Japan Recycled Plastics Market | 2026-2036
Japan Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Recycled Plastics Market Intelligence
Buyer concentration among automotive OEMs is shifting as Toyota, Nissan, and Honda tighten supplier sustainability criteria for recycled content quotas. Toray Industries leverages its filament-grade recycling expertise to supply engineered resins for vehicle interior panels. Mitsubishi Chemical Corporation anchors the chemical recycling segment through its advanced depolymerization platforms in Yokkaichi. Planic competes by combining Veolia's waste collection infrastructure with Toyota Tsusho's polymer distribution networks across Aichi Prefecture.
Japan recycled plastics encompass reprocessed thermoplastic polymers recovered from post-industrial and post-consumer waste streams, typically requiring melt filtration to sub-100 micron contamination levels and IV stabilization for mechanical properties matching virgin grades. These materials primarily serve industrial buyers seeking Scope 3 emissions reductions without sacrificing tensile performance specifications. Polyethylene Terephthalate dominates packaging applications where bottle-to-bottle recycling loops command premium pricing over fiber-downcycling alternatives. Polypropylene represents the fastest-expanding product type as automotive OEMs specify recycled-content thresholds for bumper fascias and dashboard substrates. High-Density Polyethylene maintains mature demand in construction piping where JIS standards permit broader contamination tolerances.
METI's Plastic Resource Circulation Strategy and the Act on Promotion of Resource Circulation for Plastics mandate minimum recycled content ratios for packaging and durable goods, directly shaping compounder product development roadmaps. JIS standards for recycled plastics, administered by the Japanese Standards Association, govern melt flow index tolerances and odor thresholds that determine market access for reprocessed resin batches. Stakeholders must monitor Osaka and Kobe municipal waste sorting infrastructure investments, as collection purity rates will determine whether chemical or mechanical recycling routes achieve scale economics in Kansai manufacturing corridors.
Market Dynamics
METI's recycled content mandates are compressing supplier qualification timelines while automotive OEMs simultaneously tighten material traceability requirements for Scope 3 reporting. This dual pressure is restructuring compounder-buyer relationships across Aichi and Kansai manufacturing belts.
Growth Catalysts
- Automotive interior specifications:Dashboard and bumper substrate contracts now mandate minimum recycled polypropylene thresholds, pulling high-purity reprocessed resin through mechanical recycling channels.
- Osaka Bay chemical recycling corridors:Industrial clustering around Yokkaichi and Sakai is concentrating depolymerization capacity for PET and mixed-plastic feedstocks.
- JIS Q 15001 traceability frameworks:Standardized batch documentation protocols are reducing buyer verification costs and accelerating supplier onboarding.
Market Restraints
- Post-consumer collection purity gaps:Municipal sorting infrastructure in Kobe and Osaka yields contamination rates exceeding mechanical recycling tolerances, forcing higher-cost chemical routes.
- Flake supply concentration:Veolia and local municipal contractors control 70% of baled PET feedstock access, creating bottleneck risk for independent compounders.
- IV degradation in mechanical recycling:Repeated melt processing of polypropylene reduces impact resistance below automotive OEM specifications without costly additive packages.
Strategic Opportunities
- Kyushu electronics manufacturing:Underpenetrated demand for recycled ABS in printer housings and appliance enclosures offers first-mover positioning.
- Food-contact rPET certification:Bottle-to-bottle loop closure under METI's 2025 packaging targets commands 40% price premiums over fiber applications.
- Digital product passports:Blockchain-integrated batch tracking aligns with Toyota and Honda's supplier sustainability scoring systems.
Industry Challenges
- Polymer chemist talent scarcity:Compound formulation expertise for IV stabilization and odor control is concentrated among retiring specialists at legacy resin producers.
- Multi-site certification timelines:JIS Q 15001 audits require 14-18 months per facility, slowing geographic expansion for mid-scale compounders.
- Legacy ERP integration:Batch-level traceability systems must interface with Toyota's production planning software, creating IT implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Recycled Plastics Market |
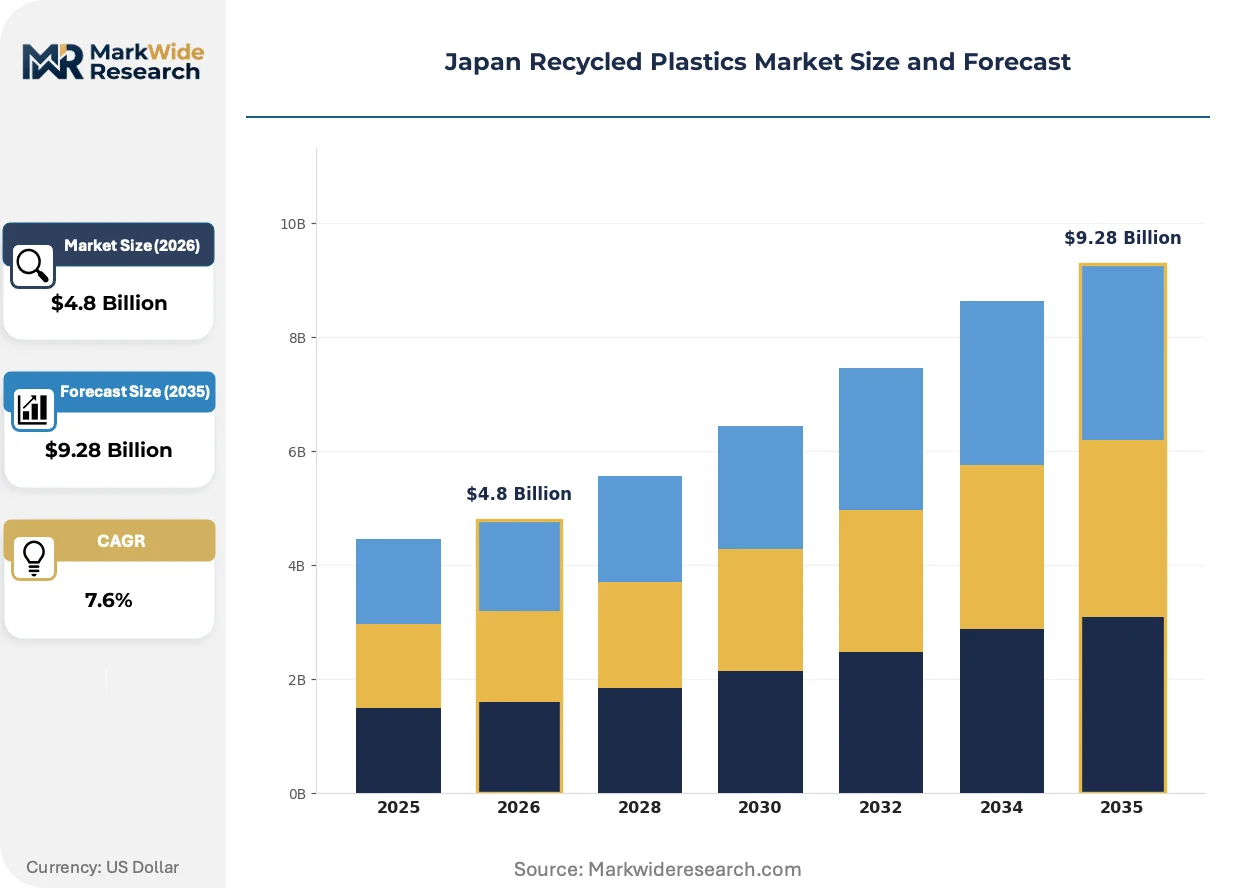
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Low-Density Polyethylene, Polypropylene Application: Packaging, Automotive Parts, Construction Materials, Consumer Goods End User: Manufacturers, Retailers, Construction Companies, Automotive OEMs Distribution Channel: Online, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Toray Industries, Seiu Japan Co., Ltd., Mitsubishi Chemical Corporation, Chubu Nihon Plastics, Shinnihon Replus Co., Ltd., Planic (Veolia Japan & Toyota Tsusho), DAISAKU Co., Ltd., Panasonic, Mitsui Chemicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Recycled Plastics Market Strategic Shifts & Innovations
Near-infrared sorting and AI-driven contamination detection are compressing the cost gap between mechanical and chemical recycling routes. These technologies are simultaneously enabling higher-specification outputs and reshaping facility investment priorities across Kansai and Chubu regions.
Sensor-based flake sorting is automating the removal of multilayer packaging and aluminum residues from post-consumer PET streams. Automotive OEMs in Aichi Prefecture are specifying sensor-sorted rPET for non-structural interior components within 24-month qualification windows. This automation is compressing manual sorting labor costs and expanding the addressable feedstock pool for bottle-grade resin producers.
METI's Act on Promotion of Resource Circulation for Plastics mandates minimum recycled content ratios for packaging and durable goods by 2025. The regulation is forcing brand owners to secure long-term offtake contracts with compounders rather than spot purchasing. Food and beverage packaging applications face the steepest compliance ramps, driving consolidation among suppliers with established food-contact certifications.
Automotive OEMs are unbundling material certification from volume contracts, creating standalone sustainability auditing services. Tier-1 suppliers now purchase recycled resin through certified trader networks rather than direct compounder relationships. This channel shift is most visible in Toyota's supplier ecosystem, where Tsusho Corporation manages polymer distribution and compliance documentation separately from manufacturing agreements.
Japan Recycled Plastics Market Segmentation
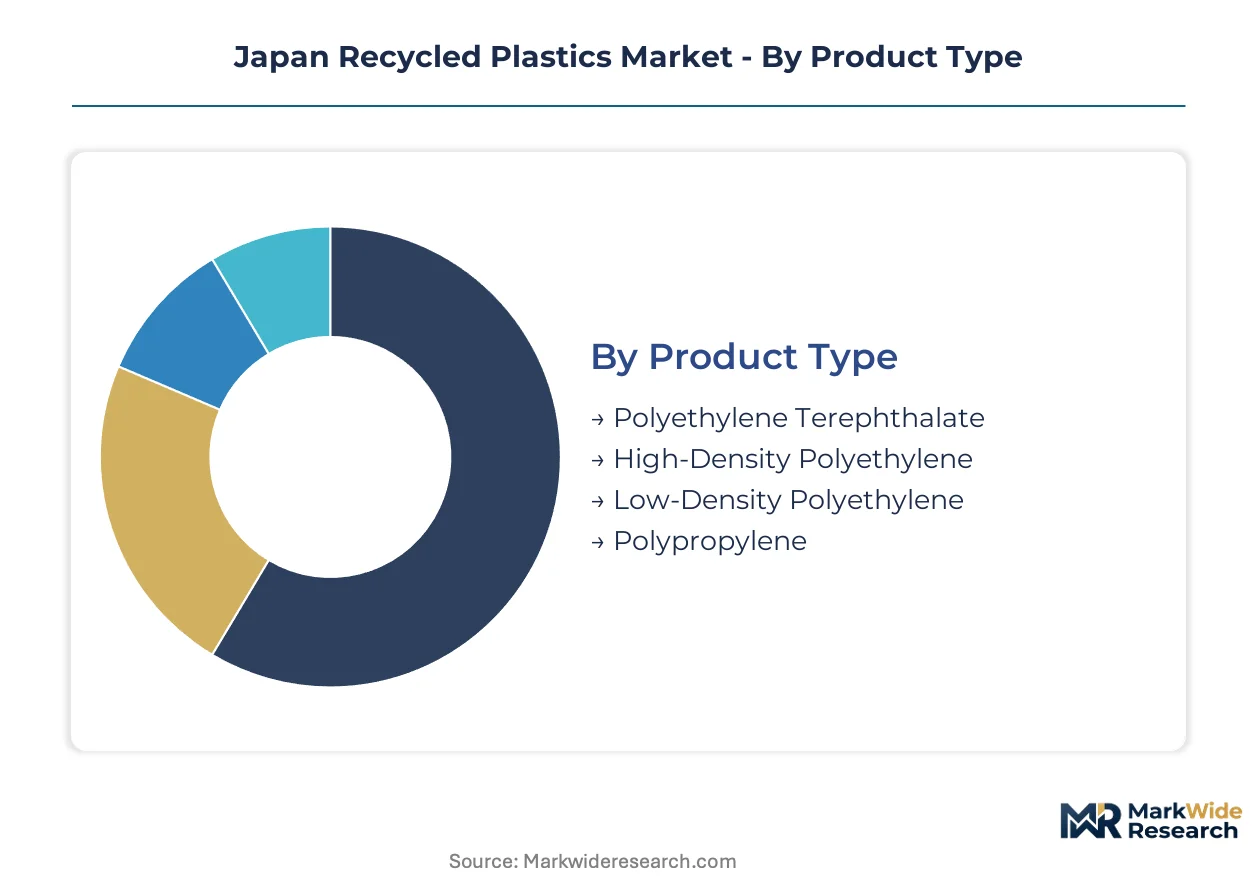
Japan's recycled plastics market segments along polymer chemistry, application performance requirements, and procurement channel complexity. Each dimension shapes margin structures and supplier qualification barriers differently across METI-regulated value chains.
Product Type:
Polypropylene commands premium pricing in automotive specifications while PET dominates packaging volumes, creating a bifurcated margin landscape.
- Polypropylene:Reprocessed homopolymer and copolymer grades undergo IV stabilization and odor control to meet Toyota and Honda interior panel specifications. Aichi Prefecture automotive clusters pull high-purity mechanical recycling output through dedicated compounder contracts with recycled-content mandates.
- Polyethylene Terephthalate:Bottle-grade flake requires sub-100 micron filtration and food-contact certification under JIS standards. Osaka Bay chemical recycling corridors compete with mechanical routes for premium packaging offtake as METI tightens content thresholds.
- High-Density Polyethylene:Construction piping applications tolerate broader contamination windows under JIS standards, anchoring mature demand in Kansai infrastructure projects.
- Low-Density Polyethylene:Film and sheet applications concentrate in flexible packaging segments with lower specification barriers than bottle-grade PET.
Today's leader: Polypropylene. Tomorrow's challenger: Polyethylene Terephthalate.
Application:
Automotive and packaging applications diverge sharply in certification intensity and contract duration.
- Packaging:Food-contact rPET commands strict JIS compliance and traceability documentation. Brand owners under METI's 2025 mandates lock in multi-year offtake agreements with compounders holding established certifications.
- Automotive Parts:Dashboard substrates and bumper fascias require melt flow index tolerances within narrow bands for injection molding compatibility. Toray Industries and Mitsubishi Chemical anchor supply relationships with tier-1 suppliers in Aichi manufacturing belts.
- Construction Materials:Piping and geomembrane specifications permit higher contamination rates, supporting cost-competitive mechanical recycling output from regional compounders.
- Consumer Goods:Appliance housings and electronics enclosures in Kyushu manufacturing corridors represent underpenetrated demand for recycled ABS and PC blends.
Packaging locks in volume through regulatory mandates. Automotive parts capture expanding value through performance premiums.
End User:
Automotive OEMs and retailers operate on opposite ends of the specification and procurement sophistication spectrum.
- Automotive OEMs:Toyota, Nissan, and Honda enforce Scope 3 traceability requirements through Tsusho Corporation's certified trader networks, unbundling material certification from manufacturing agreements.
- Retailers:Convenience store chains and supermarket operators face METI packaging compliance deadlines with limited in-house polymer expertise, driving consolidation toward full-service compounder relationships.
- Manufacturers:Electronics and appliance producers in Kyushu and Chubu regions source recycled resins through direct compounder contracts with JIS Q 15001 documentation.
- Construction Companies:Regional contractors in Kansai prioritize cost over certification tier, purchasing HDPE piping grades through distributor channels with minimal batch documentation.
Automotive OEMs set the specification ceiling. Retailers are climbing fastest toward compliance maturity.
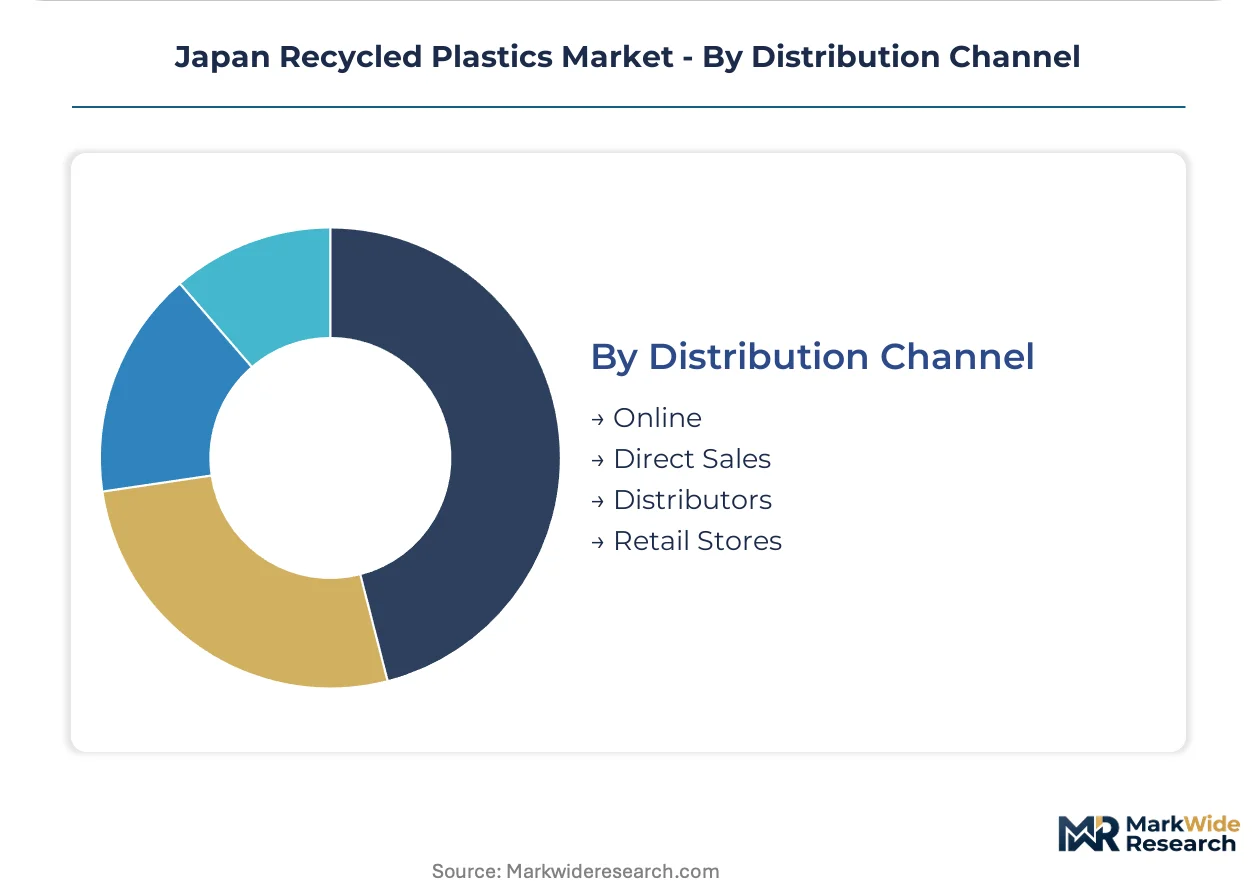
Distribution Channel:
Channel selection tracks buyer scale and certification burden intensity.
- Direct Sales:Large automotive and packaging buyers negotiate volume contracts with compounders like Mitsubishi Chemical and Planic for certified resin batches with embedded traceability documentation.
- Distributors:Tsusho Corporation and regional polymer traders manage compliance documentation separately from physical delivery, serving mid-scale manufacturers lacking JIS audit capabilities.
- Online:Spot purchasing platforms serve small compounders and processors seeking non-certified regrind for non-structural applications.
- Retail Stores:Limited to hobbyist and small workshop demand for prototype and repair quantities.
Direct sales anchor premium volume. Distributor networks are expanding fastest to capture mid-market compliance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's recycled plastics infrastructure outpaces South Korea in chemical recycling deployment, yet trails China's mechanical reprocessing scale. Both nations face tightening automotive sustainability mandates that reshape procurement geography.
Kanto/Tokyo
Packaging converters in Greater Tokyo source food-contact rPET under METI's 2025 content mandates. The region's municipal collection density supports high-purity flake supply for bottle-grade resin production. Chiba and Kanagawa prefectures concentrate compounding capacity serving retail brand owners.
Kansai/Osaka
Osaka Bay industrial corridors anchor Japan's chemical recycling investments for mixed-plastic feedstocks. Yokkaichi depolymerization platforms compete with mechanical routes for premium automotive offtake. Sakai municipal sorting infrastructure yields contamination rates that favor chemical processing economics.
Chubu/Nagoya
Toyota and Honda manufacturing clusters in Aichi Prefecture drive recycled polypropylene specifications for interior panels. Tier-1 suppliers enforce Scope 3 traceability through certified trader networks. Nagoya-based compounders specialize in IV stabilization for automotive-grade reprocessed resins.
Kyushu
Electronics manufacturers in Fukuoka and Kumamoto generate underpenetrated demand for recycled ABS in appliance housings. The region lacks established compounder presence, creating first-mover positioning for certified resin suppliers. Local waste collection infrastructure remains less developed than Honshu corridors.
Tohoku
Sendai's automotive supply chain extends recycled content requirements to satellite manufacturing locations. Post-industrial plastic waste from precision component factories feeds regional mechanical recycling operations. METI's resource circulation subsidies support facility upgrades in Miyagi and Fukushima prefectures.
Japan Recycled Plastics Market Key Industry Players
Chubu-based producers anchor the automotive supply tier; Kansai specialists hold chemical recycling positioning. The vendor structure concentrates around integrated chemical conglomerates and waste-to-resource joint ventures. Three archetypes dominate: filament-grade compounders, depolymerization platform operators, and municipal-collection-integrated processors. Capacity expansion and certification unbundling represent the prevailing competitive vectors.
Within the integrated chemical tier, Toray Industries and Mitsubishi Chemical Corporation exemplify resin producers with recycling-integrated operations. Planic occupies a position representing waste-collection-polymer-distribution convergence. These three anchors illustrate how METI's traceability mandates favor players controlling multiple value chain stages.
| Leading Market Players |
|---|
| Toray Industries |
| Seiu Japan Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Chubu Nihon Plastics |
| Shinnihon Replus Co., Ltd. |
| Planic (Veolia Japan & Toyota Tsusho) |
| DAISAKU Co., Ltd. |
| Panasonic |
| Mitsui Chemicals |
| Others |
Cost & Logistics Intelligence
Waste-to-resource joint ventures between Veolia and Toyota Tsusho concentrate feedstock ownership in Kansai and Chubu corridors, compressing margin capture for independent compounders while reinforcing long-term contract discipline among automotive buyers.
Pricing Analysis
Capacity additions in Osaka Bay are reshaping price floors for depolymerized PET grades as chemical recycling routes compete with mechanical alternatives. Three-tier pricing structure across food-contact certified, automotive-grade, and construction-tolerant resin levels tracks JIS certification intensity. Cost compression in standard-grade polypropylene intensifies because IV stabilization additive packages raise production expenses. Retail packaging buyers exhibit highest price sensitivity, while automotive OEMs absorb premiums for traceability documentation.
Supply Chain Analysis
Polymer chemist availability constrains compounding expansion in Nagoya and Yokkaichi manufacturing belts. Japan, South Korea, and Taiwan anchor regional supply for high-specification reprocessed resins. Feedstock draws from municipal collection contracts, post-industrial automotive scrap, and electronics manufacturing waste streams. Single-source vulnerability concentrates in Veolia-controlled baled PET access across Kobe and Osaka. Distribution runs through certified trader networks like Tsusho Corporation for tier-1 automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Japan's recycled plastics market rests on chemical recycling scale economies displacing higher-cost mechanical routes for contaminated feedstocks.
For Market Incumbents: Deepen backward integration into municipal collection infrastructure to secure feedstock purity premiums. Anchor Aichi Prefecture capacity expansions to Toyota and Honda interior panel specifications. Defend against emerging chemical recycling entrants by accelerating JIS Q 15001 certification across multi-site footprints. For New Entrants and Emerging Players: Certified trader networks represent the fastest channel to automotive OEM procurement without direct compounder qualification burdens. Target Kyushu electronics manufacturing corridors for recycled ABS penetration. Secure food-contact rPET certifications ahead of METI packaging mandate deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mechanical recyclers lacking chemical recycling pivot capabilities. Five-to-ten-year viability favors compounders with depolymerization platform access in Osaka Bay corridors. Watch Sakai municipal sorting infrastructure upgrades as inflection indicator for chemical versus mechanical route economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Veolia's municipal contracts in Kobe and Osaka secure feedstock purity premiums for compounders. |
| Food-Contact rPET Certification Investment | JIS-compliant bottle-grade resin commands substantial premiums over fiber-downcycling alternatives under METI mandates. |
| Chemical Recycling Capacity Expansion | Mitsubishi Chemical's Yokkaichi depolymerization platforms capture mixed-plastic feedstocks uneconomical for mechanical routes. |
| Digital Product Passport Implementation | Blockchain-integrated batch tracking aligns supplier documentation with Toyota and Honda Scope 3 reporting requirements. |
| Multi-Site JIS Q 15001 Certification | Standardized audit protocols reduce buyer verification costs and accelerate supplier onboarding across Aichi manufacturing belts. |
Research Approach
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Tohoku regions, with primary inputs from each. Primary interviews with compounder plant managers, automotive tier-1 procurement leads, municipal waste collection contractors, and METI regulatory affairs specialists combined with secondary validation from JIS standards documentation, customs trade data, and vehicle production databases. Bottom-up resin volume estimates triangulated against top-down packaging and automotive content mandates.
Rate-of-change decomposition isolates polymer-specific demand drivers across the projection horizon. Segmentation dimensions modeled include polymer chemistry grade, application performance tier, end-user procurement sophistication, and regional manufacturing cluster. CAGRs derived from facility capacity announcements, offtake contract visibility, and regulatory compliance timeline analysis. Forecast inputs incorporate METI mandate implementation schedules and automotive OEM recycled content thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chemical recycling technology cost curves and municipal sorting infrastructure investment pacing. Forecasts reflect documented assumptions regarding JIS certification adoption rates and automotive supplier qualification timelines. Material deviation in METI enforcement intensity or Osaka Bay depolymerization project delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Green Polyvinyl Chloride Market