
 Green Polyvinyl Chloride Market | 2026-2036
Green Polyvinyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Green Polyvinyl Chloride Market Foresight
Phthalate-free specification tiers are rotating toward the center of procurement decisions across major vinyl supply chains. INEOS Group Ltd leverages integrated cracker-to-compound operations to secure feedstock traceability for medical-grade and construction-grade formulations. Westlake Vinnolit GmbH anchors its position through membrane-grade PVC specialization for roofing and waterproofing systems. Sylvin Technologies, Inc. competes on custom compound flexibility, serving regional extruders with rapid formulation turnaround.
Green polyvinyl chloride denotes vinyl resin produced with bio-based or recycled feedstock content, reduced plasticizer migration, and lower lifecycle carbon intensity measured against conventional petrochemical PVC. Manufacturing employs suspension polymerization with bio-ethylene or post-consumer mechanically recycled flake, yielding chlorine content near 57 percent by weight and Shore A hardness ranging from 70 to 95 depending on plasticizer load. Rigid PVC dominates volume in pipe and window profile applications where lead and cadmium stabilizer replacement has become standard. Flexible PVC formulations for flooring and medical tubing carry higher additive complexity and corresponding margin premiums. Recycled PVC feedstock streams face quality variability constraints that limit penetration in potable water and food-contact segments.
EPA toxicity evaluations under the Toxic Substances Control Act and REACH Annex XVII restrictions on phthalate plasticizers constrain formulation choices for US and European producers. China's GB standards and MEE environmental compliance inspections enforce emissions controls at chlor-alkali integrated PVC plants. California's Department of Toxic Substances Control Safer Consumer Products regulations and the EU Green Deal industrial emissions framework will determine which compounders retain market access. Stakeholders must monitor feedstock certification scheme maturation and regional carbon border adjustment mechanisms to align capacity investments with shifting compliance boundaries.
Market Dynamics
Phthalate-free formulation mandates are compressing legacy compounder margins while rewarding integrated producers with certified feedstock traceability systems. REACH Annex XVII restrictions and California DTSC Safer Consumer Products regulations are forcing rapid reformulation across medical tubing and flooring applications.
Growth Catalysts
- REACH Annex XVII phthalate restrictions:European compounders must eliminate DEHP, DBP, and BBP from childcare articles and medical devices, redirecting R&D spend toward bio-based plasticizer platforms.
- Retrofit infrastructure programs:Germany's building energy efficiency mandates and China's urban renewal investments are accelerating specification of low-carbon PVC window profiles and membrane roofing systems.
- Bio-ethylene feedstock commercialization:Brazilian sugarcane and European wood pulp-derived ethylene chains are achieving cost parity with naphtha routes in select coastal markets.
Market Restraints
- Chlor-alkali supply concentration:Electrolysis capacity for chlorine feedstock clusters along the US Gulf Coast and China's coal-rich provinces, exposing compounders to energy price volatility and carbon border adjustment risks.
- Post-consumer PVC quality variability:Mechanical recycling of window profiles and pipes yields inconsistent molecular weight distributions, excluding recycled content from potable water and food-contact applications.
- Epoxidized soybean oil plasticizer cost premium:Bio-based primary plasticizers trade at 15-40 percent above petrochemical alternatives, compressing margins in price-sensitive construction segments.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic chlor-alkali and VCM capacity expansion incentives could anchor regional green PVC compounding clusters for export to Southeast Asian infrastructure markets.
- Digital building material passports:Blockchain-tracked embodied carbon certificates are creating premium specification tiers for low-carbon PVC in European commercial real estate procurement.
- Medical device reshoring:FDA push for domestic critical supply chains is opening qualification pathways for US-based phthalate-free tubing compounders with validated cleanroom operations.
Industry Challenges
- Formulation chemist scarcity:Expertise in bio-based stabilizer synergies and recycled feedstock process control is concentrated among retiring specialists at legacy European compounders.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of USDA BioPreferred, EU Ecolabel, and Cradle to Cradle certifications requires 18-36 month validation cycles that delay product launches.
- Legacy extruder reconfiguration:Processing equipment optimized for lead-stabilized rigid PVC requires screw and die modifications to handle calcium-zinc or organotin stabilizer rheology without output loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Polyvinyl Chloride Market |
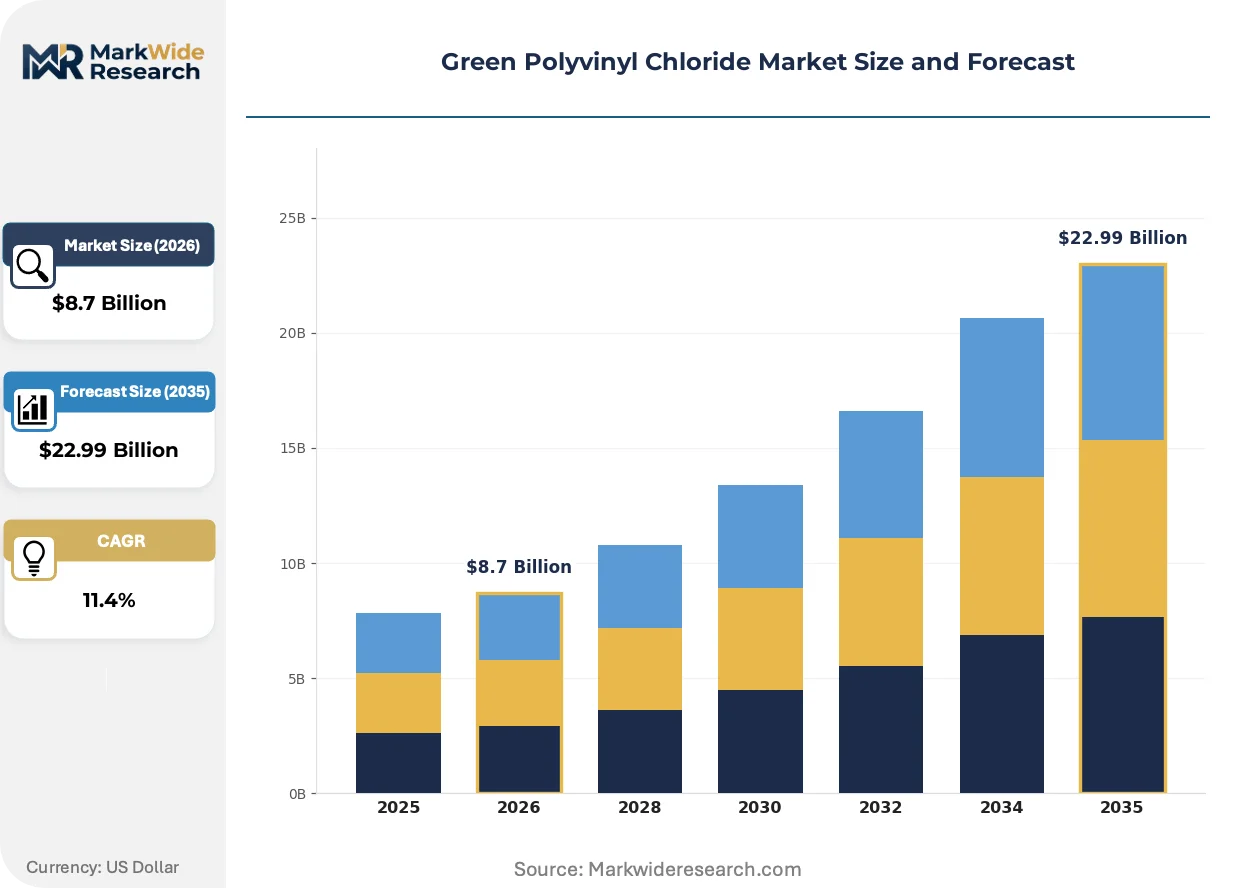
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, Specialty PVC, Blends End Use Industry: Building & Construction, Automotive, Electrical, Consumer Goods Formulation Type: Recycled PVC, Virgin PVC, Additive-Enhanced PVC, Composite PVC Application: Pipes, Flooring, Packaging, Coatings |
| Companies Covered | Formosa Plastics Corporation, INEOS Group Ltd, LG Chem Ltd, Westlake Vinnolit GmbH, Vynova Group, Sylvin Technologies, Inc., GEON, GERMANCARD Technologies GmbH, Goldstab Organics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Polyvinyl Chloride Market Shifts & Advancements
Suspension polymerization processes are splitting into dual-track systems optimized for either bio-ethylene or mechanically recycled feedstock, with equipment suppliers retrofitting reactors for rapid switching. This operational flexibility is becoming the decisive capability separating premium compounders from commodity producers.
Mass balance certification for bio-attributed PVC is bifurcating procurement tiers. Construction buyers in Germany and the Netherlands are mandating ISCC PLUS chain-of-custody documentation for public infrastructure tenders. Medical device OEMs in the United States are following with equivalent requirements for IV bags and tubing sets. The verification infrastructure is compressing spot-market volumes while expanding contracted premium supply relationships.
EPA toxicity evaluations under the Toxic Substances Control Act are accelerating substitution timelines for legacy plasticizers. The agency's systematic review of ortho-phthalates is forcing compounders to validate alternatives like DINCH and DOTP for pediatric exposure scenarios. Flooring and wallcovering segments are responding fastest, with major US retailers delisting non-compliant SKUs ahead of regulatory deadlines.
Specification authority is migrating from general contractors to institutional asset owners with net-zero commitments. University endowments and healthcare systems in California and New York are embedding embodied carbon thresholds directly into design briefs. This bypasses traditional distributor channels and forces direct technical collaboration between compounders and project sustainability consultants.
Green Polyvinyl Chloride Market Segmentation
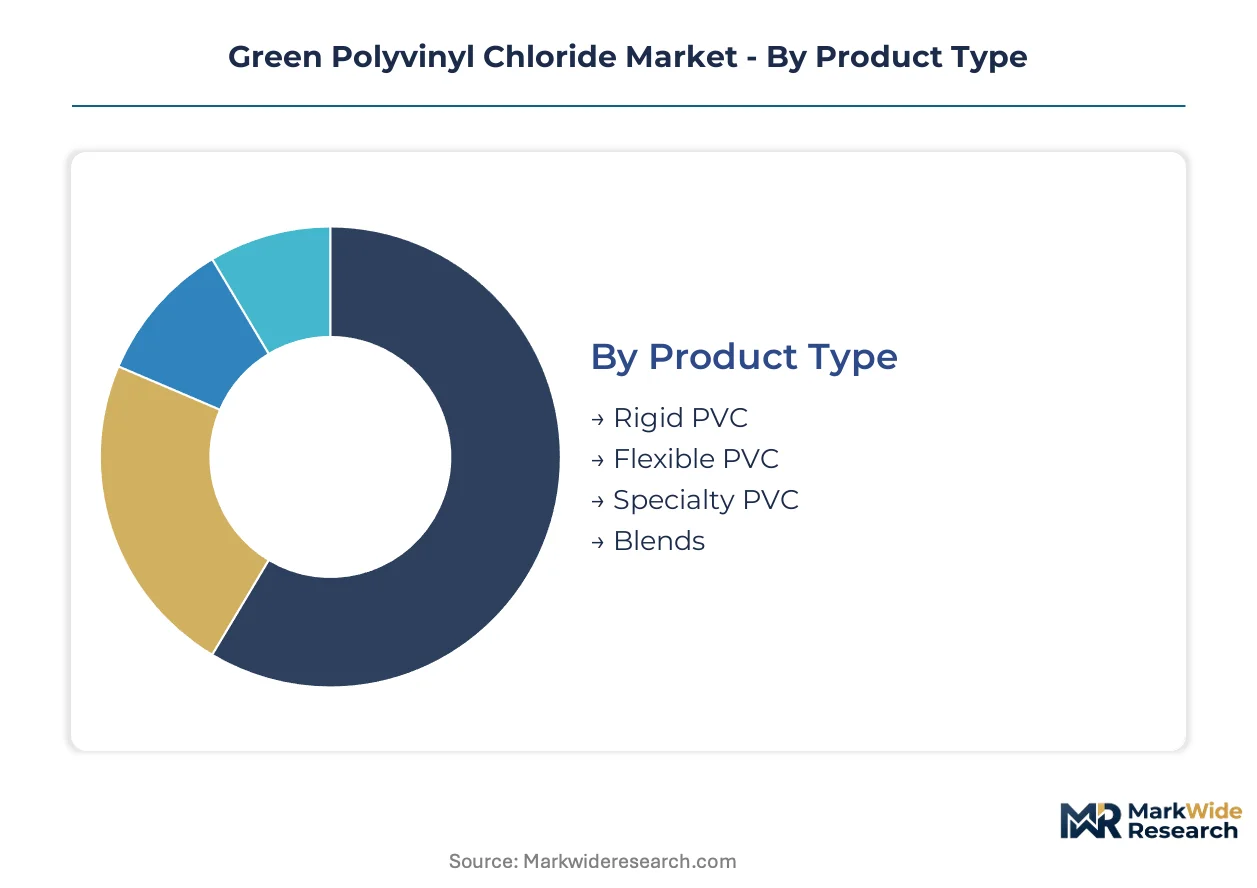
Segmentation in green PVC reveals how regulatory pressure and feedstock certification are fragmenting procurement tiers. Buyers now specify by carbon intensity thresholds and plasticizer chemistry rather than traditional performance grades alone.
Product Type:
REACH Annex XVII and California DTSC regulations enforce divergent compliance costs across material stiffness categories, reshaping compounder specialization.
- Rigid PVC:Formulations employ calcium-zinc or organotin stabilizers with near-zero phthalate content. Window profile and potable pipe specifications in Germany and the United States concentrate procurement here, driven by building energy retrofit mandates and lead replacement deadlines.
- Flexible PVC:Higher plasticizer loadings require bio-based alternatives like epoxidized soybean oil or DINCH to meet medical and childcare exposure limits. Flooring and medical tubing buyers in the Netherlands and California are consolidating supply relationships around ISCC PLUS certified compounders.
- Specialty PVC:Membrane-grade formulations for roofing systems carry exacting molecular weight controls.
- Blends:Alloyed with ABS or acrylic modifiers for impact-critical automotive interior applications.
Established volume favors Rigid PVC; emerging adoption favors Flexible PVC.
End Use Industry:
Customer procurement authority is migrating from distributors toward asset owners with embodied carbon accounting systems.
- Building & Construction:Rigid profiles and membrane systems dominate. Germany's building energy efficiency mandates and China's urban renewal programs are accelerating specification of low-carbon window frames and waterproofing systems with mass balance certification.
- Automotive:Interior trim and wiring insulation formulations face dual pressure from EU ELV directives and OEM net-zero commitments.
- Electrical:Cable jacketing requires flame-retardant plasticizer packages with restricted halogen content.
- Consumer Goods:Toys and food-contact applications face the strictest migration limits under REACH and FDA jurisdiction.
Building & Construction commands current volume; Automotive represents the steepest expansion trajectory as electrification reshapes material specifications.
Formulation Type:
Feedstock traceability infrastructure is bifurcating supply tiers between certified and uncertified compounders.
- Recycled PVC:Post-consumer window profile and pipe flake feedstocks face molecular weight variability constraints. Mechanical recycling output serves secondary construction and non-potable drainage in Germany and the United States where quality tolerance permits.
- Virgin PVC:Suspension polymerization from bio-ethylene or naphtha feedstocks retains potable water and food-contact access.
- Additive-Enhanced PVC:Custom stabilizer and plasticizer packages for medical device OEMs.
- Composite PVC:Mineral-filled formulations for cost-sensitive siding and fencing applications.
Virgin PVC retains premium specification access; Recycled PVC is gaining share fastest as mass balance certification matures.
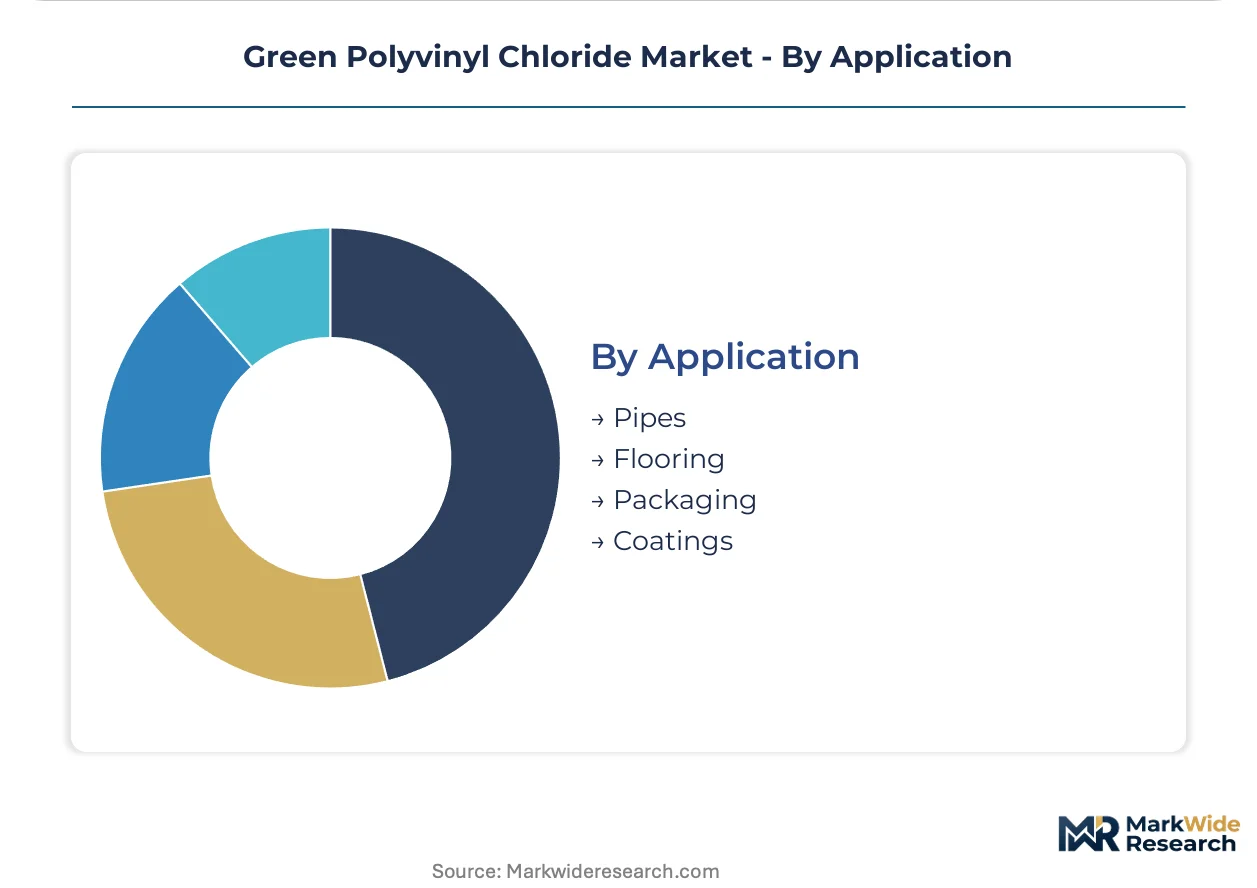
Application:
Processing equipment legacy and reformulation costs are segmenting competitive intensity by end-use conversion technology.
- Pipes:Potable water pressure pipe specifications exclude recycled content due to molecular weight consistency requirements. AWWA and DVGW certification in the United States and Germany maintains virgin PVC dominance.
- Flooring:Heterogeneous and homogeneous sheet formulations are rotating fastest toward phthalate-free plasticizer systems under retailer compliance pressure.
- Packaging:Blister packs and shrink film face lightweighting competition from PET and PLA.
- Coatings:Plastisol applications for dip-molded gloves and tool handles.
Pipes anchor current revenue concentration; Flooring is climbing the fastest as renovation cycles accelerate specification turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export membrane-grade formulations to Dutch infrastructure contractors, while Chinese producers supply recycled-content PVC to Southeast Asian retrofit programs. This trade-flow pattern concentrates procurement authority in countries with mature certification infrastructure and aggressive building decarbonization timelines.
Germany
Building energy retrofit mandates and public infrastructure tenders drive specification of low-carbon window profiles. REACH Annex XVII enforces phthalate elimination in childcare articles and medical devices. The Rhine-Ruhr industrial corridor hosts integrated chlor-alkali-to-compound operations serving membrane roofing systems for commercial real estate.
United States
State-level green building codes in California and federal infrastructure investment accelerate demand for lead-free rigid formulations. EPA toxicity evaluations under the Toxic Substances Control Act compress substitution timelines for legacy plasticizers. Gulf Coast chlorine production clusters expose compounders to energy price volatility and carbon border adjustment exposure.
China
Urban renewal investments and dual carbon goals scale procurement of low-emission PVC for window frames and waterproofing. GB standards and MEE environmental compliance inspections enforce emissions controls at integrated chlor-alkali plants. Yangtze River Delta chemical parks concentrate suspension polymerization capacity with bio-ethylene feedstock trials.
India
PLI scheme incentives for specialty chemicals attract domestic chlor-alkali and VCM capacity expansion. BIS standards for construction materials create compliance pathways for recycled-content formulations. Gujarat's chemical manufacturing belt anchors emerging compounding clusters targeting Southeast Asian infrastructure export markets.
Netherlands
Mass balance certification requirements for public tenders concentrate procurement around ISCC PLUS verified compounders. EU Green Deal industrial emissions frameworks determine market access for imported formulations. Rotterdam's port infrastructure facilitates bio-ethylene feedstock imports from Brazilian sugarcane supply chains.
Green Polyvinyl Chloride Market Competitive Landscape
Listed leaders compete with private specialists across feedstock traceability and formulation flexibility dimensions. The vendor base splits between integrated petrochemical majors with cracker-to-compound control and regional compounders serving rapid-turnaround custom orders. Three archetypes dominate: integrated producers with certified supply chains, membrane-grade specialists with exacting molecular weight capabilities, and flexible compounders with short-run customization capacity. Competitive moves concentrate on mass balance certification acquisition and retrofit of suspension polymerization reactors for dual-track bio-ethylene and recycled feedstock processing.
Within the integrated producer tier, INEOS Group Ltd and Westlake Vinnolit GmbH exemplify archetypes differentiated by operational scope. INEOS anchors positions through captive chlorine and ethylene integration, while Westlake Vinnolit occupies membrane-grade specialization for roofing and waterproofing systems. Sylvin Technologies, Inc. represents the flexible compounder archetype, serving regional extruders with rapid formulation turnaround rather than commodity volume scale. These three companies collectively illustrate how certification infrastructure and reactor flexibility separate premium supply tiers from spot-market commodity producers.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| INEOS Group Ltd |
| LG Chem Ltd |
| Westlake Vinnolit GmbH |
| Vynova Group |
| Sylvin Technologies, Inc. |
| GEON |
| GERMANCARD Technologies GmbH |
| Goldstab Organics Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Integrated chlor-alkali capacity utilization above 85 percent across the US Gulf Coast and China's coal-rich provinces anchors price floors for vinyl compounders while compressing margins at non-integrated regional operators. This scale concentration forces smaller compounders to absorb feedstock volatility or exit premium specification tiers where mass balance certification commands persistent premiums.
Pricing Analysis
Legacy lead-stabilized rigid formulations trade at the bottom tier, calcium-zinc and organotin-stabilized mid-grade compounds occupy the standard band, and ISCC PLUS-certified bio-attributed flexible grades with DINCH or epoxidized soybean oil plasticizers sit at the premium apex. Price differentiation separates certified from uncertified supply tiers, with mass balance documentation adding 12-18 percent to compound valuations in German public tenders. Cost compression in standard-grade rigid PVC is intensifying as Chinese suspension polymerization capacity expands and European energy costs reset. Flooring distributors and medical device OEMs show least price sensitivity, while residential construction extruders in price-sensitive US Sun Belt markets resist premium tier migration.
Supply Chain Analysis
Strategic stockpiling of chlorine and VCM feedstock dominates procurement behavior among integrated producers, while regional compounders run lean just-in-time inventories exposed to spot-market volatility. Supply concentrates in the United States, China, and Germany, with the Yangtze River Delta, US Gulf Coast, and Rhine-Ruhr corridor anchoring global suspension polymerization output. Raw material dependencies center on chlorine from membrane-cell electrolysis, ethylene from naphtha cracking or bio-ethylene pilot streams, and specialized plasticizers from adipic acid or soybean oil epoxidation. Single-source vulnerability runs through chlor-alkali capacity clustered in energy-price-exposed regions. Distribution runs through distributor networks serving regional extruders, with certified compounders building direct technical relationships with institutional asset owners and medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority migration toward asset owners with embodied carbon accounting systems creates platform-economics dynamics where feedstock certification interoperability determines market access. Compounders must treat mass balance verification infrastructure as the core platform layer upon which premium customer relationships are built.
For Market Incumbents: Secure captive chlorine and ethylene integration or long-term offtake agreements with Gulf Coast and Yangtze River Delta producers to defend against feedstock cost volatility. Accelerate ISCC PLUS and EU Ecolabel certification acquisition before multi-jurisdiction validation timelines extend beyond 24 months. Capacity addition in Gujarat's chemical belt under India's PLI scheme offers geographic diversification against carbon border adjustment exposure in European markets. For New Entrants and Emerging Players: Rapid formulation turnaround for regional extruders represents the most penetrable service layer where INEOS and Westlake Vinnolit maintain limited flexibility. Target medical tubing compounders in the US Southeast where FDA reshoring initiatives and phthalate-free mandates create qualification windows for cleanroom-capable newcomers. Go-to-market leverage rests on 48-hour custom stabilizer package development and direct technical service to mid-size extruders bypassing distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with multi-year supply agreements to medical device OEMs and institutional construction asset owners, insulating against spot-market cyclicality. Long-term viability over the next decade favors targets with dual-track suspension polymerization reactors capable of switching between bio-ethylene and recycled feedstock. The signal to watch is ISCC PLUS certificate issuance velocity in the Netherlands and Germany, which predicts premium tier supply contract availability 12-18 months forward.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Capacity | Captive chlorine supply from US Gulf Coast electrolysis insulates compounders from energy price spikes and carbon border adjustments. |
| Mass Balance Certification Acquisition | ISCC PLUS verification unlocks German public infrastructure tenders and Dutch commercial real estate procurement with embodied carbon thresholds. |
| Dual-Track Reactor Retrofit | Suspension polymerization equipment capable of rapid bio-ethylene and recycled feedstock switching separates premium compounders from commodity producers. |
| Medical Device Cleanroom Qualification | FDA-compliant phthalate-free tubing production captures reshoring demand from IV bag and infusion set OEMs. |
| Regional Compounding Cluster Expansion | Gujarat-based capacity under India's PLI scheme targets Southeast Asian infrastructure export markets with lower-cost certified formulations. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings from petrochemical majors, and ECHA REACH registration dossiers preceded structured interviews with suspension polymerization plant managers, procurement leads at window profile and flooring OEMs, and technical R&D directors at compounders. Primary fieldwork with distribution channel partners and sustainability consultants at institutional asset owners validated feedstock certification demand signals. Secondary triangulation drew from chlor-alkali industry association reports and building materials trade flow data. Bottom-up volume estimates across product type, formulation, and application segments were cross-checked against top-down macroeconomic indicators and construction investment forecasts.
Variance decomposition separated volume growth drivers from price mix effects across the projection horizon. Segmentation modeling incorporated rigid versus flexible grade tiers, virgin versus recycled feedstock sourcing, and end-use industry carbon intensity thresholds. CAGRs were derived from fitted growth curves calibrated to historical retrofit program deployment rates and regulatory phase-in schedules. Industry-specific inputs included chlor-alkali capacity utilization rates and bio-ethylene cost parity trajectories in coastal European markets.
Forecasts assume regulatory continuity in REACH Annex XVII, California DTSC Safer Consumer Products, and China's GB standards enforcement; material policy shifts would require re-modeling substitution timelines and certification scheme recognition. Forecasts reflect assumptions about feedstock certification scheme maturation and carbon border adjustment implementation scope. Revision becomes warranted when bio-ethylene cost parity crosses naphtha-derived ethylene thresholds in three or more major demand centers simultaneously.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
US Plastics Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market