
 Americas Plastic Sheets Market | 2026-2036
Americas Plastic Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Plastic Sheets Market Outlook
Packaging converters are collapsing their historical dependence on thin-gauge polystyrene for food clamshells as brand owners pivot toward polyethylene and PET alternatives. Dow sustains massive resin-to-sheet integration along the US Gulf Coast, capturing margin from monomer through extrusion. Plaskolite dominates the North American signage and lighting panel segment with continuous cast acrylic capacity. LyondellBasell Industries Holdings B.V. leverages its polypropylene and polyethylene resin position to supply captive sheet extruders across the Midwest and Southeast.
Americas plastic sheets are flat or extruded thermoplastic panels, typically ranging from 0.010 inches to over 2 inches in thickness, produced through calendering, extrusion, or casting processes for structural, protective, or optical applications. Polyethylene sheet leads volume in construction vapor barriers and agricultural mulch films due to its chemical resistance and low cost, while polycarbonate commands premium positioning in ballistic glazing and LED light diffusers where impact strength and optical clarity matter. PVC sheet occupies a mature but stable niche in chemical-resistant tank linings and outdoor signage, with margin pools concentrating in custom-colored and textured formulations rather than commodity grades.
The US EPA regulates volatile organic compound emissions from extrusion operations under Clean Air Act standards, while OSHA mandates workplace exposure limits for vinyl chloride monomer in PVC sheet plants. Mexico's environmental authority enforces NOM standards on industrial emissions that affect cross-border maquiladora sheet converters. Stakeholders must monitor how California's SB 54 recycled content mandates and pending federal Extended Producer Responsibility legislation reshape resin specifications and extruder capital allocation decisions.
Market Dynamics
Integrated resin-to-sheet production along the US Gulf Coast petrochemical corridor is compressing logistics costs and capturing margin from monomer through extrusion, forcing independent converters to consolidate or exit commodity grades.
Growth Catalysts
- Recycled content mandates:California's SB 54 and pending federal Extended Producer Responsibility legislation are pulling converters toward post-consumer feedstock specifications. Brand owners across food packaging and consumer goods are accelerating specifications for certified recycled sheet.
- Construction sector expansion:Brazilian and Mexican contractors are scaling orders for polycarbonate roofing panels in commercial and agricultural buildings. Climate resilience requirements in hurricane-prone zones are boosting impact-resistant glazing specifications.
- LED diffusion applications:Continuous cast acrylic and polycarbonate sheet is capturing share in architectural lighting and automotive interior panels. Optical clarity grades command premium positioning over commodity extruded alternatives.
Market Restraints
- Feedstock volatility:Ethylene and propylene monomer prices swing with crude oil and natural gas liquid benchmarks, squeezing extruder margins on fixed-price construction contracts. Gulf Coast resin producers pass through costs faster than sheet converters can renegotiate.
- Single-source supply risk:Specialty polycarbonate sheet for ballistic and aerospace applications concentrates among three North American producers. Any force majeure event at a primary optical-grade facility disrupts downstream LED and security glazing supply chains.
- Thin-gauge polystyrene displacement:Food clamshell converters face stranded asset risk as polyethylene and PET alternatives capture quick-serve restaurant and grocery packaging specifications. Styrene monomer emissions scrutiny compounds the technical obsolescence pressure.
Strategic Opportunities
- Underpenetrated Mexican industrial sheet:Cross-border maquiladora converters serving automotive and appliance OEMs lack domestic optical-grade polycarbonate supply. NOM emissions compliance investments create first-mover advantage for integrated extruders.
- Agricultural mulch film specification:Biodegradable polyethylene sheet formulations are opening replacement cycles for conventional mulch in California's Central Valley and Florida's vegetable belt. Soil health regulations are accelerating field trials.
- Digital printing substrate convergence:Rigid PVC and acrylic sheet specifications are merging for wide-format signage as UV-curable ink adhesion improves. Print-service-providers are consolidating vendor bases to reduce substrate inventory complexity.
Industry Challenges
- Extrusion operator certification gaps:OSHA vinyl chloride monomer exposure protocols and EPA Clean Air Act compliance require specialized training that community colleges and trade programs have not scaled to match Gulf Coast plant expansions.
- Recycled feedstock quality variance:Post-consumer polyethylene stream contamination creates lot-to-lot extrusion instability. Converters must invest in optical sorting and melt filtration that commodity sheet margins rarely support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Plastic Sheets Market |
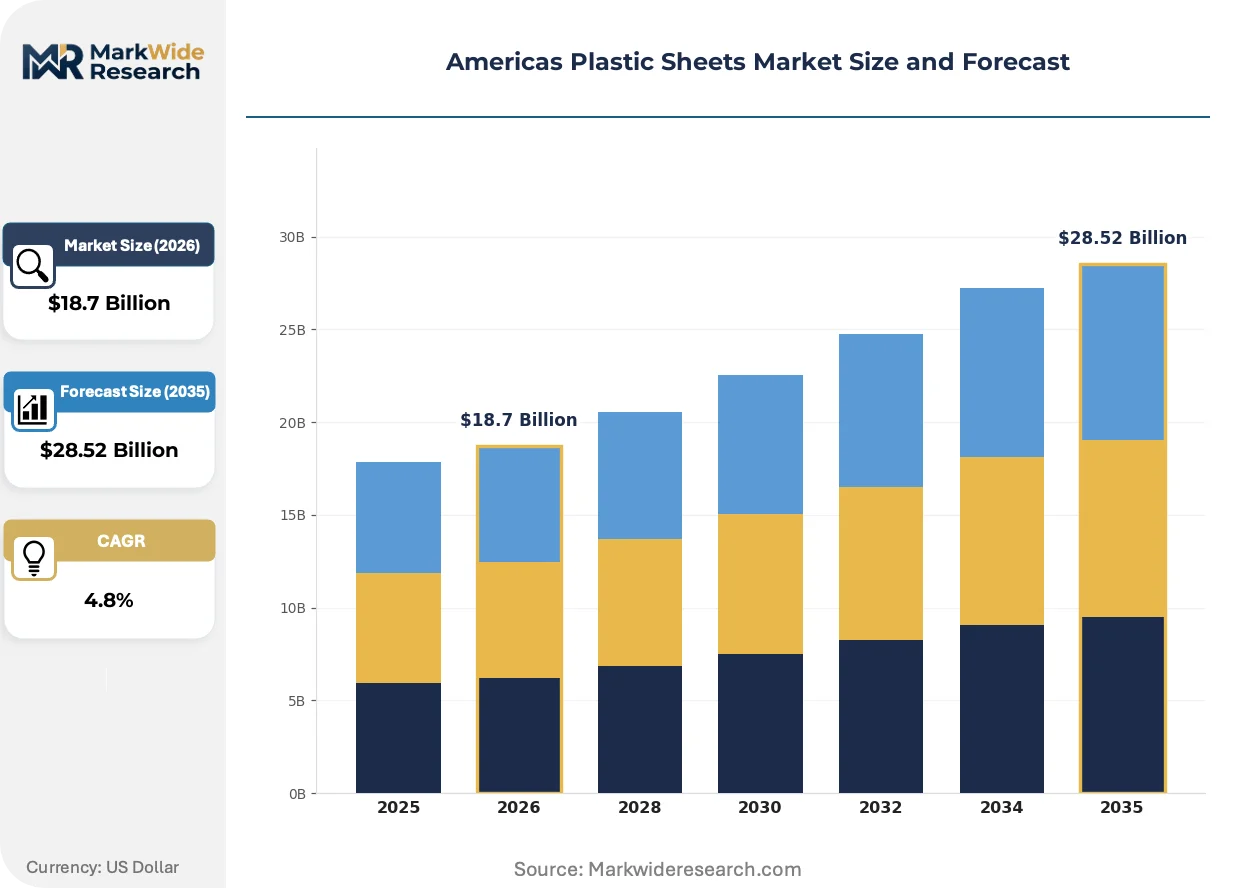
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polycarbonate, Polystyrene, PVC Application: Construction, Packaging, Automotive, Signage End User: Manufacturers, Retailers, Contractors, Distributors Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | A&C Plastics, Inc., Dow, LyondellBasell Industries Holdings B.V., Plaskolite, Seiler Plastics Corporation, United States Plastic Corporation, A-Pac Manufacturing Co., Inc., Penn Fibre, Inc., Acrilex Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Plastic Sheets Market Strategic Shifts
Coextrusion and digital surface finishing technologies are fragmenting the traditional commodity-specialty divide, enabling mid-tier extruders to capture application-specific premiums without captive resin production.
Multilayer coextrusion is displacing monolithic sheet in automotive interior panels and medical device packaging. Tier-one suppliers are specifying barrier-layer combinations of polyethylene and ethylene vinyl alcohol for moisture and oxygen protection. The technology is displacing adhesive lamination processes that required secondary converting steps and generated solvent waste streams.
California's SB 54 recycled content mandates are forcing resin specification changes across food-contact sheet applications. The state's environmental agency is enforcing phased minimums for post-consumer material in single-use packaging. Brand owners are responding by consolidating supplier qualifications around converters with certified mechanical recycling partnerships and third-party chain-of-custody documentation.
Buyer consolidation among national retail and foodservice chains is compressing supplier bases and extending contract durations. Procurement teams are demanding volume commitments across multiple sheet grades in exchange for sole-source or dual-source status. This pattern is most visible in the quick-serve restaurant segment, where three national chains now specify continent-wide single-source agreements for clamshell and tray applications.
Americas Plastic Sheets Market Segmentation
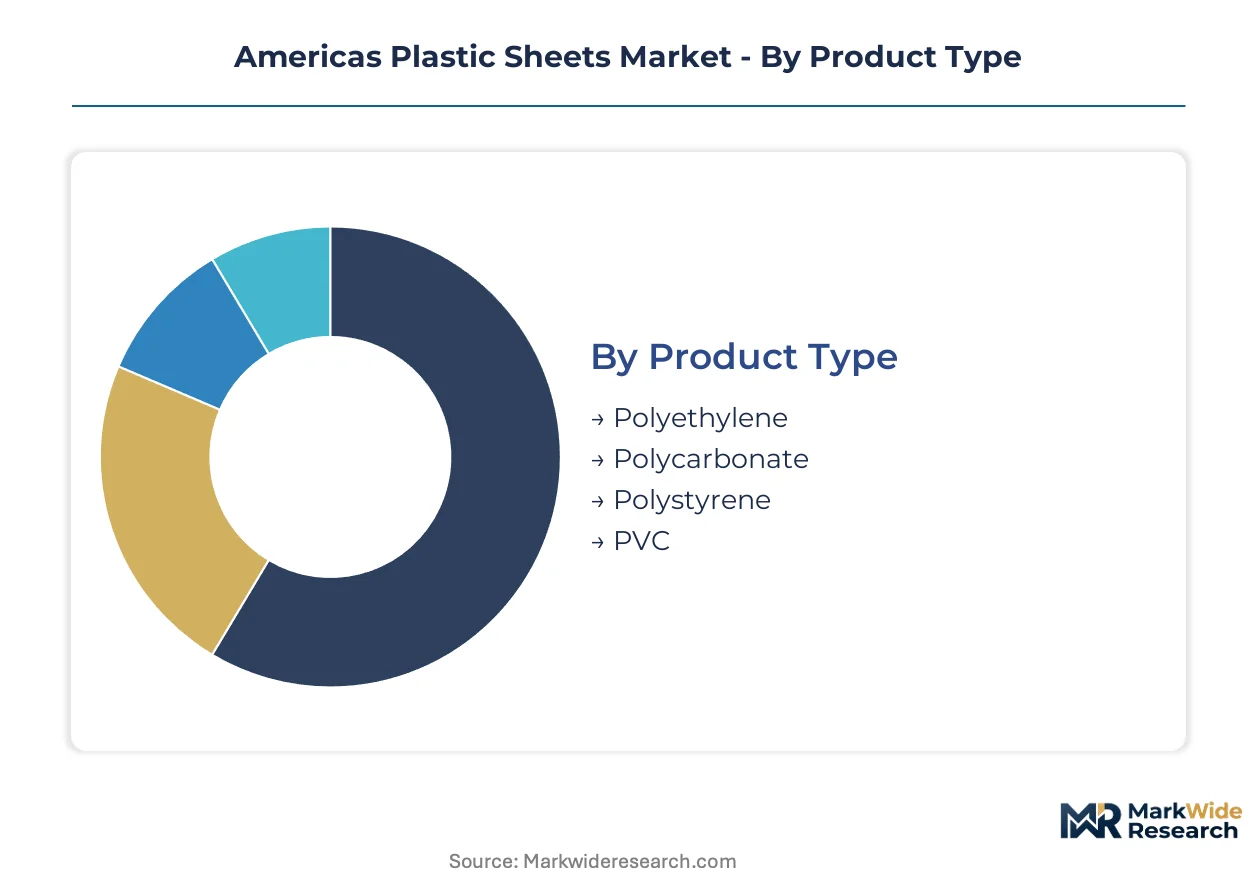
Americas plastic sheets demand fragments across resin chemistries, end-use specifications, and supply chain roles that each carry distinct margin profiles and regulatory exposure. Understanding these segment boundaries clarifies where integrated producers capture value versus where independent converters face commoditization pressure.
Product Type:
Polyethylene dominates domestic production volumes tied to Gulf Coast resin integration, while polycarbonate and specialty grades sustain export flows to Mexican and Brazilian industrial users.
- Polyethylene:Low-density and linear low-density formulations serve construction vapor barriers and agricultural mulch films. Demand concentrates in California's Central Valley and Florida's vegetable belt where soil health regulations are accelerating field trials for biodegradable alternatives.
- Polycarbonate:Optical clarity grades command premium positioning in LED light diffusers and ballistic glazing applications. Brazilian and Mexican contractors are scaling orders for roofing panels in commercial and agricultural buildings as climate resilience requirements tighten.
- Polystyrene:Thin-gauge sheet faces displacement as food clamshell converters pivot toward polyethylene and PET alternatives. Styrene monomer emissions scrutiny compounds technical obsolescence pressure from quick-serve restaurant procurement teams.
- PVC:Rigid and foamed formulations occupy mature niches in chemical-resistant tank linings and outdoor signage, with margin pools concentrating in custom-colored and textured grades rather than commodity extrusion.
Polyethylene holds the largest share; momentum sits with polycarbonate as LED diffusion and impact glazing specifications expand.
Application:
Construction and packaging applications diverge sharply in customer concentration, contract duration, and recycled content compliance burden.
- Construction:Vapor barriers, roofing panels, and temporary protective sheeting drive bulk volume. Hurricane-prone zones from Florida to the Gulf Coast are boosting impact-resistant polycarbonate glazing specifications in commercial building codes.
- Packaging:Food clamshells, medical trays, and retail blister packs dominate. California's SB 54 mandates are pulling converters toward post-consumer feedstock specifications with certified mechanical recycling partnerships.
- Automotive:Interior panels and lighting diffusers specify multilayer coextruded sheet with barrier-layer combinations. Tier-one suppliers are consolidating vendor bases around converters with optical-grade consistency.
- Signage:Continuous cast acrylic and rigid PVC serve wide-format digital printing substrates. UV-curable ink adhesion improvements are merging specifications and reducing print-service-provider inventory complexity.
Construction generates the highest volume throughput; packaging is gaining share fastest as recycled content mandates reshape resin specifications.
End User:
Direct procurement patterns split between specification-setting OEMs and price-sensitive distribution intermediaries.
- Manufacturers:Appliance, automotive, and medical device OEMs dictate tight thickness tolerances and lot traceability. These buyers are extending contract durations and demanding volume commitments across multiple sheet grades.
- Contractors:Brazilian and Mexican commercial builders order polycarbonate roofing panels through regional distribution. Climate resilience requirements in hurricane zones are shifting specifications toward impact-resistant grades.
- Retailers:National quick-serve chains and grocery consolidators now specify continent-wide single-source agreements for clamshell and tray applications, compressing supplier bases.
- Distributors:Independent stocking distributors serve fragmented sign shops and small construction contractors, capturing margin from inventory availability rather than technical specification.
Manufacturers command the most demanding specifications; retailers are consolidating purchasing power fastest through national account structures.
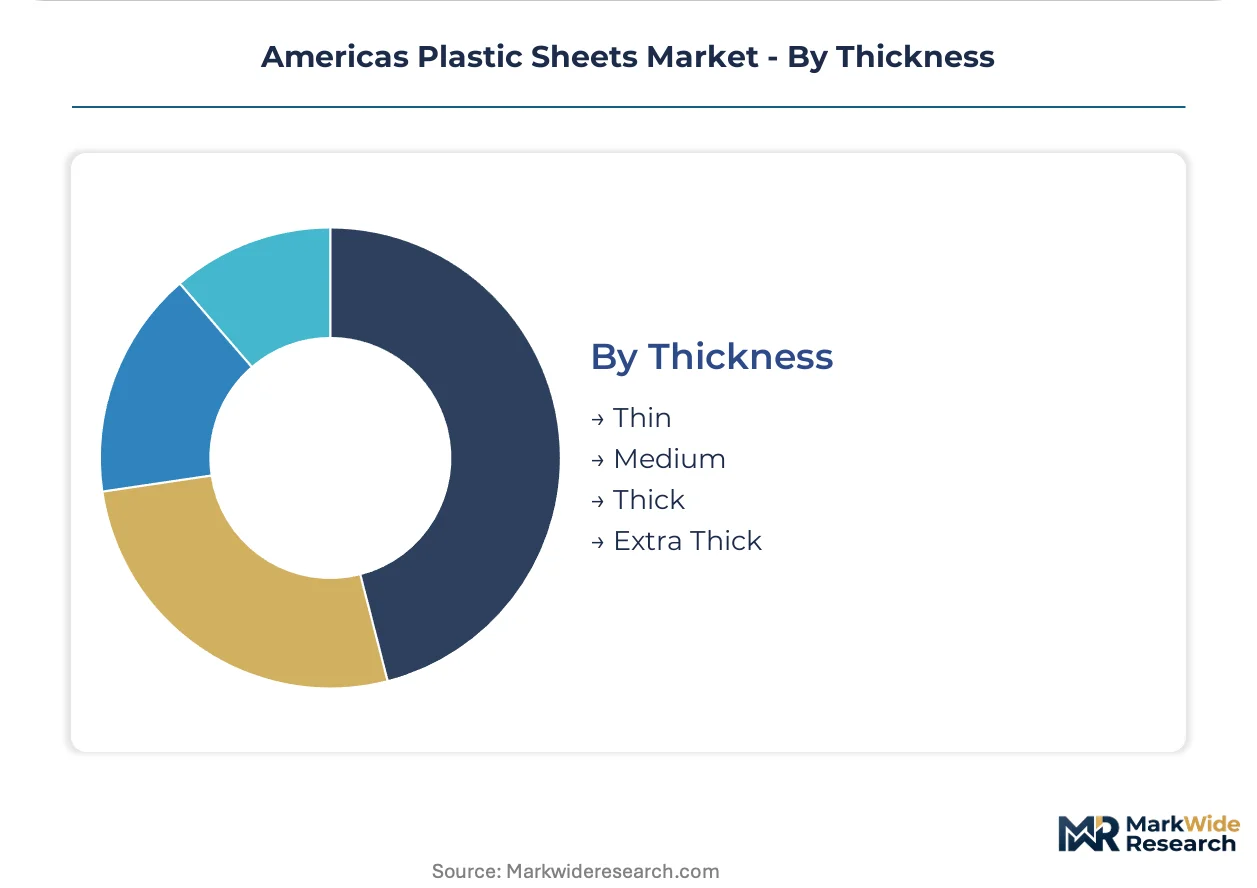
Thickness:
Thickness categories map directly to production process economics and end-use performance requirements.
- Thin:Below 0.030 inches serves food packaging clamshells and disposable medical trays. This segment faces the steepest displacement risk as brand owners abandon polystyrene for polyethylene and PET alternatives.
- Medium:0.030 to 0.125 inches captures signage, interior automotive panels, and appliance liners. Coextrusion technology is enabling barrier-layer combinations that displace adhesive lamination.
- Thick:0.125 to 0.500 inches serves construction vapor barriers, tank linings, and protective glazing. Gulf Coast integrated producers capture margin through captive resin supply.
- Extra Thick:Above 0.500 inches includes ballistic glazing, LED light diffusers, and architectural roofing panels. Specialty polycarbonate sheet for these applications concentrates among limited North American producers, creating single-source supply risk.
Medium thickness holds the broadest application base; extra thick is climbing the fastest as optical and security specifications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican sheet extruders export polycarbonate roofing panels to Brazilian contractors while Gulf Coast resin producers supply integrated sheet operations across the southern United States. Cross-border maquiladora clusters serve automotive OEMs with medium-gauge formulations.
United States
Construction contractors in Florida and the Gulf Coast specify impact-resistant polycarbonate glazing for hurricane resilience in commercial building codes. EPA Clean Air Act standards regulate volatile organic compound emissions from extrusion operations in Texas and Louisiana. The Houston-Beaumont petrochemical corridor hosts integrated resin-to-sheet production that captures margin from ethylene monomer through finished panel extrusion.
Brazil
Commercial builders and agricultural operators scale orders for polycarbonate roofing panels as climate adaptation requirements tighten in São Paulo and Rio de Janeiro states. ANVISA regulates food-contact sheet applications for packaging converters serving domestic consumer goods markets. The São Paulo industrial belt concentrates extrusion capacity for signage and construction applications serving Mercosur trade flows.
Mexico
Cross-border maquiladora converters supply automotive interior panels and appliance liners to OEMs in Nuevo León and the Bajío Region. NOM standards on industrial emissions affect sheet extrusion operations in Mexico City Metro and northern border states. Querétaro and Guanajuato host expanding extrusion capacity for optical-grade polycarbonate lacking domestic supply.
Canada
Construction vapor barrier specifications in Ontario and British Columbia drive polyethylene sheet demand for residential and commercial building envelopes. Health Canada and PMRA regulate agricultural mulch film formulations in the Prairie Provinces. The Alberta petrochemical corridor supplies resin feedstock to independent converters in Calgary and Edmonton serving western Canadian distribution networks.
Americas Plastic Sheets Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive resin supply and independent regional extruders serving niche specifications. Gulf Coast resin producers capture margin through backward integration into sheet extrusion, compressing logistics costs and displacing commodity-grade independents. Strategic archetypes include integrated resin-to-sheet operators, specialty optical-grade producers, and regional distribution-focused extruders. Dominant competitive moves involve capacity consolidation in polycarbonate optical grades and strategic partnerships for certified recycled feedstock access.
Among integrated petrochemical operators, Dow and LyondellBasell Industries Holdings B.V. represent the resin-captive archetype with Gulf Coast extrusion presence. Plaskolite occupies a position within specialty acrylic and polycarbonate sheet for signage and lighting applications. These three entities exemplify how scale and feedstock integration separate premium-tier positioning from commodity-grade pressure.
| Leading Market Players |
|---|
| A&C Plastics, Inc. |
| Dow |
| LyondellBasell Industries Holdings B.V. |
| Plaskolite |
| Seiler Plastics Corporation |
| United States Plastic Corporation |
| A-Pac Manufacturing Co., Inc. |
| Penn Fibre, Inc. |
| Acrilex Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-day resin inventory cycles along the US Gulf Coast petrochemical corridor concentrate pricing power among integrated producers who convert ethylene monomer directly into extruded sheet. This lead-time compression locks independent converters into spot resin exposure while backward-integrated operators capture margin stability through captive feedstock.
Pricing Analysis
Extrusion-generation pricing gaps separate continuous cast optical-grade polycarbonate from commodity extruded polyethylene sheet. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with optical clarity commanding substantial premiums over construction-grade formulations. Pricing pressure stems from ethylene monomer volatility that Gulf Coast resin producers pass through faster than sheet converters can renegotiate fixed-price construction contracts. Quick-serve restaurant procurement teams exhibit highest price sensitivity as they consolidate continent-wide single-source agreements.
Supply Chain Analysis
Inventory concentration in Texas and Louisiana feeds extrusion operations serving construction and packaging converters across the southern United States. Raw material flows draw from Gulf Coast ethylene crackers, imported polycarbonate resin, and post-consumer recycled polyethylene streams. Single-source vulnerability concentrates in specialty optical-grade polycarbonate where three North American producers serve ballistic glazing and LED diffuser applications. Distribution runs through integrated resin-to-sheet operators, regional stocking distributors, and direct mill relationships with national retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national quick-serve chains and grocery retailers who now specify continent-wide single-source agreements, compressing supplier bases and extending contract durations across packaging converters.
For Market Incumbents: Secure certified mechanical recycling partnerships to meet California SB 54 post-consumer feedstock mandates before brand owners disqualify uncertified suppliers. Defend margin position by expanding continuous cast acrylic capacity in optical-grade lighting applications where Plaskolite's dominance creates scarcity value. Channel control through direct mill relationships with national retail chains reduces distributor margin leakage.
For New Entrants and Emerging Players: Differentiate on biodegradable polyethylene mulch film formulations for California Central Valley vegetable growers facing soil health regulations. Target cross-border maquiladora converters in Querétaro and Guanajuato lacking domestic optical-grade polycarbonate supply. Go-to-market through NOM emissions compliance investments that create first-mover advantage over US competitors facing tariff uncertainty.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates divesting non-core sheet extrusion assets as they prioritize resin production. Long-term viability favors converters with backward integration into Gulf Coast resin supply or certified recycling partnerships. Watch for inflection when federal Extended Producer Responsibility legislation triggers stranded asset risk among thin-gauge polystyrene specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast ethylene crackers supply captive sheet extrusion, compressing logistics costs and margin volatility. |
| Certified Recycling Partnership | Mechanical recycling chain-of-custody documentation qualifies converters for California SB 54 food-contact specifications. |
| Optical-Grade Capacity Expansion | Continuous cast polycarbonate and acrylic lines serve LED diffusion and ballistic glazing premium segments. |
| Cross-Border Maquiladora Investment | NOM-compliant extrusion capacity in northern Mexico captures automotive OEM specification-setting power. |
| Biodegradable Formulation Development | Soil-health-compliant mulch films open replacement cycles in California and Florida agricultural belts. |
Study Parameters
A standing panel of sheet extrusion plant managers, procurement leads at food packaging OEMs, distribution channel partners, and EPA compliance officers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against customs trade data, ACC industry reports, SEC 10-K resin producer filings, and state environmental agency enforcement records. Bottom-up volume triangulation from extruder capacity utilization crossed with top-down resin consumption data to anchor segmentation splits.
Consistency checks validated volume and value outputs against external benchmarks including regional construction spending indices, automotive production databases, and retail packaging procurement disclosures. The analytical framework modeled demand across resin chemistry, thickness category, end-use application, and regional production hub throughout the forecast period. CAGRs were derived from segment-level growth drivers including recycled content mandate compliance, LED diffusion specification expansion, and hurricane resilience building code adoption.
Material uncertainties — feedstock price volatility, force majeure events at optical-grade facilities, and federal EPR legislation timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and brand owner specification migration that could accelerate or delay segment shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Plastic Pellets Market