
 BPA Free Plastic Market | 2026-2036
BPA Free Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
BPA Free Plastic Market Analysis
Aftermarket resin formulation services is tilting toward certified BPA-free compound development as brand owners internalize compliance risk. Eastman Chemical Company leverages its Tritan copolyester portfolio to anchor premium medical device contracts. BASF SE sustains R&D intensity in bio-based polypropylene alternatives. Dow Inc. competes through backward integration into propylene feedstock and North American manufacturing scale.
BPA free plastic denotes thermoplastic formulations manufactured without bisphenol A monomer, typically achieving glass transition temperatures between 70°C and 150°C depending on base polymer and intended sterilization compatibility. These materials serve food-contact, medical, and consumer goods applications where endocrine disruption concerns restrict conventional polycarbonate or epoxy resin use. Food packaging leads volume demand within the end use industry dimension, while medical devices captures the highest margin pool due to USP Class VI and ISO 10993 biocompatibility certification requirements. Polyethylene dominates tonnage within the material dimension, though polycarbonate alternatives command pricing premiums in optical and high-heat segments.
FDA food contact substance notifications and ECHA REACH restrictions on bisphenol A in thermal paper and food-contact articles are reshaping formulation mandates across export-oriented suppliers. The EU F-Gas Regulation and national extended producer responsibility frameworks in France and Germany are adding compliance layers beyond material safety alone. Stakeholders must monitor regulatory divergence between FDA notification pathways and EU MDR requirements for medical device polymers, as dual-certification costs will determine which compounders retain cross-Atlantic supply relationships.
Market Dynamics
REACH restrictions on bisphenol A in food-contact articles and thermal paper are forcing compounders to reformulate entire product lines, creating a supply bottleneck for certified alternatives as brand owners scramble to meet ECHA compliance deadlines.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases in refrigeration and air conditioning is redirecting equipment manufacturers toward BPA-free polymer linings and seals that withstand alternative refrigerant chemistries.
- Medical device sterilization:Gamma and steam sterilization protocols for USP Class VI certified components are expanding demand for heat-stable copolyesters in surgical instruments and diagnostic housings.
- German retail procurement:Extended producer responsibility frameworks and consumer preference for certified-safe packaging are concentrating volume demand through centralized purchasing desks of major supermarket chains.
Market Restraints
- Propylene feedstock volatility:Crude oil and natural gas liquid price swings directly compress margins for polypropylene compounders serving price-sensitive food packaging segments.
- Optical-grade copolyester concentration:Production of high-clarity alternatives to polycarbonate remains concentrated among specialized resin formulators with captive monomer supply, limiting second-source options.
- Epoxy resin substitution limits:Can and drum lining applications face technical barriers as BPA-free epoxy alternatives struggle to match corrosion resistance in high-acid food contents.
Strategic Opportunities
- India FSSAI alignment:India's food safety regulator is tightening migration limits for bisphenol A in imported packaging, creating first-mover advantage for compounders with pre-certified material portfolios.
- Bio-based polypropylene R&D:Fermentation-derived propylene pathways are converging with catalytic polymerization advances to enable mass-balanced certification for premium consumer goods applications.
- Direct-to-brand digital channels:Specialized resin distributors are building configurators that let product designers specify sterilization compatibility and regulatory certification tiers online, compressing specification cycles.
Industry Challenges
- Dual-certification timelines:Medical device polymer suppliers face divergent FDA notification pathways and EU MDR conformity assessment procedures that extend validation cycles by 12-18 months.
- Legacy injection molding retrofit:Tooling designed for polycarbonate requires temperature and pressure recalibration to process lower-heat BPA-free alternatives without dimensional drift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BPA Free Plastic Market |
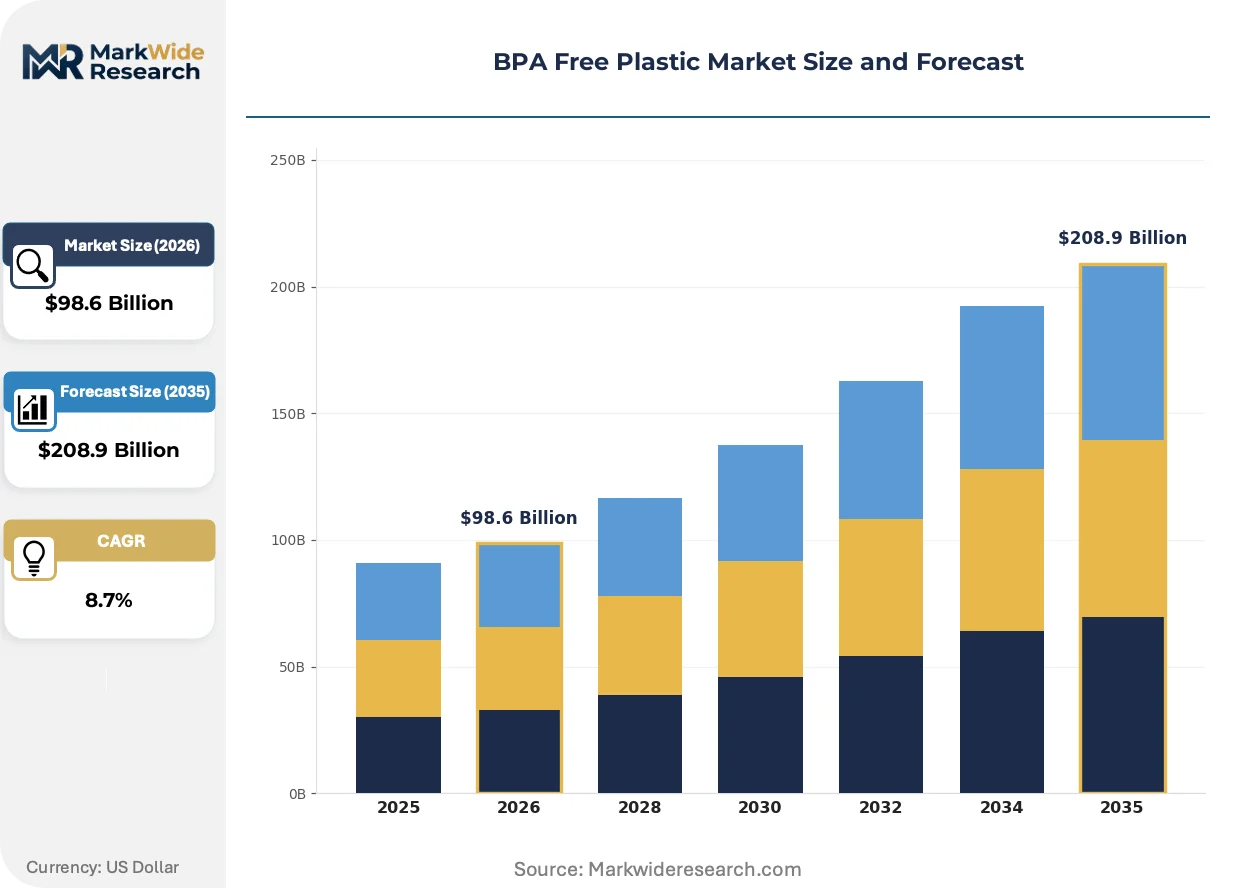
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Food Packaging, Medical Devices End Use Industry: Consumer Goods, Healthcare, Food & Beverage, Automotive Material: Polyethylene, Polypropylene, Polycarbonate, Polystyrene Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Eastman Chemical Company, BASF SE, Dow Inc., SABIC, Covestro AG, Amcor plc, Altium Packaging, DuPont de Nemours, Inc., LyondellBasell Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BPA Free Plastic Market Emerging Trajectories
Material scientists and process engineers are converging on three vectors that redefine competitive advantage: molecular architecture that eliminates endocrine-active structures, regulatory engineering that anticipates compliance evolution, and specification platforms that compress design-to-production cycles.
Copolyester formulations with cycloaliphatic monomers instead of bisphenol A are rendering obsolete optical-grade polycarbonate in medical device housings and premium food containers. Device manufacturers in Minnesota and Bavaria are qualifying these materials for steam sterilization cycles exceeding 134°C. The shift is compressing pricing premiums for clarity and heat resistance as supply scales.
ECHA's 2024 update to REACH restriction entry 66 tightens bisphenol A limits in thermal paper and food-contact plastics, forcing exporters to maintain dual inventory streams or commit entirely to reformulated grades. German converters serving discount retail chains are absorbing certification costs to retain shelf placement. The regulation is accelerating consolidation among compounders with in-house analytical capabilities for migration testing.
Brand-owner technical teams are bypassing traditional distributor networks to specify resin grades directly through compounder digital platforms with embedded regulatory documentation. Food packaging designers in California and Ile-de-France are using these tools to validate compliance against multiple jurisdiction requirements simultaneously. The behavior is fragmenting procurement volume across smaller batch orders with faster turnaround demands.
BPA Free Plastic Market Segmentation
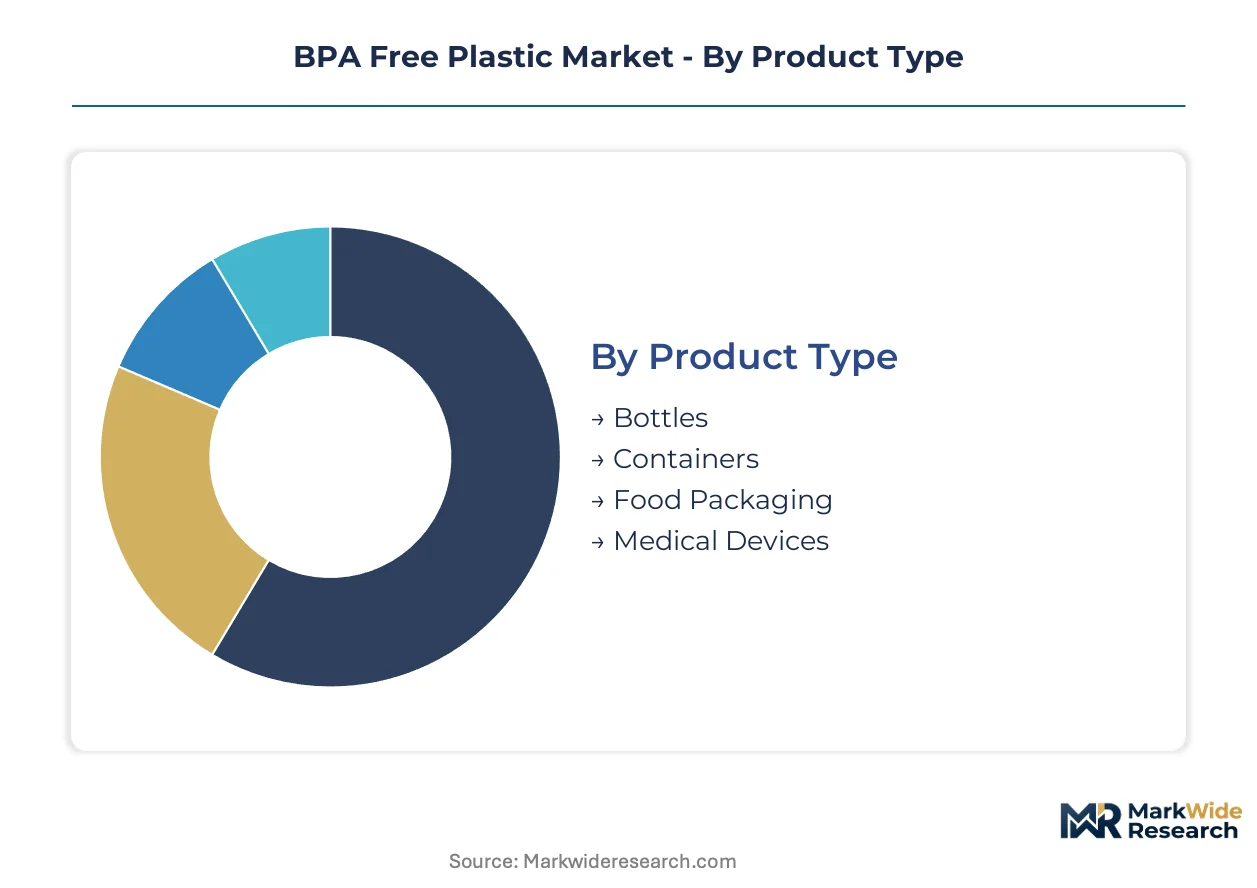
Segmentation in BPA-free plastics reveals how regulatory pressure and sterilization requirements fragment demand across incompatible specification tiers. Procurement desks now source by migration-test certification and heat-deflection temperature rather than generic polymer family alone.
Product Type:
Applications span single-use disposables through reusable medical-grade housings, with sterilization protocol determining material selection.
- Food Packaging:Flexible films and rigid trays formulated with polyethylene or polypropylene alternatives to polycarbonate. German discount retail chains and California-based organic brands are consolidating purchase orders through centralized sustainability procurement desks.
- Medical Devices:Diagnostic housings, surgical instrument handles, and fluid management components requiring USP Class VI and ISO 10993 biocompatibility certification. Bavarian device manufacturers and Minnesota sterilization facilities are qualifying cycloaliphatic copolyesters for steam cycles exceeding 134°C.
- Bottles:Reusable water bottles and infant feeding vessels utilizing Tritan copolyester or polypropylene for clarity and dishwasher durability.
- Containers:Food storage and industrial packaging applications prioritizing chemical resistance and microwave safety.
The dominant share belongs to Food Packaging, while Medical Devices is closing the gap fastest.
End Use Industry:
Volume concentrates where consumer-facing brands face the strongest liability exposure from endocrine disruption litigation.
- Food & Beverage:Primary demand driver encompassing packaging, processing equipment, and food-contact surfaces. ECHA REACH restrictions on bisphenol A in food-contact articles are forcing reformulation across European export supply chains.
- Healthcare:Surgical instruments, diagnostic equipment, and drug delivery systems requiring gamma and steam sterilization compatibility. FDA notification pathways and EU MDR conformity assessments create dual-certification burdens extending validation cycles.
- Consumer Goods:Kitchenware, personal care packaging, and children's products where brand reputation hinges on certified-safe material claims.
- Automotive:Interior trim and under-hood applications leveraging heat-stable formulations for electric vehicle battery housings and HVAC components.
Food & Beverage commands the volume base, though Healthcare delivers the steepest margin expansion trajectory.
Material:
Base polymer selection trades off optical clarity, heat resistance, and regulatory pre-certification cost.
- Polyethylene:Dominant tonnage leader for flexible packaging and blow-molded containers. LDPE and HDPE grades achieve compliance through inherent BPA-free composition rather than reformulation.
- Polypropylene:Injection-molded food containers and medical device housings benefiting from steam sterilization tolerance and fatigue resistance. Propylene feedstock volatility from crude oil and natural gas liquid price swings compresses compounder margins.
- Polycarbonate:Optical-grade copolyester alternatives are displacing traditional bisphenol A-based grades in premium applications requiring transparency and impact strength.
- Polystyrene:Foam packaging and rigid disposable applications facing substitution pressure from expanded polypropylene alternatives.
Polyethylene holds the tonnage advantage, while Polypropylene is gaining share fastest through medical device qualification.
Distribution Channel:
Channel structure reflects batch-size requirements and technical specification complexity.
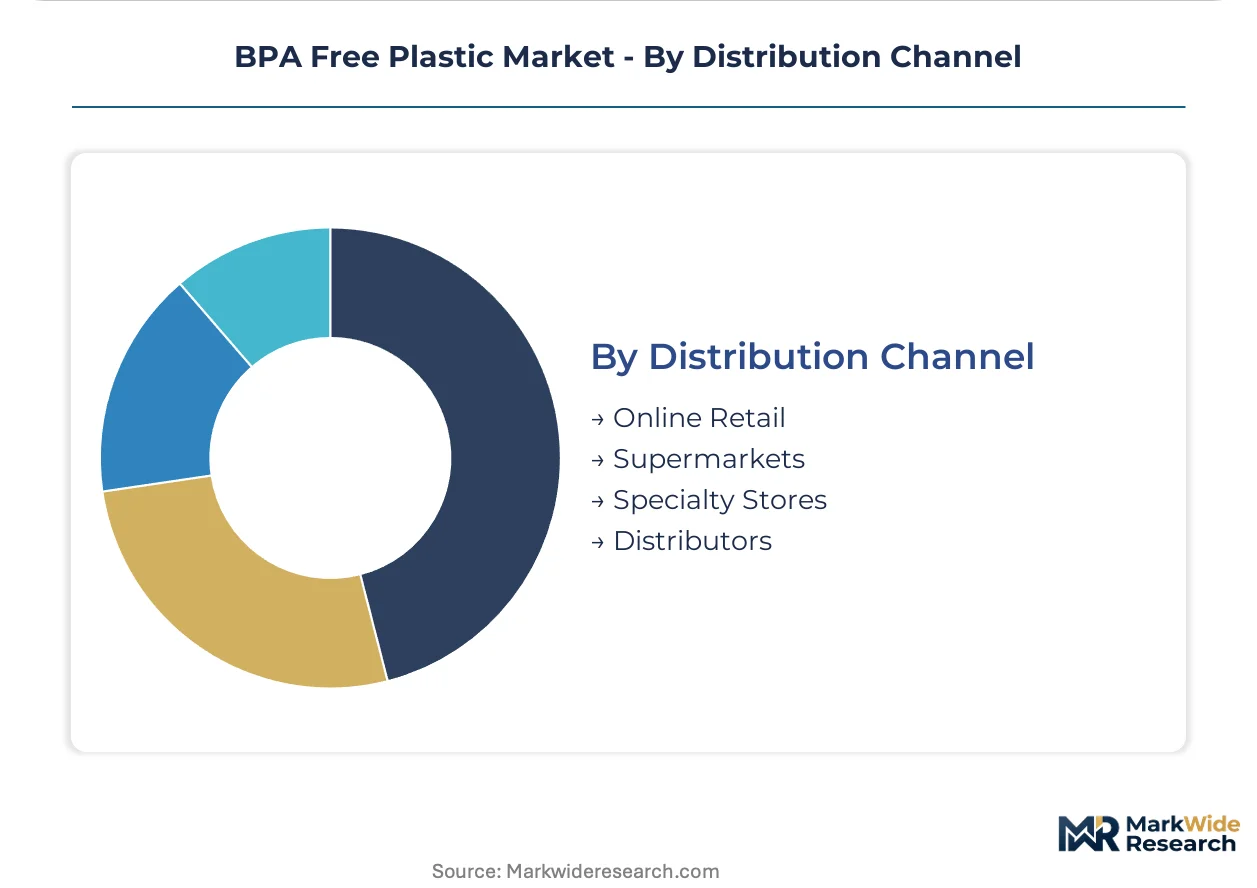
- Distributors:Specialized resin distributors with in-house compounding and migration-testing capabilities serve mid-volume converters. These intermediaries are building digital configurators allowing designers to specify sterilization compatibility and regulatory certification tiers online.
- Supermarkets:Centralized purchasing desks of major chains in Germany and France are absorbing certification costs to retain shelf placement under extended producer responsibility frameworks.
- Online Retail:Direct-to-brand digital platforms with embedded regulatory documentation enable food packaging designers to validate compliance against multiple jurisdiction requirements simultaneously.
- Specialty Stores:Niche channels serving premium consumer goods and medical device prototyping with small-batch technical service.
Distributors maintain the structural core, though Online Retail is expanding most quickly through specification-platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German supermarket chains absorb certification premiums to retain shelf placement, while Indian converters negotiate aggressively on resin costs. Medical device clusters in Minnesota and Bavaria pay steep premiums for USP Class VI pre-certification.
United States
FDA food contact substance notifications drive formulation mandates across export-oriented suppliers. The agency's notification pathways for new polymer chemistries extend validation timelines for medical device applications. Minneapolis-St. Paul anchors surgical instrument sterilization demand, with device manufacturers qualifying cycloaliphatic copolyesters for gamma and steam protocols.
Germany
ECHA REACH restrictions on bisphenol A in thermal paper and food-contact articles force compounders to maintain dual inventory streams. Extended producer responsibility frameworks concentrate procurement through centralized purchasing desks of discount retail chains. Bavarian medical device manufacturers absorb migration-testing costs to retain EU market access.
China
GB standards for food-contact plastics tighten migration limits for imported packaging materials. The country's national chemical regulator accelerates safety assessments for alternative polymer formulations. Yangtze River Delta converters retrofit polycarbonate tooling to process lower-heat BPA-free alternatives without dimensional drift.
India
FSSAI alignment with international migration standards creates first-mover advantage for compounders with pre-certified portfolios. The food safety regulator's tightening limits on bisphenol A in imported packaging reshape procurement patterns. Maharashtra-based packaging converters qualify polyethylene grades for flexible film export contracts.
Japan
METI guidelines on endocrine-disrupting chemicals in consumer products accelerate material substitution in kitchenware and infant feeding vessels. JIS standards for food-contact plastics create technical barriers for uncertified imports. Osaka-Kobe industrial corridor manufacturers develop fatigue-resistant polypropylene for reusable container applications.
BPA Free Plastic Market Vendor Landscape
Integrated resin producers and specialized compounders split the market along certification depth and feedstock control lines. Consolidation concentrates among petrochemical majors with captive monomer supply, while fragmentation persists in medical-grade formulation services. Two archetypes dominate: backward-integrated polymer producers competing on manufacturing scale, and technical compounders competing on regulatory pre-certification libraries. Capacity expansion in North American propylene derivatives and strategic partnerships for bio-based feedstock access represent the dominant competitive vectors.
Among the integrated chemical majors, Eastman Chemical Company, BASF SE, and Dow Inc. occupy positions reflecting divergent strategic emphases. Eastman anchors premium positioning through copolyester specialization. BASF exemplifies European-based diversification across material families. Dow represents North American manufacturing scale with upstream control over propylene feedstock. These three entities collectively illustrate how certification depth and geographic manufacturing footprint determine competitive positioning in regulated end-use segments.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| BASF SE |
| Dow Inc. |
| SABIC |
| Covestro AG |
| Amcor plc |
| Altium Packaging |
| DuPont de Nemours, Inc. |
| LyondellBasell Industries N.V. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta compounding capacity expansion is compressing spot pricing for polyethylene grades while concentrating bargaining power among German supermarket procurement desks absorbing REACH certification premiums. This geographic asymmetry between feedstock-abundant production zones and regulation-stringent demand centers fragments margin capture across the value chain.
Pricing Analysis
Aftermarket technical service contracts and migration-testing certification bundles drive lifetime value capture for specialized compounders. Three-tier pricing structure across medical-grade, food-contact, and industrial commodity levels segments buyers by sterilization protocol requirements. Cost compression in standard polypropylene grades is intensifying because propylene feedstock volatility from natural gas liquid markets transmits directly to converter margins. Food packaging buyers in India exhibit acute price sensitivity, while Bavarian medical device manufacturers accept steep premiums for USP Class VI pre-certification.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for export-oriented compounders. Manufacturing concentration rests on China, Germany, and the United States, with each hub serving distinct certification tiers. Raw material flows draw from Saudi Arabian propylene derivatives, Appalachian natural gas liquids, and Rotterdam petrochemical intermediates. Single-source vulnerability in cycloaliphatic monomer supply constrains optical-grade copolyester availability. Distribution runs through specialized resin distributors with in-house compounding capabilities, though direct-to-brand digital platforms are fragmenting volume across smaller batch orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward centralized retail procurement desks in Germany and France, where extended producer responsibility frameworks concentrate volume through sustainability-certified purchasing mandates. This consolidation among downstream buyers is extracting compliance investment commitments from upstream compounders.
For Market Incumbents: Pre-empt margin erosion in food packaging segments by securing backward integration into propylene feedstock through North American shale gas corridor partnerships. Lock in long-term sterilization service contracts with Minnesota and Bavarian medical device clusters to defend against emerging copolyester specialists. Certification investment in dual FDA-EU MDR pathways represents the critical lever for retaining cross-Atlantic supply relationships. For New Entrants and Emerging Players: Pursue white-space opportunity in India's FSSAI pre-certification segment, where tightening bisphenol A migration limits on imported packaging create first-mover advantage for compounders with validated portfolios. Target Maharashtra-based flexible film converters seeking export-grade polyethylene alternatives. A technical-compounder partnership model with embedded regulatory documentation accelerates specification cycles versus traditional distributor channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with captive analytical capabilities for migration testing and sterilization protocol validation. Five-to-ten year viability hinges on bio-based feedstock transition readiness and digital specification platform deployment. Acquisition targets should display in-house USP Class VI certification libraries. The signal to watch is ECHA restriction expansion beyond thermal paper into additional food-contact categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | North American shale gas corridor access insulates margins from crude oil volatility. |
| Dual-Certification Investment | Simultaneous FDA notification and EU MDR pathways retain cross-Atlantic medical device contracts. |
| Bio-Based Polypropylene R&D Partnership | Fermentation-derived propylene pathways enable mass-balanced certification for premium consumer goods. |
| Digital Specification Platform Launch | Direct-to-brand configurators compress design-to-production cycles for California and Ile-de-France packaging designers. |
| Migration Testing Laboratory Acquisition | In-house analytical capabilities accelerate ECHA compliance validation for German discount retail chains. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across resin compounders, medical device sterilization facilities, and supermarket procurement desks. Technical R&D directors at integrated chemical majors, plant managers at Yangtze River Delta converters, and regulatory affairs leads at German retail chains provided operational validation. Secondary triangulation drew from ECHA restriction updates, FDA food contact substance notifications, SEC 10-K petrochemical segment disclosures, and customs trade data for polyethylene and polypropylene flows. Bottom-up volume modeling and top-down value reconciliation anchored forecast integrity.
Calibration against historical capacity utilization rates and sterilization protocol adoption curves refined projection parameters across the analysis window. Segmentation dimensions encompassed material family, sterilization compatibility tier, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions. Feedstock cost trajectories and REACH restriction enforcement timelines served as industry-specific forecast inputs.
Sensitivities concentrate around ECHA restriction scope expansion, propylene feedstock price volatility, and medical device sterilization protocol shifts. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or bio-based polymer technology breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
North America Plastic Waste Management Market