
 South-East Asia (SEA) Plastics Market | 2026-2036
South-East Asia (SEA) Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia (SEA) Plastics Market Analytics
Polyethylene terephthalate is realigning rigid container economics as brand owners substitute glass and metal in beverage and personal care lines. SCG Chemicals PCL leverages integrated olefin complexes across Thailand's Eastern Economic Corridor to sustain feedstock cost advantages. Lotte Chemical anchors its regional position through high-purity polypropylene output serving automotive tier-one suppliers. An Phat Holdings specializes in biodegradable film formulations that differentiate its portfolio from commodity resin traders.
South-East Asia plastics encompass thermoplastic and thermoset polymers synthesized from petrochemical feedstocks, with melt flow indices, density grades, and additive packages determining process compatibility across injection, blow, and extrusion methods. These materials function as structural, barrier, and aesthetic layers in manufactured goods ranging from flexible pouches to automotive interior panels. Polyethylene dominates volume flows across the region due to its versatility in packaging films and blow-molded containers, while engineering-grade resins command margin premiums in under-hood automotive and electrical housing segments. Recycled-grade polymers represent the fastest-expanding grade category as Indonesian and Thai packaging mandates tighten post-consumer content thresholds.
Indonesia's Ministry of Environment enforces extended producer responsibility frameworks that obligate brand owners to fund collection infrastructure, while Thailand's Pollution Control Department phases single-use plastics through scheduled bans on specific product categories. Vietnam's National Technical Regulation on plastic packaging restricts certain additive chemistries, compelling reformulation investments by compounders serving export markets. Stakeholders must monitor regulatory divergence across ASEAN member states to avoid compliance fragmentation that could strand capital in non-conforming production lines.
Market Dynamics
Indonesia's extended producer responsibility mandates and Thailand's single-use plastic bans are forcing converters to requalify resin grades and reconfigure extrusion lines, compressing procurement timelines and elevating compounder qualification costs across ASEAN.
Growth Catalysts
- Extended Producer Responsibility frameworks:Indonesia's Ministry of Environment obligates brand owners to fund collection infrastructure, redirecting capital toward post-consumer recycling capacity.
- Flexible packaging substitution:Food processors in Vietnam's northern manufacturing corridor near Haiphong are substituting rigid containers with polyethylene films to reduce logistics cube and shelf-space costs.
- Automotive lightweighting:Tier-one suppliers serving Thailand's Eastern Economic Corridor are expanding polypropylene intake for interior panel applications to meet fuel efficiency targets.
Market Restraints
- Naphtha feedstock volatility:Steam cracker economics across Singapore and Thailand remain exposed to Middle Eastern naphtha price swings, compressing olefin margins without long-term offtake hedges.
- Recycled resin quality inconsistency:Indonesian packaging converters face batch-to-batch melt flow index variation in post-consumer polyethylene, forcing higher additive loading and scrap rates.
- Biodegradable film performance gaps:An Phat Holdings and comparable compounders encounter barrier property limitations in polylactic acid blends that exclude them from oxygen-sensitive food applications.
Strategic Opportunities
- Haiphong-Bac Ninh corridor expansion:Northern Vietnam's electronics assembly concentration is driving demand for engineering-grade resins in connector housings and device enclosures.
- Chemical recycling infrastructure:Pyrolysis-based feedstock recovery offers a pathway to food-contact approved recycled polyethylene, bypassing mechanical recycling quality ceilings.
- Thailand bio-based plastics roadmap:Government incentives for cassava-derived polylactic acid production create feedstock cost advantages against fossil-based alternatives for export-oriented converters.
Industry Challenges
- Polymer characterization expertise scarcity:Compounders struggle to recruit technicians proficient in rheological testing and additive-package optimization for recycled-grade formulations.
- Cross-border formulation compliance:Vietnam's National Technical Regulation on plastic packaging restricts phthalate plasticizers that remain permissible in Thai and Indonesian standards, forcing SKU proliferation.
- Legacy extrusion asset retrofit costs:Converters must modify screw geometries and cooling systems to process higher-viscosity recycled polyethylene without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia (SEA) Plastics Market |
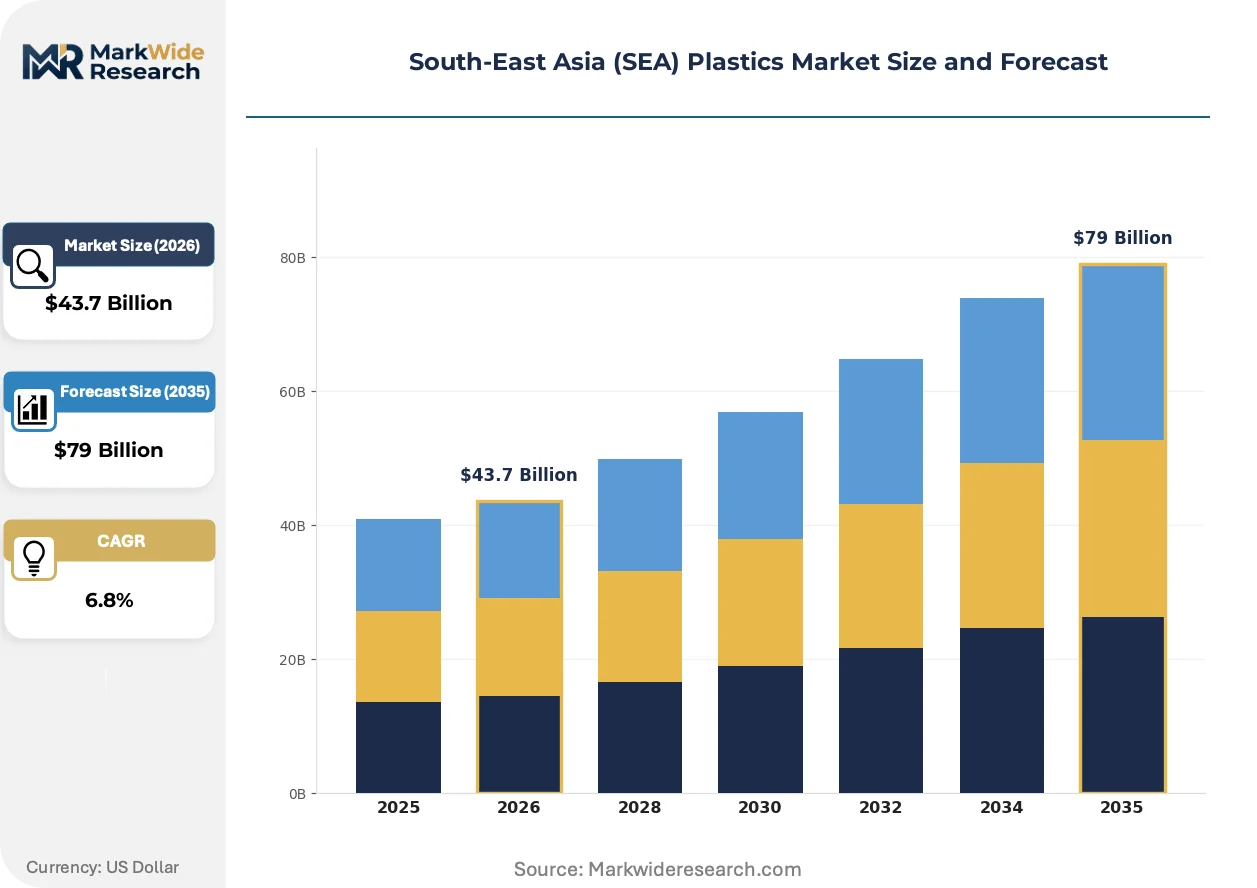
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, PVC End Use Industry: Packaging, Automotive, Construction, Consumer Goods Grade: Recycled, High-Density, Low-Density, Engineering Application: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | LyondellBasell, Long Son Petrochemicals, SCG Chemicals PCL, Dongsung, Lotte Chemical, PT Chandra Asri Petrochemical Tbk, BASF, An Phat Holdings, PETRONAS Chemicals Group Berhad, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia (SEA) Plastics Market Evolving Landscape
Material science advances and regulatory stringency are compressing product development cycles, forcing simultaneous investment in biodegradability, recycled content integration, and barrier performance enhancement.
Chemical recycling via pyrolysis and gasification is converging with mechanical recycling streams to expand food-contact approved resin supply. Brand owners in beverage and personal care segments are qualifying these hybrid outputs for bottle-to-bottle applications. This convergence is compressing the price premium between virgin and recycled polyethylene terephthalate grades.
Thailand's Pollution Control Department schedules phased bans on specific single-use plastic categories, compelling converters to accelerate biopolymer formulation timelines. The automotive sector faces parallel pressure as the country's Eastern Economic Corridor attracts EV assembly investments with stringent interior air quality standards. Suppliers are responding by certifying low-VOC polypropylene compounds ahead of mandate deadlines.
Buyer consolidation among multinational FMCG companies is compressing supplier qualification timelines and elevating audit intensity. Regional packaging converters report purchasing departments now mandate simultaneous documentation of carbon footprint, recycled content percentage, and recyclability design guidelines. This behavior shift is most visible in Indonesia, where Unilever and Nestlé procurement teams have centralized resin sourcing decisions to Jakarta headquarters.
South-East Asia (SEA) Plastics Market Segmentation
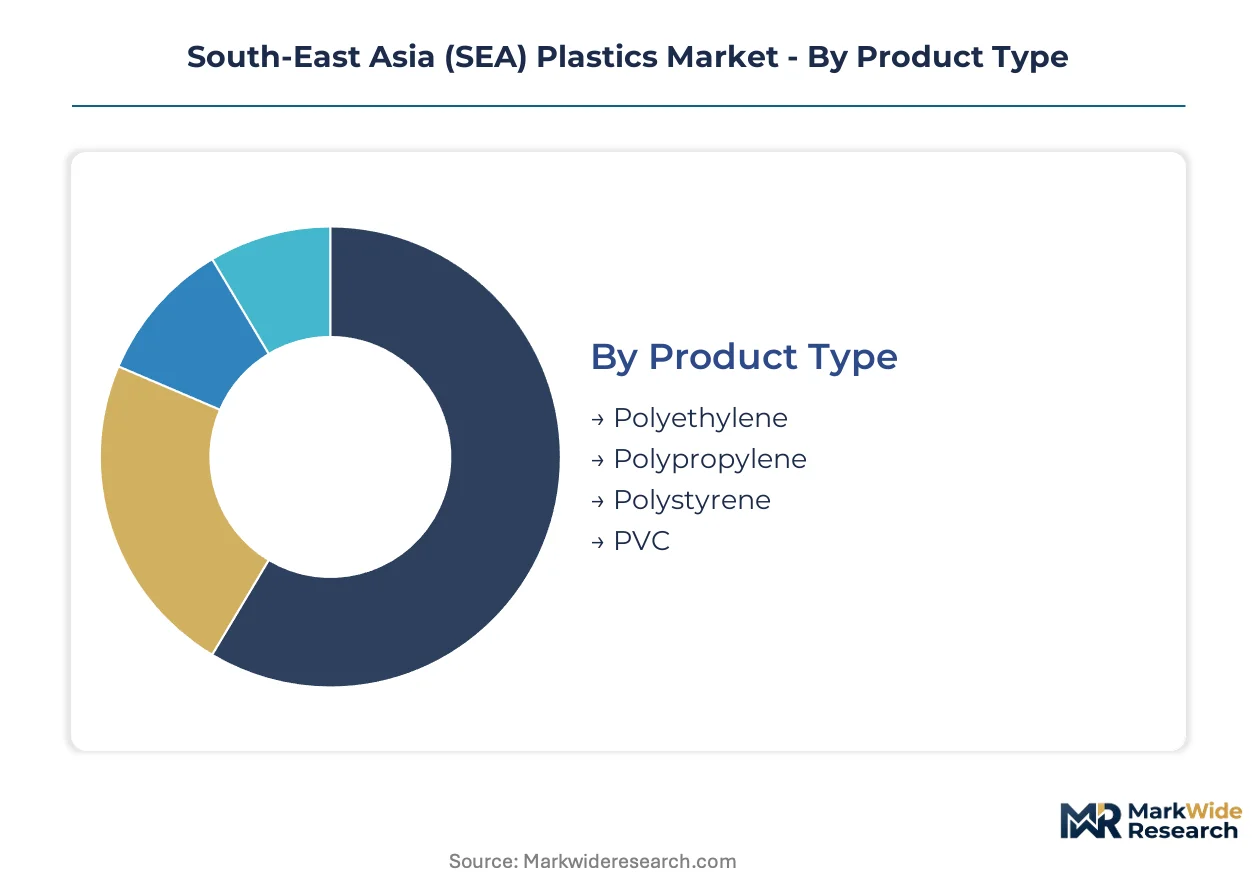
Segmentation in South-East Asia plastics reveals how capital deployment, regulatory thresholds, and processing technology intersect to determine margin capture. Converters must match resin specifications to end-use certification requirements across divergent national standards.
Product Type:
Capital intensity varies sharply by polymer chemistry, with olefin complexes demanding billion-dollar cracker investments while styrenics require less feedstock integration.
- Polyethylene:Linear low-density and high-density grades dominate flexible film and rigid container production. Thai packaging converters near Map Ta Phut consume the largest regional volumes for food wrap and shopping bag applications, driven by Indonesia's mandatory recycled content rules that favor polyethylene's mechanical recycling compatibility.
- Polypropylene:Homopolymer and copolymer formulations serve automotive interior panels and thin-wall packaging. Vietnam's northern manufacturing corridor near Bac Ninh is absorbing expanding polypropylene volumes for electronics housings and appliance components as electronics assembly concentrates there.
- Polystyrene:General-purpose and high-impact grades target disposable food service items and appliance insulation. Demand faces structural pressure from Thailand's single-use plastic bans.
- PVC:Suspension and emulsion grades supply construction piping and wire jacketing. Vietnamese infrastructure investment sustains regional consumption despite environmental scrutiny of plasticizer chemistries.
Most installed capacity flows through Polyethylene. Expansion is steepest in Polypropylene.
End Use Industry:
Application margins separate packaging commodity plays from automotive and construction specifications that reward compounder technical service capabilities.
- Packaging:Flexible films, rigid containers, and closures constitute the volume base. Indonesian brand owners now fund collection infrastructure under extended producer responsibility mandates, redirecting procurement toward post-consumer recycled grades.
- Automotive:Interior panels, under-hood components, and electrical connectors require low-VOC and heat-stabilized formulations. Thailand's Eastern Economic Corridor attracts EV assembly investments with stringent interior air quality standards that compounders must certify against.
- Construction:Piping, profiles, and geomembranes demand UV-stabilized and impact-modified grades. Vietnamese public works programs sustain demand despite cyclical property sector volatility.
- Consumer Goods:Appliance housings, furniture, and personal care packaging blend aesthetic and functional requirements. This segment exhibits the most price-sensitive procurement behavior among multinational FMCG buyers.
Packaging commands the largest volume share. Automotive applications are gaining share fastest.
Grade:
Quality tiering determines qualification timelines, with recycled and engineering grades imposing the most rigorous batch certification protocols on compounders.
- Recycled:Post-consumer and post-industrial reprocessed resins face melt flow index inconsistency that forces higher additive loading. Indonesian converters report elevated scrap rates as they adapt to mandatory recycled content thresholds.
- High-Density:Stiffness-optimized polyethylene serves crates, pallets, and blow-molded containers. Thai logistics and beverage sectors anchor regional demand.
- Low-Density:Clarity and flexibility-oriented grades target film and squeeze bottle applications. Vietnam's food processing export sector sustains consumption.
- Engineering:Nylon, polycarbonate, and acetal grades serve electrical connectors and precision gears. The Haiphong-Bac Ninh corridor is absorbing expanding volumes for electronics assembly.
High-Density and Low-Density grades retain the largest installed base. Recycled grades are climbing the fastest.
Application:
Processing method selection locks converters into specific equipment investments and determines resin viscosity and thermal stability requirements.
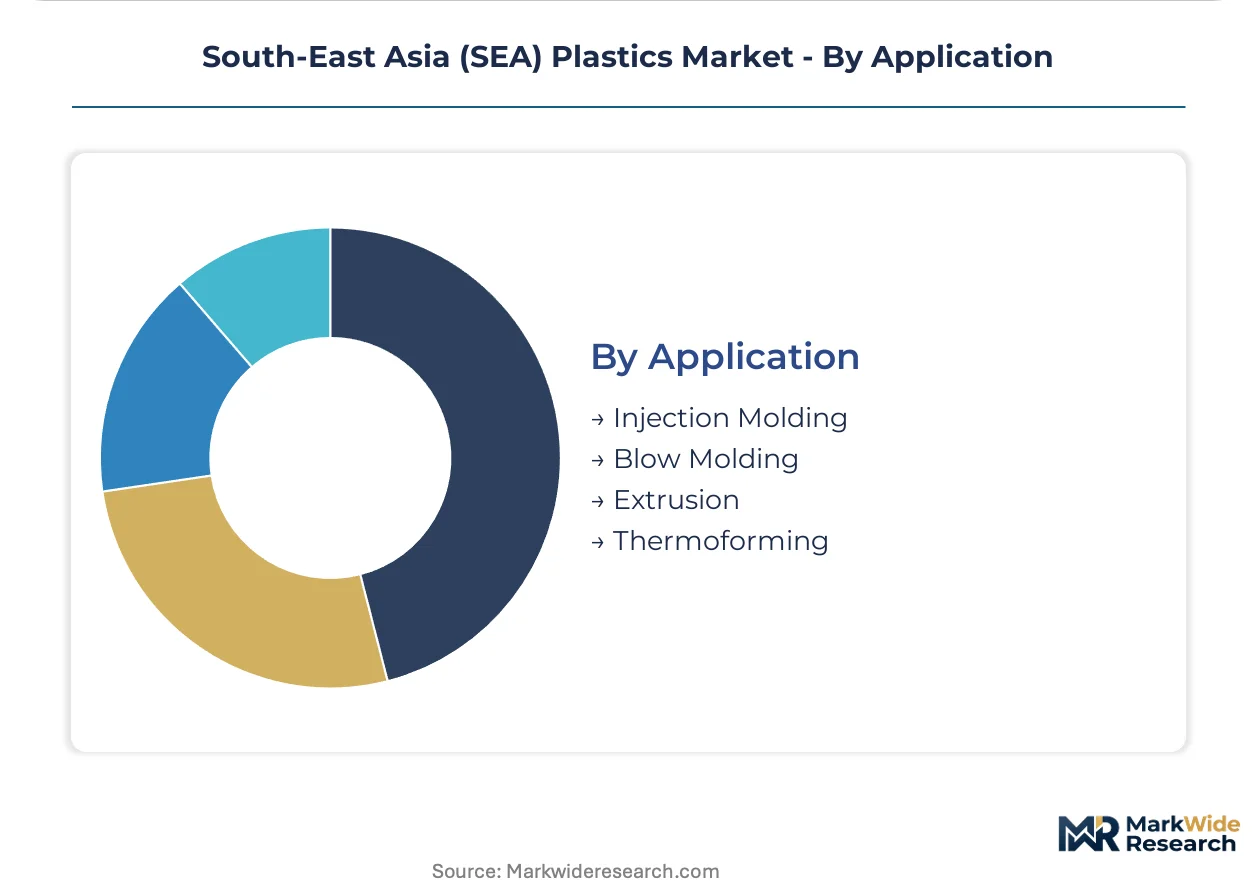
- Injection Molding:High-speed, precision part production for automotive and consumer goods. Thai tier-one suppliers are expanding polypropylene intake for interior panel applications.
- Blow Molding:Hollow container production for beverages and personal care. Chemical recycling advances are expanding food-contact approved recycled polyethylene supply for bottle-to-bottle applications.
- Extrusion:Film, sheet, and profile continuous processing. Vietnam's northern corridor converters are substituting rigid containers with polyethylene films to reduce logistics cube costs.
- Thermoforming:Thin-gauge packaging and disposable food service items. Thailand's phased single-use plastic bans are compressing demand timelines for alternative material qualification.
Extrusion and Injection Molding dominate current capacity. Blow Molding is expanding most quickly as chemical recycling infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor anchors regional resin production through integrated olefin complexes serving packaging converters across ASEAN. Vietnam's northern manufacturing belt near Haiphong and Bac Ninh is absorbing expanding polymer volumes for electronics and food processing exports. Indonesia's regulatory mandates are redirecting procurement toward post-consumer recycled grades.
Thailand
Automotive tier-one suppliers and flexible packaging converters drive polyethylene and polypropylene consumption. The Pollution Control Department phases single-use plastics through scheduled bans on specific product categories. Map Ta Phut industrial estates host SCG Chemicals PCL's integrated complexes supplying rigid container and film markets.
Vietnam
Electronics assembly concentration and food processing exports sustain engineering-grade and film resin demand. The National Technical Regulation on plastic packaging restricts certain additive chemistries for export-bound compounders. The Haiphong-Bac Ninh corridor is substituting rigid containers with polyethylene films to reduce logistics costs.
Indonesia
Mandatory recycled content rules and extended producer responsibility frameworks redirect brand owner procurement. The Ministry of Environment obligates funding of collection infrastructure. Java-based packaging converters face melt flow index variation challenges as they adapt to post-consumer polyethylene thresholds.
Singapore
Steam cracker operations and regional trading hubs expose naphtha feedstock economics to Middle Eastern price swings. The city-state's refining complex supplies olefin derivatives across ASEAN without domestic conversion capacity. Jurong Island petrochemical installations serve as price discovery points for regional resin benchmarks.
Malaysia
PETRONAS Chemicals Group Berhad anchors domestic olefin supply for downstream polymer production. Infrastructure investment in piping and construction applications sustains PVC consumption despite environmental scrutiny. The Kertih petrochemical zone integrates with Thai and Indonesian converter networks through cross-border logistics.
South-East Asia (SEA) Plastics Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and specialty formulation capabilities. The market structures around three tiers: integrated petrochemical conglomerates with captive cracker capacity, mid-scale compounders serving automotive and electronics specifications, and biodegradable specialists differentiating through polylactic acid formulations. Consolidation pressures concentrate around chemical recycling technology licensing and backward integration into pyrolysis feedstock recovery.
Within the integrated conglomerate tier, SCG Chemicals PCL and Lotte Chemical exemplify regional champions leveraging Eastern Economic Corridor infrastructure and high-purity polypropylene output respectively. An Phat Holdings occupies a specialist position in biodegradable film formulations. LyondellBasell and BASF represent global majors with technology licensing reach across ASEAN converter networks.
| Leading Market Players |
|---|
| LyondellBasell |
| Long Son Petrochemicals |
| SCG Chemicals PCL |
| Dongsung |
| Lotte Chemical |
| PT Chandra Asri Petrochemical Tbk |
| BASF |
| An Phat Holdings |
| PETRONAS Chemicals Group Berhad |
| Others |
Value Network & Pricing Analysis
Captive olefin production across Thailand's Eastern Economic Corridor anchors both supply security and pricing leverage for integrated producers serving ASEAN converter networks. SCG Chemicals PCL and comparable operators offset naphtha volatility through backward control over cracker feedstocks, while non-integrated compounders absorb margin compression without such buffers.
Pricing Analysis
Naphtha cost pass-through mechanics dominate polyethylene and polypropylene pricing, with Singapore refining benchmarks transmitting Middle Eastern crude volatility into regional resin quotations within 30-45 day lags. Contract-based long-term offtake agreements separate premium-tier buyers securing volume certainty from spot-market purchasers facing price swings. Price differentiation hinges on recycled content certification and automotive-grade compound approvals. Pricing pressure stems from Indonesian mandatory recycled content thresholds forcing converters to absorb higher additive loading costs. Multinational FMCG procurement teams exhibit lowest price sensitivity, while domestic Vietnamese packaging converters negotiate aggressively on volume.
Supply Chain Analysis
Ethylene and propylene supply rests on steam cracker operations concentrated in Thailand, Singapore, and South Korea, with naphtha feedstock drawing from Middle Eastern and regional refining outputs. Specialty additive packages for recycled-grade formulations hinge on Malaysian and Indonesian compounder capacity. Single-source vulnerability concentrates in pyrolysis-based chemical recycling technology licensing, where European and Japanese technology providers control equipment supply. Distribution runs through Map Ta Phut and Jurong Island bulk terminals into converter networks across Vietnam's northern corridor and Indonesia's Java-based packaging belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-grade certification as automotive and electronics buyers shift procurement toward low-VOC and food-contact approved compounds. Chemical recycling infrastructure investments compound this premium capture by bypassing mechanical recycling quality ceilings.
For Market Incumbents: Hedge naphtha exposure through long-term Middle Eastern supply contracts or cassava-derived bio-based feedstock positions under Thailand's roadmap incentives. Defend margin position by certifying low-VOC polypropylene compounds ahead of Eastern Economic Corridor EV assembly mandates. Prioritize backward integration into pyrolysis feedstock recovery to secure food-contact approved recycled polyethylene supply.
For New Entrants and Emerging Players: Mid-tier Vietnamese electronics assemblers in the Bac Ninh corridor represent an underserved buyer archetype seeking engineering-grade resin technical service without multinational minimum order requirements. Target this segment through localized compounding facilities with rapid formulation turnaround. Penetration accelerates by partnering with regional distributors already serving Haiphong logistics networks.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale compounders with automotive certification assets because buyer consolidation among multinational FMCG companies is compressing supplier qualification timelines and elevating audit intensity. Five-to-ten year viability favors operators with simultaneous biodegradability, recycled content, and barrier performance capabilities. Watch Indonesian Ministry of Environment enforcement intensity as the inflection signal for post-consumer recycling capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Feedstock Recovery | Bypasses mechanical recycling quality ceilings for food-contact approved polyethylene supply. |
| Low-VOC Polypropylene Certification | Qualifies compounds for Thailand Eastern Economic Corridor EV assembly interior air quality mandates. |
| Cassava-Derived Polylactic Acid Capacity | Captures Thailand bio-based plastics roadmap incentives against fossil-based resin alternatives. |
| Haiphong-Bac Ninh Corridor Compounding Facility | Positions technical service capabilities adjacent to Vietnam electronics assembly concentration. |
| Extended Producer Responsibility Infrastructure Partnership | Secures post-consumer polyethylene supply streams under Indonesian Ministry of Environment mandates. |
Research Methodology
Coverage spans Thailand, Vietnam, Indonesia, Singapore, and Malaysia, with primary inputs from each market's converter and resin production clusters. The analysis combines interviews with plant managers at integrated petrochemical complexes, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors at compounder facilities with secondary validation. Secondary sources include customs and trade data, ASEAN petrochemical association reports, SEC filings from listed producers, and national regulatory gazettes documenting extended producer responsibility frameworks. Bottom-up resin consumption estimates triangulate against top-down production capacity assessments.
Rate-of-change decomposition separates volume growth from price and mix effects across the projection horizon. The analytical framework models segmentation dimensions including grade tier (virgin, recycled, bio-based), end-use industry (packaging, automotive, construction, consumer goods), and regional production hub. CAGRs derive from trend extrapolation adjusted for regulatory mandate implementation schedules and capacity expansion announcements. Industry-specific forecast inputs include naphtha-to-olefin spread assumptions and automotive lightweighting content-per-vehicle trajectories.
Underlying measurement precision varies by segment; recycled-grade consumption carries tighter precision than bio-based plastics given mandatory reporting thresholds. Forecasts reflect assumptions around Indonesian Ministry of Environment enforcement timelines and Thailand Pollution Control Department ban implementation. Regulatory delay, naphtha price volatility, and chemical recycling technology cost curves warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
US Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Waste Plastic Bricks Market