
 US Specialty Cleaners Market | 2026-2036
US Specialty Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
US Specialty Cleaners Market Insights
US Gulf Coast chemical manufacturing capacity is reconfiguring surfactant supply chains for domestic specialty cleaner producers. Procter & Gamble leverages its Cincinnati R&D hub to sustain formulation leadership in enzyme-based degreasers. SC Johnson anchors its Racine operations around plant-derived solvent chemistry, while The Clorox Company dominates bleach-alternative disinfectant channels through retail distribution control.
Specialty cleaners comprise formulated chemical solutions designed to remove specific soils, contaminants, or residues from targeted surfaces, typically containing surfactants, solvents, chelating agents, and pH adjusters at concentrations between 5% and 20% active content depending on application intensity. These products serve industrial maintenance, commercial sanitation, and consumer household settings where general-purpose cleaners fail to address bonded grease, mineral scale, or biofilm deposits. Multi-surface cleaners and disinfectants capture the largest revenue share within product type segments, reflecting pandemic-elevated hygiene protocols that persist in commercial and healthcare settings. Concentrate delivery modes expand fastest as sustainability mandates and bulk procurement in hospitality and food service reduce packaging waste and shipping costs per usable gallon.
EPA regulates antimicrobial efficacy claims through FIFRA registration, while OSHA sets workplace chemical exposure limits that constrain volatile organic compound formulations in industrial degreasers. California's Department of Toxic Substances Control advances Safer Consumer Products regulations that pressure formulators to substitute ortho-phthalates and perchloroethylene with biodegradable alternatives. Stakeholders must monitor state-level chemical restriction cascades and bio-based feedstock cost curves to align R&D pipelines with compliance timelines and procurement specifications.
Market Dynamics
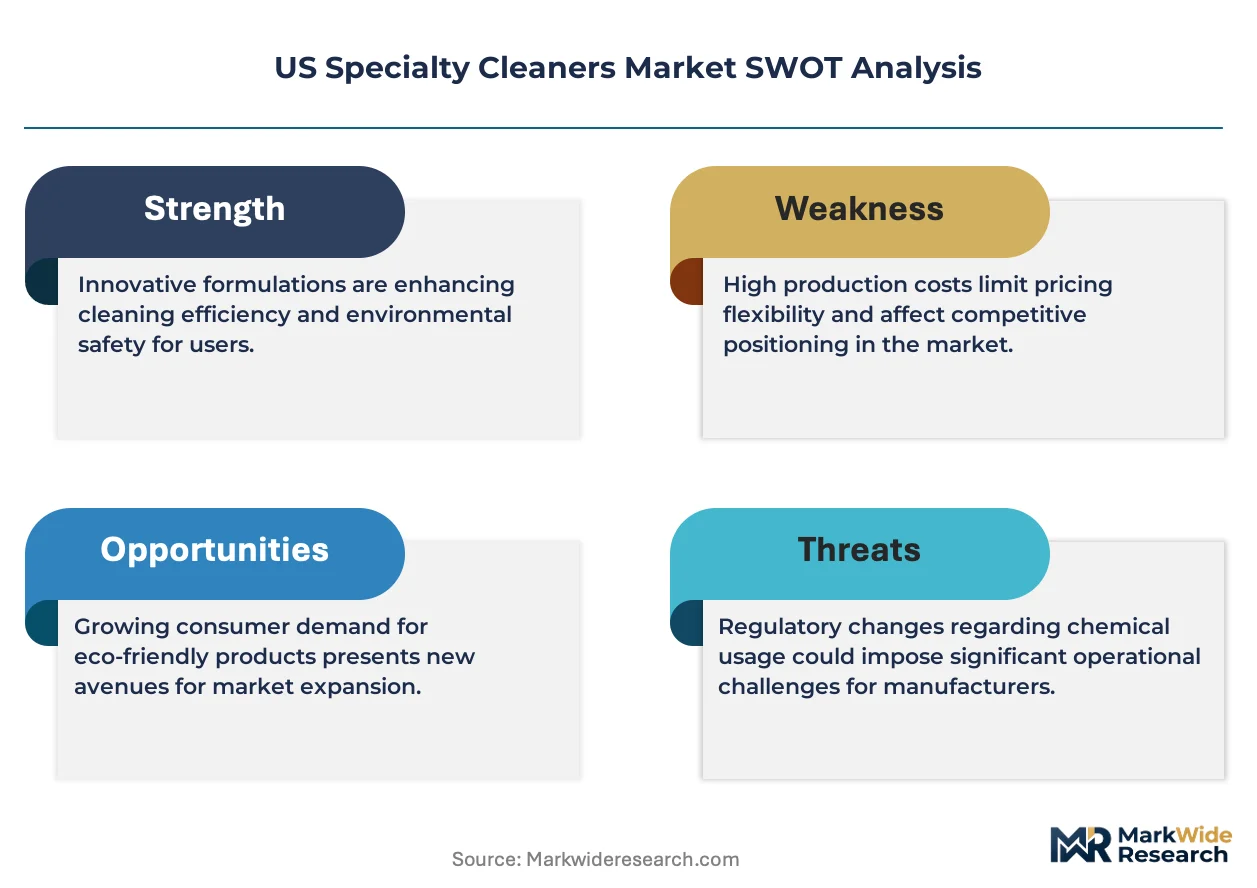
EPA FIFRA registration tightening for antimicrobial efficacy claims is forcing formulators to redesign active ingredient portfolios and extend development timelines, compressing margins for mid-tier producers while advantaging established registrants with dedicated regulatory infrastructure.
Growth Catalysts
- Hospital-grade disinfectant protocols:Healthcare facilities in Texas and California are mandating sporicidal and virucidal efficacy standards that exceed general-purpose cleaner specifications, pulling premium formulated products into routine sanitation workflows.
- REACH-aligned state chemical restrictions:California's Safer Consumer Products regulations are accelerating substitution of ortho-phthalates and perchloroethylene with biodegradable surfactant alternatives, creating compliant product differentiation.
- Concentrate delivery mode expansion:Bulk procurement systems in hospitality and food service are reducing packaging waste per usable gallon, aligning with corporate sustainability procurement scorecards.
Market Restraints
- Petrochemical feedstock volatility:Surfactant precursors derived from Gulf Coast ethylene oxide and propylene oxide face price instability tied to natural gas liquid cracking economics.
- EPA registration timeline friction:New antimicrobial active ingredients require 18-36 month efficacy data packages, freezing formulation innovation cycles for emerging pathogens.
- Aqueous ultrasonic cleaning substitution:Precision manufacturing in automotive and electronics is displacing solvent-based degreasers with water-based systems using cavitation energy.
Strategic Opportunities
- Enzyme-based degreaser R&D pipelines:Protease and lipase formulations targeting food processing equipment biofilms offer performance advantages over caustic chemistry in temperature-sensitive applications.
- Midwestern manufacturing corridor penetration:Ohio and Michigan automotive supplier clusters remain underserved by specialty cleaner technical service networks concentrated on the coasts.
- USDA BioPreferred procurement mandates:Federal purchasing requirements for biobased content are creating specification advantages for plant-derived solvent formulations in institutional contracts.
Industry Challenges
- Formulation chemist talent scarcity:Surfactant science and green chemistry expertise pools are concentrated among retiring cohorts, constraining R&D team scaling.
- Legacy equipment compatibility testing:New biodegradable formulations require extensive material compatibility validation against existing sanitation infrastructure in food processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Specialty Cleaners Market |
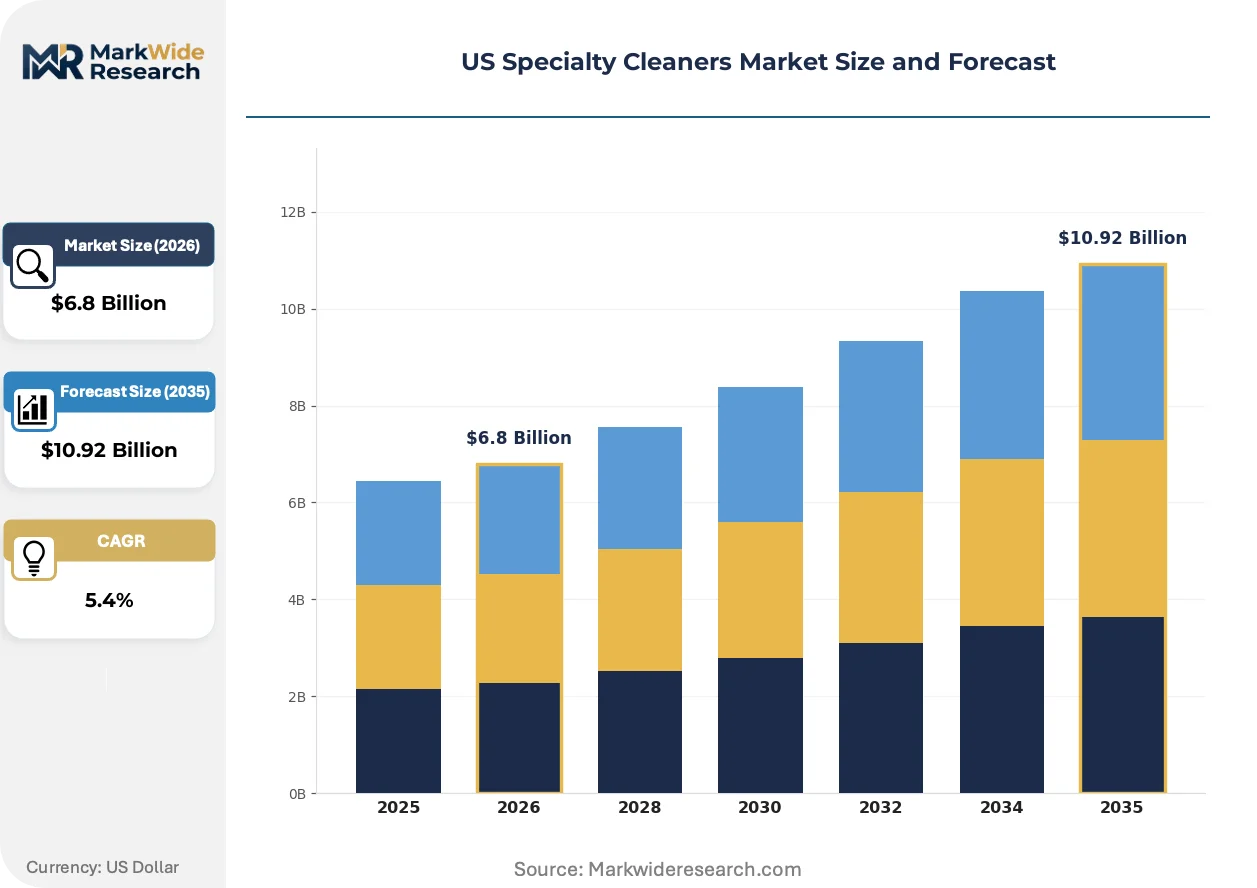
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Degreasers, Disinfectants, Multi-Surface Cleaners, Specialty Surface Cleaners End User: Households, Commercial Establishments, Automotive Industry, Healthcare Facilities Delivery Mode: Aerosol, Liquid Spray, Wipe, Concentrate Packaging Type: Plastic Bottles, Trigger Sprays, Bulk Containers, Sachets |
| Companies Covered | Procter & Gamble, The Clorox Company, SC Johnson & Son, ZEP Inc., Reckitt Benckiser Group, Unilever, Grove Collaborative Inc., Weiman Products LLC, Laticrete International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Specialty Cleaners Market Trends and Innovations
Formulation chemistry is pivoting toward bio-based feedstocks and precision enzyme systems that challenge conventional petrochemical surfactant economics across industrial maintenance and healthcare sanitation applications.
Electrochemically activated water systems are generating hypochlorous acid and sodium hydroxide on-site from salt and tap water inputs. Food processing plants in the Midwest are piloting these units for conveyor sanitation cycles. Capital equipment substitution is rendering obsolete bulk delivered hypochlorite contracts and associated drum logistics.
OSHA Permissible Exposure Limit reductions for volatile organic compounds in industrial degreasers are constraining solvent-based formulation options. Manufacturers are responding with high-boiling-point ester and terpene blends that maintain grease-cutting performance while complying with workplace air quality monitoring requirements. Metal fabrication shops in the Southeast face the steepest compliance retrofit costs.
Managed chemical service contracts are consolidating procurement decisions for multi-site hospitality and healthcare operators. Distributor technical service teams are displacing direct manufacturer relationships by embedding inventory management and dilution control equipment at customer sites. This pattern concentrates most visibly in California's integrated resort and hospital networks where procurement centralization has advanced furthest.
US Specialty Cleaners Market Segmentation
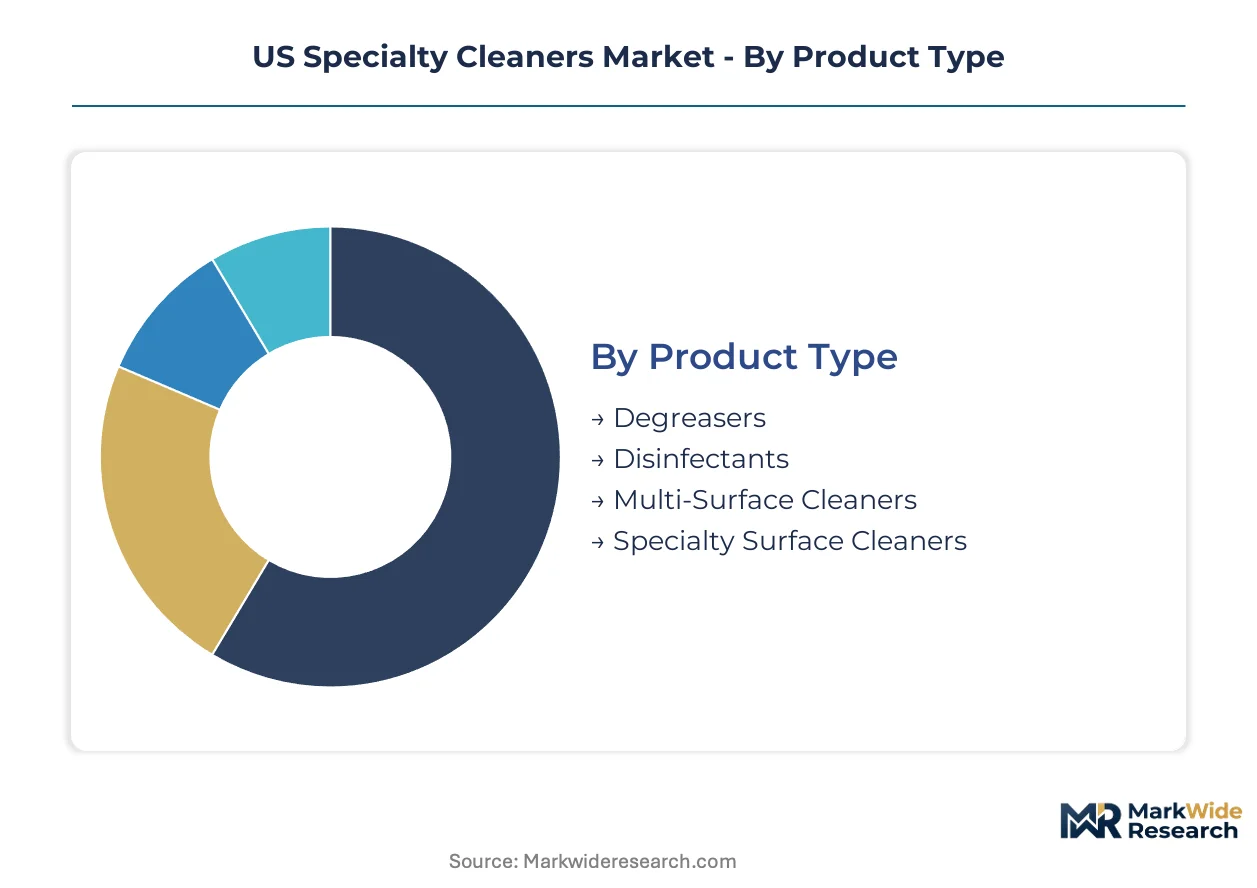
Specialty cleaner purchasing decisions split across formulation chemistry, application intensity, and operational logistics. Each segmentation axis reveals distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Mature disinfectant chemistry dominates procurement volumes while enzymatic degreaser formulations represent the emerging technology frontier.
- Multi-Surface Cleaners:Surfactant blends with pH buffering systems handle routine soil removal across diverse substrates. California healthcare networks and Texas hospitality chains specify these for daily maintenance protocols where broad compatibility reduces inventory complexity.
- Disinfectants:EPA-registered active ingredients including quaternary ammonium compounds and hydrogen peroxide achieve hospital-grade sporicidal claims. Demand concentrates in healthcare facilities where Joint Commission accreditation mandates documented efficacy against emerging pathogens.
- Degreasers:Solvent-based and aqueous alkaline formulations target bonded petroleum residues in industrial settings.
- Specialty Surface Cleaners:pH-specific chemistries address unique substrates including stainless steel, glass, and sealed stone.
Multi-surface cleaners handle the majority of throughput; disinfectants are expanding most quickly on share as healthcare protocols tighten.
End User:
Volume concentration follows commercial procurement scale while specification intensity varies sharply by contamination risk.
- Healthcare Facilities:Infection control committees mandate sporicidal and virucidal efficacy documentation exceeding retail product claims. Texas medical centers and California integrated health systems drive premium formulation demand through centralized procurement.
- Commercial Establishments:Hospitality and food service operators prioritize concentrate economics and dilution control systems. Bulk procurement contracts in California resort networks and Texas hotel chains emphasize sustainability scorecard alignment.
- Automotive Industry:Precision manufacturing requires residue-free cleaning for coating adhesion and electronic component assembly.
- Households:Retail channels emphasize convenience packaging and fragrance differentiation over technical performance metrics.
Commercial establishments command the largest volume commitment; healthcare facilities are climbing the fastest as regulatory scrutiny intensifies.
Delivery Mode:
Packaging format selection directly determines shipping economics and workplace exposure compliance.
- Concentrate:Dilution-at-use systems reduce packaging mass per usable gallon. Food service and hospitality procurement teams in California specify concentrates to meet corporate waste reduction targets and reduce drum handling logistics.
- Liquid Spray:Ready-to-use formulations dominate residential and light commercial applications where dilution equipment is unavailable.
- Wipe:Pre-saturated substrates serve healthcare surface disinfection and automotive detailing where controlled saturation prevents overspray.
- Aerosol:Pressurized delivery enables targeted application in confined mechanical spaces and vertical surfaces.
Liquid spray retains the broadest installed base; concentrate formats are gaining share fastest on sustainability procurement mandates.
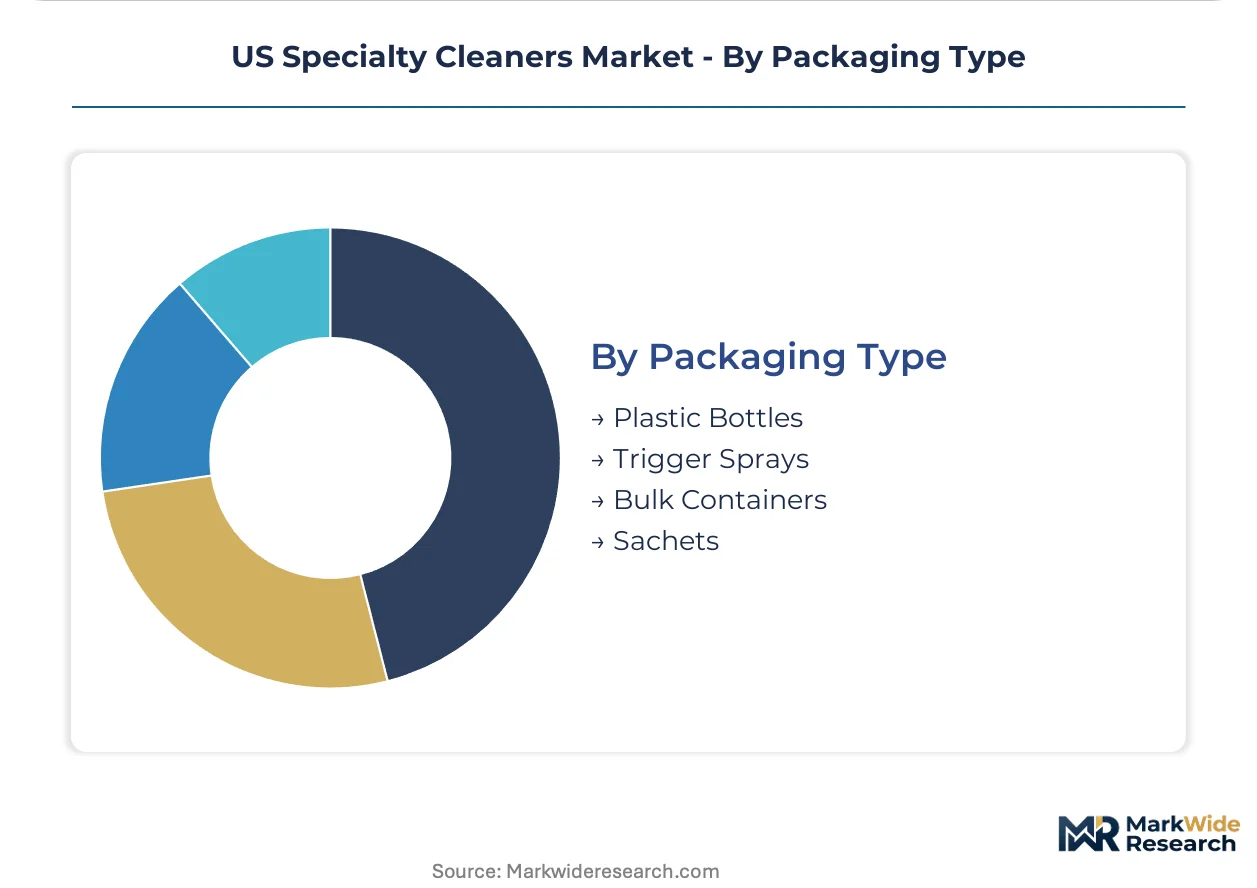
Packaging Type:
Container engineering balances chemical compatibility, dispensing precision, and reverse logistics burden.
- Trigger Sprays:Mechanical pump systems eliminate propellant requirements and enable adjustable spray patterns. California retail channels favor these for household and light commercial segments under volatile organic compound regulations.
- Bulk Containers:Refillable totes and drums serve high-throughput manufacturing and food processing plants with captive dilution systems.
- Plastic Bottles:Standard cylindrical containers dominate retail shelf presence and e-commerce fulfillment.
- Sachets:Single-use water-soluble pouches address hospitality amenity programs and field service applications where portability constraints apply.
Trigger sprays move the highest unit volume; bulk containers are advancing fastest as manufacturing procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration requirements anchor demand concentration in California and Texas, where healthcare networks and hospitality chains drive premium formulation procurement. State-level chemical restrictions in California cascade into neighboring markets, reshaping supplier compliance investments across the Southwest and Pacific Coast.
California
Healthcare facilities in Los Angeles and San Francisco mandate hospital-grade disinfectant protocols exceeding federal baseline standards. The Department of Toxic Substances Control advances Safer Consumer Products regulations targeting ortho-phthalate elimination. Integrated resort networks in Southern California centralize procurement around concentrate delivery systems to meet corporate waste reduction scorecards.
Texas
Medical centers in Houston and Dallas drive sporicidal efficacy specification demand through Joint Commission accreditation requirements. State environmental regulations lag California's chemical restriction trajectory, creating formulation flexibility for industrial degreaser suppliers. Petrochemical manufacturing clusters along the Gulf Coast generate captive demand for maintenance chemistry in downstream processing equipment.
Ohio
Automotive supplier corridors around Cleveland and Cincinnati remain underserved by specialty cleaner technical service networks concentrated on coastal markets. OSHA workplace exposure monitoring in metal fabrication shops constrains volatile organic compound formulation options. Procter & Gamble's Cincinnati R&D hub anchors enzyme-based degreaser development pipelines serving regional food processing equipment markets.
Michigan
Precision manufacturing in Detroit-area automotive assembly plants demands residue-free cleaning chemistry for coating adhesion protocols. State procurement offices increasingly reference USDA BioPreferred biobased content thresholds in institutional cleaning contracts. Midwestern distributor networks are consolidating managed chemical service relationships with multi-site manufacturing operators.
Illinois
Food processing plants in Chicago's industrial corridor pilot electrochemically activated water systems for conveyor sanitation cycles. State environmental regulators monitor California's chemical restriction cascades for potential adoption timelines. Bulk container refill systems in manufacturing procurement are displacing drum logistics for high-throughput cleaning operations.
US Specialty Cleaners Market Competitive Landscape
Diversified consumer goods conglomerates and industrial chemical specialists split the market across divergent channel access models. Consolidation pressure concentrates around EPA registration infrastructure ownership, where dedicated regulatory teams compress development timelines for established registrants. Three archetypes dominate: retail-brand conglomerates with R&D scale, industrial-focused chemical distributors with technical service embedding, and plant-derived formulation specialists capturing sustainability procurement mandates. Competitive moves center on managed chemical service contract consolidation and biobased feedstock supply chain anchoring.
Among consumer-brand conglomerates, Procter & Gamble, The Clorox Company, and SC Johnson occupy positions representing distinct formulation chemistry bets. Procter & Gamble exemplifies enzyme-based innovation archetypes through its Cincinnati research concentration. The Clorox Company anchors bleach-alternative disinfectant positioning within retail channel control frameworks. SC Johnson represents plant-derived solvent chemistry specialization against petrochemical formulation baselines. These three entities collectively illustrate how regulatory infrastructure scale and feedstock sourcing strategy determine competitive positioning in antimicrobial claim registration and sustainability specification capture.
| Leading Market Players |
|---|
| Procter & Gamble |
| The Clorox Company |
| SC Johnson & Son |
| ZEP Inc. |
| Reckitt Benckiser Group |
| Unilever |
| Grove Collaborative Inc. |
| Weiman Products LLC |
| Laticrete International Inc. |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast ethylene oxide and propylene oxide production clusters anchor surfactant precursor supply, concentrating margin capture among integrated petrochemical producers while mid-tier formulators face feedstock cost pass-through limitations. EPA registration infrastructure ownership determines pricing power in antimicrobial segments, where established registrants command premium positioning against commodity surfactant alternatives.
Pricing Analysis
California commands a 15-25% premium over Texas for hospital-grade disinfectant procurement, reflecting DTSC compliance costs and logistics density. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered sporicidal formulations from general-purpose surfactants and private-label alternatives. Cost compression in mid-tier enzymatic degreasers is intensifying because Procter & Gamble's Cincinnati R&D scale advantages compress competitor margins. Healthcare facilities exhibit lowest price sensitivity due to Joint Commission accreditation requirements, while food service operators prioritize concentrate economics over performance premiums.
Supply Chain Analysis
Tariff exposure between US Gulf Coast producers and specialty chemical importers from Germany and Japan dominates supply chain risk assessment for precision solvent formulations. Surfactant precursor supply concentrates in Texas, Louisiana, and coastal China, with ethylene oxide derivatives feeding domestic formulation plants. Raw material portfolios draw from petroleum distillates, plant-derived terpenes, and enzyme fermentation stocks. Single-source vulnerability persists in quaternary ammonium compound active ingredients, where limited EPA-registered suppliers constrain formulation flexibility. Distribution runs through industrial chemical distributors with embedded technical service teams, displacing direct manufacturer relationships in multi-site hospitality and healthcare accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defense story. EPA FIFRA registration infrastructure creates switching costs that entrench established players against commodity entrants, with 18-36 month approval timelines freezing out formulation innovators lacking dedicated compliance teams.
For Market Incumbents: Harden EPA registration asset monetization by extending active ingredient portfolios into emerging pathogen claims before patent cliffs erode quaternary ammonium compound exclusivity. Deepen backward integration into Gulf Coast surfactant precursor supply through offtake agreements with ethylene oxide producers, securing cost position against feedstock volatility. Channel control through managed chemical service contracts in California integrated resort networks creates captive demand with multi-year renewal visibility.
For New Entrants and Emerging Players: Establish a beachhead in Ohio and Michigan automotive supplier corridors, where coastal technical service networks remain underdeveloped and residue-free coating adhesion chemistry commands specification premiums. Target USDA BioPreferred procurement mandates in federal institutional contracts, where biobased content thresholds disadvantage petrochemical incumbents. A direct-to-plant technical service model with on-site dilution control equipment bypasses distributor consolidation in Midwestern manufacturing clusters.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial chemical distributors that have consolidated regional technical service networks but lack EPA registration infrastructure for antimicrobial claim expansion. Long-term viability hinges on regulatory entrenchment durability and biobased feedstock cost curve convergence against petroleum chemistry. The signal to watch is California DTSC chemical restriction cascade adoption timelines in neighboring Southwest states, which would accelerate compliant formulation substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Portfolio Expansion | Captures sporicidal claim exclusivity in Texas medical center procurement cycles. |
| Backward Integration into Surfactant Precursors | Secures ethylene oxide supply position against Gulf Coast petrochemical volatility. |
| Managed Chemical Service Contract Consolidation | Embeds inventory control systems at California hospitality operator sites. |
| USDA BioPreferred Certification Investment | Unlocks federal institutional procurement specifications for plant-derived formulations. |
| Midwestern Technical Service Network Buildout | Addresses automotive supplier corridor coverage gaps in Ohio and Michigan. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists at Procter & Gamble, SC Johnson, and The Clorox Company; procurement directors at California integrated health systems and Texas medical centers; plant managers at Midwestern food processing facilities; and technical service leads at ZEP Inc. and regional industrial distributors. Secondary validation drew from EPA FIFRA registration databases, OSHA permissible exposure limit documentation, California DTSC Safer Consumer Products regulatory filings, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling across product type, end user, delivery mode, and packaging format segments was triangulated against top-down macroeconomic indicators.
Calibration against historical EPA registration timeline data and surfactant feedstock price series anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry intensity, application environment contamination risk, operational logistics scale, and regional regulatory compliance tier. CAGRs were derived from regression analysis of procurement volume trends and specification intensity shifts. Industry-specific forecast inputs incorporated electrochemically activated water substitution rates in food processing and enzyme-based degreaser performance validation data from temperature-sensitive equipment trials.
Stress conditions across petrochemical feedstock volatility, EPA registration timeline extension, and California chemical restriction cascade adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding healthcare facility accreditation mandate persistence and hospitality sustainability procurement scorecard weighting. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Metal Polish Products Market