
 High Purity Argon Market | 2026-2036
High Purity Argon Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Argon Market Analytics
Buyer concentration among semiconductor foundries is expanding as tier-one chip manufacturers consolidate long-term supply agreements with industrial gas majors. Linde Plc leverages its on-site gas generation infrastructure to anchor contracts with leading wafer fabs across East Asia. Air Liquide competes through cryogenic logistics networks that sustain delivery reliability for electronics-grade argon customers. Messer SE & Co. KGaA specializes in regional merchant gas distribution, occupying niche positions in Central European metal fabrication markets.
High purity argon denotes argon refined to concentrations exceeding 99.999% through cryogenic air separation and adsorptive purification, serving primarily as an inert shielding medium and plasma carrier in precision manufacturing environments. Gaseous argon dominates electronics manufacturing applications where consistent flow rates protect silicon wafer integrity during thermal processing. Liquefied argon leads metal fabrication and welding segments, with cryogenic argon capturing emerging demand from superconducting magnet research institutions requiring ultra-low temperature baths.
FDA purity standards for pharmaceutical-grade argon and EPA emissions frameworks for air separation plants shape compliance costs and facility siting decisions in the United States. REACH registration requirements and the EU F-Gas Regulation constrain European import pathways and drive localized production investments. China's GB standards for electronic industrial gases and SAMR certification protocols filter market access for foreign suppliers. Stakeholders must monitor how semiconductor subsidy programs in the United States, Japan, and South Korea redirect argon demand toward newly commissioned fab locations.
Market Dynamics
Semiconductor foundries are consolidating argon procurement around on-site generation infrastructure, compressing merchant gas distribution margins and redirecting capital toward captive air separation investments in East Asian manufacturing corridors.
Growth Catalysts
- Wafer processing intensity:Advanced node fabrication below 7nm requires higher argon throughput per wafer for sputtering and thermal annealing processes.
- China's dual carbon goals:MEE emissions standards and GB purity mandates for electronic industrial gases are accelerating domestic air separation capacity expansion.
- REACH registration:ECHA compliance requirements for imported industrial gases are incentivizing European localized production investments.
Market Restraints
- Electricity cost volatility:Cryogenic air separation consumes 0.8-1.2 kWh per cubic meter of argon, exposing producers to grid price swings.
- Supply concentration:Three industrial gas majors control over 70% of electronics-grade argon liquefaction capacity in East Asia.
- Helium substitution limits:Superconducting magnet cooling applications cannot fully migrate to argon due to boiling point differentials.
Strategic Opportunities
- India's PLI scheme:Semiconductor fabrication subsidies are creating first-mover advantage for on-site gas generation contracts at greenfield fab sites.
- Space launch applications:Reusable rocket engine testing facilities are emerging as high-volume argon consumers for propulsion system inerting.
- Additive manufacturing:Electron beam melting systems for titanium aerospace components require ultra-high purity argon shielding environments.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for air separation plant operation and maintenance are concentrated among retiring workforces in Germany and Japan.
- GB/T 4842 certification timelines:Foreign suppliers face 18-24 month approval cycles for China's electronic-grade argon quality standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Argon Market |
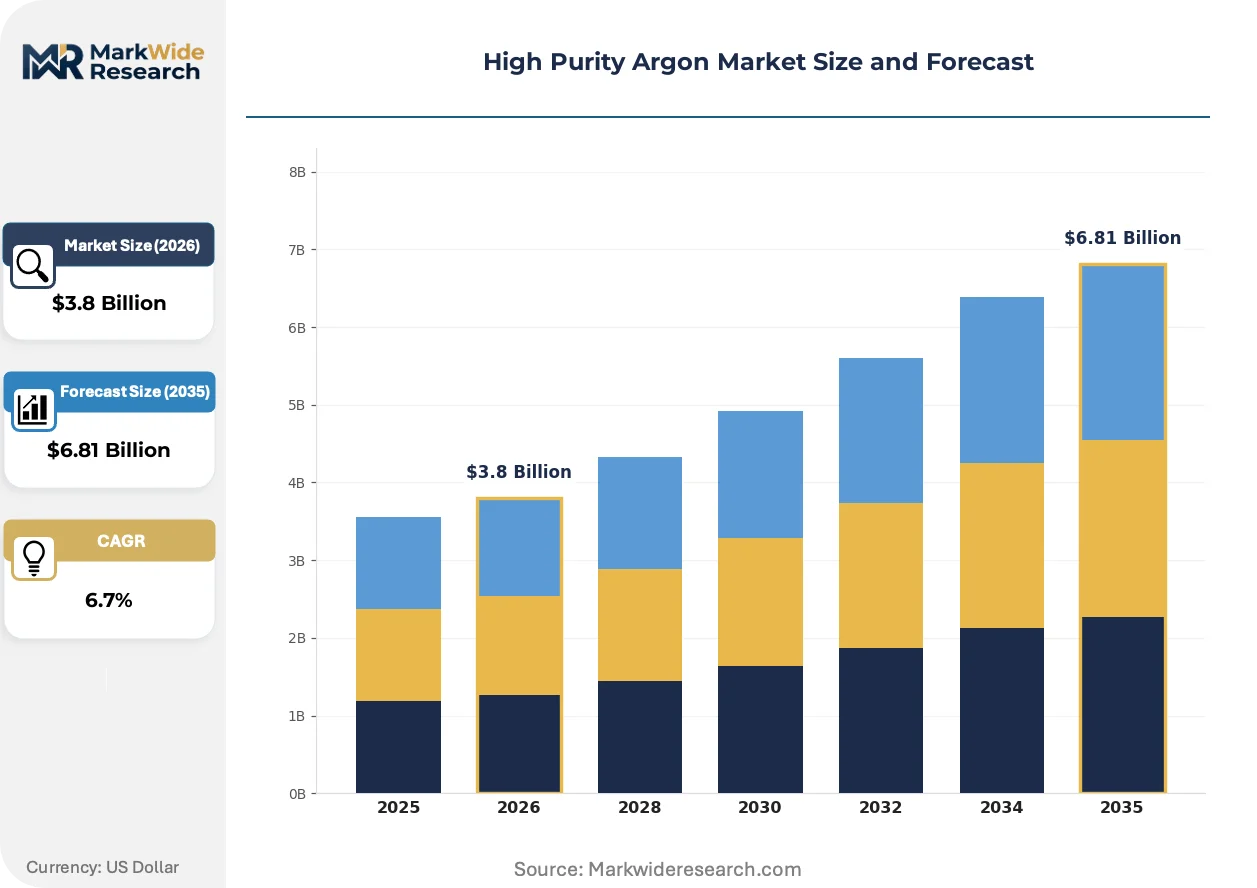
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefied Argon, Gaseous Argon, Argon Mixtures, Cryogenic Argon Application: Welding, Metal Fabrication, Electronics Manufacturing, Pharmaceuticals End User: Manufacturers, Research Institutions, Medical Facilities, Aerospace Distribution Channel: Direct Sales, Online Retailers, Distributors, Industrial Suppliers |
| Companies Covered | Linde Plc, Air Liquide, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Nippon Sanso Holdings Corporation, Iwatani Corporation, SOL Spa, Gruppo SIAD, Resonac Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Argon Market Evolving Landscape
Argon supply architecture is fragmenting as distributed generation technologies erode centralized merchant gas economics, while regulatory tightening around fluorinated gases and carbon intensity reshapes investment priorities.
Membrane separation technology is modularizing on-site argon recovery systems for mid-scale semiconductor fabs. Tier-two foundries in South Korea's Pyeongtaek corridor are deploying skid-mounted units to supplement bulk liquid deliveries. This distributed approach is compressing reliance on long-haul cryogenic trucking and enabling just-in-time purity management.
EPA emissions frameworks for air separation plants are tightening nitrogen oxide and particulate discharge limits. Facility siting decisions in Texas and Arizona now incorporate carbon capture readiness assessments. Merchant gas operators are responding by co-lating production with renewable energy assets to preserve contract eligibility with sustainability-mandated buyers.
Long-term take-or-pay contracts are displacing spot market purchases among leading wafer manufacturers. Samsung and TSMC procurement teams are negotiating 10-15 year supply agreements with built-in price escalation caps. This concentration of buyer commitment is most visible in Japan's Kyushu silicon island, where three mega-fabs have synchronized their argon tender cycles.
High Purity Argon Market Segmentation
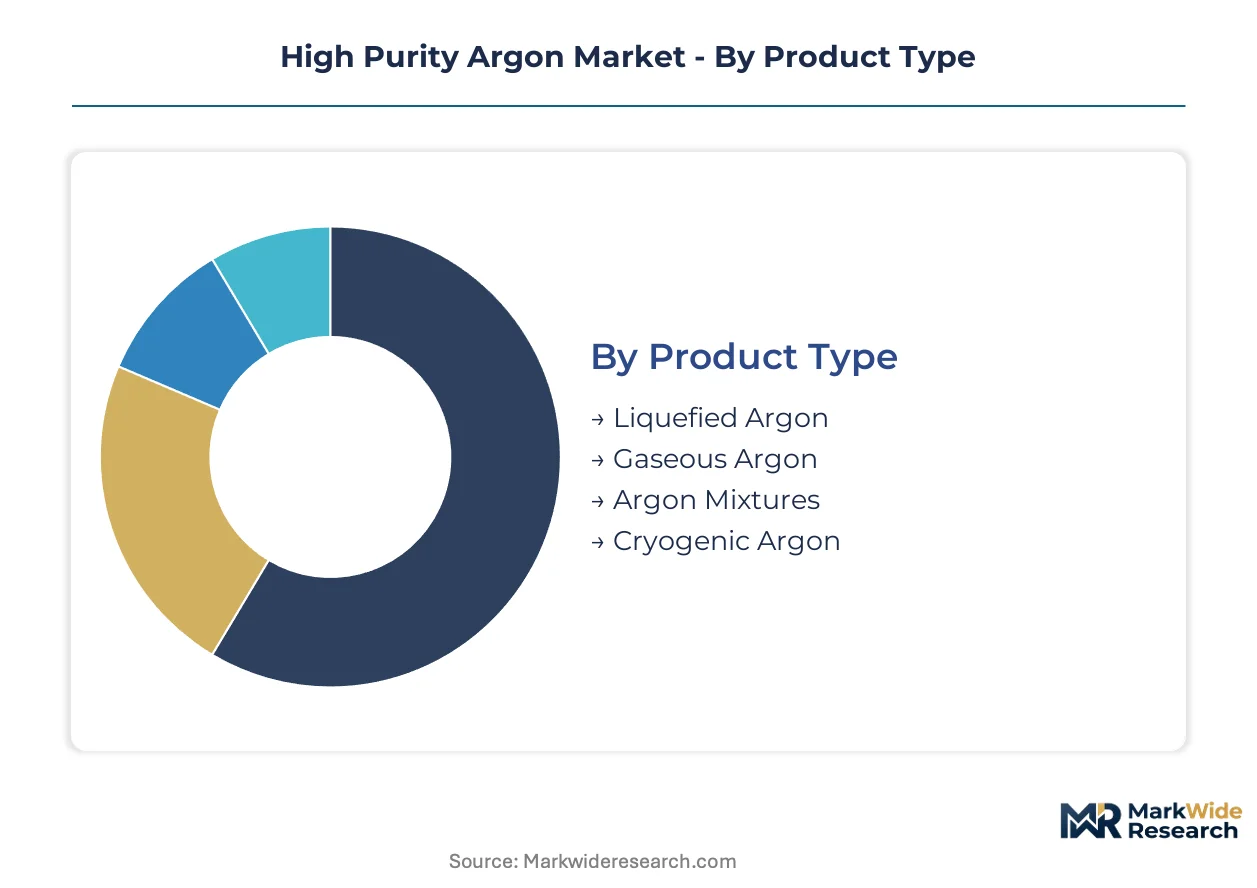
High purity argon supply chains fragment across four structural dimensions, each commanding distinct logistics infrastructure and margin profiles. Product form determines cryogenic handling requirements, while application concentration in semiconductor corridors reshapes regional production investments.
Product Type:
Supply concentration among cryogenic air separation majors tilts competitive leverage toward liquefaction scale and on-site generation capabilities.
- Liquefied Argon:Cryogenic liquid stored at minus 186 degrees Celsius enables dense bulk transport via specialized tanker fleets. Metal fabrication demand concentrates in Germany's Ruhr industrial belt and Japan's Chubu manufacturing corridor, where welding shops prioritize volume procurement over purity grades.
- Gaseous Argon:Vaporized from liquid storage or generated on-site through pressure swing adsorption, this form serves semiconductor foundries requiring uninterrupted flow rates. South Korea's Pyeongtaek corridor and Taiwan's Tainan Science Park anchor consumption for wafer sputtering and thermal annealing processes.
- Argon Mixtures:Blends with helium, hydrogen, or carbon dioxide tailor shielding properties for specialized welding applications. Aerospace contractors in France and Italy specify custom mixtures for titanium airframe joining operations.
- Cryogenic Argon:Ultra-cold liquid baths support superconducting magnet research at CERN in Switzerland and KEK in Japan, where boiling point stability matters more than volume throughput.
Today's leader: Liquefied Argon. Tomorrow's challenger: Gaseous Argon.
Application:
Cost tier stratification separates commodity welding consumption from premium electronics-grade contracts with tenfold purity multipliers.
- Electronics Manufacturing:99.9999% purity specifications govern argon for silicon wafer processing. Advanced node fabrication below 7nm demands higher throughput per wafer, concentrating procurement among TSMC, Samsung, and Intel fabs across Taiwan, South Korea, and Arizona.
- Welding:Standard purity grades suffice for arc shielding in structural steel and automotive assembly. German automotive suppliers and Japanese shipyards represent anchor demand for merchant gas distributors.
- Metal Fabrication:Laser cutting and plasma arc operations consume argon-helium mixtures for stainless steel processing. Italian and Spanish fabrication shops favor regional merchant suppliers over long-haul bulk deliveries.
- Pharmaceuticals:FDA and EMA pharmaceutical-grade certifications enable argon for drug packaging inerting and biological sample preservation. Swiss and Danish biologics manufacturers specify documented chain-of-custody protocols.
Electronics Manufacturing commands the steepest expansion trajectory as semiconductor subsidies redirect argon demand toward newly commissioned fab locations.
End User:
Customer type fragmentation splits procurement between long-term take-or-pay contracts and spot market flexibility.
- Manufacturers:Tier-one semiconductor foundries negotiate decade-long supply agreements with built-in price escalation caps. Chemical processors and specialty steel mills represent secondary volume demand.
- Research Institutions:CERN, DESY, and Brookhaven National Laboratory procure cryogenic argon for particle detector cooling and superconducting magnet maintenance. Grant-funded budgets constrain contract duration.
- Medical Facilities:Hospitals and cryobiology labs utilize argon for tissue preservation and surgical instrument sterilization. German and French university medical centers anchor European demand.
- Aerospace:Reusable rocket engine testing facilities at SpaceX McGregor and Blue Origin Kent emerge as high-volume consumers for propulsion system inerting and thermal protection verification.
Manufacturers dominate contract value. Aerospace represents the fastest-climbing consumption category.
Distribution Channel:
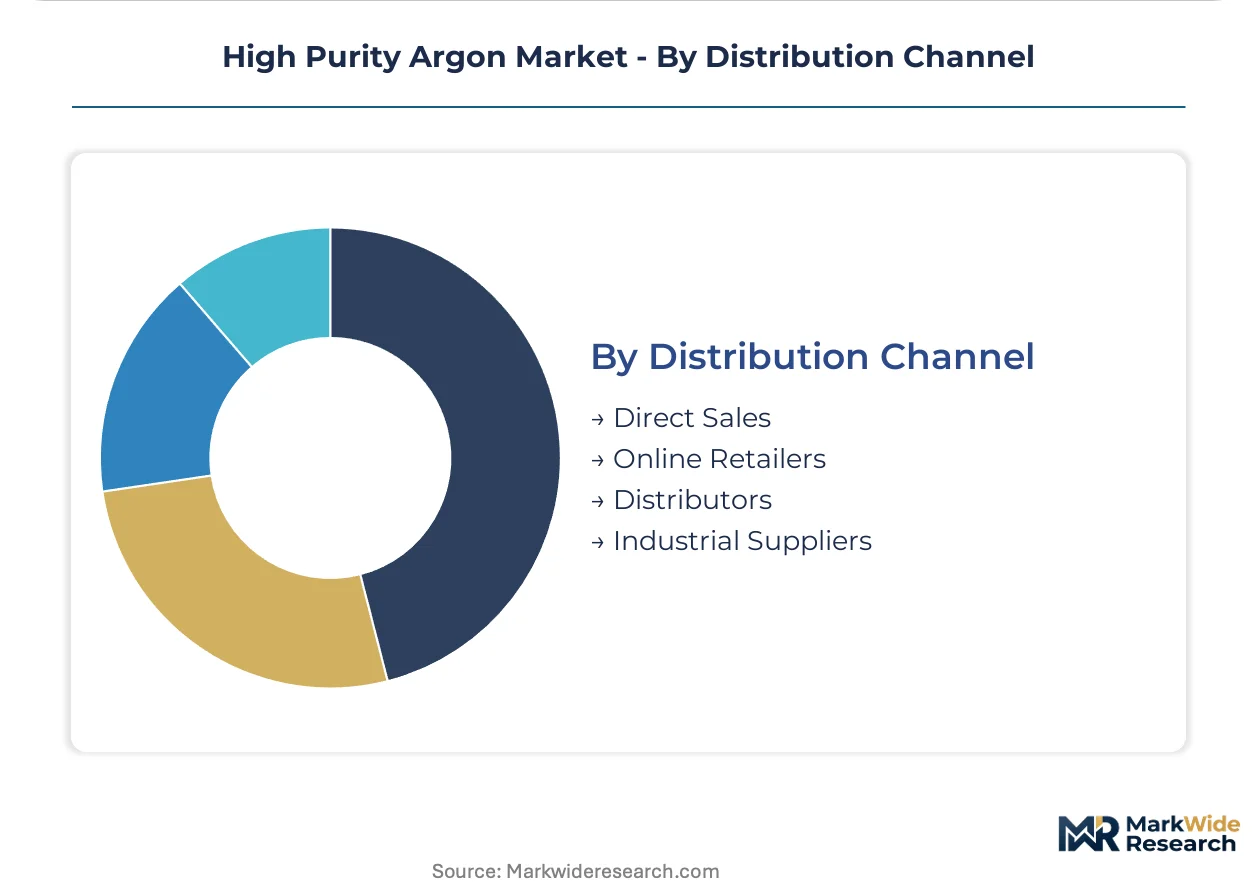
Margin compression in merchant gas distribution favors direct sales relationships with volume consumers.
- Direct Sales:Linde and Air Liquide deploy on-site generation infrastructure at semiconductor mega-fabs, bypassing liquid delivery economics entirely. Ten to fifteen year contracts lock in captive production arrangements.
- Distributors:Regional industrial gas specialists serve mid-scale metal fabricators with mixed gas cylinder programs. Central European distributors maintain density advantages through route-optimized delivery fleets.
- Industrial Suppliers:Welding equipment retailers bundle argon cylinders with MIG/TIG system sales. Italian and Polish distribution networks concentrate this channel.
- Online Retailers:E-commerce penetration remains marginal for cryogenic products, though specialty gas e-procurement platforms gain traction among research institutions with standardized purity requirements.
Direct Sales commands contract value concentration. Online Retailers face structural barriers in cryogenic logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic air separation expansion contrasts with South Korea's reliance on long-term import contracts for semiconductor-grade supply. Japan maintains captive production dominance through integrated industrial gas infrastructure. The United States and Germany anchor Western hemisphere capacity with diverging regulatory compliance costs.
China
MEE emissions standards and GB/T 4842 certification timelines are redirecting foreign supplier investments toward joint ventures with state-owned chemical enterprises. SAMR quality protocols filter market access through 18-24 month approval cycles. Yangtze River Delta fabrication clusters in Shanghai and Wuxi are absorbing domestic argon output from newly commissioned air separation units.
South Korea
Pyeongtaek semiconductor corridor fabs are consolidating procurement around on-site generation infrastructure for advanced node production below 7nm. MFDS pharmaceutical-grade specifications enable argon for biologics packaging applications. Busan-Ulsan industrial belt merchant gas distributors face margin compression from direct sales agreements at Samsung and SK Hynix facilities.
Japan
Kyushu silicon island mega-fabs have synchronized tender cycles toward decade-long take-or-pay contracts with built-in price escalation caps. METI industrial gas policy favors captive production investments over merchant distribution networks. Chubu manufacturing corridor welding shops maintain secondary demand for standard purity liquefied argon deliveries.
United States
CHIPS Act subsidies are redirecting argon demand toward Arizona and Texas greenfield fab locations with carbon capture readiness assessments. EPA nitrogen oxide discharge limits tighten air separation plant siting decisions in semiconductor corridors. SpaceX McGregor and Blue Origin Kent rocket testing facilities emerge as high-volume consumers for propulsion system inerting applications.
Germany
Ruhr industrial belt metal fabrication demand concentrates among regional merchant gas specialists with route-optimized delivery fleets. ECHA REACH registration requirements incentivize localized production investments over import-dependent supply chains. Bavarian automotive suppliers specify custom argon-helium mixtures for titanium airframe joining operations in aerospace subcontractor networks.
High Purity Argon Market Competitive Landscape
East Asian producers anchor the captive generation tier; European specialists hold merchant distribution density in metal fabrication corridors. Three industrial gas majors control over 70% of electronics-grade liquefaction capacity, compressing mid-scale competitor margins. Strategic archetypes separate into integrated air separation conglomerates, regional cylinder gas distributors, and on-site generation technology providers. Dominant competitive moves include backward integration into renewable energy assets and capacity co-location with semiconductor mega-fabs.
Within the integrated conglomerate tier, Linde Plc and Air Liquide exemplify scale-driven positioning through on-site infrastructure deployment. Messer SE & Co. KGaA occupies a specialist position in Central European merchant distribution. Nippon Sanso Holdings Corporation anchors Japanese captive production capabilities. These entities represent divergent geographic and service-model archetypes rather than direct substitutability in procurement decisions.
| Leading Market Players |
|---|
| Linde Plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer SE & Co. KGaA |
| Nippon Sanso Holdings Corporation |
| Iwatani Corporation |
| SOL Spa |
| Gruppo SIAD |
| Resonac Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Tier-one semiconductor foundries consolidating procurement around decade-long take-or-pay contracts have compressed spot market liquidity and anchored electronics-grade argon pricing to captive generation economics. This buyer concentration shifts pricing power toward producers with on-site infrastructure deployed at mega-fab locations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard purity grades while electronics-grade premiums widen. Contract-based long-term offtake dominates procurement, with price differentiation resting on GB/T 4842 certification status and volume scale commitments. Cost compression in merchant distribution is intensifying because on-site generation bypasses liquid delivery economics entirely. Mid-scale metal fabricators exhibit highest price sensitivity; semiconductor foundries with sustainability mandates show lowest.
Supply Chain Analysis
Cryogenic engineering talent scarcity in Germany and Japan constrains air separation plant commissioning timelines and maintenance capacity. Supply concentrates in China, South Korea, and the United States, with production drawing from specialized cryogenic equipment, high-purity adsorbent materials, and renewable energy feedstocks. Single-source vulnerability runs through East Asian electronics-grade liquefaction infrastructure. Distribution feeds from direct on-site generation at semiconductor mega-fabs, supplemented by regional merchant gas networks for welding and fabrication segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High purity argon offers margin expansion potential through the premium-tier shift toward 99.9999% electronics-grade specifications and on-site generation contracts that capture value from cryogenic logistics elimination.
For Market Incumbents: Extend captive generation footprints at greenfield semiconductor fabs in Arizona and Texas before CHIPS Act subsidies lock in competitor positions. Anchor long-term contracts with built-in price escalation caps to defend against merchant margin erosion from distributed membrane separation technology. For New Entrants and Emerging Players: Regional welding equipment retailers in Central Europe represent underexploited channel partners for cylinder gas programs targeting mid-scale fabricators. India's PLI scheme semiconductor subsidies create first-mover white space for skid-mounted on-site generation contracts at greenfield fab sites. For Investors and Strategic Acquirers: Industrial gas majors with renewable energy co-location capabilities are the most active acquirers in this space. Five-to-ten year viability favors targets with GB/T 4842 certification progress and established cryogenic logistics networks. Monitor SAMR approval timelines for foreign suppliers as inflection indicator for China market access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Deployment | Bypasses cryogenic trucking economics and locks in decade-long contracts with TSMC and Samsung fabs. |
| Renewable Energy Co-Location | Preserves contract eligibility with sustainability-mandated semiconductor buyers under EPA emissions frameworks. |
| GB/T 4842 Certification Investment | Opens market access to China's Yangtze River Delta fabrication clusters through SAMR quality protocols. |
| Membrane Separation Modularization | Enables tier-two foundries in South Korea's Pyeongtaek corridor to supplement bulk liquid deliveries. |
| Cryogenic Engineering Talent Pipeline | Addresses workforce scarcity constraining air separation plant commissioning in Germany and Japan. |
Research Methodology
Bottom-up semiconductor fabrication modeling reconciled against top-down air separation capacity tracking forms the analytical core. Primary interviews with plant managers at industrial gas facilities, procurement leads at tier-one foundries, and distribution channel partners in Central Europe combined with secondary validation from customs trade data, SEC filings of listed industrial gas majors, and MEE emissions disclosure records. Triangulation across these sources calibrated regional production estimates against consumption intensity metrics.
Input-output matrices mapped argon throughput per wafer across node generations against announced fab capacity expansions. Segmentation dimensions modeled include product form, application purity tier, end-user contract type, and regional regulatory cluster. CAGRs derived from slope analysis of capacity-constrained supply growth intersecting with demand projections from semiconductor equipment spend cycles and dual carbon policy implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CHIPS Act subsidy disbursement timing, GB/T 4842 certification approval velocity, and grid electricity price volatility affecting cryogenic separation economics. Forecasts reflect documented assumptions around semiconductor node migration schedules and carbon intensity regulations. Material deviation in SAMR market access protocols or MEE emissions enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Welding Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
3D Printing Gases Market