
 Recycled Thermoplastic Market | 2026-2036
Recycled Thermoplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Thermoplastic Market Analysis
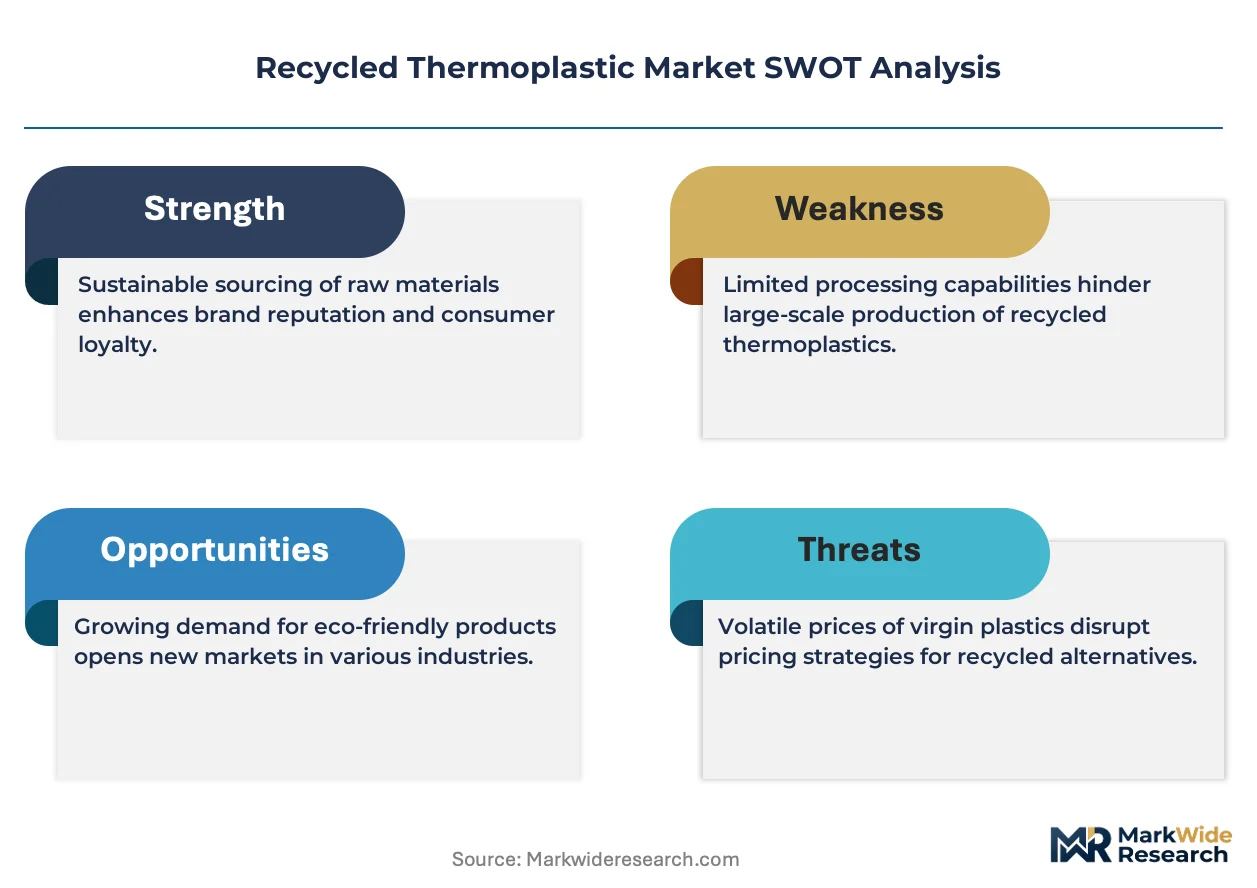
REACH compliance is realigning the cost-of-entry calculus for European resin suppliers, forcing upgrades in traceability and chemical safety documentation. Veolia leverages its integrated waste-to-polymer infrastructure across France and Benelux to sustain supply security for brand-owner contracts. KW Plastics anchors North American supply through its large-scale polypropylene reprocessing capacity in Alabama. Custom Polymers differentiates via specialized compounding services that bridge the gap between post-consumer flake and injection-grade pellet.
Recycled thermoplastics comprise post-industrial and post-consumer polymer streams that undergo sorting, washing, extrusion, and pelletization to achieve melt flow indices and mechanical properties suitable for re-manufacturing. Polyethylene dominates volume flows due to its prevalence in packaging film and bottle applications, though margin pools concentrate in prime-grade reprocessed polypropylene serving automotive underhood components. Thermoplastic elastomers represent the fastest-expanding product category as footwear and consumer goods brands pursue soft-touch recycled content. Within end-use industries, packaging absorbs the highest tonnage while automotive components command the strongest price premiums for certified prime-grade material meeting OEM volatile organic compound specifications.
The EPA enforces recycled content guidelines under federal procurement mandates, while the EU Green Deal's packaging and packaging waste regulation tightens collection targets and recycled content minimums for plastic containers. California's SB 54 imposes extended producer responsibility fees that directly alter the economics of virgin versus recycled resin selection for brands distributing in the state. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment supply chains into incompatible regional specifications that multiply certification burdens for multi-national material suppliers.
Market Dynamics
The EU Green Deal's recycled content mandates are compressing decision timelines for resin procurement, forcing automotive OEMs and packaging converters to requalify supply chains around certified post-consumer feedstock streams.
Growth Catalysts
- REACH compliance:ECHA's chemical safety documentation requirements are compelling European suppliers to upgrade traceability systems, creating competitive differentiation for compliant resin producers.
- Automotive lightweighting:OEMs are expanding reprocessed polypropylene procurement for underhood components to meet fuel efficiency targets without sacrificing thermal performance.
- Mechanical recycling infrastructure:Germany's industrial corridor concentration enables just-in-time flake-to-pellet supply chains that reduce logistics costs for converters.
Market Restraints
- Post-consumer feedstock volatility:Collection rates for polyethylene film fluctuate with municipal budget cycles, creating input cost instability for reprocessors.
- Food-contact certification barriers:FDA and EFSA approval timelines for recycled content in direct food applications extend 18-24 months, blocking rapid market entry.
- Prime-grade polypropylene scarcity:Automotive specifications for volatile organic compound emissions limit qualified suppliers to a narrow tier of reprocessors with advanced purification capacity.
Strategic Opportunities
- Thermoplastic elastomer expansion:Footwear brands are pursuing soft-touch recycled content for midsole applications, opening premium pricing tiers outside traditional packaging markets.
- Extended producer responsibility tailwinds:California's SB 54 fee structures are altering virgin-versus-recycled economics for brands distributing in the state, incentivizing localized reprocessing investment.
- Chemical recycling convergence:Pyrolysis and depolymerization technologies are bridging the gap between mechanically degraded feedstock and injection-grade pellet quality.
Industry Challenges
- Polymer identification skill gaps:Near-infrared spectroscopy and robotics integration require technicians trained in both materials science and automation maintenance.
- Multi-jurisdiction certification burdens:Compliance fragmentation between EPA guidelines, EU Green Deal mandates, and state-level EPR programs multiplies audit costs for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Thermoplastic Market |
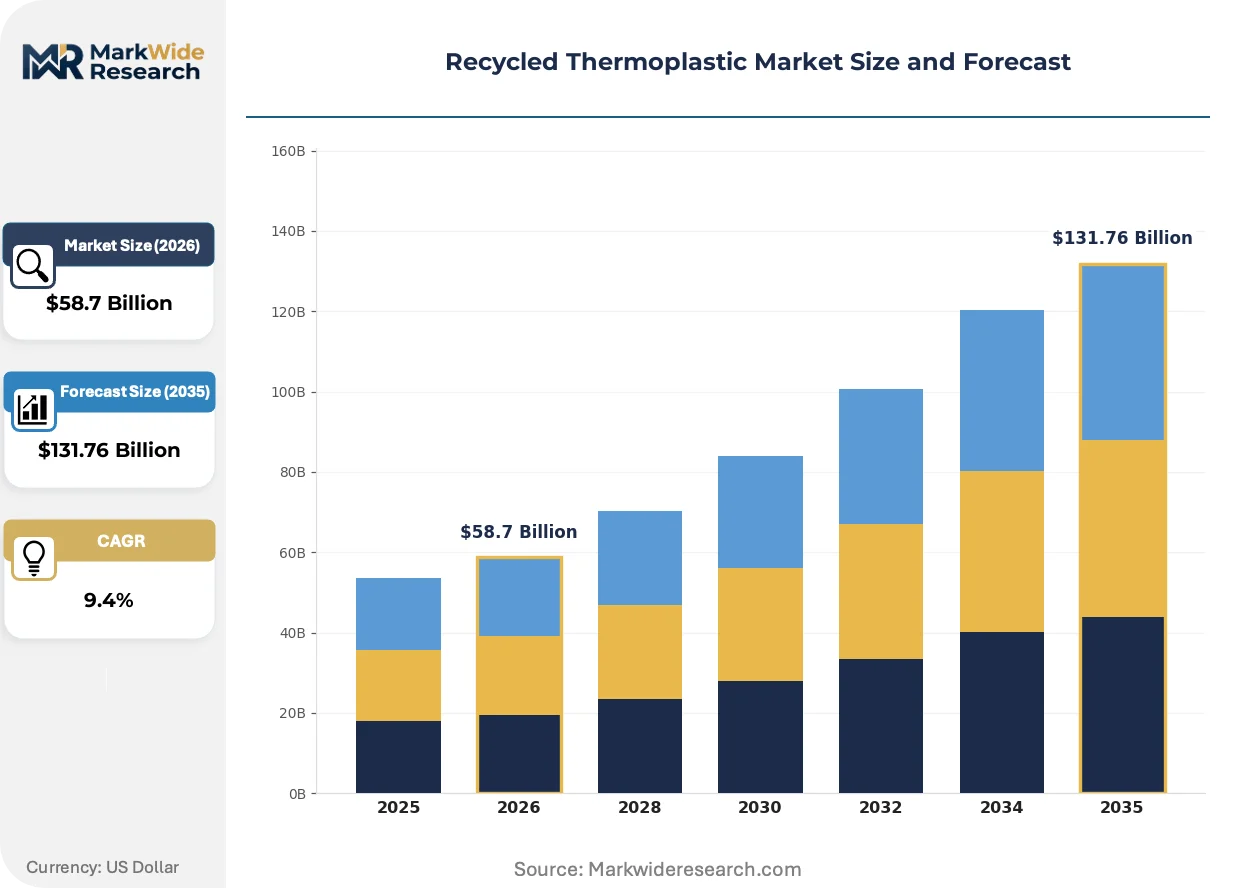
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Thermoplastic Elastomers End Use Industry: Packaging, Automotive Components, Consumer Goods, Electronics Quality Grade: Prime, Reprocessed, Off-Spec, Others Processing Technology: Injection Molding, Blow Molding, Extrusion, Film Casting |
| Companies Covered | B. Schoenberg & Co., Custom Polymers, Veolia, Fresh Pak Corporation, Envision Plastics, Plastipak Holdings, Clear Path Recycling, KW Plastics, Suez, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Thermoplastic Market Emerging Trajectories
Digital traceability platforms and advanced sorting technologies are compressing the cost structure of post-consumer resin qualification, enabling brand owners to verify chain-of-custody claims at batch-level granularity.
Advanced washing and extrusion systems with integrated melt-filtration are consolidating quality variance in post-consumer polyethylene streams. Packaging converters serving beverage and personal care brands are adopting these systems to meet EFSA food-contact specifications without blending down with virgin resin. The technology is consolidating margin pools around reprocessors capable of delivering consistent melt flow indices across seasonal feedstock fluctuations.
California's SB 54 extended producer responsibility framework is restructuring cost allocation across the packaging value chain. Brand owners now face direct fees based on virgin resin usage, compelling reformulation of procurement contracts to prioritize certified recycled content. The regulation is most acutely affecting multinational CPG companies with significant distribution exposure in the state.
Automotive OEMs are compressing supplier qualification cycles from 36 months to 18 months for interior and underhood components. Tier-1 manufacturers are responding by pre-certifying recycled polypropylene grades across multiple OEM specifications simultaneously. This pattern is most visible in Germany's automotive supply base, where proximity to mechanical recycling infrastructure enables rapid sample turnaround.
Recycled Thermoplastic Market Segmentation
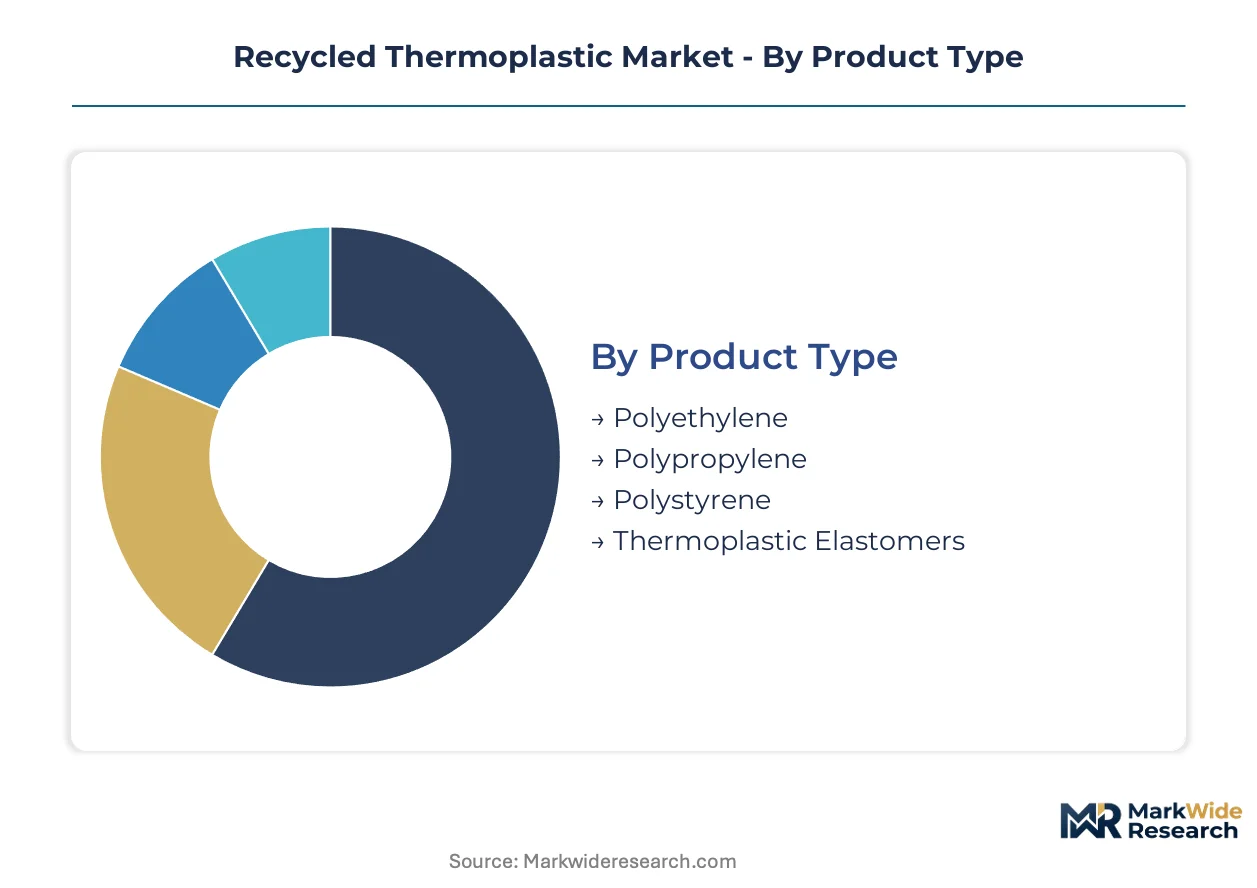
Segmentation in recycled thermoplastics reveals how technical specifications, regulatory thresholds, and processing constraints fragment procurement decisions across end-use industries. Each dimension—product chemistry, application requirements, quality certification, and conversion technology—creates distinct margin pools and supplier qualification barriers.
Product Type:
Standardization dominates commodity polyethylene and polypropylene streams, while thermoplastic elastomers demand customized compounding to match shore hardness and compression set specifications.
- Polyethylene:Post-consumer film and bottle streams undergo density-based sorting to produce LDPE, LLDPE, and HDPE fractions with controlled melt flow indices. Packaging converters in Germany's industrial corridor absorb the highest tonnage, though margin compression from virgin resin price volatility constrains reprocessor profitability.
- Polypropylene:Automotive underhood specifications for thermal stability and volatile organic compound emissions create stringent purification requirements. Tier-1 suppliers serving BMW and Volkswagen cluster near mechanical recycling infrastructure in Bavaria and Baden-Württemberg to enable rapid sample qualification cycles.
- Polystyrene:Expanded and crystal grades from packaging and construction waste face limited reprocessing infrastructure due to contamination sensitivity and low bulk density logistics costs.
- Thermoplastic Elastomers:TPV, TPU, and SEBS streams require specialized compounding to restore elasticity after thermal degradation. Footwear brands including Adidas and Nike specify recycled content for midsole applications, opening premium pricing tiers outside commodity packaging markets.
Leading the category by volume: Polyethylene. Growing fastest: Thermoplastic Elastomers.
End Use Industry:
Cost tier stratification separates packaging's high-volume, thin-margin procurement from automotive's certification-intensive, premium-grade sourcing.
- Packaging:Beverage, food, and personal care brands drive polyethylene and polypropylene demand under EU Green Deal recycled content mandates. EFSA food-contact approval timelines of 18-24 months block rapid market entry for uncertified reprocessors.
- Automotive Components:Interior trim, underhood housings, and bumper fascias require prime-grade polypropylene with documented chain-of-custody. OEM lightweighting targets expand reprocessed resin procurement, though volatile organic compound specifications limit qualified suppliers.
- Consumer Goods:Durables and housewares absorb off-spec and reprocessed grades where aesthetic consistency matters less than cost reduction. California's SB 54 extended producer responsibility fees alter virgin-versus-recycled economics for brands distributing in the state.
- Electronics:Housings and cable insulation demand flame-retardant compounded grades with restricted substance documentation under REACH and RoHS. Limited post-consumer feedstock availability for engineering thermoplastics constrains segment expansion.
Highest volume absorption: Packaging. Steepest margin expansion: Automotive Components.
Quality Grade:
Application maturity determines grade selection—established automotive and food-contact specifications enforce prime-grade procurement, while emerging applications tolerate broader quality variance.
- Prime:Certified post-consumer resin meeting OEM volatile organic compound specifications and EFSA food-contact standards commands strongest price premiums. Automotive Tier-1s pre-qualify grades across multiple OEM specifications simultaneously to compress 36-month qualification cycles.
- Reprocessed:Mechanically recycled flake-to-pellet streams suit non-critical applications in consumer goods and secondary packaging. Melt flow index consistency varies with seasonal feedstock fluctuations, requiring blending protocols or virgin resin dilution.
- Off-Spec:Batches deviating from target specifications find outlet in construction and agricultural applications where mechanical property variance carries lower liability. Pricing discounts of 30-50% versus prime grades reflect quality uncertainty.
- Others:Experimental and developmental grades from chemical recycling pilot plants bridge mechanically degraded feedstock and injection-grade quality. Pyrolysis and depolymerization outputs remain volume-constrained pending scale-up validation.
Widest procurement base: Reprocessed. Tightest supply: Prime.
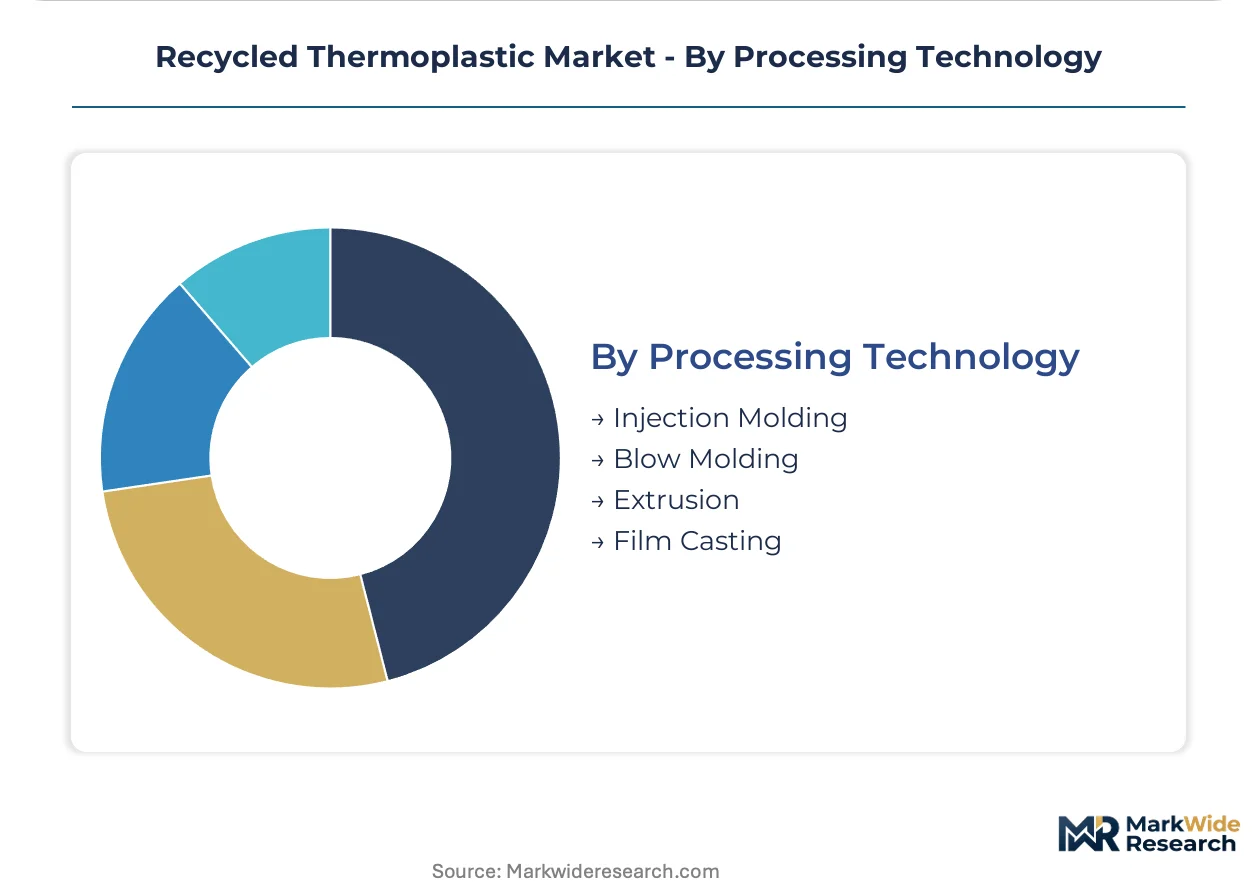
Processing Technology:
Customer type fragmentation separates brand-owner specification control from converter equipment constraints and reprocessor technical capabilities.
- Injection Molding:Automotive and electronics housings demand tight dimensional tolerance and surface finish, requiring pelletized feedstock with consistent melt flow indices. Germany's automotive supply base favors just-in-time flake-to-pellet supply chains to reduce inventory carrying costs.
- Blow Molding:Bottle and container production for beverage and personal care brands requires food-contact certified polyethylene with controlled parison swell characteristics. EFSA and FDA approval timelines constrain rapid formulation changes.
- Extrusion:Sheet, profile, and pipe applications tolerate broader melt viscosity ranges, enabling higher incorporation of reprocessed grades. Construction and agricultural markets absorb significant off-spec volume through this channel.
- Film Casting:Stretch film and barrier layer production demands exceptional clarity and mechanical consistency, limiting recycled content incorporation without advanced washing and melt-filtration systems. Packaging converters serving premium brands adopt these systems to meet specifications without virgin resin blending.
Most technically demanding: Film Casting. Highest recycled content tolerance: Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and packaging converters cluster near mechanical recycling infrastructure in Germany's industrial corridor, while regulatory divergence between jurisdictions segments supply chains into incompatible regional specifications.
United States
California's SB 54 extended producer responsibility fees alter virgin-versus-recycled economics for brands distributing in the state. The EPA enforces recycled content guidelines under federal procurement mandates. KW Plastics anchors North American supply through its large-scale polypropylene reprocessing capacity in Alabama.
Germany
BMW and Volkswagen procurement teams compress supplier qualification cycles from 36 months to 18 months for interior and underhood components. The EU Green Deal's recycled content mandates compel resin producers to reformulate supply chains. Tier-1 manufacturers cluster near mechanical recycling infrastructure in Bavaria and Baden-Württemberg to enable rapid sample turnaround.
France
Veolia leverages integrated waste-to-polymer infrastructure across France and Benelux to sustain supply security for brand-owner contracts. REACH compliance realigns cost-of-entry calculus for European resin suppliers. Automotive OEMs and packaging converters near Paris and Lyon benefit from proximity to advanced sorting and extrusion systems.
China
Packaging converters serving beverage and personal care brands adopt advanced washing and melt-filtration systems to meet quality specifications. The country's national environmental regulator tightens collection targets for plastic containers. Industrial clusters in the Yangtze River Delta and Pearl River Delta concentrate mechanical recycling capacity near converter demand.
Japan
Electronics manufacturers demand flame-retardant compounded grades with restricted substance documentation. METI guidelines shape recycled content procurement for durable goods producers. Industrial concentrations in Kanto and Kansai regions enable just-in-time flake-to-pellet supply chains for precision molding applications.
Recycled Thermoplastic Market Vendor Landscape
North American producers anchor one tier; European specialists hold certification-intensive positions serving automotive OEMs. The vendor base separates into consolidated waste-to-polymer integrators, mid-scale reprocessors with regional feedstock control, and specialized compounders bridging flake-to-pellet quality gaps. Three archetypes dominate: infrastructure-heavy integrators, technology-focused purifiers, and formulation-centric compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves as reprocessors secure brand-owner contracts.
Among North American reprocessors, Custom Polymers and KW Plastics occupy positions reflecting different scale and specialization archetypes. Veolia exemplifies the integrated waste-to-polymer model through its European infrastructure holdings. These three entities represent the competitive spectrum from specialized compounding services to large-scale polypropylene reprocessing to vertically integrated waste management systems.
| Leading Market Players |
|---|
| B. Schoenberg & Co. |
| Custom Polymers |
| Veolia |
| Fresh Pak Corporation |
| Envision Plastics |
| Plastipak Holdings |
| Clear Path Recycling |
| KW Plastics |
| Suez |
| Others |
Supply Flow & Price Mechanics
Polymer identification technicians concentrated in Germany's industrial corridor command wage premiums that compress margin spreads between prime-grade automotive polypropylene and standard reprocessed polyethylene. REACH documentation requirements and EFSA food-contact certification timelines extend cost structures for compliant resin producers, widening the labor-cost differential between certified and uncertified supply tiers.
Pricing Analysis
Volume flows concentrate in commodity polyethylene packaging grades where thin margins reflect virgin resin price volatility, while automotive prime-grade polypropylene commands substantial premiums for volatile organic compound compliance and documented chain-of-custody. Three-tier pricing structure across prime, reprocessed, and off-spec grades separates certified automotive feedstock from packaging-grade flake and construction-bound off-spec batches. Cost compression in standard polyethylene streams is intensifying because municipal collection budget cycles create feedstock input instability. Packaging converters serving beverage brands exhibit highest price sensitivity due to thin conversion margins, while automotive Tier-1 suppliers prioritize qualification security over unit cost.
Supply Chain Analysis
Certification and qualification gating through EFSA food-contact timelines and OEM volatile organic compound specifications fragments supplier bases into narrow tiers of compliant reprocessors. Supply concentrates in Germany, the United States, and China, with mechanical recycling infrastructure clustering near automotive OEMs in Bavaria and packaging converters in the Yangtze River Delta. Raw material dependencies include post-consumer polyethylene film collections, polypropylene automotive scrap streams, and thermoplastic elastomer manufacturing offcuts. Single-source vulnerability runs through limited prime-grade polypropylene reprocessors with advanced purification capacity. Distribution runs through just-in-time flake-to-pellet supply chains serving Germany's automotive corridor and long-term offtake contracts for North American packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal recycled content mandates and REACH documentation requirements erect barrier-to-entry moats favoring reprocessors with pre-existing certification infrastructure.
For Market Incumbents: Acquire advanced melt-filtration and washing systems to defend prime-grade positioning against chemical recycling entrants. Expand backward integration into post-consumer collection networks to secure feedstock volume stability against municipal budget volatility. Pre-qualify resin grades across multiple OEM specifications simultaneously to compress 18-month qualification cycles into competitive advantage.
For New Entrants and Emerging Players: Mid-tier footwear brands seeking soft-touch recycled content for midsole applications represent the most penetrable buyer archetype outside saturated packaging markets. California-based consumer goods distributors facing SB 54 extended producer responsibility fees offer localized entry points with regulatory tailwinds. Pursue specialized thermoplastic elastomer compounding partnerships to bypass prime-grade polypropylene certification barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated waste-to-polymer operators given EU Green Deal packaging waste regulation tightening collection targets. Long-term viability centers on reprocessors with captive feedstock control and multi-jurisdiction certification infrastructure. Watch pyrolysis and depolymerization scale-up validation as inflection signal for chemical recycling displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive post-consumer feedstock secures volume stability against municipal budget cycles. |
| Multi-OEM Pre-Qualification Programs | Compressed 18-month cycles create switching costs for automotive Tier-1 procurement teams. |
| Advanced Melt-Filtration System Deployment | EFSA food-contact compliance enables premium pricing in beverage packaging segments. |
| Thermoplastic Elastomer Compounding Capacity | Footwear brand contracts open margin pools outside commodity polyethylene markets. |
| Chemical Recycling Pilot Scale-Up | Pyrolysis validation bridges mechanically degraded feedstock and injection-grade quality. |
Methodological Framework
Independent corroboration across reprocessor technical directors, automotive Tier-1 procurement managers, and packaging converter operations heads underwrites the qualitative findings. Primary interviews with EFSA regulatory consultants, Veolia waste-to-polymer integration specialists, and KW Plastics plant engineers combined with secondary validation from EU Green Deal implementation reports, EPA procurement guideline filings, and ACC plastics recycling statistics. Bottom-up resin flow modeling and top-down end-use demand estimation triangulate volume and value outputs.
Comparable-period anchoring to historical mechanical recycling capacity utilization and automotive lightweighting procurement trends established the forecast window baseline. Segmentation modeling spans product chemistry, quality grade tier, end-use industry, and processing technology dimensions across the projection horizon. CAGRs derive from regression analysis against feedstock collection rate trajectories and regulatory mandate implementation schedules. Forecast inputs include OEM volatile organic compound specification tightening timelines and extended producer responsibility fee structure evolution.
Revisions become necessary when chemical recycling scale-up accelerates beyond pilot-phase validation or when EU Green Deal recycled content mandates tighten faster than mechanical recycling capacity expansion. Forecasts reflect assumptions about feedstock collection infrastructure investment continuity and automotive qualification cycle compression sustainability. A model refresh is warranted upon material change in EFSA food-contact approval timelines or California SB 54 fee structure amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Plastic Ignition Holders Market