
 Rubber Conveyor Belt Market | 2026-2036
Rubber Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Conveyor Belt Market Analysis
Synthetic polymer compounds is decoupling rubber conveyor belt economics from natural rubber price volatility. Continental AG leverages captive polymer research to sustain margin stability across heavy duty grades. Bridgestone Corporation anchors Asia-Pacific supply through integrated manufacturing in Japan and Thailand. Fenner Dunlop competes in mining-specialized belting with deep technical service networks across Australian and South African operations.
A rubber conveyor belt consists of layered elastomeric compounds reinforced with fabric or steel cord carcasses, engineered to tensile strengths exceeding 3,000 N/mm for heavy load transport over extended distances. The product conveys bulk and unitized materials through continuous friction-driven motion in industrial processing and distribution systems. Heavy duty belting dominates value pools due to mining replacement cycles and extreme operating conditions. Flame retardant grades are expanding fastest as underground safety regulations tighten across multiple jurisdictions. Bulk handling applications concentrate volume demand where coal, iron ore, and aggregate throughput requirements dictate specifications.
OSHA mandates in the United States govern workplace conveyor safety and emergency stop protocols, while REACH and RoHS frameworks in Europe restrict hazardous substance content in rubber compounds. China's GB standards and SAMR oversight enforce domestic quality certification for industrial belting imports. Stakeholders must monitor evolving fire safety classifications and polymer sustainability requirements as procurement criteria shift toward lifecycle accountability and carbon disclosure alignment.
Market Dynamics
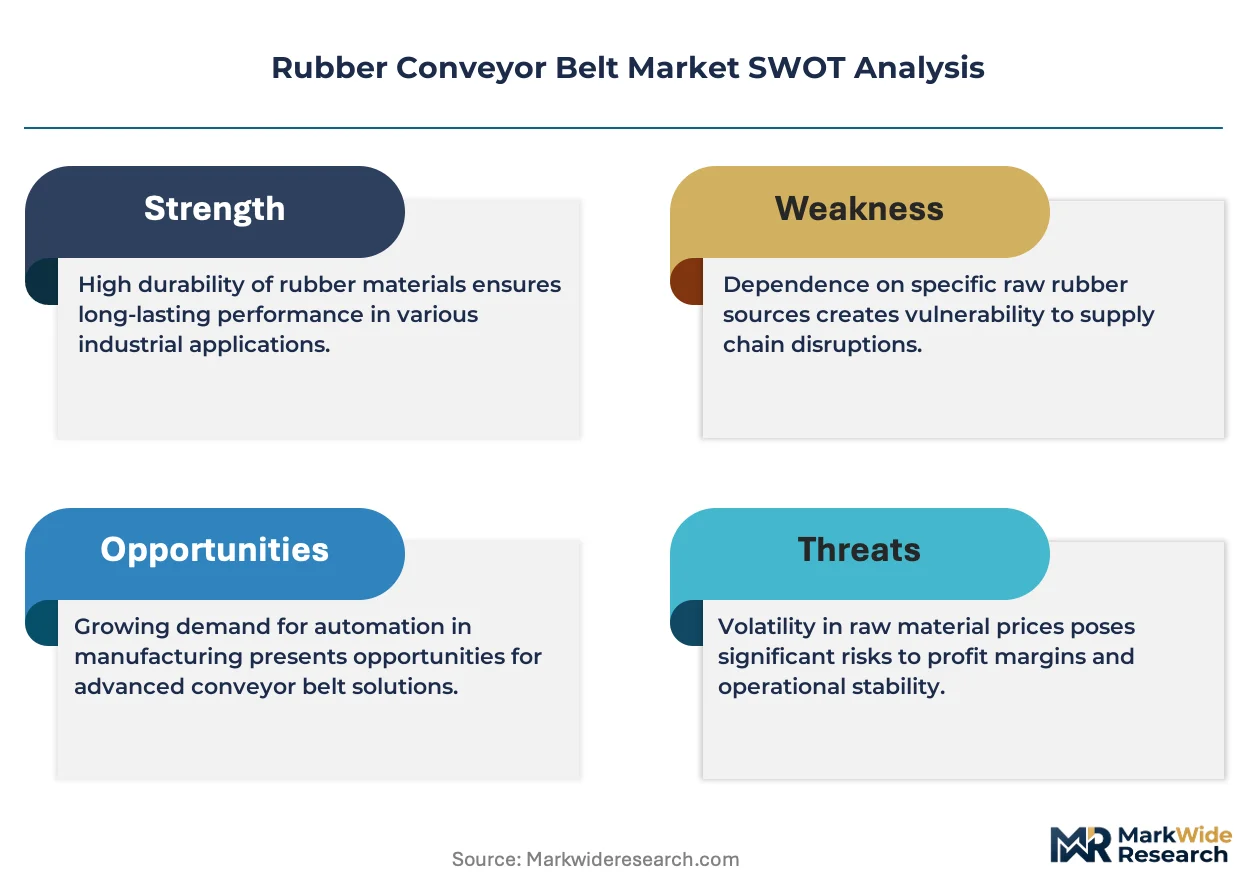
Synthetic polymer substitution is decoupling belt economics from natural rubber volatility, while MSHA flame retardant mandates and REACH compliance are compressing supplier margins and forcing compound reformulation across heavy duty grades.
Growth Catalysts
- MSHA flame retardant standards:Underground mining safety mandates in the United States are accelerating replacement cycles for certified belting in coal and metal ore operations.
- Steel and cement production clusters:China's industrial corridor provinces sustain continuous demand for heat-resistant and abrasion-grade conveyor systems in bulk material handling.
- Copper and iron ore throughput expansion:Mining operators in Australia and Chile are commissioning new bulk handling infrastructure to match export volume targets.
Market Restraints
- Petrochemical feedstock volatility:Synthetic rubber and polymer compound costs fluctuate with crude oil derivatives, compressing margin stability for non-integrated manufacturers.
- Cartridge belt import concentration:Standard-grade light duty belting faces price pressure from concentrated Southeast Asian supply, limiting pricing power for regional producers.
- Steel cord substitution limits:Extreme tensile requirements above 5,000 N/mm remain technically constrained by fabric carcass performance ceilings in ultra-deep mining applications.
Strategic Opportunities
- EU Green Deal carbon disclosure alignment:Lifecycle accountability requirements are creating procurement preference for suppliers with polymer recycling capabilities and embodied carbon transparency.
- Desalination and phosphate handling:Chemical-resistant belt grades are penetrating water treatment and fertilizer processing applications previously served by alternative conveying methods.
- Digital monitoring integration:Embedded sensor layers enabling predictive maintenance are opening premium pricing tiers for condition-monitored belting in critical path operations.
Industry Challenges
- Compound formulation expertise scarcity:REACH and RoHS substance restrictions require specialized polymer chemistry capabilities that outpace current technical workforce supply.
- Multi-jurisdiction certification timelines:Simultaneous GB standard, MSHA, and CE marking approvals extend product launch cycles by 12-18 months for new belt constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Conveyor Belt Market |
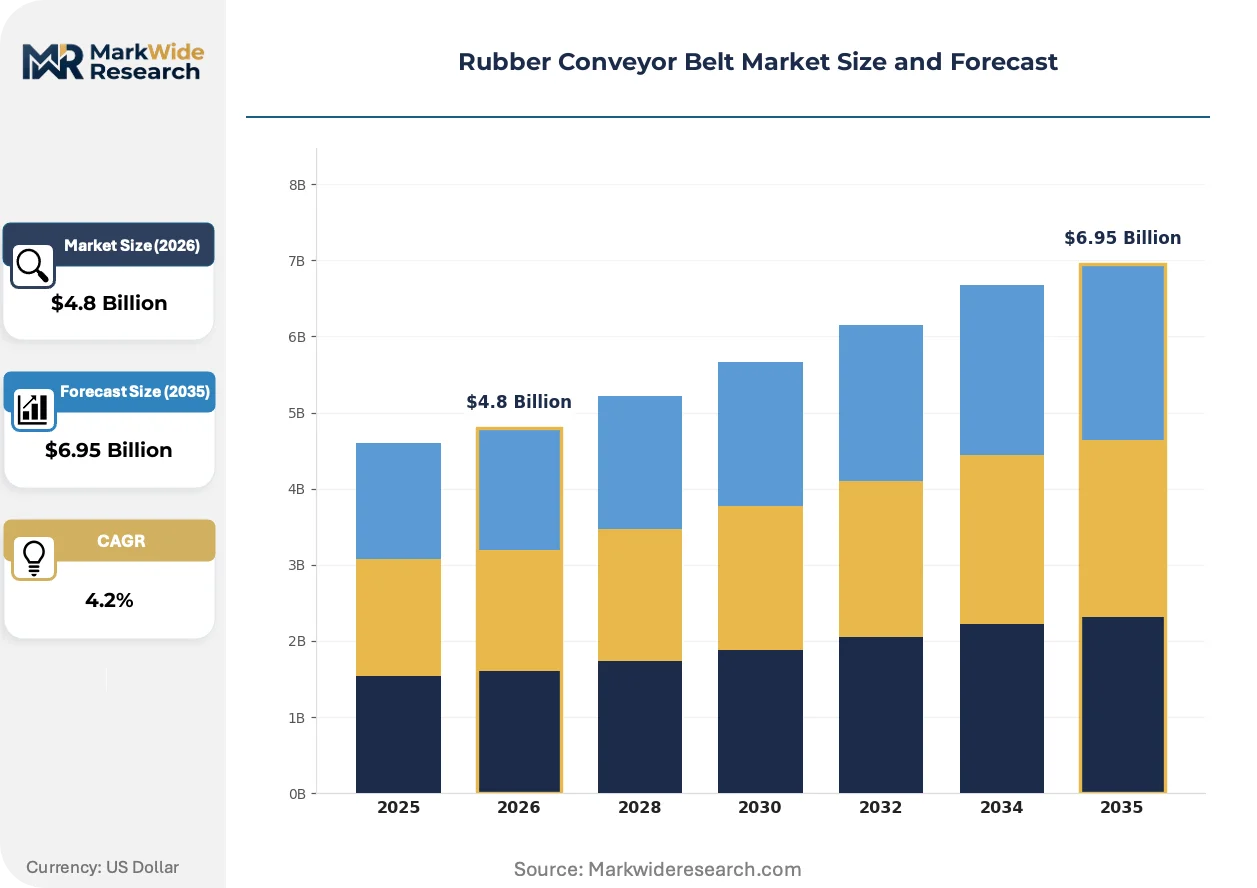
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Heavy Duty, Oil Resistant, Flame Retardant End User: Mining, Agriculture, Construction, Manufacturing Application: Bulk Handling, Package Handling, Mining Operations, Food Processing Material Grade: EPDM, Nitrile, Neoprene, SBR |
| Companies Covered | Continental AG, Bridgestone Corporation, Fenner Dunlop, The Yokohama Rubber Co. Ltd., Bando Chemical Industries Ltd., Sempertrans, Zhejiang Double Arrow Rubber Co. Ltd., Goodyear Rubber Products, Qingdao Rubber Six Conveyor Belt Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Conveyor Belt Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape belt construction priorities, with durability metrics and environmental compliance displacing pure cost optimization in procurement criteria.
Aramid fiber reinforcement is consolidating market share in medium-duty applications where weight reduction and flex fatigue resistance outweigh steel cord tensile supremacy. Mining maintenance departments in Chile and Australia are specifying aramid carcasses for overland conveyors exceeding 15 kilometers. This consolidation is compressing demand for traditional nylon-polyester multi-ply constructions in non-critical path installations.
REACH substance restriction amendments are forcing systematic elimination of short-chain chlorinated paraffins and selected plasticizers from rubber compounds across European supply chains. Compounders are accelerating bio-based plasticizer and alternative flame retardant validation programs to maintain market access. Heavy duty underground grades face the steepest compliance cost escalation, with reformulated compounds undergoing extended MSHA and ECHA dual certification protocols.
Lifecycle service contracting is displacing transactional belt procurement in Australian and South African mining operations, with suppliers assuming responsibility for installation, splicing, and scheduled replacement. This model transfers inventory carrying costs and technical risk to manufacturers while locking in multi-year volume commitments. Procurement teams in iron ore and coal export terminals are consolidating supplier panels to capture total cost of ownership advantages from integrated service agreements.
Rubber Conveyor Belt Market Segmentation
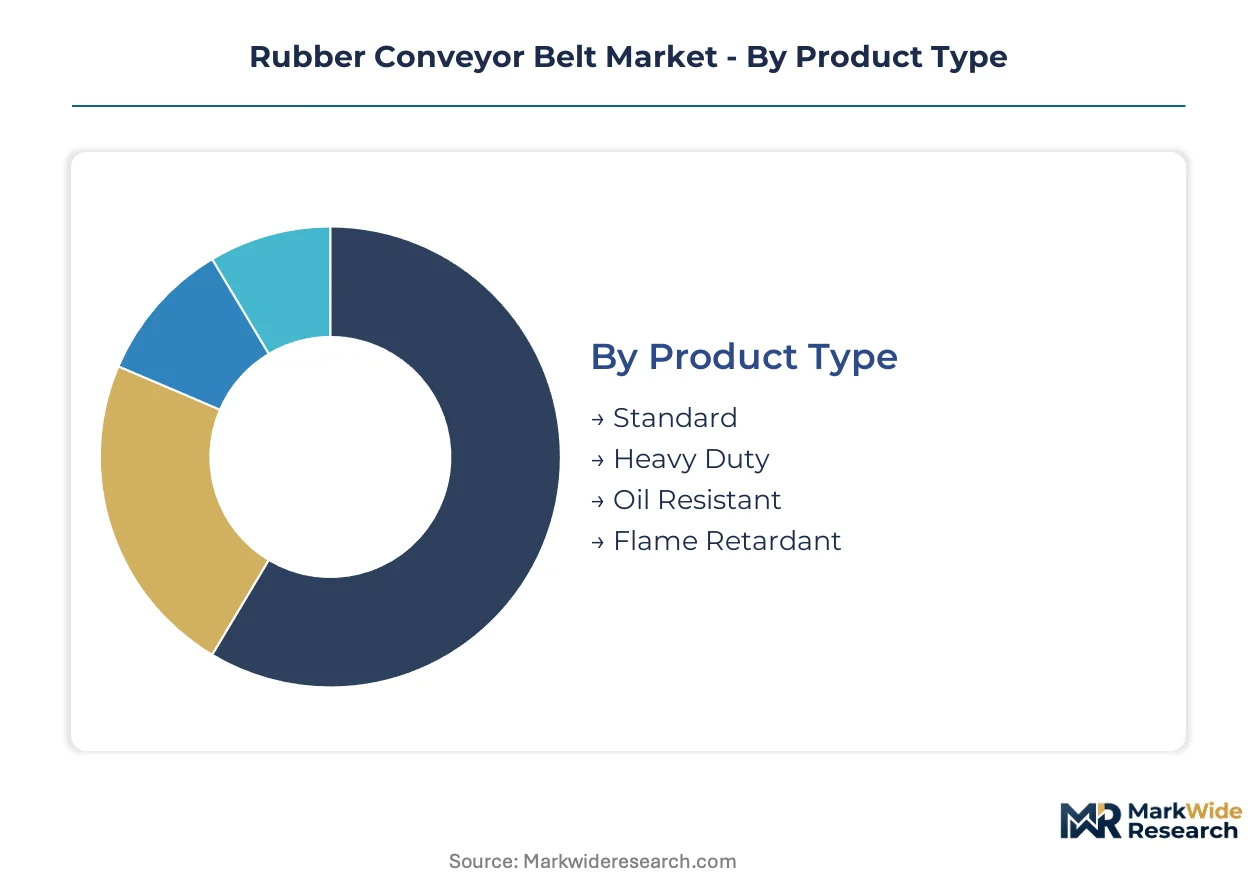
Rubber conveyor belt procurement hinges on matching compound specifications to operational hazards, with certification requirements varying sharply across mining depth, chemical exposure, and temperature extremes. Segmentation discipline separates premium-grade suppliers from commodity competitors.
Product Type:
Certification burden falls heaviest on underground-rated constructions, where MSHA flame retardant approval and REACH substance compliance create dual-track validation requirements for suppliers serving cross-border mining operations.
- Standard:General-purpose constructions using SBR or natural rubber blends for ambient-temperature bulk handling in surface applications. Agricultural grain elevators and package distribution centers in China's Henan and Shandong provinces sustain replacement demand for economy-grade plied constructions.
- Heavy Duty:Steel cord or multi-ply fabric carcasses rated above 2,500 N/mm tensile strength, engineered for iron ore and copper concentrate transport over 10+ kilometer distances. Australian Pilbara operations and Chilean Atacama mines specify these grades for 24/7 continuous duty cycles exceeding 50,000 operating hours.
- Oil Resistant:Nitrile-blend compounds for petrochemical handling and vegetable oil processing environments. Food-grade variants serve palm oil refineries in Malaysia and soybean crushing facilities in Argentina.
- Flame Retardant:Halogen-free or low-smoke formulations meeting MSHA 30 CFR Part 14 and EN 12882 fire safety classifications for underground coal and metal mining.
Heavy Duty sits at the top of the volume ranking, with Flame Retardant climbing the fastest.
End User:
Customer scale determines service model intensity, with tier-one miners demanding lifecycle contracting while smaller agricultural and construction buyers transact on spot replacement cycles.
- Mining:Surface and underground extractive operations consuming 60-meter-plus belt widths for overland conveying systems. Copper porphyry deposits in Chile's Antofagasta Region and Western Australia's iron ore belt drive specification intensity for abrasion-resistant carcasses.
- Agriculture:Grain handling terminals and oilseed processing plants requiring moderate-duty constructions with FDA-compliant food-contact surfaces. Brazilian soybean export terminals and US Midwest elevator cooperatives concentrate seasonal procurement.
- Construction:Aggregate quarries and cement plants utilizing portable crushing and screening circuits. Limestone and granite operations in India's Rajasthan and Andhra Pradesh states generate continuous demand for impact-resistant belt edges.
- Manufacturing:Assembly line and warehousing applications favoring lightweight PVC or PU alternatives, with rubber retaining share only in high-temperature or heavy-load process stages.
Mining commands the dominant procurement volume, though Agriculture shows the steepest expansion trajectory as grain export infrastructure modernizes across South America and the Black Sea region.
Application:
Operating environment severity dictates carcass construction and cover compound thickness, with bulk mineral handling imposing the most extreme mechanical and thermal stresses.
- Bulk Handling:Continuous transport of coal, iron ore, bauxite, and phosphate rock through fixed and mobile stacking systems. Dust suppression requirements and 24/7 duty cycles favor steel cord constructions with 15mm-plus top cover thickness.
- Package Handling:Logistics and distribution center sortation requiring precision tracking and low-noise operation. E-commerce fulfillment growth in Germany's Rhine-Ruhr corridor and Japan's Kanto Plain sustains demand for fabric-ply constructions with specialized friction coatings.
- Mining Operations:Integrated extraction-to-processing circuits including primary crushing, overland transport, and stockyard reclaim. Deep-level gold and platinum operations in South Africa's Witwatersrand Basin specify flame-retardant steel cord grades for vertical shaft hoisting and decline conveyor applications.
- Food Processing:Bakery, meat, and dairy conveying requiring temperature resistance from -40°C freezing tunnels to 120°C baking ovens. EU hygiene regulations and USDA dairy grade standards constrain compound formulation options.
Bulk Handling anchors procurement volumes, while Food Processing gains share fastest on regulatory upgrading in emerging markets.
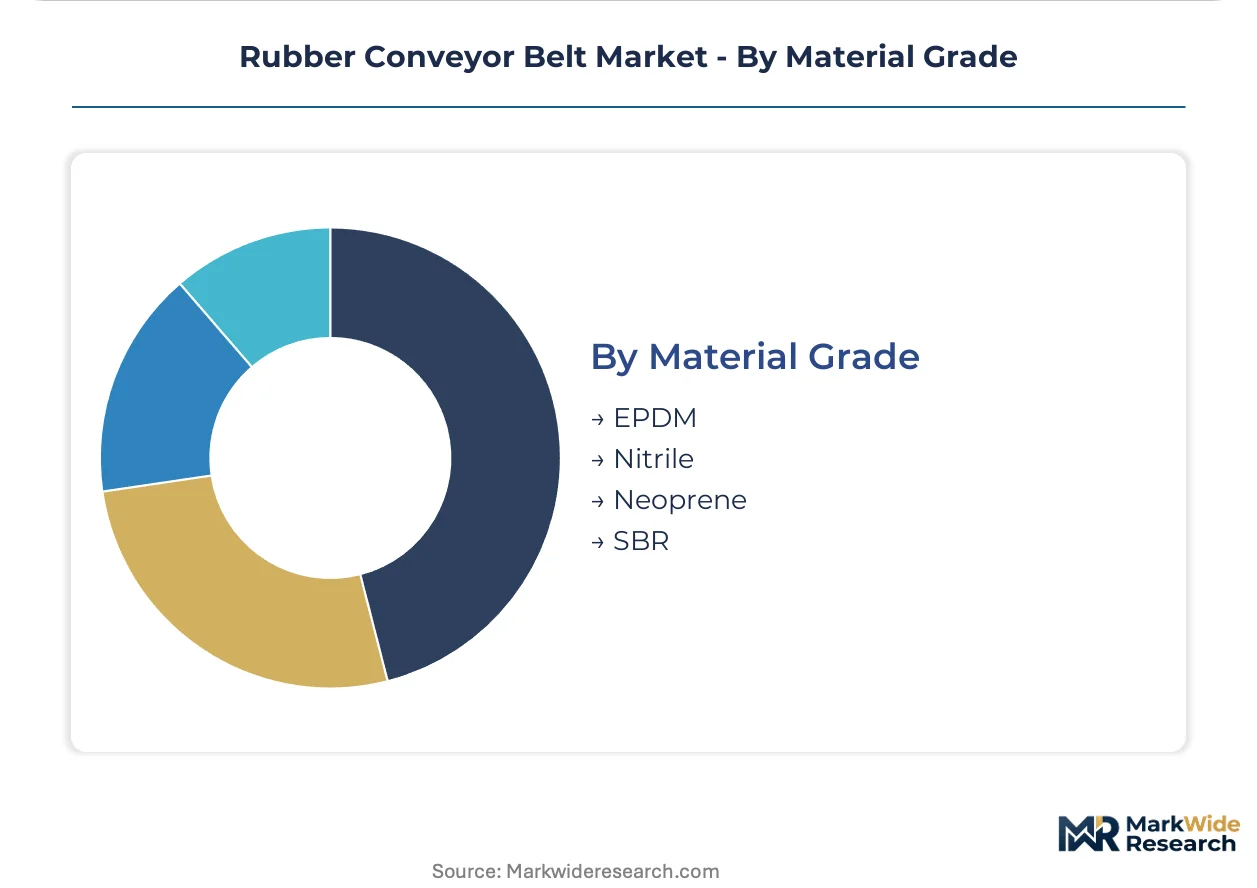
Material Grade:
Polymer selection balances temperature performance, chemical resistance, and cost position, with EPDM and nitrile compounds commanding premiums over commodity SBR.
- EPDM:Ethylene-propylene-diene monomer rubber delivering superior ozone and weathering resistance for outdoor overland conveyors in high-UV environments. Saudi phosphate handling and Australian iron ore export terminals specify EPDM cover compounds for 20-year service life targets.
- Nitrile:Acrylonitrile-butadiene copolymer with exceptional oil and hydrocarbon resistance. Petrochemical refineries along the US Gulf Coast and Rotterdam-Antwerp-Rhine chemical cluster favor nitrile-blend carcasses for solvent and lubricant exposure.
- Neoprene:Chloroprene polymer balancing flame resistance, weathering durability, and moderate oil resistance. General industrial applications in Japan's manufacturing belt and Taiwan's electronics assembly corridors sustain steady demand.
- SBR:Styrene-butadiene rubber offering lowest-cost option for ambient-temperature, non-hazardous bulk handling. Chinese domestic producers leverage SBR-heavy formulations to compete on price in Southeast Asian export markets.
SBR dominates volume rankings on cost sensitivity in developing markets, with Nitrile expanding most quickly as petrochemical and biofuel processing capacity adds globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore belt in Western Australia sustains the world's most intensive heavy-duty conveyor belt replacement cycles. Mining operators in Chile's Atacama Desert and China's industrial corridor provinces generate comparable specification intensity for abrasion-resistant carcasses. Regulatory divergence across MSHA, REACH, and GB standards fragments certification requirements for cross-border suppliers.
Australia
Iron ore export terminals in Port Hedland and Dampier commission steel cord constructions rated above 4,000 N/mm for 20-kilometer overland systems. The country's national mining regulator enforces stringent fire safety protocols for underground coal operations in Queensland's Bowen Basin. BHP and Rio Tinto maintenance departments in the Pilbara region are consolidating supplier panels under lifecycle service contracting models.
China
Steel mills in Hebei Province and cement plants across Shandong sustain continuous demand for heat-resistant belt grades in bulk material handling. SAMR oversight through GB standards enforces domestic quality certification for industrial belting imports. Manufacturing clusters in Jiangsu and Zhejiang provinces host integrated fabricators serving both domestic replacement cycles and Southeast Asian export markets.
Chile
Copper concentrate transport from Escondida and Collahuasi mines to Antofagasta port facilities requires abrasion-resistant carcasses with 18mm top cover thickness. The country's national mining regulator aligns safety standards with MSHA frameworks for underground operations in the El Teniente complex. Codelco procurement teams in Santiago are specifying aramid fiber reinforcement for decline conveyor applications exceeding 1,000 meters depth.
Germany
Chemical-resistant belt grades serve petrochemical refineries along the Rhine-Ruhr corridor and lignite mining operations in the Lusatia region. REACH substance restrictions through ECHA mandate systematic elimination of short-chain chlorinated paraffins from rubber compounds. Continental AG's polymer research facilities in Hanover anchor compound formulation capabilities for heavy-duty European mining contracts.
United States
Coal operators in Wyoming's Powder River Basin and copper mines in Arizona's Morenci district drive specification diversity across surface and underground applications. MSHA 30 CFR Part 14 flame retardant mandates accelerate replacement cycles for certified belting in Appalachian underground coal operations. Aggregate quarries in Texas and Florida generate steady demand for impact-resistant standard-grade constructions in portable crushing circuits.
Rubber Conveyor Belt Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and service network density. The vendor base separates into three tiers: integrated polymer compounders with captive R&D, mining-focused specialists with deep technical service networks, and price-competitive fabricators concentrated in Southeast Asian supply clusters. Strategic moves concentrate on lifecycle service contracting to lock in multi-year volume commitments and compound formulation differentiation to capture REACH and MSHA compliance premiums.
Within the integrated polymer compounder tier, Continental AG and Bridgestone Corporation exemplify backward integration into synthetic rubber research that insulates margin stability from petrochemical feedstock volatility. Among mining-focused specialists, Fenner Dunlop occupies a position anchored by technical service density across Australian and South African operations. These three companies represent the dominant archetypes: Continental AG and Bridgestone Corporation exemplify scale-driven polymer mastery, while Fenner Dunlop exemplifies application-specific service intensity.
| Leading Market Players |
|---|
| Continental AG |
| Bridgestone Corporation |
| Fenner Dunlop |
| The Yokohama Rubber Co. Ltd. |
| Bando Chemical Industries Ltd. |
| Sempertrans |
| Zhejiang Double Arrow Rubber Co. Ltd. |
| Goodyear Rubber Products |
| Qingdao Rubber Six Conveyor Belt Co. |
| Others |
Supply Flow & Price Mechanics
Synthetic polymer substitution in heavy-duty belt compounds simultaneously compresses natural rubber cost exposure and concentrates formulation expertise among integrated compounders with captive R&D infrastructure. This technological pivot reshapes margin stability across the supplier base while amplifying pricing power for REACH-compliant and MSHA-certified grades.
Pricing Analysis
Petrochemical feedstock pass-through dynamics govern synthetic rubber compound economics, with crude oil derivative volatility transmitting directly to cover compound costs. Three-tier pricing structure across premium, standard, and economy levels separates MSHA-certified flame retardant grades from general-purpose SBR constructions and import-concentrated light-duty belting. Cost compression in standard-grade segments is intensifying because of Southeast Asian cartridge belt import pressure. Agricultural cooperatives in Brazil and US Midwest elevator operators exhibit highest price sensitivity, while Australian iron ore miners prioritize lifecycle cost over unit pricing.
Supply Chain Analysis
China's GB standards and SAMR domestic-content mandates are reshaping sourcing patterns for industrial belting imports, compelling foreign suppliers to localize compounding or surrender procurement access. Manufacturing gravity centers on China, Thailand, and Japan for integrated polymer production, with Germany and the United States anchoring specialty compound formulation. Supply chains draw from synthetic rubber feedstocks, aramid fiber reinforcements, and steel cord carcasses sourced from petrochemical complexes and textile manufacturers. Single-source vulnerability concentrates in specialty polymer additives facing REACH substance restrictions. Distribution runs through direct mining procurement contracts, industrial distributor networks, and OEM bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MSHA flame retardant mandates and REACH substance restrictions continuously force replacement cycles and compound reformulation, sustaining demand visibility for certified suppliers.
For Market Incumbents: Deepen backward integration into synthetic rubber research to insulate margin stability from petrochemical volatility. Expand technical service density across Australian and Chilean mining corridors to defend lifecycle contracting positions against integrated polymer compounders. Prioritize dual-certification capabilities for MSHA and REACH compliance to capture premium pricing tiers. For New Entrants and Emerging Players: Capture white-space in chemical-resistant belt grades for desalination and phosphate handling applications previously served by alternative conveying methods. Target agricultural grain export infrastructure modernization across South America and the Black Sea region where specification intensity remains moderate. Pursue digital monitoring integration as a differentiated go-to-market angle for predictive maintenance contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking certification capabilities but holding established mining service relationships. Long-term viability hinges on regulatory compliance moats widening through substance restriction amendments and safety standard convergence. Watch MSHA and ECHA dual-certification approval timelines as the signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Research | Captive formulation capabilities insulate Continental AG and Bridgestone Corporation from synthetic rubber feedstock volatility. |
| Lifecycle Service Contracting | Suppliers like Fenner Dunlop transfer inventory risk to manufacturers while locking multi-year volume from BHP and Rio Tinto. |
| Dual-Certification Investment | Simultaneous MSHA and REACH compliance opens cross-border mining procurement in Chile's El Teniente and US Appalachian operations. |
| Embedded Sensor Layer Development | Digital monitoring integration enables predictive maintenance premiums for condition-monitored belting in Pilbara iron ore systems. |
| Aramid Fiber Reinforcement Scale-Up | Weight reduction and flex fatigue resistance displace traditional nylon-polyester constructions in Chilean and Australian overland conveyors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Australian and Chilean mining operations, procurement leads at Chinese steel mills, technical R&D directors at polymer compounders, and aftermarket service heads at industrial distributors with secondary validation. Trade data from customs authorities, SEC filings from listed compounders, mining sector maintenance expenditure disclosures, and ECHA substance restriction amendments anchored supply-side assessment. Bottom-up belt replacement cycle modeling and top-down mining capital expenditure analysis provided cross-checks.
Comparable-period anchoring to historical replacement intensity across mining, cement, and steel production clusters structured the projection framework. Segmentation dimensions spanned product type, end-use industry, material grade tier, and regional regulatory cluster. CAGRs derived from installed base depreciation schedules, throughput expansion announcements, and compliance-driven replacement mandates. Forecast inputs incorporated MSHA certification timelines, REACH substance restriction phase-outs, and aramid fiber adoption curves in overland conveyor specifications.
Feedstock price volatility, certification approval delays, and mining capital expenditure cycles are the dominant revision risks to volume and value projections. Forecasts reflect assumptions regarding regulatory enforcement continuity and polymer substitution economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Chemicals Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Tapes Market
Rubber
Tire Reinforcement Materials Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
EPDM Rubber Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Global Rubber Vulcanization Market
Rubber
Global Rubber Process Oil Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Rubber Bulb Seals Market
Rubber
Rubber Rollers Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Liquid Polybutadiene Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market